
 Aluminium Foil Sachet Market | 2026-2036
Aluminium Foil Sachet Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Foil Sachet Market Outlook
Pharmaceutical contract manufacturers are redrawing procurement patterns for aluminium foil sachets as single-unit dosing replaces bulk blister formats in emerging markets. Amcor plc leverages its integrated healthcare packaging footprint to sustain preferential access to FDA-validated production lines. Constantia Flexibles anchors European demand through specialized cold-form foil capabilities that serve temperature-sensitive biologics. Novelis competes on recycled-content aluminium supply, positioning its closed-loop recycling as a differentiated input for sustainability-mandated buyers.
Aluminium foil sachets are laminated flexible pouches, typically constructed from aluminium foil layers between 6 and 12 microns thick bonded to polyethylene or polyester films, engineered to provide complete moisture, oxygen, and light barriers for sensitive contents. Their primary commercial purpose centers on extending shelf stability for pharmaceuticals, instant beverages, and cosmetic samples where degradation from environmental exposure threatens product integrity. Stand up pouches dominate value pools in food and beverages due to premium shelf presence and resealability, while flat sachets retain cost leadership in pharmaceutical unit-dose applications where tear-open convenience supersedes display requirements. Heat seal closure types command the largest volume share across usage areas, though zipper formats are gaining fastest in personal care trial-size packaging where repeat access adds functional value.
FDA 21 CFR Part 177 indirect food additive rules and EU REACH Annex XVII substance restrictions jointly determine laminate composition eligibility for food-contact and medical applications, effectively filtering out non-compliant regional suppliers from qualified vendor lists. BIS certification requirements under India's Compulsory Registration Scheme for packaged goods further segment export-accessible manufacturers from purely domestic players. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as these mechanisms will increasingly internalize end-of-life collection costs into sachet pricing structures and reshape supplier economics.
Market Dynamics
Unit-dose pharmaceutical compliance packaging is compressing batch sizes and accelerating format changeover frequency across converter operations, forcing capital redeployment toward quick-change laminating lines.
Growth Catalysts
- REACH Annex XVII substance restrictions:European laminate specifications now exclude certain plasticizers and adhesives, filtering qualified suppliers and tightening vendor consolidation among compliant converters.
- India's PLI scheme for pharmaceuticals:Domestic API and formulation manufacturing incentives are expanding foil sachet demand for export-oriented generic packaging.
- Cold-chain biologics expansion:Temperature-sensitive monoclonal antibody therapies require specialized cold-form foil barriers that standard blister packs cannot provide.
Market Restraints
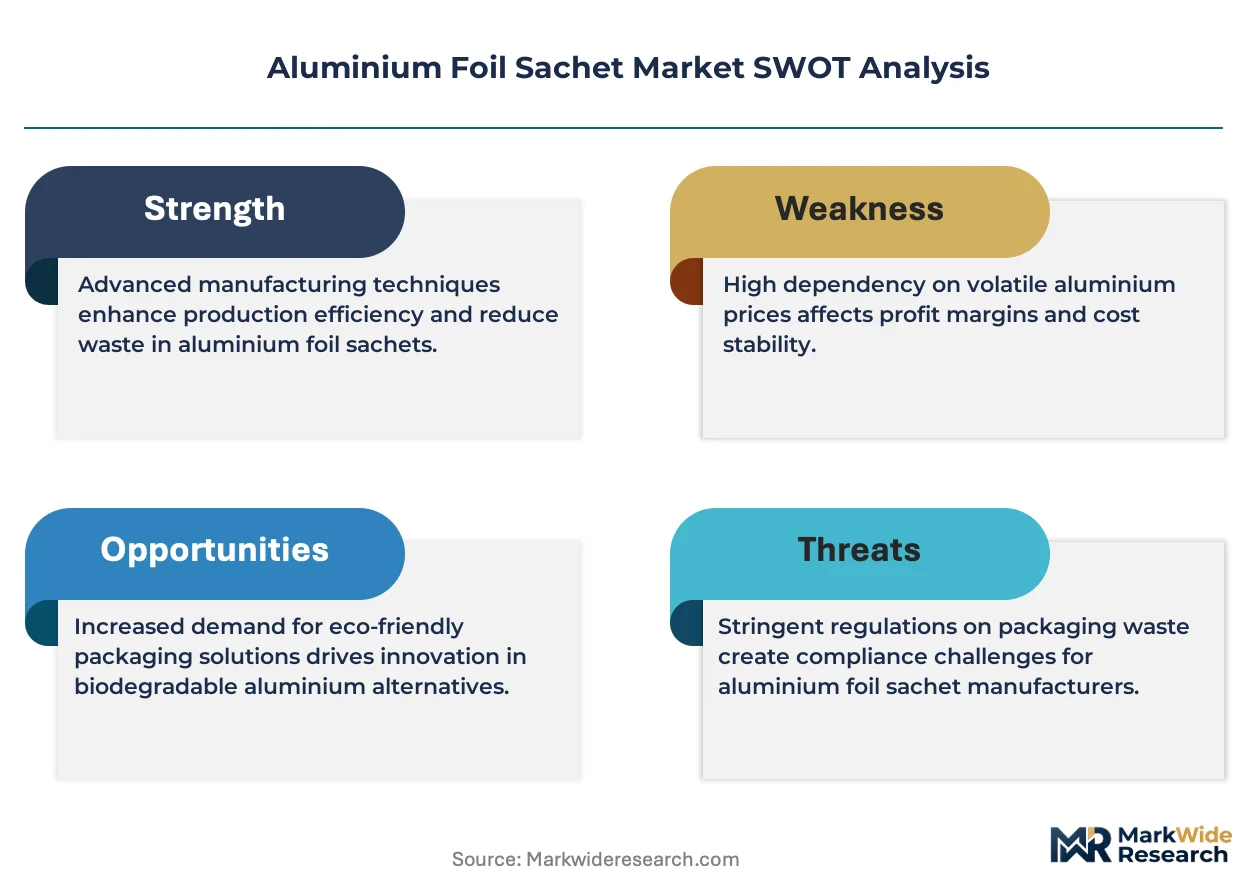
- Primary aluminium ingot volatility:LME price swings transmit directly to foil substrate costs, compressing converter margins on fixed-price annual contracts.
- Rolled foil supply concentration:Five European and Asian mills control thin-gauge pharmaceutical-grade foil supply, creating single-source vulnerability for mid-tier converters.
- Multi-layer recycling incompatibility:Polyethylene-aluminium laminate separation remains uneconomical at scale, exposing producers to rising extended producer responsibility fees.
Strategic Opportunities
- Sub-Saharan Africa generic drug distribution:WHO prequalification programs are opening tender markets for foil-sachet unit doses in malaria and HIV therapeutic categories.
- EU Packaging and Packaging Waste Regulation recyclability mandates:Mono-material aluminium designs qualify for preferred EPR fee structures, rewarding early redesign investments.
- Digital printing convergence with barrier laminates:HP Indigo and Xeikon systems now handle food-contact certified inks, enabling personalized pharmaceutical adherence packaging.
Industry Challenges
- FDA 21 CFR Part 177 validation timelines:New laminate adhesive approvals require 18-24 month migration studies, delaying product launches for reformulated structures.
- Quick-change laminator operator scarcity:Converters struggle to recruit technicians skilled in both adhesive chemistry and servo-driven registration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Foil Sachet Market |
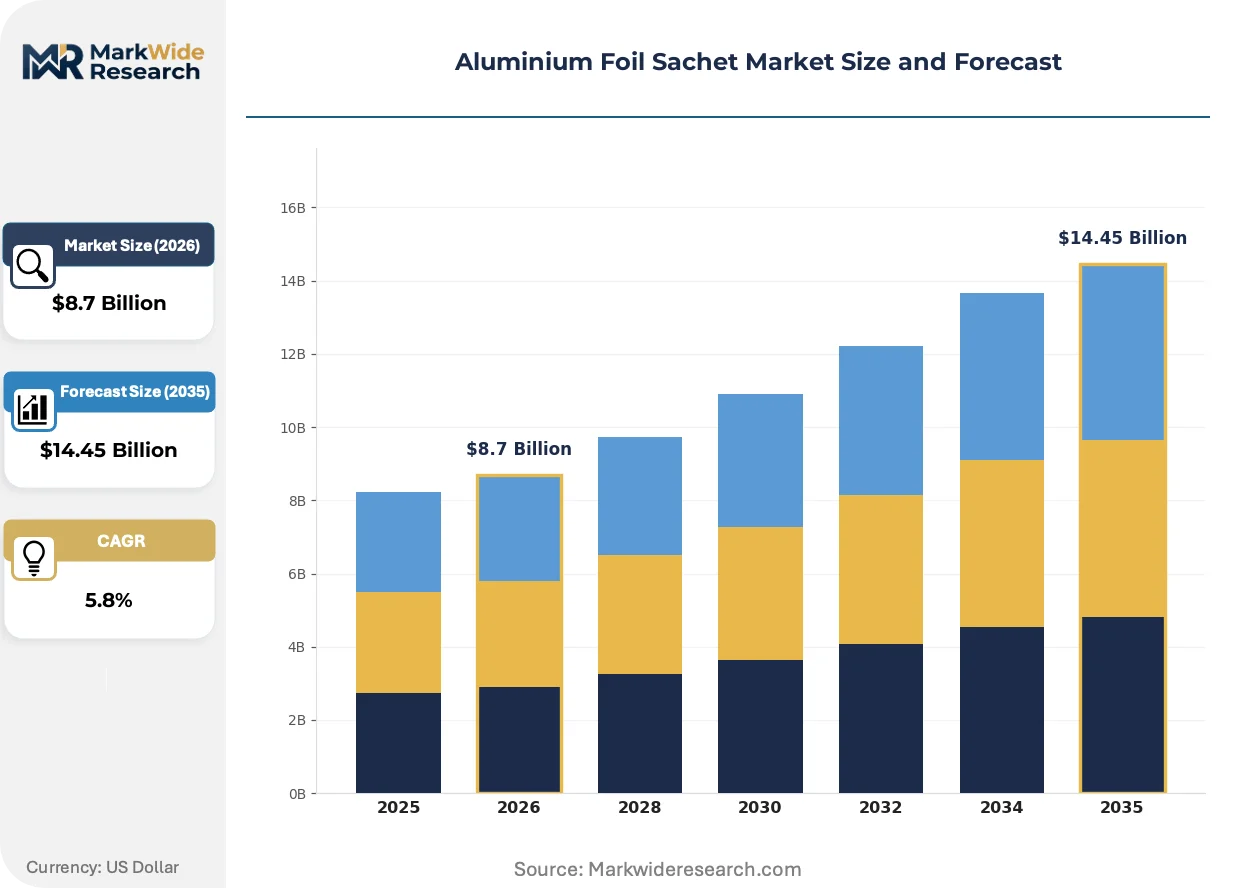
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand Up Pouches, Gusseted Pouches, Sachets Usage Area: Pharmaceuticals, Food & Beverages, Personal Care, Industrial Closure Type: Heat Seal, Tear Notch, Zipper, Press-to-Close Thickness: 30 Micron, 50 Micron, 70 Micron, 100 Micron |
| Companies Covered | Amcor plc, Constantia Flexibles, Novelis, Hindalco Industries Limited, China Hongqiao Group Limited, RUSAL, Huhtamaki, Mondi Group, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Foil Sachet Market Strategic Shifts
Active and intelligent packaging functionalities are migrating from premium food applications into pharmaceutical foil sachets, reshaping converter R&D priorities and equipment specifications simultaneously.
Printed electronics integration is miniaturizing. Conductive ink humidity sensors embedded between foil and sealant layers now provide real-time moisture ingress detection for moisture-sensitive drugs. Contract manufacturers serving FDA-regulated ANDA filers are piloting these structures for stability protocol enhancement. The technology is miniaturizing quality assurance workflows, compressing laboratory testing burdens into distributed packaging intelligence.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon elimination from pharmaceutical cold-chain logistics. Temperature-indicating sachet formats that eliminate electronic data logger dependencies are gaining traction among European generic exporters. German and French logistics providers now specify these passive indicators for lane qualification studies.
Hospital pharmacy consolidation is compressing supplier lists. Integrated delivery networks in the United States now mandate unit-dose packaging for 90 percent of formulary items, displacing bulk bottle dispensing. Purchasing committees prioritize converters with FDA drug master file coverage, shifting volume toward pre-qualified supply bases.
Aluminium Foil Sachet Market Segmentation
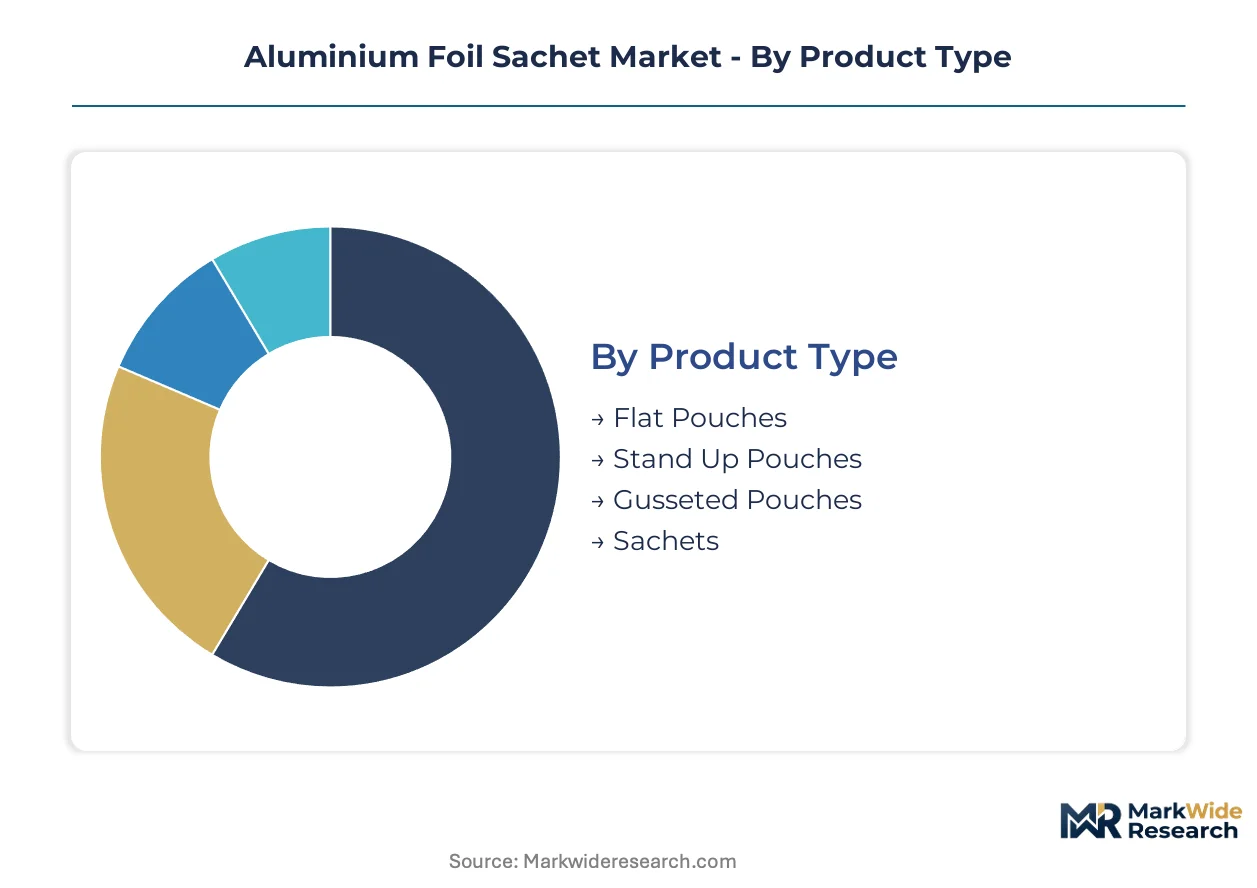
Aluminium foil sachet procurement varies sharply by end-use barrier requirements and line-speed compatibility. Converter investments track segment-specific regulatory validation burdens and format changeover economics.
Product Type:
Substitution pressure from fibre-based pouches and mono-material plastics weighs heaviest on commodity flat formats, while technical barriers protect specialized stand-up and gusseted structures.
- Flat Pouches:Two-dimensional laminates with 6-12 micron aluminium cores, optimized for high-speed pharmaceutical form-fill-seal lines. Generic drug exporters in India source these in volume for WHO-prequalified tender markets where unit-dose compliance is mandatory.
- Stand Up Pouches:Bottom-gusseted structures with self-supporting bases, constructed from thicker foil laminates with added PET or nylon structural layers. Premium instant beverage brands in Germany and France specify these for retail shelf differentiation and resealability.
- Gusseted Pouches:Side-folded formats expanding to rectangular cross-sections when filled, common in industrial chemical sampling where puncture resistance exceeds display requirements.
- Sachets:Single-serve tear-open pouches, typically 30-50 micron total thickness, dominating cosmetic sample and condiment portion-pack distribution.
Flat pouches retain volume leadership; stand up pouches hold the steepest expansion curve.
Usage Area:
Cost tier stratification separates validated pharmaceutical grades from commodity food-contact specifications, with regulatory compliance costs creating tiered entry barriers.
- Pharmaceuticals:Cold-form and tropical blister foil laminates requiring FDA 21 CFR Part 177 drug master file coverage and EMA-compliant stability documentation. Temperature-sensitive biologics demand specialized 70-100 micron structures with enhanced moisture barriers.
- Food & Beverages:Standard heat-seal laminates for instant coffee, powdered drink mixes, and retortable sauces. EU REACH Annex XVII compliance on adhesive plasticizers filters qualified supplier lists for European branded goods manufacturers.
- Personal Care:Trial-size shampoo, conditioner, and serum sachets favor zipper closures and cosmetic-grade printing. Korean beauty exporters drive specification innovation for travel-retail distribution formats.
- Industrial:Lubricant samples, adhesive sachets, and chemical reagent packaging where puncture resistance and chemical compatibility outweigh barrier sophistication.
Pharmaceuticals command premium pricing tiers; personal care applications are expanding most quickly.
Closure Type:
Volume concentration favors established heat-seal infrastructure, while zipper and press-to-close formats capture margin through functional differentiation.
- Heat Seal:Hermetic fusion of PE or PP sealant layers under controlled temperature and pressure, delivering oxygen transmission rates below 0.01 cc/m²/day. Pharmaceutical unit-dose lines in the United States and Germany standardize on this format for tamper-evidence and line-speed economics.
- Tear Notch:Laser-scored or mechanical perforations enabling clean opening without tools, common in elderly-accessible pharmaceutical designs and single-serve food portions.
- Zipper:Interlocking plastic profiles laminated between foil and sealant layers, adding 15-25% material cost for repeat-access convenience in personal care and snack applications.
- Press-to-Close:Simplified interlocking strips without zipper sliders, targeting cost-sensitive resealable formats in emerging market detergent and spice packaging.
Heat seal closures dominate unit volumes; zipper formats gain share fastest in premium personal care.
Thickness:
Application-driven specification ranges from minimal barrier sachets to heavy-gauge industrial formats, with pharmaceutical validation requirements compressing mid-tier adoption.
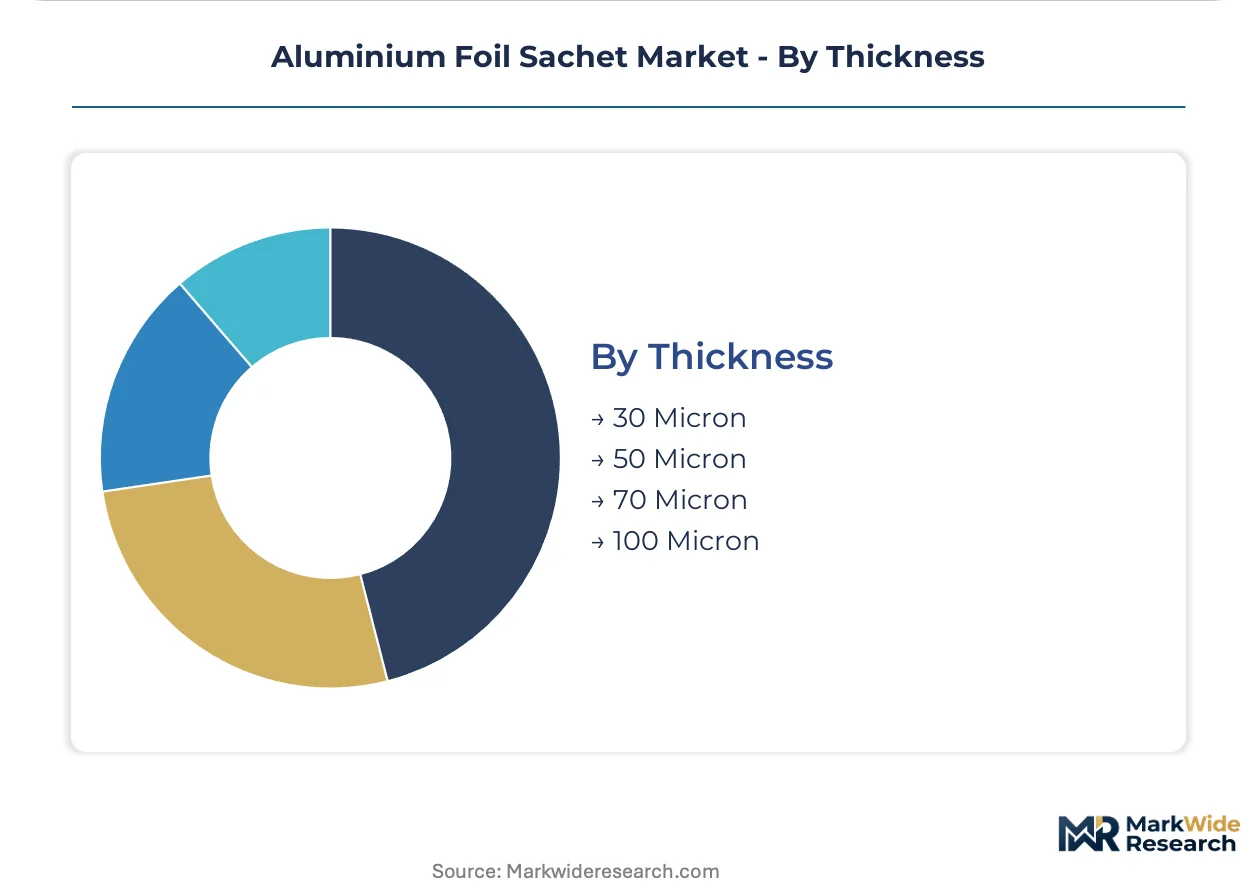
- 30 Micron:Ultra-thin laminates for cost-optimized cosmetic samples and condiment portions where short shelf life limits barrier demands. Indian domestic FMCG brands specify these for price-sensitive rural distribution.
- 50 Micron:Standard pharmaceutical unit-dose thickness balancing barrier performance and formability. FDA-validated converters in Italy and Spain maintain dedicated production lanes for this specification band.
- 70 Micron:Enhanced barrier structures for moisture-sensitive generics and probiotic formulations requiring extended tropical stability. WHO prequalification programs specify this grade for malaria and HIV therapeutic distribution in Sub-Saharan Africa.
- 100 Micron:Cold-form foil and heavy industrial formats where puncture resistance and deep-draw thermoforming compatibility are essential. Temperature-sensitive monoclonal antibody packaging drives qualification investments in this tier.
50 micron specifications retain volume leadership; 100 micron structures hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European laminate import flows, while India's Jawaharlal Nehru Port anchors generic pharmaceutical export corridors to Sub-Saharan Africa and Southeast Asia.
United States
Hospital pharmacy consolidation and unit-dose mandates drive foil sachet procurement for 90 percent of formulary items. FDA 21 CFR Part 177 validation requirements filter qualified converters. The Philadelphia-Wilmington corridor hosts specialized laminators serving ANDA filers with drug master file coverage.
Germany
Premium instant beverage brands specify stand-up pouch formats for retail differentiation. EU F-Gas Regulation phase-down accelerates temperature-indicating sachet adoption for cold-chain lane qualification. The Rhine-Main industrial cluster concentrates converter R&D for mono-material aluminium designs.
India
PLI scheme incentives expand domestic API and formulation manufacturing, amplifying foil sachet demand for export-oriented generic packaging. BIS certification under the Compulsory Registration Scheme segments export-accessible manufacturers. Gujarat's pharmaceutical belt concentrates contract packaging operations for WHO-prequalified tenders.
China
Integrated aluminium smelter-foil mill complexes supply cost-optimized substrate for commodity laminates. NMPA pharmaceutical packaging regulations align with international PIC/S standards for export market access. The Yangtze River Delta hosts converter clusters serving Korean beauty exporters.
Brazil
Generic drug distribution networks in the Sudeste region adopt unit-dose formats for public health program compliance. ANVISA pharmaceutical packaging regulations require stability documentation for tropical climate zones. São Paulo's industrial corridor concentrates flexographic printing capacity for regional FMCG brands.
Aluminium Foil Sachet Market Competitive Environment
Concentration sits with integrated packaging conglomerates and specialized foil converters. The vendor base stratifies across three tiers: multinational healthcare packaging platforms with FDA-validated production networks, regional laminators with cold-form foil specializations, and commodity substrate suppliers competing on recycled-content aluminium. Dominant competitive moves include portfolio diversification into mono-material recyclable structures and backward integration into captive foil rolling capacity.
Within the integrated packaging tier, Amcor plc and Constantia Flexibles exemplify multinational platforms with healthcare-specialized production networks. Novelis occupies a distinct position as a recycled-content aluminium substrate supplier, anchoring sustainability-mandated procurement channels. These three entities represent the primary competitive archetypes: end-to-end packaging solutions, specialized barrier laminates, and circular-economy material inputs.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles |
| Novelis |
| Hindalco Industries Limited |
| China Hongqiao Group Limited |
| RUSAL |
| Huhtamaki |
| Mondi Group |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for pharmaceutical-grade thin-gauge foil concentrate pricing power among European and Asian mills, compressing converter margins on fixed-price annual contracts while rewarding integrated producers with captive rolling capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cold-form laminates from REACH-compliant food-contact grades and commodity cosmetic sachets. Price differentiation hinges on certification tier and volume scale, with annual contract volumes above ten million units unlocking preferential substrate allocations. Pricing pressure stems from LME aluminium ingot volatility transmitting directly to foil substrate costs. Generic drug exporters in India exhibit highest price sensitivity; biologics contract manufacturers show least sensitivity due to stability-mandated barrier specifications.
Supply Chain Analysis
China, Germany, and India anchor rolled foil supply, with Chinese integrated smelter-mill complexes feeding commodity laminates and German specialized mills serving pharmaceutical-grade demand. Raw material dependencies center on primary aluminium ingot, polyethylene sealant resins, and FDA-compliant adhesive chemistries. Single-source vulnerability concentrates in thin-gauge pharmaceutical foil where five mills control qualified supply. Distribution runs through converter networks with regional laminating capabilities, feeding form-fill-seal operations at contract packaging facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical validation services and drug master file maintenance contracts expand faster than substrate sales, converting transactional foil supply into recurring revenue streams with multi-year lock-in.
For Market Incumbents: Shield market position by deepening backward integration into captive foil rolling capacity, eliminating mill-supplier vulnerability. Accelerate mono-material aluminium redesign investments ahead of EU Packaging and Packaging Waste Regulation EPR fee restructuring. Prioritize FDA drug master file coverage expansion to capture hospital pharmacy consolidation volume.
For New Entrants and Emerging Players: Cold-chain logistics indicator services represent a service-layer gap where incumbents under-serve European generic exporters. Penetrate temperature-indicating sachet formats for F-Gas Regulation compliance markets. Pursue WHO prequalification program partnerships as the fastest go-to-market channel for Sub-Saharan African tender access.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with under-monetized healthcare laminating assets. Five-to-ten-year viability favors converters with validated biologics barrier capabilities over commodity food-contact exposure. Monitor EU extended producer responsibility fee implementation timelines as the critical inflection signal for mono-material redesign ROI.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Aluminium Redesign | Qualifies for preferred EU EPR fee structures ahead of regulatory deadlines. |
| FDA Drug Master File Expansion | Captures hospital pharmacy consolidation volume requiring pre-qualified supply bases. |
| Cold-Form Foil Capacity Addition | Serves temperature-sensitive monoclonal antibody therapies with specialized barriers. |
| Digital Printing Integration | Enables personalized pharmaceutical adherence packaging with HP Indigo certified systems. |
| Backward Integration into Foil Rolling | Eliminates single-source mill vulnerability and secures substrate cost control. |
Study Parameters
Operator-level perspectives from laminating line technicians, pharmaceutical packaging procurement managers, regulatory affairs specialists, and cold-chain logistics coordinators anchored the qualitative base. Primary fieldwork combined with secondary validation from FDA 21 CFR Part 177 filings, EMA stability documentation databases, EU REACH Annex XVII substance restriction updates, and BIS Compulsory Registration Scheme notifications. Bottom-up unit economics from converter operations triangulated against top-down trade flow analysis across the analysis window.
Sensitivity analysis tested forecast robustness across LME aluminium price bands, EPR fee implementation scenarios, and pharmaceutical contract manufacturing growth assumptions. Segmentation dimensions modeled include product type, usage area, closure mechanism, thickness specification, and regional regulatory cluster. CAGRs derived from installed laminating capacity expansion trajectories and end-use demand elasticity across pharmaceutical, food and beverage, and personal care verticals. Cold-chain biologics penetration and generic drug unit-dose compliance mandates served as primary demand-side forecast inputs.
Forecasts assume regulatory continuity in FDA 21 CFR Part 177, EU REACH, and India's PLI scheme regimes; material policy shifts would require re-modeling. Specific risks include accelerated extended producer responsibility fee implementation, primary aluminium supply disruption from energy transition constraints, and pharmaceutical validation timeline compression. Recalibration cycles align with material shifts in laminate adhesive approval timelines and biologics cold-chain infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market