
 North America Sachet Packaging Market | 2026-2036
North America Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sachet Packaging Market Analytics
Single-serve configuration bundling is shifting buyer choice across food service and hospitality channels, replacing bulk condiment dispensers with portion-controlled sachet arrays. Amcor plc leverages its North American film extrusion network to sustain cost-competitive supply to quick-service chains. Glenroy, Inc. specializes in high-barrier flexible structures that extend shelf stability for sensitive pharmaceutical and cosmetic formulations. Huhtamaki anchors its position through proprietary forming technology that controls unit economics at high throughput.
North America sachet packaging denotes small-format sealed pouches, typically ranging from 1 milliliter to 30 milliliters in fill volume, constructed from laminated films or foil-paper composites via horizontal or vertical form-fill-seal processes, designed for single-use dispensing of liquids, powders, or semi-solids. The food segment dominates current volume through condiment, sauce, and sweetener applications, while the biodegradable material category records the fastest structural expansion as brand owners respond to state-level extended producer responsibility mandates. Pharmaceutical sachets command premium margin pools due to child-resistant certification requirements and serialization compliance under drug supply chain regulations.
The US Food and Drug Administration governs food-contact notifications and pharmaceutical packaging standards, while Health Canada and PMRA administer parallel requirements for Canadian-market sachets, and California's SB 54 regulations directly constrain plastic content thresholds for single-use packaging sold into that state. These overlapping frameworks compel converters to maintain dual-certification laboratories and region-specific material libraries. Stakeholders must monitor pending EPA per- and polyfluoroalkyl substance restrictions and provincial extended producer responsibility rollouts to anticipate material substitution timelines and capital redeployment needs.
Market Dynamics
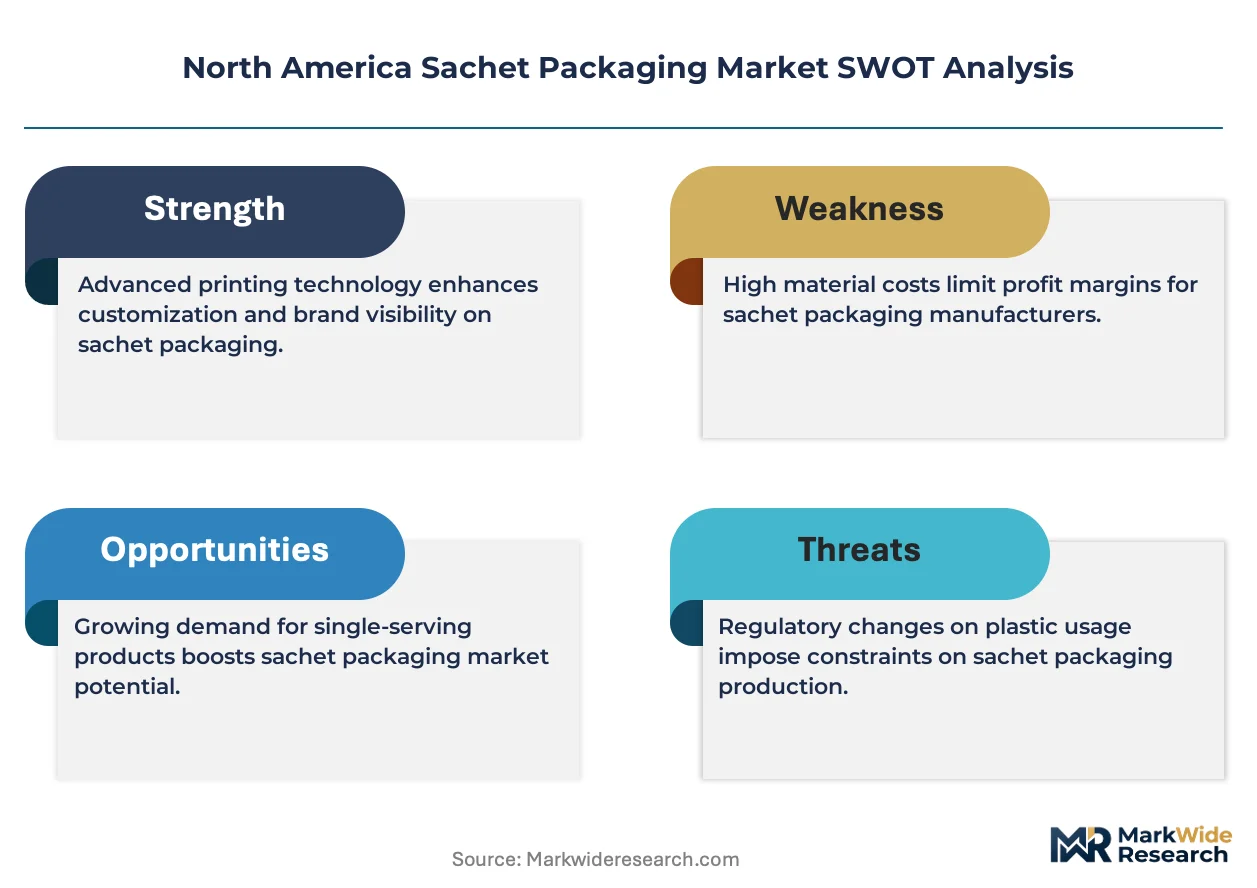
California's SB 54 extended producer responsibility mandates are compressing material substitution timelines across North American sachet converters, forcing simultaneous compliance with FDA food-contact notifications and state-level plastic reduction thresholds.
Growth Catalysts
- Quick-service restaurant condiment automation:Portion-controlled sachet arrays are replacing bulk dispensers in United States food service chains, driving unit volume expansion through standardized meal kits and drive-thru packaging specifications.
- Health Canada serialization requirements:Pharmaceutical sachets now require track-and-trace compliance for Canadian distribution, creating premium demand for certified converters with integrated printing and verification capabilities.
- Biodegradable film extrusion advances:PLA and PHA barrier structures are achieving moisture resistance parity with conventional laminates, enabling adoption in California's food processing corridor ahead of plastic content deadlines.
Market Restraints
- Aluminum foil supply concentration:North American foil rolling capacity concentrates among three primary suppliers, creating input cost volatility for high-barrier pharmaceutical and cosmetic sachet structures.
- Dual-certification laboratory overhead:Converters must maintain separate FDA and Health Canada testing protocols, adding fixed cost burden that disadvantages mid-tier regional players.
- Extended producer responsibility fee structures:California, Oregon, and Maine impose divergent per-unit packaging fees, complicating pricing standardization across state lines.
Strategic Opportunities
- Mexico pharmaceutical manufacturing expansion:COFEPRIS regulatory alignment with FDA standards is attracting contract packaging investment for US-export sachet production at lower conversion costs.
- Cosmetic sample sachet premiumization:Single-use skincare and fragrance formats are displacing miniature bottles in direct-to-consumer subscription channels, commanding margin multiples above food applications.
- Curbside-compostable material certification:BPI and CMA certification programs are creating brand-owner preference for converters with validated home and industrial composting pathways.
Industry Challenges
- Child-resistant certification timelines:Pharmaceutical sachets require 16 CFR 1700 protocol testing that extends product development cycles by four to six months versus standard flexible packaging.
- Legacy forming equipment retrofit costs:Horizontal form-fill-seal lines require substantial capital expenditure to accommodate biodegradable film sealing temperature profiles and reduced web tension tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sachet Packaging Market |
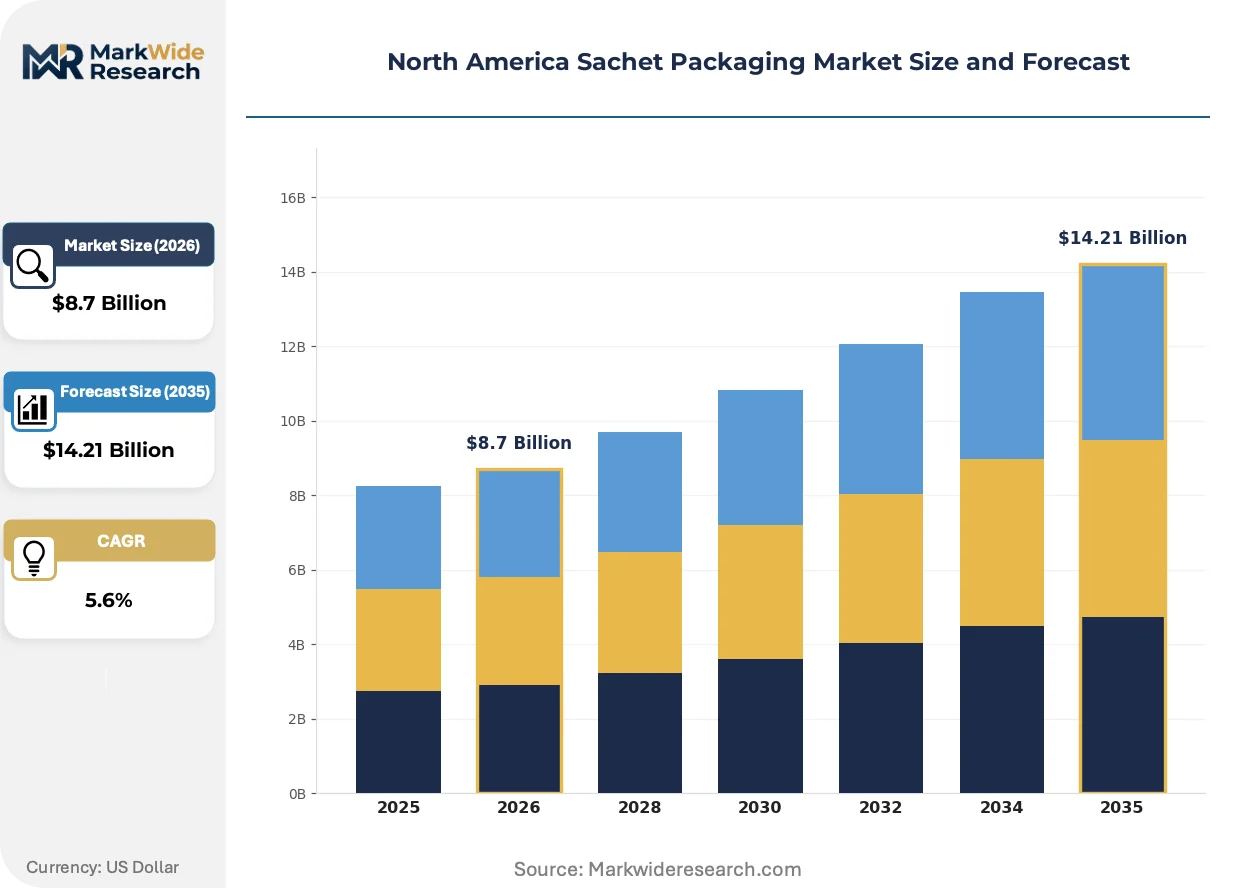
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Cosmetics, Pharmaceuticals, Chemicals Material: Plastic, Paper, Foil, Biodegradable End User: Retail, Food Service, Healthcare, Industrial Format: Single-Serve, Multi-Serve, Custom Design, Others |
| Companies Covered | Graphic Packaging International, LLC, Glenroy, Inc., Amcor plc, Amber Packaging, RATTPACK, Huhtamaki, ePac Holdings, LLC, Sealed Air Corporation, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sachet Packaging Market Evolving Landscape
Material science advances and regulatory compression are converging to redefine sachet construction specifications across food, pharmaceutical, and cosmetic end-uses. Converters are racing to qualify next-generation barrier structures before state-level plastic bans activate.
Water-based barrier coatings are rewriting the technical feasibility of mono-material sachet construction. Quick-service chains in the United States are piloting these structures for condiment applications at scale. The technology is compressing the timeline for curbside-recyclable packaging certification previously blocked by polyethylene adhesive lamination requirements.
The EPA's pending per- and polyfluoroalkyl substance restrictions are eliminating fluorinated barrier treatments from food-contact sachets. Converters are accelerating migration to silicone oxide and aluminum oxide vapor-deposited alternatives. Pharmaceutical applications in Canada face the steepest reformulation burden due to Health Canada's parallel PFAS monitoring protocols.
Direct-to-consumer sample subscription models are fragmenting minimum order quantities and compressing changeover frequency. Cosmetic brands are unbundling traditional bulk sampling programs into individualized sachet assortments. This pattern concentrates most visibly in California's beauty manufacturing cluster and New York metropolitan area fulfillment hubs.
North America Sachet Packaging Market Segmentation
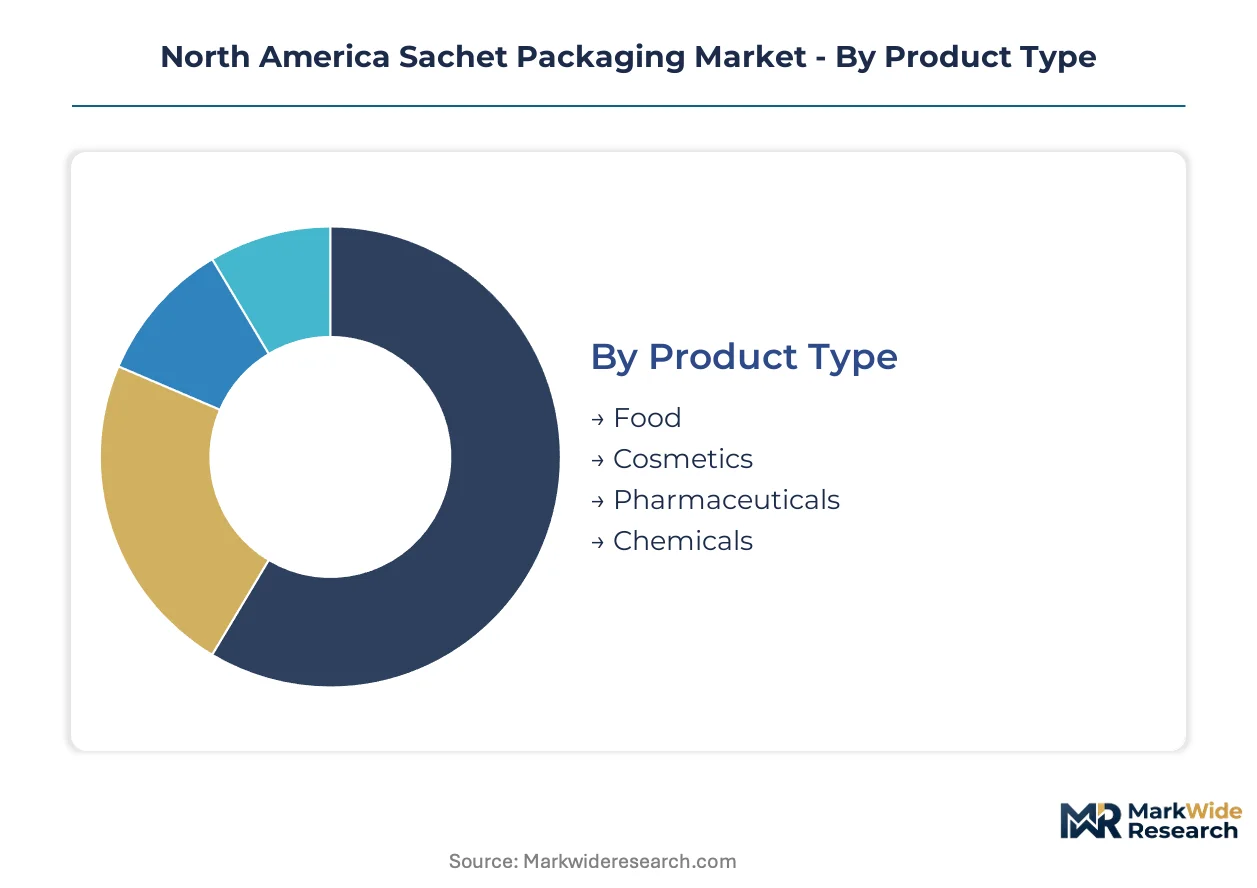
Sachet packaging configurations in North America diverge sharply across end-use requirements, with food-contact compliance, pharmaceutical barrier specifications, and cosmetic premium aesthetics demanding incompatible material stacks and forming protocols. Converters must maintain parallel production lines to serve these distinct specification tiers without cross-contamination risk.
Product Type:
Technical specifications governing fill volume, barrier performance, and dispensing mechanics separate these application clusters.
- Food:Condiment and sauce sachets dominate unit volume, with laminated polyethylene-foil structures achieving oxygen transmission rates below 0.1 cc/m²/day for shelf-stable applications. Quick-service restaurant automation in the United States is standardizing 9-gram ketchup and 12-gram mayonnaise sachets as default meal kit components.
- Pharmaceuticals:Unit-dose sachets for oral dissolving films and topical gels require child-resistant certification under 16 CFR 1700 protocols, extending qualification timelines. Health Canada serialization mandates are concentrating demand among converters with integrated track-and-trace printing capabilities in Ontario and Quebec.
- Cosmetics:Skincare sample sachets leverage metallized films and soft-touch coatings for shelf impact in direct-to-consumer subscription channels. California's beauty manufacturing cluster is driving premiumization through embossed sealing and holographic decoration.
- Chemicals:Industrial adhesive and lubricant sachets employ high-strength sealants and chemical-resistant substrates for manufacturing line integration.
Mature deployment sits with Food. Newer deployment is concentrated in Cosmetics.
Material:
Cost structures and regulatory compliance timelines vary dramatically across substrate categories, with state-level mandates forcing premature substitution in some channels.
- Plastic:Multi-layer polyethylene and polypropylene laminates retain cost advantage for high-volume food service applications. California's SB 54 plastic reduction thresholds are compressing allowable content percentages ahead of neighboring states.
- Biodegradable:PLA and PHA barrier structures are achieving moisture resistance parity with conventional films through silicon oxide vapor deposition. Adoption concentrates in California's food processing corridor where extended producer responsibility fees create immediate economic pressure.
- Foil:Aluminum-foil composites provide absolute barrier performance for pharmaceutical and retort food applications. Supply concentrates among three North American rolling mills, creating input cost volatility.
- Paper:Fiber-based sachets with water-based barrier coatings are qualifying for curbside recycling streams, displacing plastic in quick-service condiment trials.
Mature deployment sits with Plastic. Newer deployment is concentrated in Biodegradable.
End User:
Procurement scale and specification authority separate these demand channels, with food service chains exercising disproportionate influence over format standardization.
- Food Service:Quick-service restaurant chains specify sachet dimensions, seal strength, and print registration tolerances through centralized procurement. Portion-controlled arrays are displacing bulk condiment dispensers across United States drive-thru operations.
- Retail:Supermarket and convenience store channels demand shelf-ready multipacks with hang-hole features and retail-ready case counts.
- Healthcare:Hospital and clinic procurement emphasizes unit-dose compliance and tamper-evident features for medication administration.
- Industrial:Manufacturing line integration requires sachet burst strength and dispensing compatibility with automated equipment.
Mature deployment sits with Retail. Newer deployment is concentrated in Food Service.
Format:
Forming equipment capabilities and changeover economics determine which converters can profitably serve each format tier.
- Single-Serve:Horizontal form-fill-seal lines produce 1-30 milliliter sachets at throughputs exceeding 600 units per minute. Standardization around quick-service restaurant specifications is reducing format variation.
- Custom Design:Die-cut shapes, tear-notch configurations, and branded dispensing geometries command margin premiums in cosmetic sampling. Direct-to-consumer subscription fragmentation is compressing minimum order quantities.
- Multi-Serve:Larger format sachets for food service bulk dispensing and industrial applications employ vertical form-fill-seal processes.
- Others:Specialty formats including stick packs and spouted sachets serve niche hydration and beverage concentrate applications.
Mature deployment sits with Single-Serve. Newer deployment is concentrated in Custom Design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US-Mexico-Canada Agreement's tariff-free zones for packaging materials concentrate converter investment along cross-border manufacturing corridors. California's extended producer responsibility mandates and Ontario's pharmaceutical serialization requirements are reshaping regional capacity allocation. Industrial clusters in Chicago, Toronto, and Mexico City anchor production networks serving distinct end-use specifications.
United States
Quick-service restaurant automation drives condiment sachet standardization across national chains. The FDA's updated food-contact substance notification requirements compress material qualification timelines for California-bound shipments. Chicago's flexible packaging hub houses horizontal form-fill-seal capacity serving Midwest food processing operations.
Canada
Health Canada serialization mandates for pharmaceutical distribution create premium demand for track-and-trace capable converters. The PMRA administers parallel compliance protocols for pesticide and agricultural chemical sachets. Ontario's contract packaging corridor in the Greater Toronto Area concentrates unit-dose pharmaceutical capacity for US export.
Mexico
COFEPRIS regulatory alignment with FDA standards attracts pharmaceutical sachet contract manufacturing for North American markets. Lower conversion costs and proximity to US distribution centers drive capacity expansion. Nuevo León's Monterrey metroplex hosts multinational converter subsidiaries serving quick-service restaurant supply chains.
North America Sachet Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material tiers and end-use specifications. The vendor base stratifies into three functional layers: multinational film extruders with integrated converting networks, regional specialists in high-barrier pharmaceutical structures, and digital-printing-enabled short-run converters. Consolidation pressure intensifies as extended producer responsibility mandates raise compliance fixed costs. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with quick-service restaurant procurement consortia.
Within the multinational integrated tier, Amcor plc and Sealed Air Corporation exemplify scale-driven positioning through captive film supply networks. Glenroy, Inc. occupies a specialist position in high-barrier flexible structures for sensitive formulations. Huhtamaki anchors forming technology leadership for high-throughput food service applications. These three represent distinct strategic archetypes: resin-to-sachet integration, barrier-performance specialization, and proprietary equipment economics.
| Leading Market Players |
|---|
| Graphic Packaging International, LLC |
| Glenroy, Inc. |
| Amcor plc |
| Amber Packaging |
| RATTPACK |
| Huhtamaki |
| ePac Holdings, LLC |
| Sealed Air Corporation |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in North American flexible packaging have compressed working capital cycles and standardized procurement terms across Midwest converting clusters, tightening pricing discipline while amplifying volume leverage over resin suppliers and quick-service restaurant buyers.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade sachets accelerates because Health Canada serialization mandates are concentrating certified capacity among fewer converters. Three-tier pricing structure across premium, standard, and economy levels separates child-resistant certified pharmaceutical units from food-grade condiment arrays and industrial chemical formats. Price differentiation traces to certification grade and volume scale, with quick-service chains exercising extreme price sensitivity through centralized procurement while cosmetic brands absorb premiums for embossed and holographic decoration.
Supply Chain Analysis
Workforce availability constraints in Chicago, Toronto, and Monterrey metroplexes are pushing automation investment and wage escalation across forming equipment operations. Raw material supply draws from domestic polyethylene producers, three concentrated North American aluminum foil rolling mills, and imported PLA/PHA biopolymer feedstocks. Single-source vulnerability in foil supply creates input cost volatility for high-barrier pharmaceutical structures. Distribution runs through quick-service restaurant procurement consortia and direct-to-consumer fulfillment hubs in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from California's SB 54 extended producer responsibility mandates is forcing mid-tier converters without dual-certification laboratories toward exit or acquisition.
For Market Incumbents: Cement barrier technology leadership through silicon oxide vapor deposition qualification ahead of EPA PFAS restrictions. Acquire distressed biodegradable film extrusion capacity in California's food processing corridor to capture extended producer responsibility fee savings. Lock in multi-year supply agreements with the three North American foil rolling mills to neutralize input cost volatility. For New Entrants and Emerging Players: Quick-service restaurant automation partners offer the most penetrable entry channel for condiment sachet qualification. Target cosmetic sample subscription boxes in California's beauty manufacturing cluster where minimum order quantity compression disadvantages incumbent scale players. Pursue BPI and CMA curbside-compostable certification as the primary go-to-market differentiator against legacy polyethylene laminates. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with Health Canada serialization capabilities in Ontario and Quebec. Long-term viability hinges on regulatory compliance infrastructure rather than pure conversion cost. Monitor EPA PFAS restriction finalization timing as the critical inflection signal for material substitution capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Extrusion Scale-Up | PLA and PHA barrier qualification ahead of California SB 54 plastic reduction deadlines captures extended producer responsibility fee arbitrage. |
| Dual-Certification Laboratory Investment | Parallel FDA and Health Canada testing protocols concentrate pharmaceutical sachet demand among qualified converters. |
| Backward Integration into Resin Compounding | In-house production of certified food-contact and pharmaceutical-grade polymers secures margin control against volatile spot markets. |
| Quick-Service Restaurant Procurement Partnership | Strategic alignment with centralized chain specifications locks in volume commitments for standardized condiment array formats. |
| Child-Resistant Certification Capability Buildout | 16 CFR 1700 protocol testing infrastructure extends pharmaceutical sachet development timelines and concentrates premium margin pools. |
Research Methodology
Document review covered FDA food-contact substance notifications, Health Canada serialization guidance, California SB 54 regulatory filings, and SEC 10-K disclosures from publicly traded packaging conglomerates, complemented by interviews with quick-service restaurant procurement directors, flexible packaging plant managers, pharmaceutical contract manufacturing executives, and resin compounding technical leads. Secondary validation drew from customs and trade data, American Chemistry Council resin production reports, and BPI/CMA compostability certification databases. Bottom-up unit volume estimates triangulated against top-down market value reconstructions.
Cross-referencing historical capacity expansion patterns against expert panel input on substitution timeline acceleration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-user channel, and geographic regulatory cluster. CAGRs derived from regression analysis of correlated demand drivers including quick-service restaurant unit growth, pharmaceutical unit-dose dispensing adoption, and state-level extended producer responsibility fee implementation schedules.
Caveats apply where EPA PFAS restriction finalization, aluminum foil supply disruption, or rapid biodegradable barrier performance degradation could materially shift the outlook. Forecasts embed assumptions about regulatory compliance timeline adherence and material science advancement trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Japan Sachet Packaging Market