
 Germany Sachet Packaging Market | 2026-2036
Germany Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Sachet Packaging Market Insights
The split between premium and commodity tiers in German sachet packaging is hardening as brand owners demand high-barrier, printed laminates for personal care while generic food service pouches compete on unit cost. Constantia Flexibles leverages its Austrian-German manufacturing network to dominate pharmaceutical-grade sachet supply. Sudpack Holding GmbH specializes in recyclable mono-material pouches that align with retailer sustainability mandates. Bischof + Klein SE & Co. KG anchors flexible packaging demand through its long-standing relationships with German confectionery and dairy processors.
Germany sachet packaging denotes small-format, sealed flexible pouches—typically 1–50 ml in volume—constructed from multi-layer polymer films, aluminum laminates, or emerging compostable substrates, produced through horizontal or vertical form-fill-seal processes to deliver portion-controlled dispensing of liquids, gels, or powders. The personal care segment leads value generation due to premium cosmetic sampler demand and travel-retail recovery, while compostable films represent the fastest-growing material category as the EU Green Deal tightens disposal requirements. Resealable closure types command margin premiums in retail channels, whereas tear-notch formats dominate food service and institutional bulk packs where reopening is unnecessary.
The German market operates under REACH chemical safety rules, the EU Packaging and Packaging Waste Regulation's extended producer responsibility schemes, and KBA-adjacent state waste enforcement that shapes local compliance costs. These frameworks compel converters to validate mono-material recyclability and document recycled content quotas, raising barriers for non-compliant imports. Stakeholders must monitor PPWR implementation timelines and pre-emptively certify compostable film streams to avoid displacement when mandatory recycling targets activate.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter margins while forcing rapid substrate transitions, with German brand owners now mandating mono-material recyclability certificates before contract renewal.
Growth Catalysts
- Single-serve coffee adoption:German food service operators are replacing bulk dispensers with portion-controlled sachets to reduce waste and standardize serving sizes across franchise networks.
- REACH chemical safety compliance:Validated barrier coatings that eliminate aluminum layers are unlocking pharmaceutical sampling contracts previously blocked by substance migration concerns.
- North Rhine-Westphalia converting cluster:Concentrated film extrusion and printing capacity in this industrial corridor enables 48-hour turnaround for pan-European brand owner campaigns.
Market Restraints
- Aluminum laminate input volatility:Primary aluminum pricing fluctuations from European smelter energy costs are destabilizing cost-plus contracts for high-barrier pharmaceutical sachets.
- Compostable film certification delays:Industrial composting facility scarcity across German states is creating disposal infrastructure gaps that undermine compostable substrate value propositions.
- Mono-material technical ceiling:Current polyethylene barrier performance falls short of oxygen transmission requirements for retorted condiment applications, locking in multi-layer dependence.
Strategic Opportunities
- Baden-Württemberg precision manufacturing:Automotive supplier conversion expertise in this southwestern state offers transferable automation capabilities for pharmaceutical-grade sachet lines.
- EU Green Deal packaging mandates:Mandatory recycled content quotas from 2030 create first-mover advantage for converters with pre-certified post-consumer polyethylene feedstock streams.
- Travel-retail sampler recovery:Premium cosmetic brand owners are expanding miniature format portfolios as duty-free passenger volumes rebound through Frankfurt and Munich hubs.
Industry Challenges
- Multi-layer delamination expertise shortage:German technical universities produce fewer polymer processing engineers than converter hiring pipelines require, elongating R&D cycle times for recyclable substrate development.
- Legacy form-fill-seal retrofit costs:Horizontal FFS equipment installed during the 2010s lacks servo-driven precision for ultra-thin mono-material films, forcing capital-intensive line replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Sachet Packaging Market |
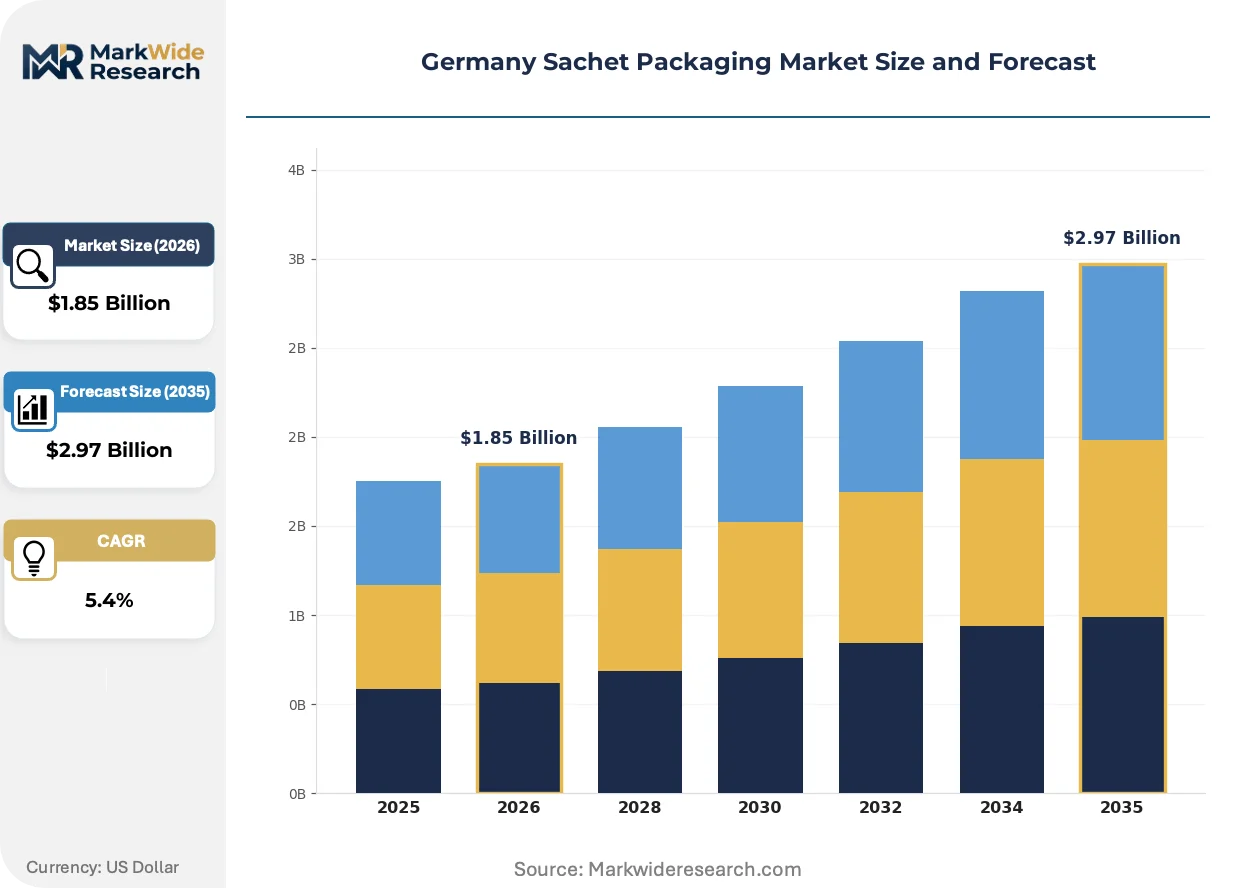
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverages, Personal Care, Household Products Material: Plastic, Paper, Aluminum, Compostable Films Closure Type: Resealable, Non-resealable, Spout, Tear Notch End User: Retail, E-commerce, Wholesale, Food Service |
| Companies Covered | Constantia Flexibles, Huhtamaki Group, Mondi Group, Amcor Plc, Sudpack Holding GmbH, Coveris Management GmbH, Bischof + Klein SE & Co. KG, Sonoco Products Company, ProAmpac Holdings LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Sachet Packaging Market Trends and Innovations
Digital printing integration and compostable barrier chemistry are converging to collapse minimum order quantities while satisfying retailer sustainability scorecards.
Water-based high-barrier coatings are overtaking solvent-based lamination in premium cosmetic samplers. German personal care brand owners are specifying these coatings for travel-retail exclusives to meet retailer chemical disclosure requirements. This transition is overtaking conventional gravure-printed aluminum laminates in segments where shelf presence justifies unit cost premiums.
Extended producer responsibility schemes under the EU Packaging and Packaging Waste Regulation are reallocating end-of-life costs onto converters. German state-level KBA enforcement is tightening documentation requirements for recyclability claims, forcing material suppliers to commission third-party sorting trials. Pharmaceutical sachet specifications remain partially exempt, creating a compliance bifurcation between regulated and unregulated end-uses.
Brand owner procurement teams are consolidating supplier panels to reduce audit burden. Mid-sized German confectionery processors are losing access to major retail listings as buying power concentrates among pan-European category managers. This concentration is most visible in North Rhine-Westphalia, where former regional dairy sachet contracts are migrating to Austrian-German integrated converters with pan-European service capabilities.
Germany Sachet Packaging Market Segmentation
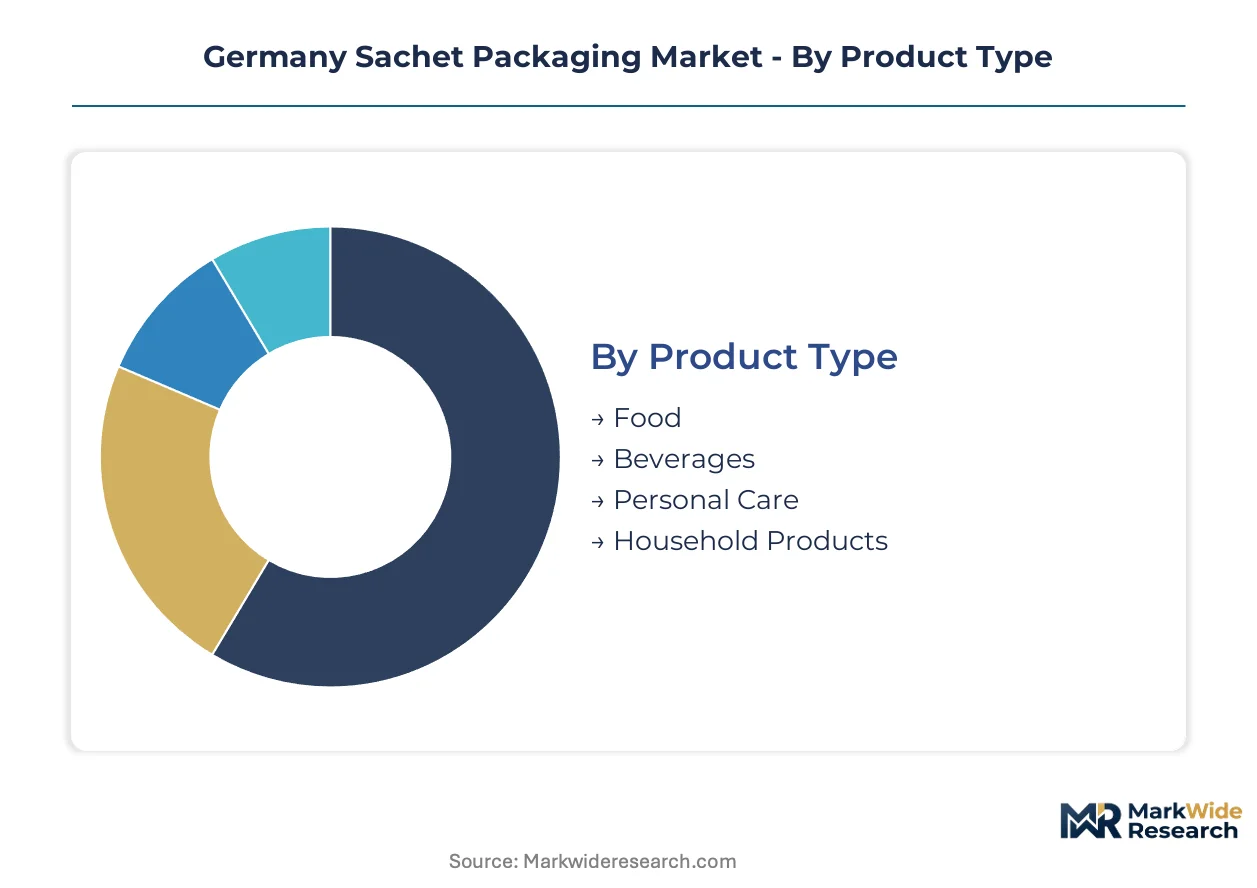
German sachet packaging demand fragments across substrate technologies, product categories, and dispensing formats. Each segmentation axis carries distinct margin profiles and compliance burdens under evolving EU packaging mandates.
Product Type:
Replacement cycles vary sharply across end-use categories, with food service operators refreshing formats faster than industrial household buyers.
- Personal Care:Premium cosmetic samplers and travel-retail miniatures deploy high-barrier laminates with gravure-printed branding. Frankfurt and Munich airport duty-free recovery is accelerating miniature format procurement from North Rhine-Westphalia converters.
- Food:Single-serve condiments and sauce portions dominate quick-service restaurant procurement, though retort compatibility requirements perpetuate aluminum laminate dependence. German franchise networks are standardizing sachet dimensions to reduce dispensing machine retrofit costs.
- Beverages:Concentrated drink mixes and single-serve coffee pods utilize moisture-resistant films with oxygen scavenger layers. Food service operators are displacing bulk dispensers with portion-controlled formats to reduce waste.
- Household Products:Detergent samples and cleaning wipes employ cost-optimized polyethylene structures for promotional distribution. Retailer sustainability scorecards are beginning to restrict non-recyclable substrates in this category.
Volume placements concentrate in Food; the faster expansion belongs to Personal Care.
Material:
Cost tiers separate commodity substrates from certified sustainable alternatives, with compliance documentation becoming a de facto pricing dimension.
- Plastic:Multi-layer polyethylene and polypropylene laminates retain cost advantages for high-volume food service contracts. Mono-material recyclability certificates are now mandatory for renewal with German retail chains.
- Compostable Films:Polylactic acid and cellulose-based substrates command 40-60% premiums over conventional plastics. Industrial composting infrastructure gaps across German states are limiting disposal pathway reliability.
- Aluminum:High-barrier foils remain essential for pharmaceutical sampling and retorted food applications. European smelter energy cost volatility is destabilizing long-term contract pricing.
- Paper:Fiber-based pouches with bio-based barrier coatings are penetrating dry goods and confectionery segments. Water-based coating R&D is advancing to replace polyethylene linings in premium chocolate sampler applications.
Plastic substrates retain the largest installed base; compostable films are climbing the fastest.
Closure Type:
Application requirements dictate dispensing mechanism selection, with resealability commanding substantial margin premiums in retail channels.
- Resealable:Zipper and press-to-close mechanisms add 15-25% to unit costs while enabling multi-dose personal care formats. German cosmetic brand owners specify these for premium sampler lines targeting travel-retail exclusivity.
- Tear Notch:Perforated opening features dominate food service and institutional bulk packs where single-use consumption patterns eliminate reopening needs. Horizontal form-fill-seal lines achieve highest throughput with this simplest format.
- Spout:Fitment-integrated pouches enable controlled dispensing of viscous personal care gels and liquid detergents. Baden-Württemberg automation suppliers are developing precision placement equipment for pharmaceutical-grade spouted sachets.
- Non-resealable:Basic heat-sealed edges persist in lowest-cost condiment and sauce portions. This format faces displacement pressure as EU extended producer responsibility schemes reallocate end-of-life costs.
Tear notch configurations capture the highest shipment volumes; resealable closures are gaining share fastest in premium segments.
End User:
Customer type determines order scale, specification stringency, and sustainability documentation requirements.
- Food Service:Franchise networks and institutional caterers procure standardized formats in million-unit batches with minimal customization. North Rhine-Westphalia converting clusters serve pan-European food service distributors with 48-hour campaign turnaround.
- Retail:Supermarket and drugstore chains demand recyclable mono-material constructions with third-party sorting trial documentation. KBA-adjacent state enforcement is tightening recyclability claim verification requirements.
- E-commerce:Direct-to-consumer subscription boxes favor compact, lightweight sachets for sample assortment shipping. Unboxing experience specifications are elevating print quality requirements for this channel.
- Wholesale:Industrial and janitorial supply distributors purchase bulk-packed generic formats with minimal branding. Price competition is most intense in this segment as mid-sized German processors lose share to integrated converters.
Food service generates the largest order volumes; retail channels are imposing the steepest compliance cost escalations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's industrial corridor anchors German sachet packaging demand through concentrated film extrusion and converting capacity that serves pan-European brand owners with rapid campaign turnaround.
North Rhine-Westphalia
Food service distributors and franchise networks drive sachet procurement volumes across this western industrial belt. The KBA enforces strict packaging waste documentation requirements that elevate compliance costs for converters operating here. Düsseldorf and Cologne host converting clusters where 48-hour production turnaround supports pan-European retail campaigns.
Baden-Württemberg
Precision manufacturing expertise from automotive supply chains transfers into pharmaceutical-grade sachet automation systems. REACH chemical safety compliance for barrier coatings attracts personal care brand owners seeking validated substrate solutions. Stuttgart and Karlsruhe house engineering specialists developing servo-driven form-fill-seal equipment for ultra-thin mono-material films.
Bavaria
Munich's travel-retail recovery accelerates demand for premium cosmetic sampler formats through its international airport hub. The EU Packaging and Packaging Waste Regulation mandates mono-material recyclability certificates for retail channel access. Nuremberg and Augsburg converters supply confectionery processors with high-barrier laminates for chocolate portion packs.
Lower Saxony
Dairy processors and agricultural cooperatives procure bulk condiment sachets for institutional food service channels. Extended producer responsibility schemes under federal packaging law reallocate end-of-life costs onto converters serving this northern region. Hanover and Braunschweig maintain distribution infrastructure connecting to North Sea ports for export-oriented production.
Hesse
Frankfurt's airport duty-free expansion drives miniature format procurement for premium cosmetic brand portfolios. The EU Green Deal's 2030 recycled content quotas pressure converters to certify post-consumer polyethylene feedstock streams. Offenbach and Darmstadt host mid-sized processors losing retail listings to integrated converters with pan-European service capabilities.
Germany Sachet Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with validated mono-material recyclability separating contract winners from displacement risks. The vendor base stratifies between integrated multinational converters, regional specialists with deep customer relationships, and mid-sized processors facing panel consolidation. Three archetypes dominate: Austrian-German integrated networks with pharmaceutical-grade capabilities, mono-material recyclability specialists aligned with retailer mandates, and legacy processors anchored in confectionery and dairy supply chains. Competitive moves concentrate on backward integration into film extrusion and pre-emptive certification of compostable substrate streams.
Among German and Austrian integrated converters, Constantia Flexibles, Sudpack Holding GmbH, and Bischof + Klein SE & Co. KG occupy distinct positioning within this tiered structure. Constantia Flexibles represents the cross-border integrated archetype leveraging manufacturing networks for pharmaceutical-grade supply. Sudpack Holding GmbH exemplifies the sustainability-aligned specialist focused on recyclable mono-material constructions. Bischof + Klein SE & Co. KG anchors the legacy relationship tier through long-standing ties with domestic confectionery and dairy processors.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Huhtamaki Group |
| Mondi Group |
| Amcor Plc |
| Sudpack Holding GmbH |
| Coveris Management GmbH |
| Bischof + Klein SE & Co. KG |
| Sonoco Products Company |
| ProAmpac Holdings LLC |
| Others |
Pricing and Supply Chain Analysis
EU Packaging and Packaging Waste Regulation mandates for mono-material recyclability certificates are compressing converter margins and forcing rapid substrate transitions, compelling supply chains to absorb certification costs while brand owners demand price stability. This regulatory pressure concentrates pricing power among integrated converters with pre-certified film streams, while mid-sized processors face displacement from retail supplier panels.
Pricing Analysis
Throughput-based contract structures dominate food service procurement, with million-unit batch pricing indexed to 48-hour campaign turnaround capabilities. Price differentiation separates pharmaceutical-grade barrier laminates with REACH-validated coatings from generic polyethylene condiment pouches. Cost compression in commodity tiers intensifies as aluminum laminate input volatility from European smelter energy costs destabilizes cost-plus agreements. Franchise networks exhibit highest price sensitivity, whereas premium cosmetic brand owners in travel-retail channels absorb unit cost premiums for gravure-printed sampler formats.
Supply Chain Analysis
KBA-adjacent state enforcement of extended producer responsibility schemes is reshaping sourcing patterns toward domestic film extrusion capacity with third-party sorting trial documentation. Raw material supply draws from Austrian-German integrated polymer processing, Italian gravure printing equipment, and Nordic pulp sources for emerging paper-based barrier developments. Single-source vulnerability concentrates in pharmaceutical-grade aluminum foil supply from European smelters facing energy cost instability. Distribution runs through North Rhine-Westphalia converting clusters serving pan-European brand owners with just-in-time campaign logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified mono-material recyclability capacity scarcity props pricing power for compliant converters, creating supply-constrained conditions that favor first-movers with pre-validated substrate streams.
For Market Incumbents: Acquire industrial composting facility partnerships to close disposal infrastructure gaps undermining compostable film value propositions. Backward integration into post-consumer polyethylene feedstock streams secures first-mover positioning ahead of mandatory recycled content quotas. Defend against Austrian-German integrated networks by anchoring regional relationships with North Rhine-Westphalia dairy and confectionery processors through dedicated line capacity guarantees. For New Entrants and Emerging Players: Begin with Baden-Württemberg precision manufacturing partnerships to transfer automotive supplier automation expertise into pharmaceutical-grade sachet equipment. Target e-commerce subscription box channels where unboxing experience specifications elevate print quality requirements and minimum order quantities collapse. Pursue direct-to-consumer sampler assortment contracts with premium cosmetic brand owners expanding miniature format portfolios through Frankfurt and Munich airport duty-free recovery. For Investors and Strategic Acquirers: The window for entry favors mono-material recyclability specialists with pre-certified substrate streams and established retailer sustainability scorecard relationships. Long-term viability hinges on converters with validated compostable film disposal pathways and documented post-consumer feedstock supply agreements. Watch for PPWR implementation timeline acceleration as the inflection signal that displaces non-compliant imports from retail supplier panels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive supply of mono-material substrates satisfies KBA documentation requirements for retail channel access. |
| Compostable Film Certification Program | Pre-emptive third-party sorting trials align with EU Green Deal tightening of disposal requirements. |
| Precision Automation Partnership | Baden-Württemberg servo-driven form-fill-seal expertise enables ultra-thin mono-material film handling. |
| Long-term Supply Agreement | Fixed-price aluminum laminate contracts hedge European smelter energy cost volatility for pharmaceutical tiers. |
| Sustainability Repositioning | Water-based barrier coating R&D replaces solvent-based lamination for travel-retail chemical disclosure compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Germany sachet packaging analysis. Primary interviews with converting plant managers, brand owner procurement leads, polymer processing engineers, and KBA state enforcement officers combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, REACH chemical safety filings, and North Rhine-Westphalia industrial cluster production statistics. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Segment-level granularity modeled substrate technologies, product categories, dispensing formats, and end-user channels across the projection horizon. Personal care, food, beverage, and household product demand trajectories incorporated replacement cycle variations and compliance cost escalations. CAGRs derived from trend extrapolation of single-serve coffee adoption rates, travel-retail passenger volume recovery patterns, and pharmaceutical sampling contract migration toward validated barrier coatings. Industry-specific inputs included aluminum laminate pricing volatility indices and industrial composting facility capacity expansion pipelines.
Underlying measurement precision varies by segment; pharmaceutical-grade and premium cosmetic sampler categories carry tighter precision than generic food service condiment tiers due to specification documentation density. Forecasts reflect assumptions regarding PPWR implementation timelines, REACH barrier coating validation throughput, and compostable film disposal infrastructure development that could revise trajectories if regulatory acceleration or facility construction delays materialize. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
India Sachet Packaging Market