
 Sachet Packaging Machines Market | 2026-2036
Sachet Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Sachet Packaging Machines Market Outlook
Premium-grade sanitary construction is rotating through pharmaceutical and probiotic applications where clean-in-place compatibility and allergen isolation command priority. Syntegon Technology GmbH leverages its Bosch heritage in containment engineering to sustain high-specification order flow. MULTIVAC SEPP HAGGENMÜLLER SE & Co. KG anchors thermoforming-to-sachet integration for medical device packaging. Ishida Co., Ltd. dominates precision weighing integration in Asian multi-lane installations.
Sachet packaging machines are electromechanical systems that form, fill, and seal small flexible pouches typically ranging from 1 milliliter to 100 milliliters using heat-sealable films or laminates; they operate at speeds from 40 to 1,200 cycles per minute depending on lane configuration and product viscosity. These machines serve manufacturers seeking portion control, extended shelf stability, and low material cost per unit in mass-consumer goods. Vertical form fill seal equipment occupies the largest installed base due to its mechanical simplicity and adaptability to granular and liquid products alike. Automatic technology leads new capital expenditure as labor cost arbitrage diminishes across emerging manufacturing zones. Multi-lane systems represent the fastest-growing configuration where pharmaceutical strip packaging and condiment multipacks drive throughput requirements.
FDA cGMP guidelines and EU MDR requirements enforce validated seal integrity and batch traceability for pharmaceutical sachet lines, while REACH and EU Packaging and Packaging Waste Regulation constrain material selection toward mono-material or recyclable laminate structures. China's SAMR implements GB standards for food contact materials that restrict additive migration in plastic film sachets. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to retrofit existing lines for compatible substrates or invest in greenfield robotic systems designed for thinner, harder-to-seal films.
Market Dynamics
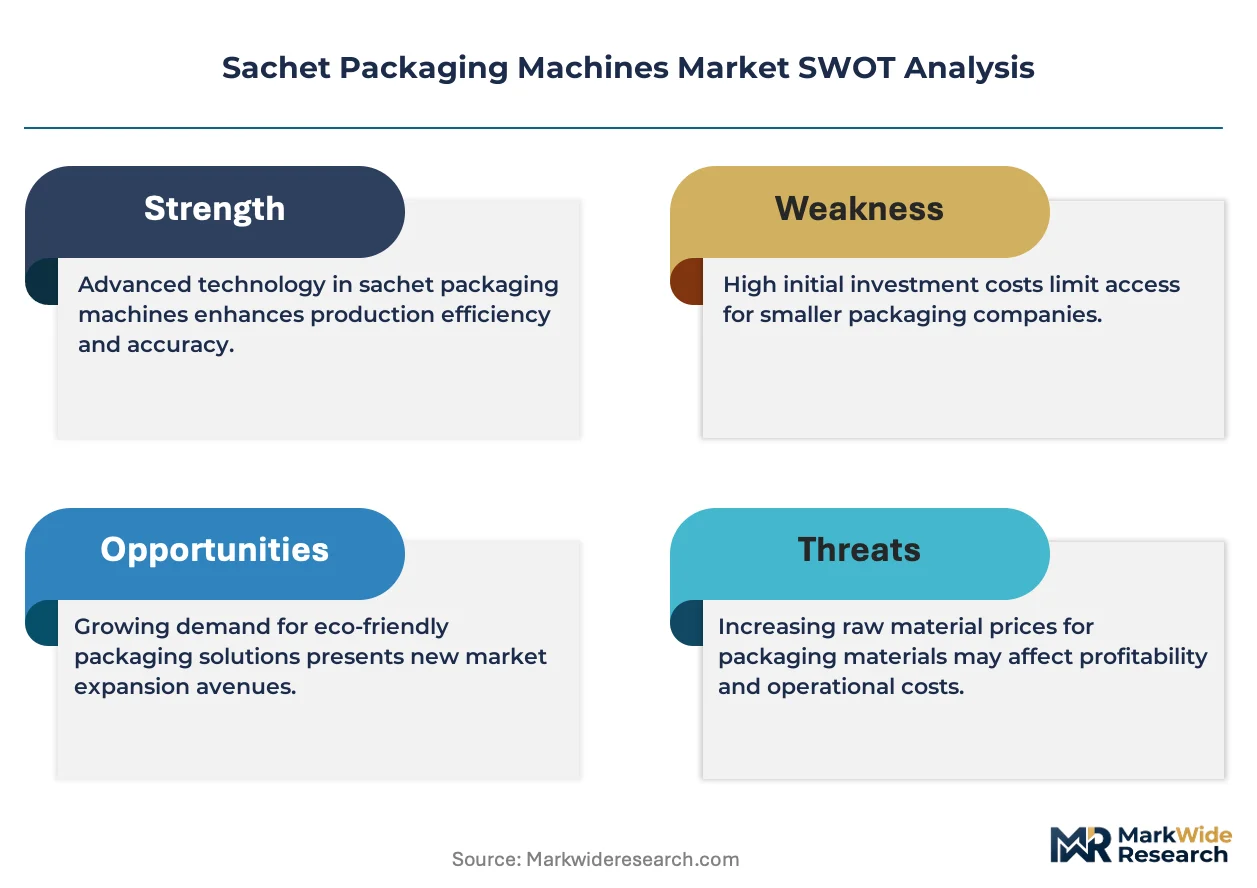
Mono-material film mandates are compressing incumbent sealing technologies while forcing equipment retrofits across installed bases in Europe and Asia-Pacific.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding recycled content quotas for flexible packaging are compelling manufacturers to upgrade lines for compatible substrates. This regulatory pressure accelerates capital deployment toward modular sealing systems.
- Instant coffee sachet volumes:Southeast Asian beverage producers are expanding single-serve format lines in Vietnam and Indonesia, creating concentrated demand for high-speed multi-lane configurations.
- Clean-in-place compatibility:Pharmaceutical and probiotic applications now require sanitary construction with validated allergen isolation, pulling premium-grade equipment orders.
Market Restraints
- Specialized laminate supply concentration:Heat-sealable mono-material films with adequate barrier properties remain concentrated among a limited supplier base in Germany and Japan, creating input bottlenecks.
- Thin-film sealing limitations:Downgauged recyclable substrates require tighter temperature control windows that legacy pneumatic systems cannot consistently achieve.
- REACH compliance friction:Chemical registration requirements for adhesive layers in multi-ply structures extend material qualification timelines by 12-18 months.
Strategic Opportunities
- Underpenetrated African markets:Condiment and oral rehydration salt sachet production in Nigeria and Kenya relies heavily on semi-automatic equipment, creating upgrade potential as labor costs rise.
- Medical device thermoforming convergence:Integration of thermoforming and sachet sealing into single lines addresses sterile barrier packaging demand for catheters and surgical kits.
- India PLI scheme for food processing:Capital subsidy incentives for packaging machinery are attracting greenfield investments in Gujarat and Maharashtra.
Industry Challenges
- Mechatronics skill scarcity:Servo-driven multi-lane systems require technicians proficient in both mechanical alignment and programmable logic controllers, a combination scarce in Vietnam and Indonesia.
- Legacy line integration complexity:Retrofitting existing vertical form fill seal equipment for thinner films demands coordinated upgrades to sealing jaws, temperature controllers, and film transport systems.
- FDA cGMP validation timelines:Pharmaceutical sachet lines require documented seal integrity protocols that extend commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sachet Packaging Machines Market |
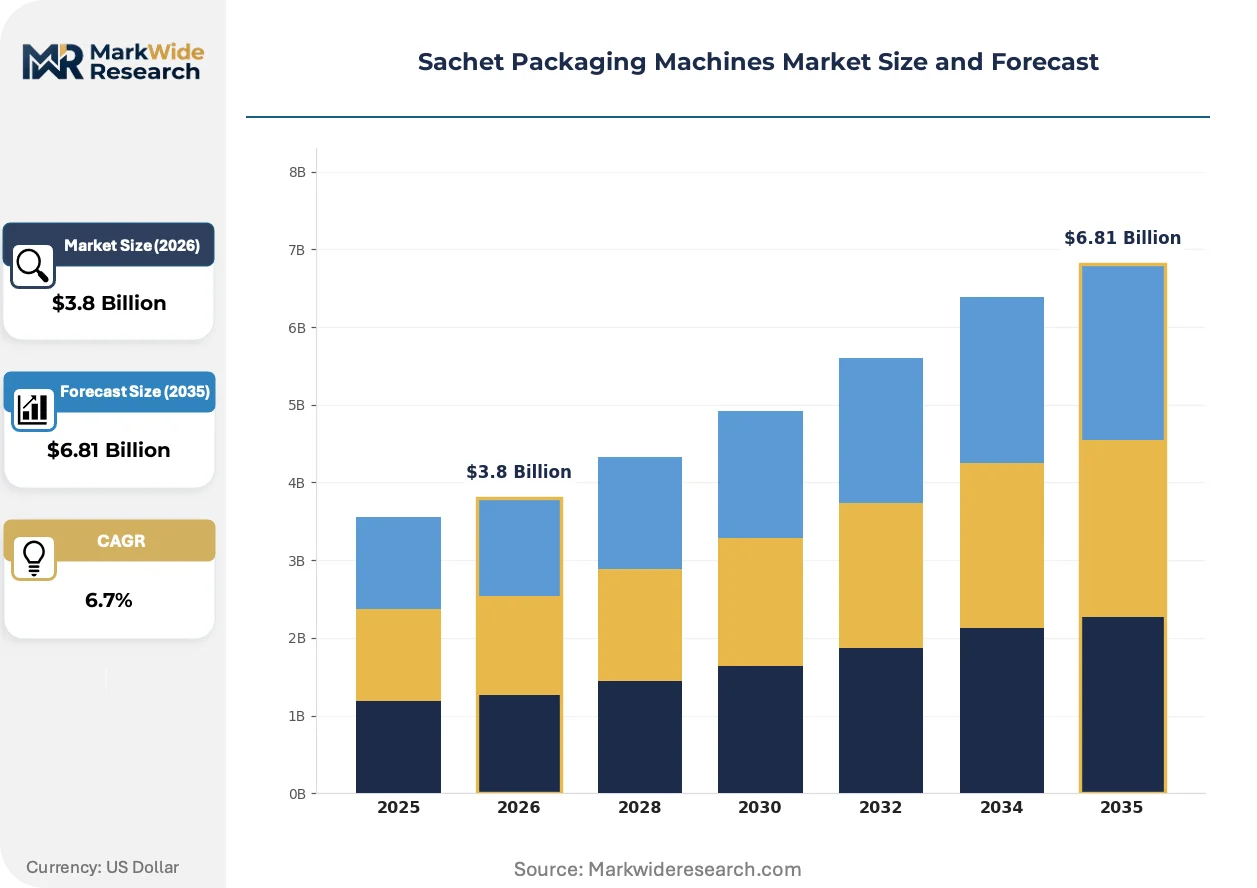
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Form Fill Seal, Horizontal Form Fill Seal, Multi-Lane, Sachet Filling Machines End User: Food & Beverages, Pharmaceuticals, Personal Care, Household Products Technology: Automatic, Semi-Automatic, Manual, Robotic Packaging Material: Plastic Films, Aluminum Foil, Paper, Composites |
| Companies Covered | MULTIVAC SEPP HAGGENMÜLLER SE & Co. KG, Kliklok International Ltd., Hangzhou Shengde Machinery Co., Ltd., Syntegon Technology GmbH, Romaco Group, Uhlmann Pac-Systeme GmbH & Co. KG, GEA Group Aktiengesellschaft, Triangle Package Machinery Company, Ishida Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sachet Packaging Machines Market Strategic Shifts
Electromechanical sealing architectures are displacing pneumatic systems across high-throughput installations, while regulatory material mandates and procurement model evolution reshape competitive requirements.
Ultrasonic sealing technology is fragmenting traditional heat-bar approaches in pharmaceutical and probiotic packaging lines. This method uses high-frequency mechanical vibration rather than thermal conduction to bond films, enabling reliable seals on temperature-sensitive substrates. European medical device manufacturers are adopting it fastest, with Asian pharmaceutical contract packers following within 18-24 month lag cycles. The technology is fragmenting equipment vendor specialization, as ultrasonic competence now separates premium-tier suppliers from standard-tier competitors.
REACH restrictions on per- and polyfluoroalkyl substances in food contact materials are eliminating grease-resistant fluoropolymer coatings from sachet film laminates. This regulatory shift forces reformulation of barrier layers toward silicon oxide or aluminum oxide vapor-deposited alternatives. Condiment and instant soup producers in Germany and France face the tightest compliance deadlines and are accelerating qualification of new film structures with equipment suppliers.
Equipment-as-a-service contracting is displacing outright purchase models among mid-scale Southeast Asian food processors. Under this arrangement, packagers pay per million sachets produced while vendors retain ownership and maintenance responsibility. This model compresses customer capital requirements but demands vendors build regional spare parts inventories and field service density. The shift is most visible in Vietnam, where instant coffee co-packers favor operational expenditure structures over balance-sheet-heavy investments.
Sachet Packaging Machines Market Segmentation
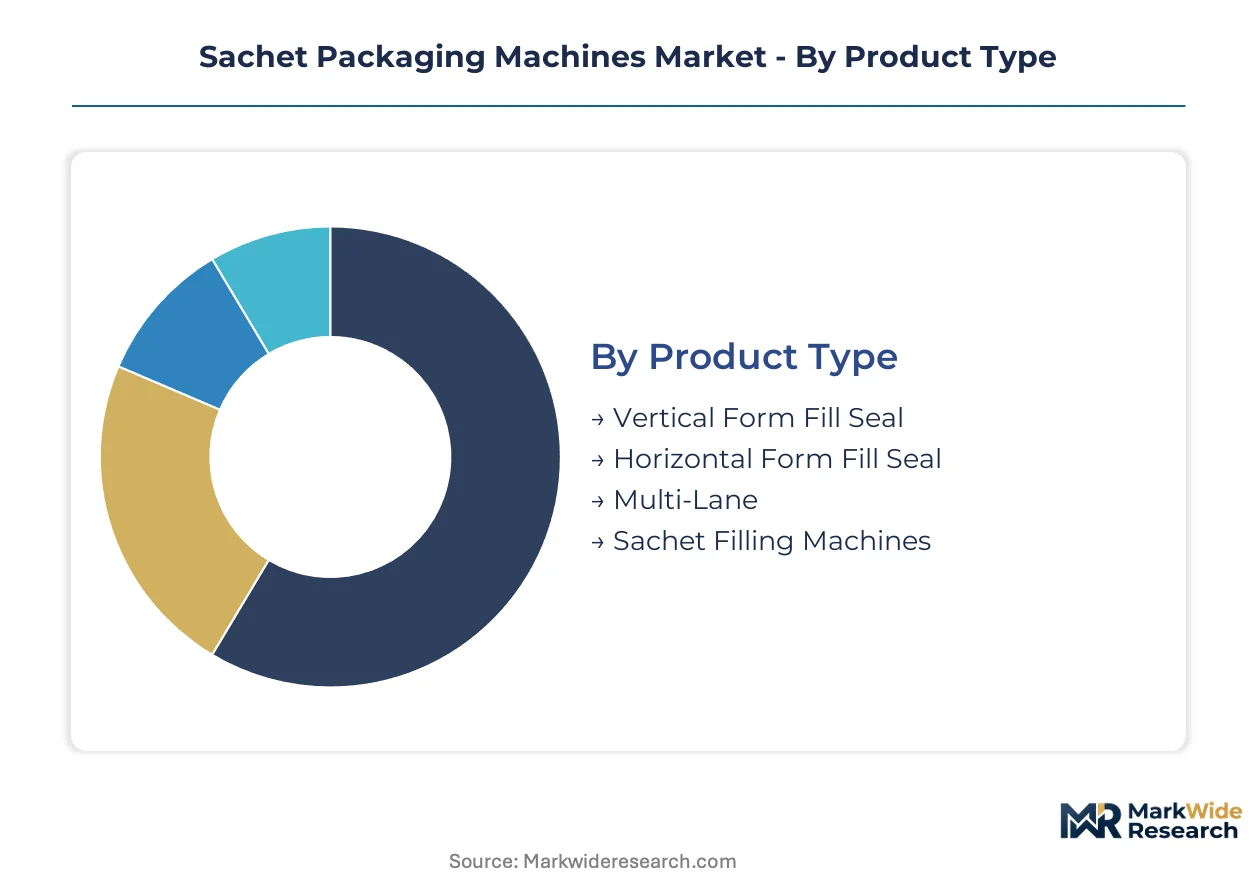
Sachet packaging machines serve divergent compliance regimes across pharmaceutical, food, and consumer goods verticals, with equipment specification tightly coupled to substrate compatibility and validation requirements. Segmentation reveals how regulatory pressure on mono-material films and sanitary construction reshapes capital allocation across machine categories.
Product Type:
EU MDR and FDA cGMP validation protocols differentiate equipment tiers through seal integrity documentation requirements and clean-in-place compatibility.
- Vertical Form Fill Seal:Mechanical simplicity and broad adaptability to granular and liquid products sustain the largest installed base. Food and beverage producers in Vietnam and Indonesia favor this configuration for instant coffee and condiment sachets where speed and reliability outweigh precision demands. Established volume favors Vertical Form Fill Seal; emerging adoption favors Multi-Lane.
- Multi-Lane:Parallel processing architectures achieve 40 to 1,200 cycles per minute through electromechanical synchronization of multiple forming and sealing stations. Pharmaceutical strip packaging and condiment multipacks in Southeast Asia drive concentrated demand for high-throughput configurations that justify premium capital expenditure. This segment gains share fastest where labor cost arbitrage diminishes.
- Horizontal Form Fill Seal:Film transport geometry suits medical device and sterile barrier applications requiring controlled atmosphere forming.
- Sachet Filling Machines:Standalone filling modules integrate with third-party sealing systems for custom line configurations in contract packaging environments.
Established volume favors Vertical Form Fill Seal; emerging adoption favors Multi-Lane.
End User:
Application-specific validation timelines and material qualification requirements create divergent procurement cycles across customer verticals.
- Food & Beverages:Instant coffee sachet volumes in Vietnam and Indonesia concentrate demand for high-speed multi-lane systems. REACH restrictions on per- and polyfluoroalkyl substances and EU Packaging and Packaging Waste Regulation recycled content quotas compel line upgrades for mono-material film compatibility. This vertical commands the steepest expansion trajectory.
- Pharmaceuticals:Probiotic and oral dosage applications require premium-grade sanitary construction with validated allergen isolation and clean-in-place protocols. FDA cGMP guidelines and EU MDR requirements enforce documented seal integrity and batch traceability, extending commissioning periods. European medical device manufacturers lead adoption of ultrasonic sealing for temperature-sensitive substrates.
- Personal Care:Single-serve shampoo and cosmetic samples drive demand for precision dosing and aesthetic seal quality in Asian markets.
- Household Products:Detergent and cleaning agent sachets prioritize chemical resistance and cost-efficient throughput over validation complexity.
Regulatory stringency concentrates margin in Pharmaceuticals; volume scale concentrates in Food & Beverages.
Technology:
Labor cost structures and technician availability determine automation tier selection across emerging manufacturing zones.
- Automatic:Servo-driven architectures with programmable logic controllers dominate new capital expenditure as labor cost arbitrage diminishes across Southeast Asia. Electromechanical sealing systems displace pneumatic alternatives where tighter temperature control windows are required for downgauged recyclable substrates. Nigeria and Kenya present upgrade potential from semi-automatic baselines as wage pressures mount.
- Semi-Automatic:Operator-assisted configurations persist in African condiment and oral rehydration salt production where capital constraints limit full automation.
- Manual:Benchtop units serve micro-scale producers and pilot line qualification in fragmented developing markets.
- Robotic:Articulated handling systems integrate with thermoforming modules for sterile medical device packaging at European manufacturers.
Capital deployment favors Automatic; penetration gaps favor Semi-Automatic in underdeveloped regions.
Packaging Material:
Substrate selection constrains sealing technology compatibility and determines equipment retrofit requirements across installed bases.
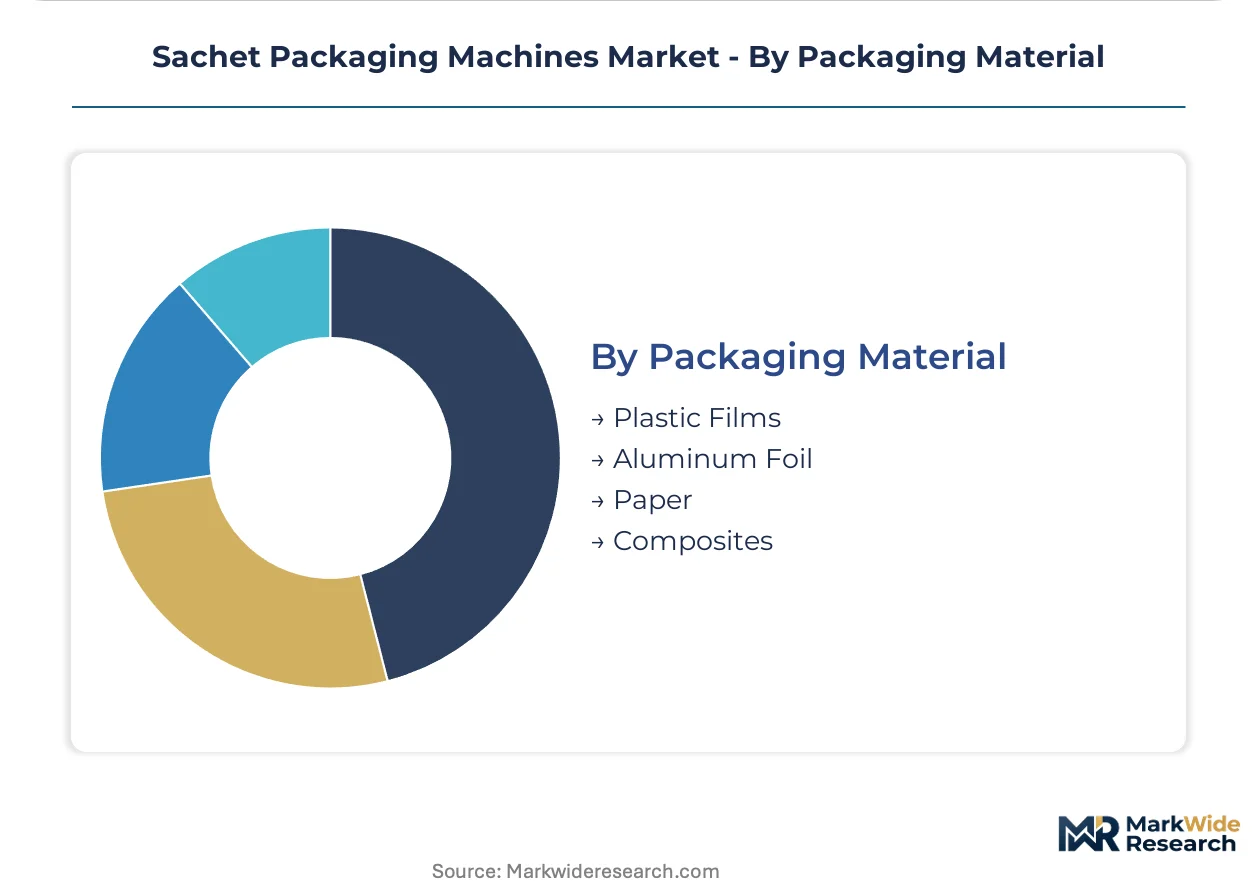
- Plastic Films:Heat-sealable mono-material structures dominate flexible packaging volumes. Germany and Japan concentrate supply of barrier-grade films with adequate oxygen and moisture protection, creating input bottlenecks. China's SAMR GB standards restrict additive migration in food contact applications.
- Aluminum Foil:Vapor-deposited barrier layers replace fluoropolymer-coated alternatives under REACH restrictions, requiring requalified sealing parameters.
- Paper:Fiber-based substrates gain traction in European personal care applications with limited barrier demands.
- Composites:Multi-ply laminates face extended qualification timelines under REACH chemical registration requirements for adhesive layers.
Regulatory momentum favors Plastic Films; barrier performance favors Aluminum Foil in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier-grade film supply concentrates in Germany and Japan, while equipment demand clusters in Southeast Asian manufacturing zones where instant coffee and condiment sachet volumes are climbing fastest.
Germany
Heat-sealable mono-material film production anchors European supply chains, with vapor-deposited barrier layers replacing fluoropolymer-coated alternatives under REACH restrictions. The country's chemical regulator enforces extended qualification timelines for adhesive layers in multi-ply structures. Industrial machinery specialists in Baden-Württemberg and Bavaria sustain premium-grade equipment order flow for pharmaceutical applications.
Japan
Precision weighing integration dominates Asian multi-lane installations, serving probiotic and oral dosage packaging lines with validated allergen isolation protocols. METI standards guide servo-driven automation adoption as labor cost arbitrage diminishes. Equipment fabricators in the Chubu region around Nagoya anchor thermoforming-to-sachet integration for medical device packaging.
Vietnam
Instant coffee co-packers are expanding single-serve format lines, creating concentrated demand for high-speed multi-lane configurations. Equipment-as-a-service contracting displaces outright purchase models among mid-scale food processors favoring operational expenditure structures. Ho Chi Minh City industrial zones attract capital subsidy inflows for packaging machinery deployment.
Indonesia
Condiment sachet volumes are driving throughput requirements for electromechanical sealing architectures that displace pneumatic systems. The country's national food safety regulator implements additive migration restrictions in plastic film sachets that constrain material selection. Manufacturing clusters in Java face mechatronics skill scarcity as servo-driven systems require technicians proficient in both mechanical alignment and programmable logic controllers.
India
Capital subsidy incentives under the PLI scheme for food processing are attracting greenfield investments in Gujarat and Maharashtra. Semi-automatic equipment persists in fragmented developing markets, though automatic technology leads new capital expenditure as wage pressures mount. Mumbai-Pune industrial corridors see rising procurement of clean-in-place compatible systems for sanitary construction requirements.
Sachet Packaging Machines Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the sachet packaging machines market. European and Japanese manufacturers anchor premium-tier positioning through containment engineering heritage and precision integration capabilities, while Chinese fabricators occupy cost-optimized segments serving high-volume food processing markets. Three strategic archetypes dominate: precision weighing specialists, thermoforming integrators, and multi-lane synchronization experts. Competitive moves concentrate on modular sealing system development for mono-material film compatibility and regional field service density expansion to support equipment-as-a-service contracting.
Within the premium-tier vector, Syntegon Technology GmbH and MULTIVAC SEPP HAGGENMÜLLER SE & Co. KG occupy positions anchored by European engineering heritage and medical device packaging integration. Ishida Co., Ltd. represents the precision weighing specialist archetype in Asian multi-lane installations. These three exemplify how regulatory validation requirements and substrate compatibility demands stratify competitive positioning across pharmaceutical, food, and consumer goods verticals.
| Leading Market Players |
|---|
| MULTIVAC SEPP HAGGENMÜLLER SE & Co. KG |
| Kliklok International Ltd. |
| Hangzhou Shengde Machinery Co., Ltd. |
| Syntegon Technology GmbH |
| Romaco Group |
| Uhlmann Pac-Systeme GmbH & Co. KG |
| GEA Group Aktiengesellschaft |
| Triangle Package Machinery Company |
| Ishida Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Vapor-deposited barrier layers replacing fluoropolymer-coated films are simultaneously shifting supply geography toward Germany and Japan while compressing pricing power for legacy pneumatic sealing equipment. This substitution dynamic forces equipment vendors to absorb requalification costs or concede margin to retain pharmaceutical and food processing accounts.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the installed base, with three-tier pricing separating pharmaceutical-grade sanitary systems from standard food processing units and economy semi-automatic configurations. Price differentiation rests on clean-in-place certification tier and servo-driven electromechanical architecture versus pneumatic legacy systems. Cost compression in mid-tier food processing equipment is intensifying because mono-material film mandates demand coordinated upgrades to sealing jaws and temperature controllers. Contract packaging operations in Vietnam exhibit highest price sensitivity due to equipment-as-a-service contracting preferences, while European medical device manufacturers show lowest sensitivity given validation timeline costs.
Supply Chain Analysis
Regional spare parts inventories and field service density determine lead-time performance for equipment-as-a-service contracts in Southeast Asia. Heat-sealable mono-material film supply concentrates in Germany and Japan, while precision weighing integration components anchor in Japanese Chubu region manufacturing clusters. Equipment fabrication draws from specialty servo motor suppliers in Germany, precision sensors from Japan, and control systems from Taiwan. Single-source vulnerability persists in barrier-grade film supply where REACH restrictions have eliminated alternative fluoropolymer-coated suppliers. Distribution runs through OEM-direct channels for pharmaceutical accounts and regional distributor networks for food processing equipment in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sachet packaging machines market represents high-growth disruption as ultrasonic sealing technology fragments traditional heat-bar approaches and regulatory material mandates force wholesale equipment replacement cycles across European and Asian installed bases.
For Market Incumbents: Shield premium-tier positioning by deepening ultrasonic sealing competence ahead of 18-24 month Asian adoption lag cycles. Acquire or partner with mono-material film qualification specialists to control substrate compatibility validation timelines. Vertical integration into regional spare parts warehousing secures equipment-as-a-service contract viability against emerging Chinese fabricators.
For New Entrants and Emerging Players: FDA cGMP fast-track certification programs offer entry into pharmaceutical contract packaging where incumbent validation backlogs create queue advantages. Target semi-automatic equipment upgrade cycles in Nigeria and Kenya condiment production before wage pressures accelerate automatic technology adoption. Lead with equipment-as-a-service contracting to bypass capital constraint barriers among mid-scale Southeast Asian food processors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European precision weighing specialists holding Ishida-tier integration capabilities but lacking ultrasonic sealing R&D investment. Five-to-ten year viability hinges on regulatory compliance technology rather than volume scale. Monitor EU MDR seal integrity documentation requirements as the inflection signal separating acquisition targets with sustainable moats from stranded legacy equipment portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Technology Adoption | Enables reliable seals on temperature-sensitive substrates for European medical device manufacturers. |
| Mono-Material Film Line Retrofit | Addresses EU Packaging and Packaging Waste Regulation recycled content quotas for flexible packaging. |
| Equipment-as-a-Service Contracting | Compresses customer capital requirements while demanding regional field service density in Vietnam. |
| Clean-in-Place Compatibility Investment | Satisfies FDA cGMP guidelines and EU MDR requirements for pharmaceutical probiotic applications. |
| Regional Spare Parts Warehousing | Supports equipment-as-a-service maintenance responsibility for Southeast Asian instant coffee co-packers. |
Study Parameters
Cross-validation between machinery OEM technical documentation and regulatory filing databases anchors the qualitative findings in this study. Primary interviews with packaging line engineers, pharmaceutical contract manufacturing executives, food processing plant managers, and equipment procurement directors at Southeast Asian beverage producers combined with secondary validation from EU MDR guidance documents, FDA cGMP inspection observations, SAMR GB standard publications, and METI automation adoption reports. Bottom-up triangulation across individual equipment configurations and top-down validation against regional capital expenditure patterns ensure analytical coherence.
Sensitivity analysis across servo motor cost trajectories, mono-material film availability scenarios, and labor cost arbitrage erosion rates informs projection robustness. Segmentation dimensions modeled include product type architecture, end-use vertical compliance regime, technology automation tier, and packaging material substrate compatibility across the projection horizon. CAGRs derive from installed base replacement cycles, greenfield capacity announcements, and regulatory deadline clustering without specific year anchoring. Industry-specific forecast inputs incorporate REACH chemical registration timeline delays and PLI scheme capital subsidy uptake rates in India.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and barrier-grade film supply concentration; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market