
 Sachet and Pouch Handling Systems Market | 2026-2036
Sachet and Pouch Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sachet and Pouch Handling Systems Market Analytics
Machine vision integration with robotic pick-and-place modules is narrowing the performance gap between dedicated pouch lines and universal handling platforms. Syntegon Technology GmbH leverages its pharmaceutical-grade isolator expertise to anchor high-containment sachet applications. Marchesini Group S.p.A. sustains Italian leadership in cosmetic sample pouch integration with downstream cartoning. Körber AG competes through modular line architectures that accommodate quick format changes across confectionery and nutraceutical batches.
Sachet and pouch handling systems comprise electromechanical equipment designed to orient, fill, seal, and discharge flexible primary packages at speeds ranging from 50 to 1,200 units per minute depending on format complexity and product rheology. These systems employ servo-driven film transport, precision dosing pumps or auger fillers, and thermal or ultrasonic sealing jaws to create hermetic barriers against moisture and oxygen ingress. Vertical Form Fill Seal equipment dominates unit installations due to its compact footprint and suitability for free-flowing granules and powders in food and chemical applications. Automated Packaging lines represent the fastest-expanding segment as pharmaceutical contract manufacturers adopt fully integrated track-and-trace capabilities. Heat Sealing technology maintains the largest installed base, though Ultrasonic Sealing is displacing legacy methods in moisture-sensitive pharmaceutical sachets where seal integrity directly impacts shelf life claims.
The FDA enforces strict validation protocols for pharmaceutical pouch lines under 21 CFR Part 11, compelling equipment vendors to supply documented IQ/OQ/PQ qualification packages. EMA's Annex 1 revisions on sterile manufacturing extend to single-dose sachet filling in EU markets, requiring isolator-based handling systems for ophthalmic and inhalation products. REACH compliance on adhesive and film substrates shapes material selection for European food contact applications. Stakeholders must weigh capital deployment between incremental line upgrades and greenfield automated installations as regulatory divergence between FDA and EMA intensifies qualification burdens.
Market Dynamics
Machine vision-guided robotics is collapsing the traditional trade-off between dedicated high-speed lines and flexible universal platforms, forcing equipment vendors to reengineer architectures around software-defined format changeover rather than mechanical retooling.
Growth Catalysts
- Emerging Asia-Pacific manufacturing clusters:Contract packagers in India and Vietnam scale automated pouch capacity to meet export-grade shelf-ready packaging standards for FMCG multinationals.
- EU Single-Use Plastics Directive:Accelerated migration toward recyclable mono-material films creates pull for sealing technologies compatible with polyethylene and polypropylene barrier structures.
- Pharmaceutical serialization mandates:Track-and-trace requirements under FDA 21 CFR Part 11 and EMA Annex 1 drive replacement of legacy heat-sealing lines with integrated vision-inspection systems.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for 316L pharmaceutical-grade steel and precision motion components compress OEM margins on fixed-price contracts.
- Concentrated film supply:European converters dominate high-barrier mono-material substrate production, creating single-source risk for Asian equipment deployers.
- Ultrasonic transducer technical limitations:Frequency drift in continuous-duty pharmaceutical applications limits seal consistency below 400 units per minute on complex multi-lane formats.
Strategic Opportunities
- Underpenetrated Indonesian pharmaceutical packaging:Domestic vaccine and generic drug manufacturers lack isolator-based sachet capacity for ophthalmic and inhalation products.
- Convergence of AI-driven defect detection with collaborative robotics:Vision-guided cobots enable mid-tier food processors to automate pouch handling without dedicated line engineering.
- EU Green Deal packaging waste targets:Mandatory recycled content thresholds create aftermarket retrofit demand for sealing jaw upgrades on existing VFFS installations.
Industry Challenges
- Mechatronics technician scarcity:Servo programming and vision system calibration skills lag equipment deployment timelines in Southeast Asian manufacturing hubs.
- IQ/OQ/PQ certification timeline compression:Pharmaceutical customers demand simultaneous FDA and EMA qualification packages, stretching vendor documentation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sachet and Pouch Handling Systems Market |
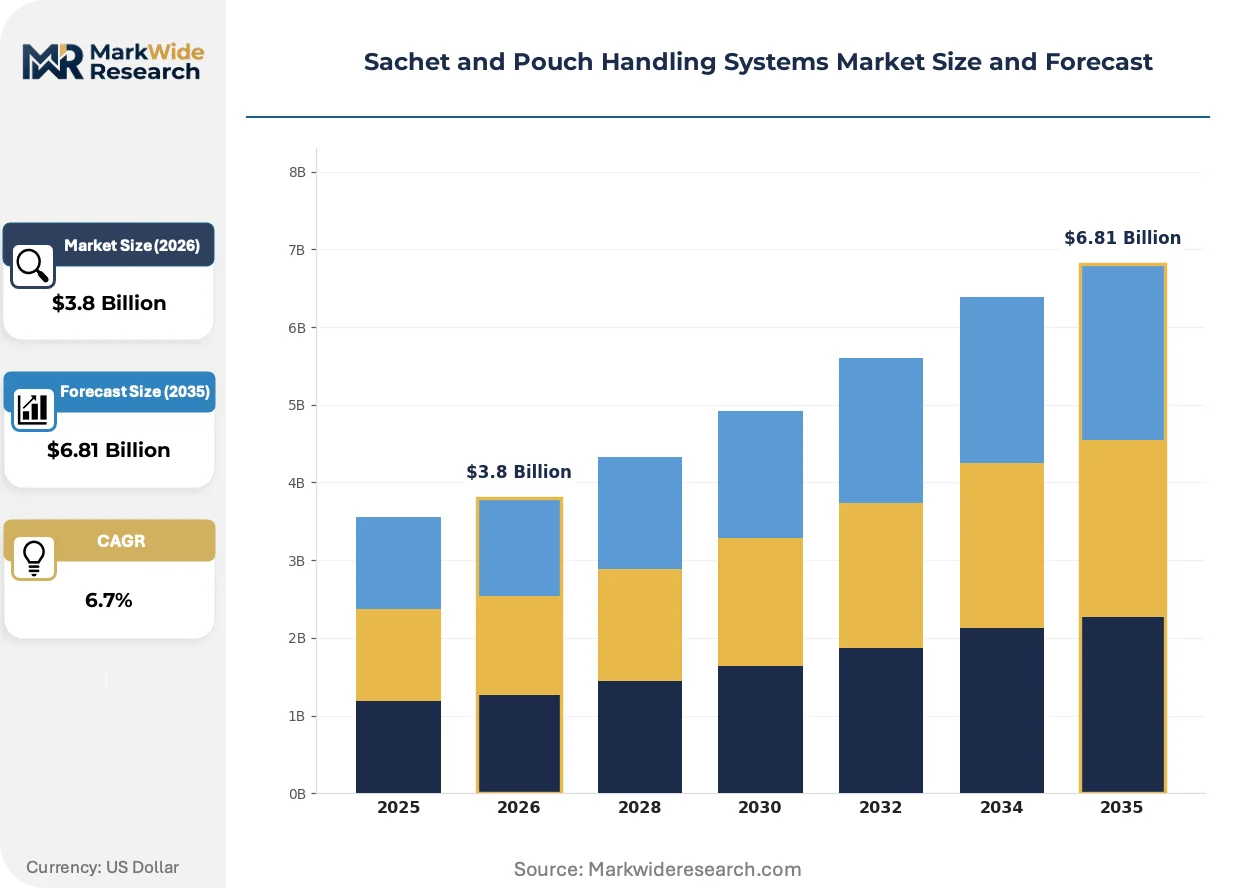
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Form Fill Seal, Horizontal Form Fill Seal, Pneumatic Conveying, Automated Packaging Technology: Heat Sealing, Ultrasonic Sealing, Laser Sealing, Vibration Sealing End User: Food Industry, Pharmaceutical Industry, Cosmetic Industry, Chemical Industry Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | Syntegon Technology GmbH, Marchesini Group S.p.A., Universal Pack S.r.l., Matrix Packaging Machinery, Körber AG, Viking Masek, Nichrome Packaging Solutions, Mespack, HPM Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sachet and Pouch Handling Systems Market Evolving Landscape
Active alignment between regulatory mandates and hardware-software integration is compressing development cycles, with vendors racing to embed compliance documentation directly into machine operating systems rather than treating validation as a post-installation deliverable.
Ultrasonic sealing with titanium horn geometries is collapsing the performance gap between thermal and non-thermal methods in moisture-sensitive pharmaceutical sachets. European contract manufacturers are retrofitting VFFS lines at pace to eliminate heat-induced film distortion. The technology is collapsing legacy equipment replacement cycles from seven years to four in high-value drug packaging.
EMA Annex 1 revisions on sterile manufacturing now explicitly cover single-dose sachet filling, extending isolator requirements previously confined to vial and syringe operations. Pharmaceutical OEMs must revalidate existing lines or replace open-constraint handling systems. German and Italian equipment vendors are responding with pre-qualified isolator modules that compress customer validation timelines.
Buying patterns among multinational FMCG procurement functions are consolidating vendor relationships around full-line responsibility rather than discrete machine purchases. Food manufacturers in Brazil and Mexico now demand integrated film supply, equipment, and aftermarket service under unified contract structures. This bundling shift is visible most acutely in confectionery and nutraceutical verticals where format complexity outpaces in-house engineering capacity.
Sachet and Pouch Handling Systems Market Segmentation
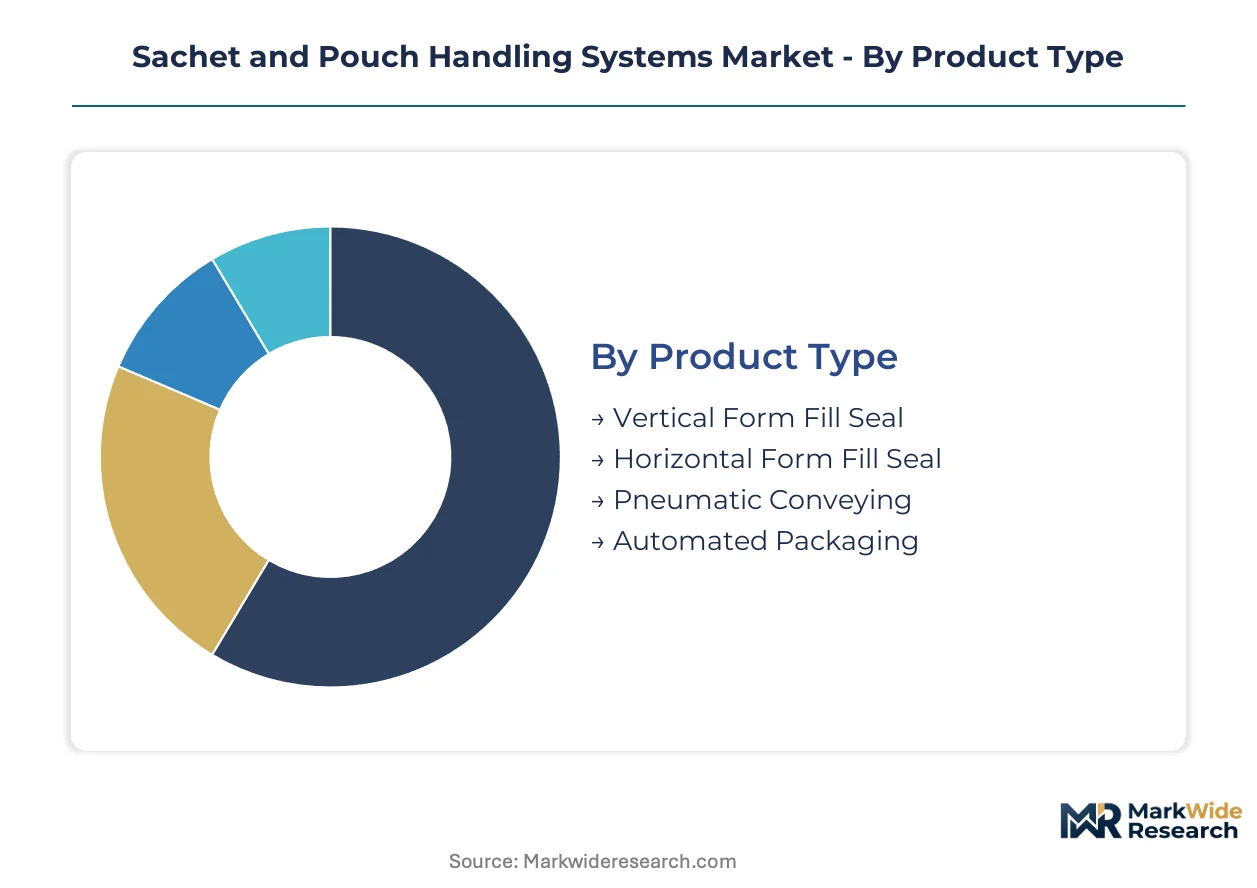
Sachet and pouch handling systems fragment across equipment architecture, sealing physics, throughput tiers, and regulatory exposure. Each dimension carries distinct margin profiles and qualification burdens that shape vendor positioning and customer procurement criteria.
Product Type:
Equipment architecture determines footprint constraints, format flexibility, and integration complexity with upstream dosing and downstream cartoning.
- Vertical Form Fill Seal:Servo-driven film transport pulls flat stock through forming collars to create pillow or gusseted pouches. Indian contract packagers deploy VFFS lines at scale for free-flowing spice powders and instant beverage granules destined for Middle Eastern export markets.
- Automated Packaging:Fully integrated lines combine robotic pick-and-place, vision inspection, and track-and-trace serialization in single-source configurations. Pharmaceutical contract manufacturers in Germany and Italy specify these systems to compress FDA 21 CFR Part 11 and EMA Annex 1 validation timelines.
- Horizontal Form Fill Seal:Flat film webs index through sealing jaws to accommodate pre-made pouches or flow-wrapped products. Cosmetic sample sachets for European duty-free retail channels favor this format for premium graphic presentation.
- Pneumatic Conveying:Vacuum-transfer systems orient and feed empty pouches into filling stations without mechanical grippers. Hygienic design variants serve aseptic dairy applications where contact-part elimination reduces bioburden risk.
Vertical Form Fill Seal holds installed capacity. Automated Packaging is rotating up the share rankings.
Technology:
Sealing method selection hinges on film substrate compatibility, seal integrity requirements, and thermal sensitivity of packaged contents.
- Heat Sealing:Resistive jaw elements apply calibrated temperature and pressure to create hermetic bonds. Legacy polyethylene and polypropylene mono-material films in European food contact applications rely on this mature, cost-minimized approach.
- Ultrasonic Sealing:High-frequency mechanical vibration generates localized molecular friction without bulk heating. Swiss and German pharmaceutical packagers specify titanium horn geometries for moisture-sensitive ophthalmic sachets where seal distortion compromises barrier claims.
- Laser Sealing:Focused infrared energy enables non-contact bonding of complex multi-layer barrier structures. High-value medical device pouches leverage this precision for narrow seal zones that preserve usable package dimensions.
- Vibration Sealing:Oscillatory mechanical energy joins thermoplastic films at lower temperatures than thermal methods. Niche applications in temperature-labile nutraceutical gels favor this emerging approach.
Heat Sealing dominates current installations. Ultrasonic Sealing is climbing the fastest as EMA Annex 1 isolator requirements displace open thermal systems.
End User:
Customer verticals impose divergent validation protocols, cleanliness classifications, and throughput specifications that filter equipment vendor eligibility.
- Food Industry:Shelf-ready packaging mandates from FMCG multinationals drive demand for format-flexible lines. Brazilian and Mexican confectionery processors specify quick-changeover VFFS systems to accommodate seasonal SKU proliferation.
- Pharmaceutical Industry:Single-dose sachets for inhalation and ophthalmic products require isolator-based containment. FDA 21 CFR Part 11 and EMA Annex 1 compliance documentation consumes 30-40% of total project timelines.
- Cosmetic Industry:Sample-size pouches for fragrance and skincare trial formats prioritize premium aesthetics over barrier performance. Italian equipment vendors anchor this segment with integrated downstream cartoning.
- Chemical Industry:Aggressive contents demand corrosion-resistant 316L stainless steel contact surfaces. Agricultural pesticide sachets in Vietnam and Indonesia specify pneumatic conveying to eliminate mechanical wear from abrasive granules.
Food Industry anchors volume demand. Pharmaceutical Industry is gaining share fastest on regulatory-driven replacement cycles.
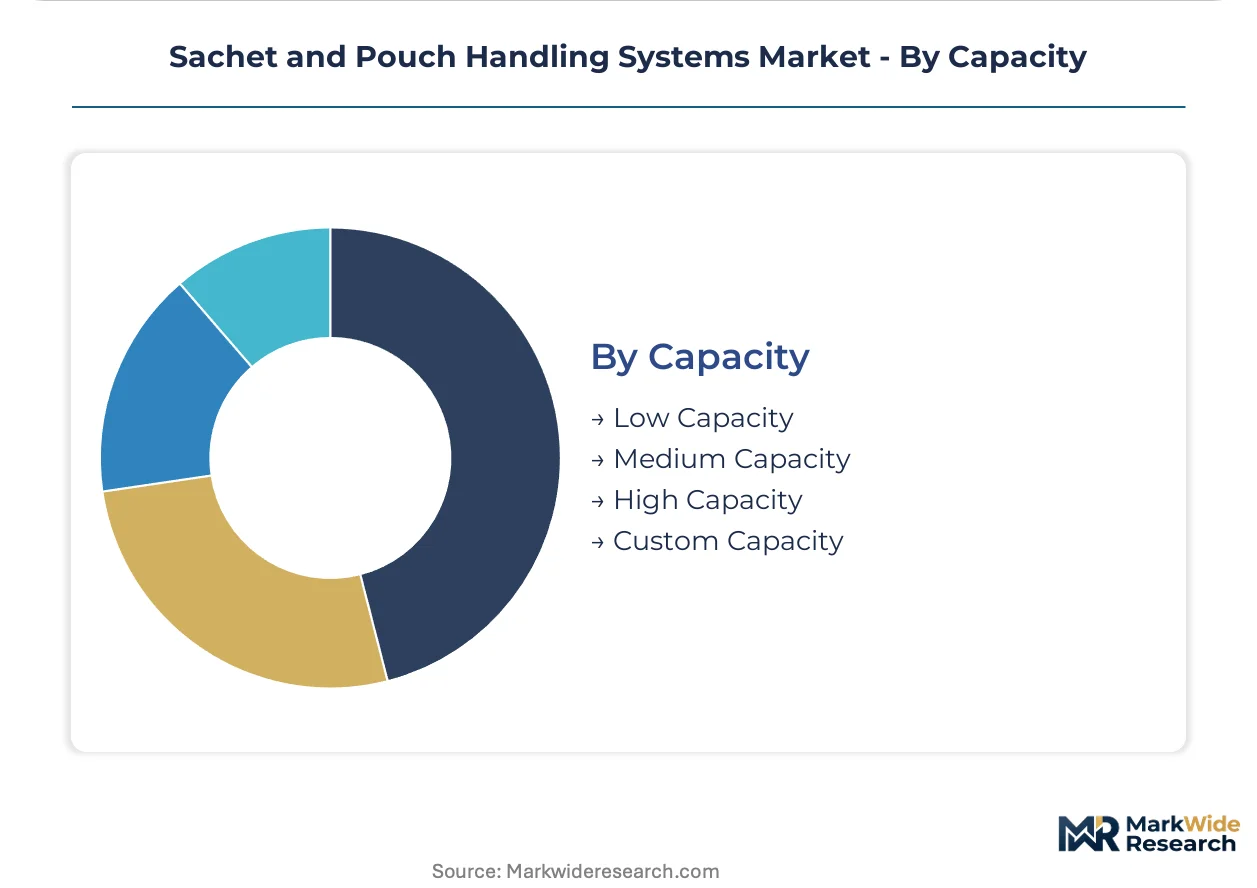
Capacity:
Throughput tier selection reflects batch economics, product value density, and labor cost arbitrage in target manufacturing geographies.
- High Capacity:Multi-lane configurations exceed 800 units per minute on standardized pouch formats. Southeast Asian contract packagers serving pan-Asian FMCG distribution networks deploy these lines to minimize per-unit conversion costs.
- Custom Capacity:Modular architectures accommodate non-standard pouch geometries or intermittent production schedules. European nutraceutical startups specify these systems to preserve capital flexibility amid uncertain demand trajectories.
- Medium Capacity:Single-lane servo systems deliver 200-600 units per minute with mechanical changeover. Mid-tier Indian food processors favor this tier for balanced automation investment.
- Low Capacity:Semi-automatic or tabletop units serve pilot production and regional micro-brands. Indonesian domestic pharmaceutical manufacturers utilize this tier for vaccine sachet development batches.
High Capacity commands the largest installed base. Custom Capacity is rotating up the share rankings as batch-size fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract packagers and pharmaceutical manufacturers concentrate equipment procurement across five national markets where regulatory divergence and export-grade packaging standards create distinct deployment patterns.
Germany
EMA Annex 1 revisions on sterile manufacturing drive isolator-based sachet line replacements among pharmaceutical contract manufacturers. The country's national pharmaceutical regulator enforces documentation timelines that compress vendor qualification windows. Bavaria-based equipment fabricators supply pre-validated isolator modules to domestic packagers serving pan-European distribution networks.
India
FSSAI shelf-ready packaging mandates and CDSCO pharmaceutical serialization rules converge on automated pouch handling investments. The country's national pharmaceutical regulator accelerates track-and-trace compliance timelines for generic drug exporters. Maharashtra and Gujarat manufacturing clusters deploy high-capacity VFFS lines for spice powders and instant beverage granules bound for Middle Eastern markets.
United States
FDA 21 CFR Part 11 validation protocols consume 30-40% of pharmaceutical pouch line project timelines, favoring vendors with embedded compliance documentation. The national pharmaceutical regulator's strict qualification requirements favor integrated automated packaging over discrete machine purchases. Midwestern contract packagers serving FMCG multinationals specify quick-changeover systems to accommodate seasonal SKU proliferation.
Italy
Cosmetic sample pouch integration with downstream cartoning anchors equipment demand from fragrance and skincare trial format producers. REACH compliance on adhesive substrates shapes material selection for European food contact applications. Emilia-Romagna-based vendors sustain leadership in premium aesthetic packaging for duty-free retail channels.
Vietnam
Agricultural pesticide sachet producers specify pneumatic conveying systems to eliminate mechanical wear from abrasive granules. The country's national standards body aligns food contact material regulations with ASEAN harmonization frameworks. Southern manufacturing hubs scale automated capacity to meet export-grade packaging standards for FMCG multinationals.
Sachet and Pouch Handling Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where full-line responsibility bundling displaces discrete machine procurement. German and Italian fabricators anchor the premium tier through pharmaceutical-grade isolator expertise, while Indian and Southeast Asian vendors occupy mid-market positions through cost-optimized VFFS architectures. Two strategic archetypes dominate: validation-integrated specialists serving regulated pharmaceutical verticals, and format-flexible generalists capturing FMCG contract packaging. Competitive moves concentrate on geographic expansion through regional service hubs and technology licensing partnerships that accelerate local compliance documentation.
Among Germany-based GmbH-structured entities, Syntegon Technology GmbH and Körber AG occupy positions within the pharmaceutical-validation archetype, with the former representing isolator-based containment expertise and the latter exemplifying modular line architectures. Italy-based S.p.A. and S.r.l. entities including Marchesini Group S.p.A. and Universal Pack S.r.l. sit within the cosmetic-food integration tier, anchoring premium aesthetic packaging formats. These named companies serve as geographic and structural anchors for understanding competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| Marchesini Group S.p.A. |
| Universal Pack S.r.l. |
| Matrix Packaging Machinery |
| Körber AG |
| Viking Masek |
| Nichrome Packaging Solutions |
| Mespack |
| HPM Global Inc. |
| Others |
Value Network & Pricing Analysis
European converter dominance in high-barrier mono-material substrates concentrates pricing power among film suppliers serving Asian equipment deployers. This upstream concentration funnels margin pools toward sealing technology vendors who can guarantee compatibility with polyethylene and polypropylene barrier structures.
Pricing Analysis
Cost-plus contracts with stainless steel and servo motor indexation dominate pharmaceutical-grade equipment procurement. Three-tier pricing structure across premium isolator-integrated systems, standard VFFS architectures, and economy semi-automatic units reflects certification grade and after-sales bundling intensity. Cost compression in mid-tier Indian and Vietnamese contract packaging is intensifying because fixed-price contracts expose OEMs to input volatility. Food industry buyers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize validation documentation over unit economics.
Supply Chain Analysis
316L pharmaceutical-grade stainless steel feedstock draws from German, Japanese, and South Korean metallurgical suppliers. Precision servo motors and ultrasonic transducers rest on Taiwanese and German component ecosystems. Single-source vulnerability in European high-barrier mono-material film production creates concentration risk for Asian equipment deployers. Distribution runs through regional service hubs anchored by Bavarian and Emilia-Romagna fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
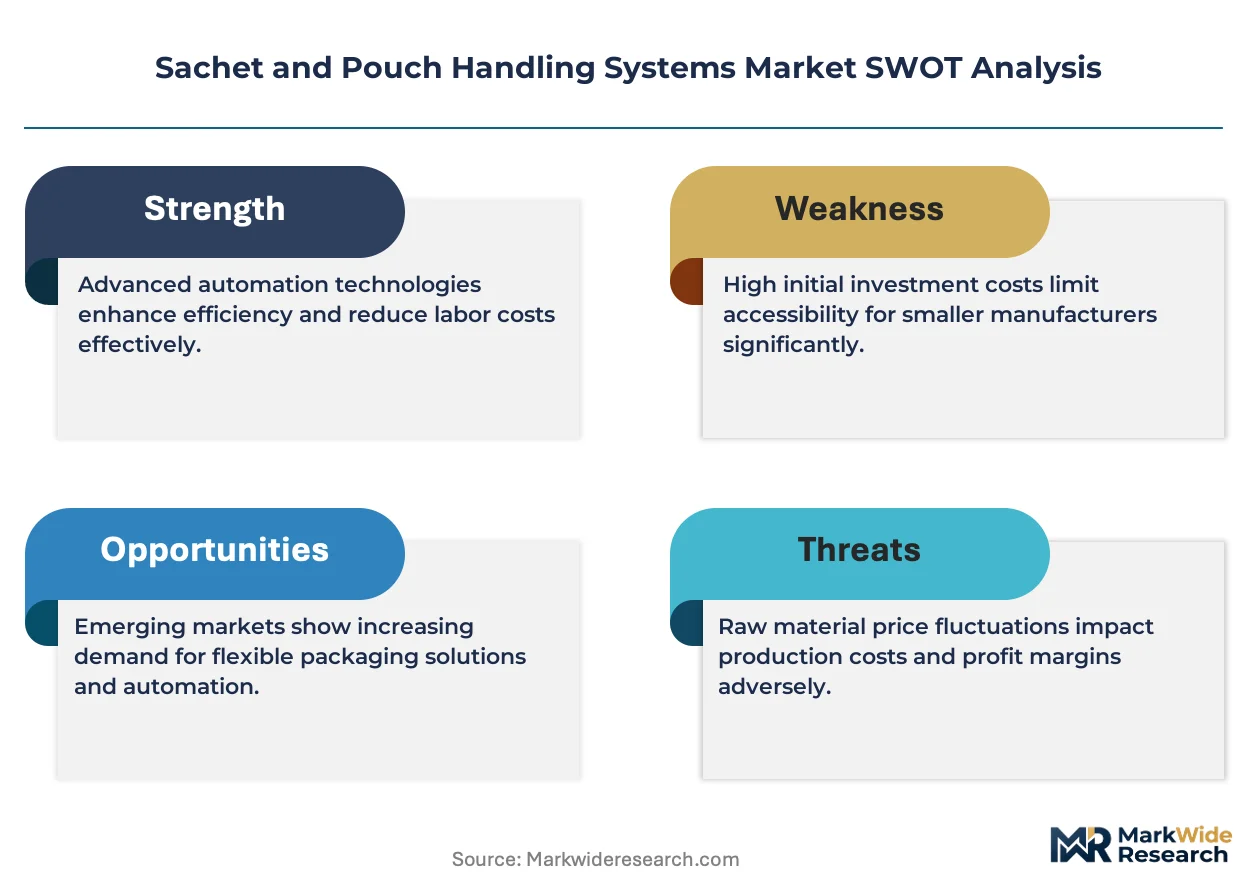
The market rewards vendors who control scarce isolator engineering talent and pre-validated documentation capacity. Mechatronics technician shortages in Southeast Asian manufacturing clusters amplify returns to firms with captive training pipelines.
For Market Incumbents: Insulate pharmaceutical-grade margins by embedding IQ/OQ/PQ documentation directly into machine operating systems rather than treating validation as post-installation deliverables. Deepen backward integration into titanium horn geometries for ultrasonic sealing applications to offset servo motor cost volatility. Acquire regional service capabilities in Maharashtra and Gujarat manufacturing clusters to compress response times for Indian contract packagers. For New Entrants and Emerging Players: Establish a beachhead in Indonesian pharmaceutical packaging by supplying isolator-based sachet capacity for domestic vaccine and generic drug manufacturers lacking ophthalmic and inhalation product handling systems. Target mid-tier Brazilian and Mexican food processors with vision-guided cobot solutions that bypass dedicated line engineering requirements. Lead with AI-driven defect detection integration to differentiate against legacy heat-sealing vendors. For Investors and Strategic Acquirers: Capital is best deployed toward validation-integrated specialists with embedded FDA 21 CFR Part 11 and EMA Annex 1 documentation capabilities rather than format-flexible generalists facing margin compression. Long-term viability hinges on software-defined format changeover architectures that collapse mechanical retooling cycles. Watch ultrasonic transducer frequency stability breakthroughs above 400 units per minute as the inflection signal for pharmaceutical line replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Module Pre-qualification | Compresses EMA Annex 1 validation timelines for German pharmaceutical contract manufacturers. |
| Vision-guided Cobot Integration | Enables mid-tier Indian food processors to automate without dedicated line engineering. |
| Backward Integration into Titanium Horns | Secures supply continuity for Swiss and German moisture-sensitive ophthalmic sachet producers. |
| Regional Service Hub Expansion | Reduces response latency for Vietnamese agricultural pesticide sachet pneumatic conveying systems. |
| Software-defined Format Changeover | Collapsing mechanical retooling cycles differentiates against legacy VFFS vendors in seasonal SKU environments. |
Research Methodology
Desk research of equipment specification databases, regulatory filing repositories, and trade flow records preceded structured interviews with pharmaceutical packaging engineers, contract manufacturing procurement leads, food industry maintenance directors, and OEM aftermarket service heads. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 1 revision drafts, REACH compliance filings, and ASEAN harmonization frameworks. Bottom-up equipment shipment tallies were triangulated against top-down end-use demand estimates.
Assumptions held fixed include EMA Annex 1 isolator requirement enforcement timelines and EU Single-Use Plastics Directive migration schedules, while stainless steel input costs and ultrasonic transducer technical performance thresholds were varied across sensitivity bands. Segmentation dimensions modeled encompass equipment architecture, sealing physics, throughput tier, and regulatory exposure cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity announcements across the projection horizon. Industry-specific inputs included pharmaceutical serialization mandate compliance deadlines and FMCG shelf-ready packaging standard adoption curves.
Stress conditions across servo motor cost volatility, film substrate supply disruption, and mechatronics technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with specific risk factors including regulatory divergence between FDA and EMA qualification protocols and ultrasonic sealing frequency drift in continuous-duty applications. Cross-checking against customs records for 316L stainless steel and precision motion component trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market