
 China Sachet Packaging Market | 2026-2036
China Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Sachet Packaging Market Insights
Single-serve bundling is consolidating buyer preference across China's FMCG channels as brands downsize standard SKUs into trial-friendly configurations. Amcor Plc leverages its laminated film expertise to anchor pharmaceutical sachet supply for domestic generics producers. Huhtamaki Oyj competes through heat-seal technology leadership in liquid dairy and condiment formats. Logos Pack specializes in aluminum barrier sachets for hygroscopic pharmaceutical powders, occupying a defensible niche against multinational incumbents.
China sachet packaging denotes sealed flexible pouches typically ranging from 1 milliliter to 100 milliliters, constructed from multilayer coextruded films or foil laminates via form-fill-seal or pre-made pouch filling processes, designed for portion-controlled dispensing of consumable and chemical products. The food segment dominates volume through instant seasoning and snack applications where laminated film structures balance oxygen barrier against cost. Pharmaceutical sachets command premium positioning as NMPA enforces child-resistant opening standards and aluminum blister-compatible formats. Plastic remains the baseline material for high-throughput cosmetics and shampoo samples, though paper-based alternatives are gaining trial placement in e-commerce subscription boxes.
SAMR enforces GB standards for food contact materials that restrict specific plasticizers and mandate migration testing, directly shaping substrate selection for domestic sachet converters. MEE dual carbon goals are pressuring packaging producers toward thinner film gauges and recyclable mono-material structures, accelerating R&D spend across the supplier base. Stakeholders must monitor how NMPA's evolving pharmaceutical serialization rules intersect with sachet format requirements, as traceability mandates could reshape equipment investment priorities without warning.
Market Dynamics
MEE dual carbon goals are forcing domestic converters toward thinner film gauges and recyclable mono-material structures, compressing legacy multilayer laminate economics while rewarding R&D-heavy suppliers with NMPA-certified pharmaceutical capabilities.
Growth Catalysts
- Urban single-serve consumption:Trial-sized snack and seasoning sachets are displacing bulk formats in Shanghai and Guangzhou convenience channels as younger households prioritize portion control and pantry minimization.
- GB standards enforcement:SAMR-mandated migration testing for food contact materials is filtering out subscale domestic converters, consolidating volume toward certified suppliers with in-house analytical laboratories.
- Pharmaceutical serialization readiness:NMPA's evolving traceability rules for generic drug packaging are pulling investment into sachet lines with integrated coding and aggregation capabilities ahead of formal mandates.
Market Restraints
- Aluminum foil price volatility:Barrier-grade foil inputs for pharmaceutical and hygroscopic powder sachets swing with LME pricing, compressing margin predictability for mid-tier converters without annual supply contracts.
- Coastal production concentration:Over 70% of certified sachet capacity clusters within 200 kilometers of Shanghai and Guangzhou port infrastructure, exposing supply continuity to regional logistics disruptions and labor cost inflation.
- Mono-material performance gaps:Current recyclable polyethylene structures fail to match aluminum-laminate oxygen barriers for oxygen-sensitive pharmaceuticals, limiting immediate substrate substitution in premium segments.
Strategic Opportunities
- Inland e-commerce subscription penetration:Tier-2 and Tier-3 city consumers are adopting trial-size cosmetics and personal care sachets through Douyin and Tmall flagship stores, opening logistics-light distribution models beyond coastal manufacturing clusters.
- Child-resistant opening innovation:NMPA's pending pediatric safety standards for OTC pharmaceuticals create first-mover advantage for converters with patented tear-notch or peel-push mechanisms already validated in European markets.
- Paper-based substrate hybridization:FSC-certified paper-polymer laminates are gaining placement in premium skincare subscription boxes as brands respond to MEE circular economy messaging with demonstrably lower plastic mass per unit.
Industry Challenges
- Multi-layer extrusion technician scarcity:Domestic vocational pipelines produce insufficient operators for seven-layer coextrusion lines, forcing converters to poach talent or absorb 18-month training cycles for green hires.
- Serialization equipment lead times:NMPA-compliant track-and-trace modules for sachet form-fill-seal lines currently carry 26-week delivery schedules from European and Japanese OEMs, compressing upgrade windows for domestic generics producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sachet Packaging Market |
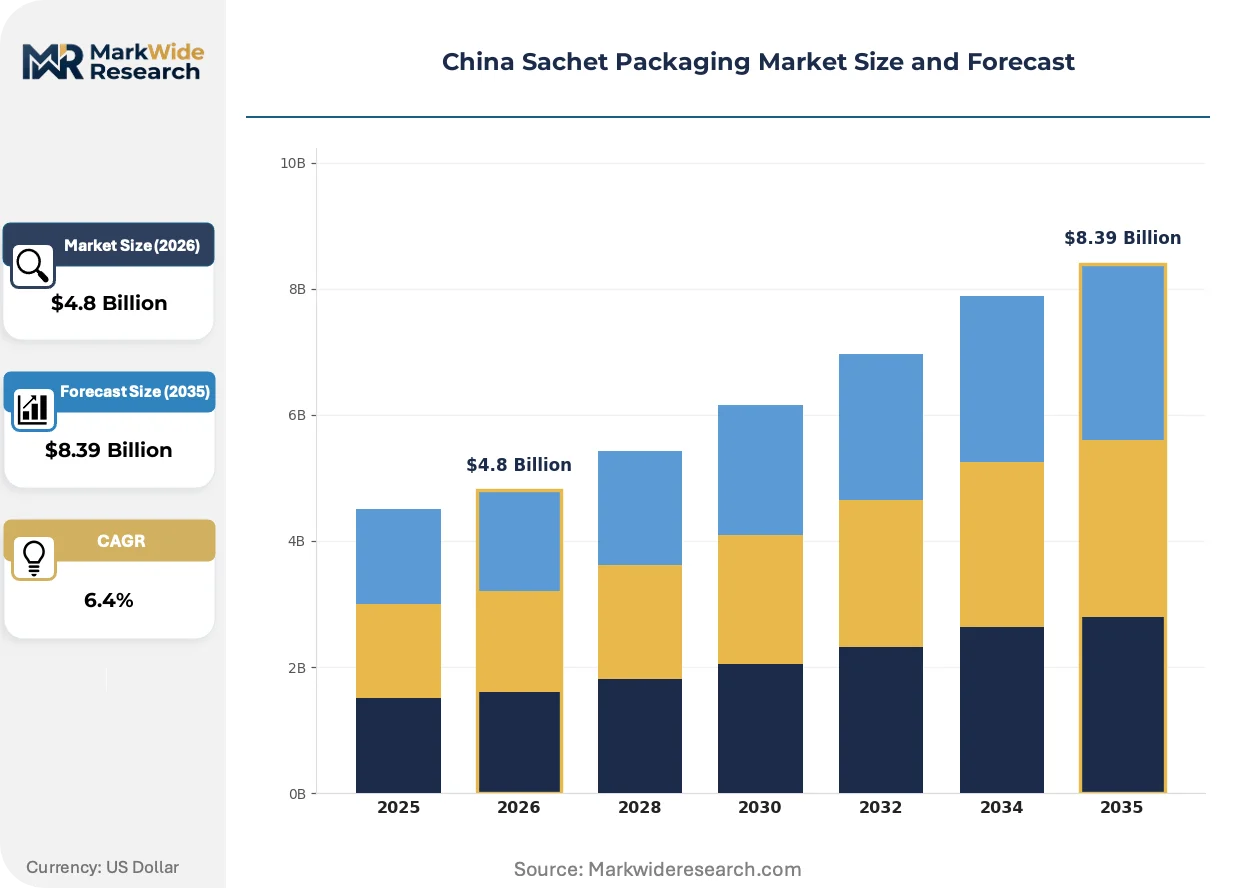
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Personal Care, Pharmaceuticals, Household Chemicals Material: Plastic, Aluminum, Paper, Laminated Film Application: Cosmetics, Liquids, Snacks, Powders End User: Retailers, Wholesalers, Manufacturers, E-commerce |
| Companies Covered | Amcor Plc, Mondi Group, Huhtamaki Oyj, RinPac, Logos Pack, Yantai Bagmart Packaging Co., Ltd, Dongguan Fuliter Paper Products Co., Ltd, Constantia Flexibles, ProAmpac Holdings LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sachet Packaging Market Trends and Innovations
Digital printing and automated quality assurance are compressing batch minimums and accelerating format changeover, enabling economically viable production of region-specific seasonal SKUs and pharmaceutical serial-number variations.
Vision-guided robotic inspection is automating defect detection in high-speed sachet lines, replacing manual sampling protocols that previously tolerated 0.3% leaker rates in liquid dairy applications. Domestic dairy processors in Hebei and Shandong are retrofitting existing form-fill-seal equipment with third-party camera arrays at 40% lower capital intensity than full line replacement. This retrofit pathway is automating quality consistency without displacing incumbent mechanical platform investments.
NMPA's draft technical guidelines for pharmaceutical packaging materials are mandating extractables and leachables documentation for all new sachet submissions, forcing domestic generics producers to rebuild supplier qualification dossiers. The documentation burden falls heaviest on aluminum barrier formats for hygroscopic powders, where historical supplier relationships lacked systematic migration data. Converters with pre-existing US FDA Type III Drug Master Files are leveraging that documentation to accelerate NMPA approval timelines for multinational pharmaceutical clients.
Direct-to-consumer sampling via social commerce is fragmenting order profiles toward sub-10,000 unit batches with 48-hour turnaround requirements. Beauty brands operating Douyin flagship stores are contracting regional converters for campaign-specific sachet designs that rotate monthly, displacing the annual contract manufacturing agreements that previously dominated FMCG procurement. This velocity is most visible in Guangzhou's cosmetics cluster, where dedicated sampling converters now operate 24-hour production cells with digital pre-press workflows eliminating traditional platemaking delays.
China Sachet Packaging Market Segmentation
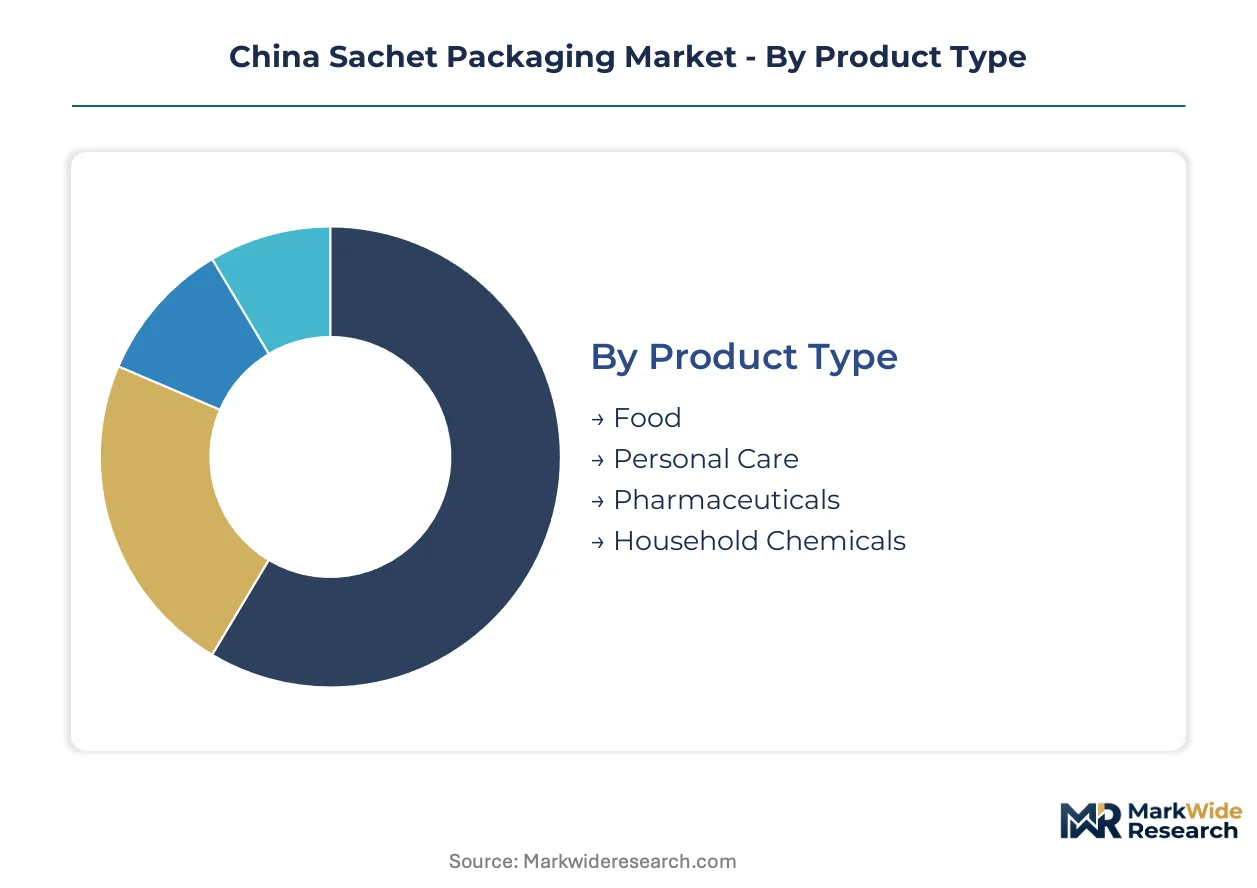
Sachet packaging in China exhibits divergent technical requirements across end-use applications, with pharmaceutical and food segments imposing distinct certification burdens that reshape supplier economics. Understanding these segment boundaries clarifies where NMPA compliance investments yield sustainable margin premiums versus commodity conversion pressure.
Product Type:
Food and pharmaceutical sachets carry the heaviest regulatory documentation loads under SAMR GB standards and NMPA pharmaceutical packaging guidelines respectively, while personal care and household chemicals operate under lighter notification frameworks.
- Food:Laminated film structures dominate instant seasoning and snack applications where oxygen barrier properties balance against unit economics. Demand clusters in Shanghai and Guangzhou convenience channels as younger households downsize pantry inventories toward trial-friendly portions.
- Pharmaceuticals:Aluminum barrier formats for hygroscopic powders require extractables and leachables documentation under NMPA draft technical guidelines. Domestic generics producers are rebuilding supplier qualification dossiers, favoring converters with pre-existing US FDA Type III Drug Master Files.
- Personal Care:Shampoo and skincare sample sachets utilize plastic substrates for high-throughput cosmetics production. E-commerce subscription boxes through Douyin flagship stores are fragmenting order profiles toward sub-10,000 unit batches with rapid turnaround requirements.
- Household Chemicals:Detergent and cleaning product sachets employ cost-optimized multilayer structures. Volume concentrates with coastal manufacturers serving established FMCG distribution networks.
Leading the category by volume: Food. Growing fastest: Pharmaceuticals.
Material:
Substrate selection in China tracks MEE dual carbon enforcement intensity, with recyclable mono-materials gaining share in personal care while aluminum retains pharmaceutical barrier mandates.
- Plastic:Polyethylene and polypropylene structures serve high-throughput personal care and household chemical segments. Thinner film gauges are spreading under MEE pressure, though oxygen barrier limitations constrain pharmaceutical adoption.
- Laminated Film:Multilayer coextruded constructions balance cost and performance across food seasoning applications. Seven-layer coextrusion technician scarcity is forcing 18-month training cycles or talent poaching among domestic converters.
- Aluminum:Barrier-grade foil inputs for hygroscopic pharmaceutical powders swing with LME pricing, compressing margin predictability for mid-tier converters lacking annual supply contracts. NMPA child-resistant opening standards are accelerating format innovation.
- Paper:FSC-certified paper-polymer hybrids are gaining trial placement in premium skincare subscription boxes. MEE circular economy messaging is pulling brand owners toward demonstrably lower plastic mass per unit.
Dominant by installed capacity: Laminated Film. Expanding most quickly: Paper.
Application:
Application-level segmentation reveals divergent automation requirements, with liquid dairy demanding vision-guided robotic inspection while powder pharmaceuticals prioritize barrier integrity over speed.
- Snacks:Single-serve seasoning and nut portions are displacing bulk formats in urban convenience channels. Form-fill-seal lines accommodate high-volume production with moderate barrier specifications.
- Powders:Pharmaceutical and nutritional powder sachets command premium positioning through aluminum-laminate oxygen barriers. NMPA serialization readiness is pulling investment into lines with integrated coding capabilities.
- Liquids:Dairy and condiment sachets in Hebei and Shandong are retrofitting with camera arrays for defect detection. Domestic processors are automating quality consistency at 40% lower capital intensity than full line replacement.
- Cosmetics:Trial-size skincare and fragrance samples rotate monthly through Guangzhou's 24-hour production cells. Digital pre-press workflows are eliminating traditional platemaking delays for campaign-specific designs.
Highest throughput concentration: Snacks. Steepest technology upgrade trajectory: Liquids.
End User:
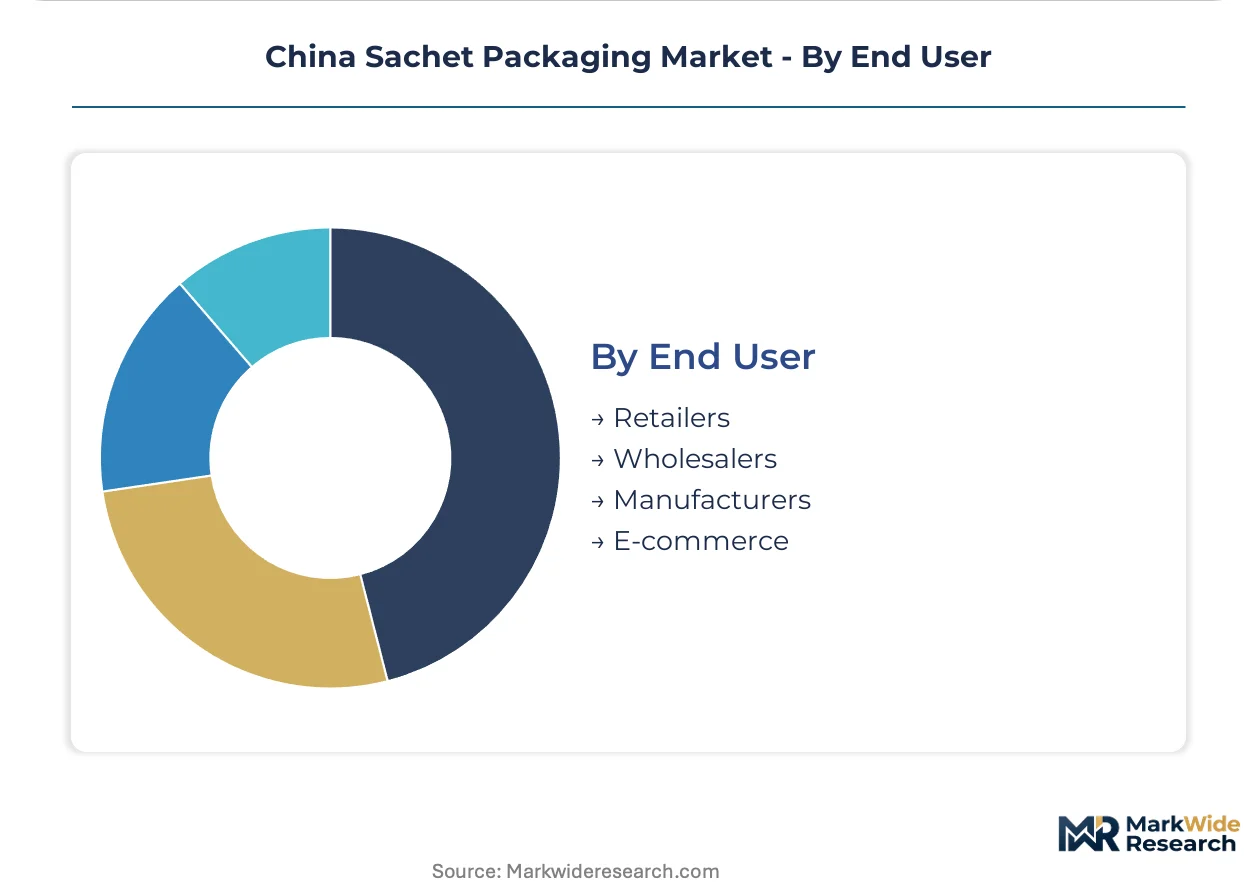
End-user channel structure determines batch size economics and geographic service requirements, with e-commerce fragmentation contrasting manufacturer-scale procurement.
- Manufacturers:Pharmaceutical and food producers dominate volume through annual contract agreements. NMPA-compliant track-and-trace modules carry 26-week delivery schedules from European and Japanese OEMs, compressing upgrade windows.
- E-commerce:Beauty brands operating Douyin and Tmall flagship stores are contracting regional converters for fragmented order profiles. Tier-2 and Tier-3 city penetration is opening logistics-light distribution models beyond coastal clusters.
- Retailers:Convenience chains in Shanghai and Guangzhou are consolidating shelf space toward trial-friendly SKU configurations. Single-serve bundling is displacing bulk formats as younger consumers prioritize pantry minimization.
- Wholesalers:Traditional FMCG distribution networks retain volume in household chemicals and mass-market personal care. Coastal production concentration exposes continuity to regional logistics disruptions.
Commanding largest order scale: Manufacturers. Gaining share fastest: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal manufacturing clusters concentrate over two-thirds of certified sachet capacity, while inland provinces are capturing e-commerce-driven consumption growth through logistics-light distribution models.
Yangtze River Delta
Shanghai anchors pharmaceutical sachet demand as domestic generics producers rebuild supplier dossiers under NMPA draft technical guidelines. SAMR enforces GB standards for food contact materials that restrict plasticizers and mandate migration testing. Zhejiang and Jiangsu converters cluster around port infrastructure, exposing supply continuity to regional logistics disruptions.
Pearl River Delta
Guangzhou's cosmetics cluster operates 24-hour production cells for Douyin flagship store sampling campaigns with monthly design rotations. MEE dual carbon goals press producers toward thinner film gauges and recyclable mono-material structures. Dongguan and Shenzhen house dedicated converters serving fragmented e-commerce order profiles below 10,000 units.
Beijing-Tianjin-Hebei
Hebei dairy processors retrofit form-fill-seal lines with vision-guided robotic inspection at 40% lower capital intensity than full replacement. NMPA serialization readiness pulls investment into integrated coding capabilities ahead of formal mandates. Tianjin's port infrastructure serves northern pharmaceutical distribution networks.
Shandong Peninsula
Qingdao and Yantai converters supply instant seasoning sachets displacing bulk formats in urban convenience channels. Seven-layer coextrusion technician scarcity forces 18-month training cycles or talent poaching among domestic suppliers. Provincial vocational pipelines produce insufficient operators for advanced multilayer lines.
Sichuan-Chongqing
Chengdu and Chongqing capture Tier-2 and Tier-3 city penetration for trial-size personal care sachets through Tmall flagship stores. Inland logistics networks reduce dependency on coastal manufacturing clusters. Western consumption growth outpaces local converter certification capacity.
China Sachet Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification requirements. The vendor base stratifies between multinational laminate technology leaders, domestic pharmaceutical barrier specialists, and regional high-throughput converters. Three archetypes dominate: NMPA-certified pharmaceutical suppliers, heat-seal technology leaders in liquid formats, and aluminum barrier niche players. Competitive moves concentrate on serialization equipment upgrades and mono-material R&D partnerships.
Among multinational packaging conglomerates, Amcor Plc and Mondi Group occupy positions as diversified laminate technology providers with cross-border certification capabilities. Huhtamaki Oyj exemplifies the heat-seal specialization archetype for liquid dairy and condiment applications. Domestic specialists Logos Pack and RinPac represent the pharmaceutical barrier niche, leveraging aluminum-laminate expertise against incumbent competition. Yantai Bagmart Packaging Co., Ltd and Dongguan Fuliter Paper Products Co., Ltd anchor the regional high-throughput tier serving fragmented e-commerce order profiles.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Huhtamaki Oyj |
| RinPac |
| Logos Pack |
| Yantai Bagmart Packaging Co., Ltd |
| Dongguan Fuliter Paper Products Co., Ltd |
| Constantia Flexibles |
| ProAmpac Holdings LLC |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap converters in Zhejiang and Jiangsu provinces anchor supply discipline through generational control over multilayer coextrusion assets, translating coastal production concentration into pricing power against fragmented inland buyers while MEE dual carbon enforcement compresses margin buffers across non-certified competitors.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade aluminum barrier sachets accelerates because LME-linked foil inputs swing unpredictably against annual contract volumes. Three-tier pricing structure across NMPA-certified premium, GB-compliant standard, and non-certified economy levels separates converter tiers by documentation burden. Brand owners in Guangzhou cosmetics clusters show lowest price sensitivity for child-resistant opening innovations, while Hebei dairy processors negotiate aggressively on vision-system retrofit bundles.
Supply Chain Analysis
Domestic-content mandates under MEE circular economy directives are reshaping substrate sourcing toward certified mono-material suppliers with in-house recycling streams. Barrier-grade aluminum foil draws from Australian bauxite and Chinese smelter capacity, while seven-layer coextrusion equipment rests on European and Japanese OEM backlogs. Single-source vulnerability concentrates in serialization module procurement, where 26-week delivery schedules from overseas OEMs compress upgrade windows. Distribution runs through Shanghai and Guangzhou port infrastructure for coastal manufacturing clusters, with inland e-commerce fulfillment bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China sachet packaging market is becoming a vertical-integration race as converters pursue captive supply of NMPA-certified aluminum laminates to defend margin structure against volatile spot-market foil pricing.
For Market Incumbents: Lock in serialization equipment allocation queues with European OEMs before NMPA mandates formalize, while acquiring distressed seven-layer coextrusion technician training pipelines from provincial vocational institutes to preempt talent poaching cycles. Backward integration into aluminum foil slitting operations in Jiangsu insulates margin against LME volatility. For New Entrants and Emerging Players: Tier-2 city e-commerce subscription buyers represent the most penetrable white-space segment, with Douyin flagship store contracts for trial-size cosmetics sachets offering logistics-light entry without coastal manufacturing infrastructure. Partner with FSC-certified paper-polymer laminate specialists to capture MEE circular economy messaging premiums in premium skincare sampling. For Investors and Strategic Acquirers: Distressed-cycle entries favor NMPA-certified pharmaceutical barrier specialists in the Yangtze River Delta with pre-existing US FDA Type III Drug Master Files, as generics producers rebuild supplier dossiers under draft technical guidelines. Watch NMPA pediatric safety standard finalization as inflection indicator for child-resistant opening patent value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil Slitting | Captures margin from LME volatility for Jiangsu-based pharmaceutical converters. |
| Serialization Equipment Pre-Allocation | Secures 26-week OEM delivery slots ahead of NMPA mandate formalization. |
| Seven-Layer Coextrusion Technician Acquisition | Preempts 18-month training cycles through distressed vocational institute partnerships. |
| FSC-Certified Paper-Polymer Hybrid Development | Aligns with MEE circular economy messaging for Guangzhou cosmetics sampling. |
| Child-Resistant Opening Patent Licensing | Captures first-mover premium under pending NMPA pediatric safety standards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of sachet converter operations managers, pharmaceutical packaging procurement leads at domestic generics producers, MEE environmental compliance officers, and Douyin e-commerce fulfillment directors. Bottom-up capacity modeling triangulated against top-down consumption estimates from SAMR food contact material notifications and NMPA pharmaceutical packaging submissions.
Granularity-level framing modeled volume and value across product type, material substrate, application format, and end-user channel dimensions throughout the forecast period. CAGRs derived from trend extrapolation of single-serve consumption velocity, regulatory compliance cost trajectories, and substrate substitution elasticities under MEE dual carbon enforcement.
Revisions become necessary when NMPA serialization mandates accelerate ahead of equipment delivery capacity, or when aluminum foil price volatility exceeds historical bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
US Sachet Packaging Market