
 Asia Pacific Sachet Packaging Market | 2026-2036
Asia Pacific Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sachet Packaging Market Outlook
Indonesian flexible packaging converters is shifting toward high-barrier metallized film capacity to serve instant noodle and coffee sachet demand. UFlex Limited leverages its Noida R&D center to develop proprietary coextrusion recipes for tropical humidity resistance. Amcor plc sustains manufacturing scale across multiple ASEAN sites with standardized equipment platforms. Huhtamaki India Ltd. anchors South Asian supply through its Mumbai and Chennai plants serving FMCG majors.
Asia Pacific sachet packaging denotes single-serve sealed pouches typically constructed from laminated plastic, aluminum foil, or paper substrates with tear-notch functionality, manufactured via horizontal or vertical form-fill-seal processes at widths under 150 millimeters. These structures preserve shelf stability for hygroscopic powders, liquids, and semi-solids in tropical climates where refrigeration penetration remains uneven. Stand-up pouches and flat sachets command the largest volume positions, though biodegradable films represent the fastest-expanding material class as brand owners face Extended Producer Responsibility obligations. Food and Beverages dominates end-user consumption, while Pharmaceuticals offers the deepest margin pools due to serialization and child-resistance compliance requirements.
India's BIS and China's SAMR enforce divergent food-contact migration limits that force converters to maintain separate film inventories and certification documentation. Japan's METI circular economy guidelines and Australia's TGA pharmaceutical packaging rules add further compliance layers for exporters. Indonesia's national standards body and Thailand's FDA implement periodic market surveillance that disqualifies non-compliant imports from shelf placement. Stakeholders must monitor evolving Extended Producer Responsibility frameworks across ASEAN member states to anticipate resin substitution mandates and recycling infrastructure investments.
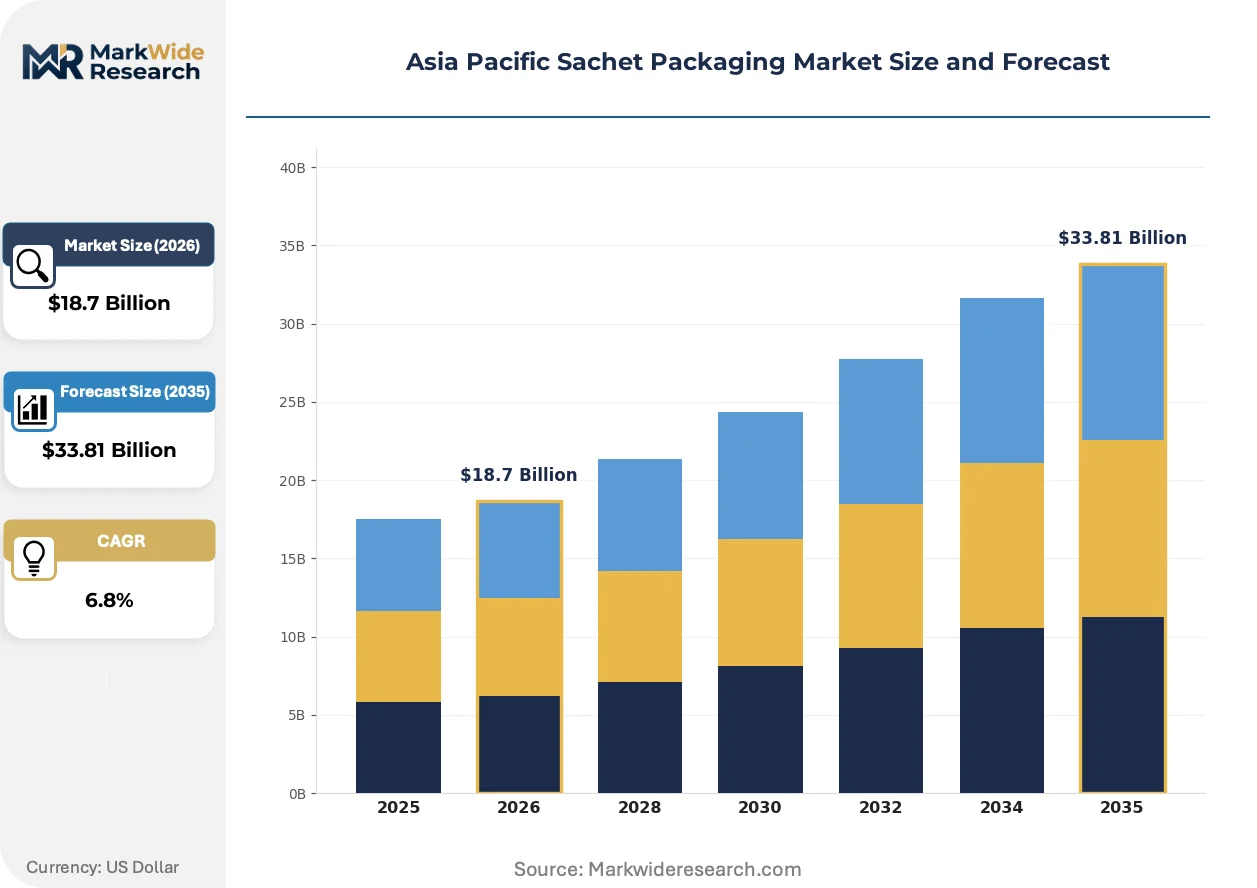
Market Dynamics
Indonesia's instant coffee and seasoning sachet clusters are pulling metallized film capacity toward Southeast Asian palm oil processing zones, restructuring converter location decisions around feedstock proximity rather than labor arbitrage alone.
Growth Catalysts
- China's GB standards migration:Food-contact material rules are forcing multilayer barrier upgrades across Guangdong and Zhejiang converter bases, creating specification premiums for certified structures.
- India's PLI scheme for packaging machinery:Domestic equipment subsidies are reducing import dependence for form-fill-seal lines, accelerating local sachet throughput capacity.
- Indonesia's convenience retail densification:Warung modernization programs and minimart expansion are embedding single-serve formats into daily consumption patterns across Java and Sumatra.
Market Restraints
- Aluminum foil price volatility:Metallized PET substitution remains incomplete for oxygen-sensitive pharmaceuticals, leaving converters exposed to LME aluminum swings.
- Thai FDA import surveillance tightening:Periodic shelf audits are disqualifying non-compliant Malaysian and Vietnamese shipments, fragmenting cross-border supply reliability.
- Biodegradable film performance gaps:PLA and PHA structures still exhibit moisture transmission rates 3-4x above conventional laminates, limiting tropical deployment.
Strategic Opportunities
- Vietnam's underpenetrated pharmaceutical sachet segment:Serialization mandates for OTC liquid doses remain unevenly enforced, creating first-mover windows for compliant barrier suppliers.
- Australia's TGA child-resistance rules:Push-through sachet demand for analgesics is expanding specification complexity that Asian converters can capture with targeted R&D.
- Digital printing convergence with short-run flexo:SKU proliferation in premium seasonings is enabling variable-data sachet production without plate changeover costs.
Industry Challenges
- Multilayer coextrusion technician scarcity:Vietnam and Philippines converter bases lack depth in blown film die adjustment expertise for barrier layer uniformity.
- BIS certification timeline compression:India's laboratory testing queues for food-contact migration studies now extend 14-18 weeks, delaying export readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sachet Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Sachets, Gusseted Sachets, Tear Notches Material: Plastic, Aluminum Foil, Paper, Biodegradable Films End User: Food & Beverages, Personal Care, Pharmaceuticals, Household Goods Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Constantia Flexibles, UFlex Limited, Amcor plc, Scientex Berhad, Huhtamaki India Ltd., Huhtamaki, SCG Packaging, TOPPAN Inc., Mondi, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sachet Packaging Market Strategic Shifts
Material science advances and regulatory serialization mandates are compressing product development cycles while expanding the addressable application set for high-barrier sachet structures.
Metallized polyethylene terephthalate film with enhanced aluminum deposition density is overtaking conventional foil laminates in instant noodle seasoning applications. Indonesian and Thai brand owners are specifying these structures for 12-month shelf life guarantees in uncontrolled humidity retail environments. The shift is compressing converter margins on legacy foil-based workflows while rewarding capital investment in vacuum metallization capacity.
Japan's METI circular economy guidelines are mandating mono-material compatibility for household packaging by 2030, forcing multilayer sachet designers toward polyethylene or polypropylene-only barrier solutions. Converter R&D centers in Osaka and Nagoya are accelerating metallized mono-PE development to preserve oxygen transmission performance without aluminum foil. Pharmaceutical exporters to Japan now face dual compliance burdens against both PMDA stability requirements and METI recyclability targets.
Direct-store-delivery networks for ambient beverages are displacing traditional distributor warehousing in Philippines and Indonesia sachet supply chains. Brand owners are negotiating shorter production runs with converters to match warung-level demand signals rather than regional stockpile forecasts. This pattern is most visible in Java's instant coffee sachet replenishment, where weekly SKU mix changes now outpace monthly planning horizons.
Asia Pacific Sachet Packaging Market Segmentation
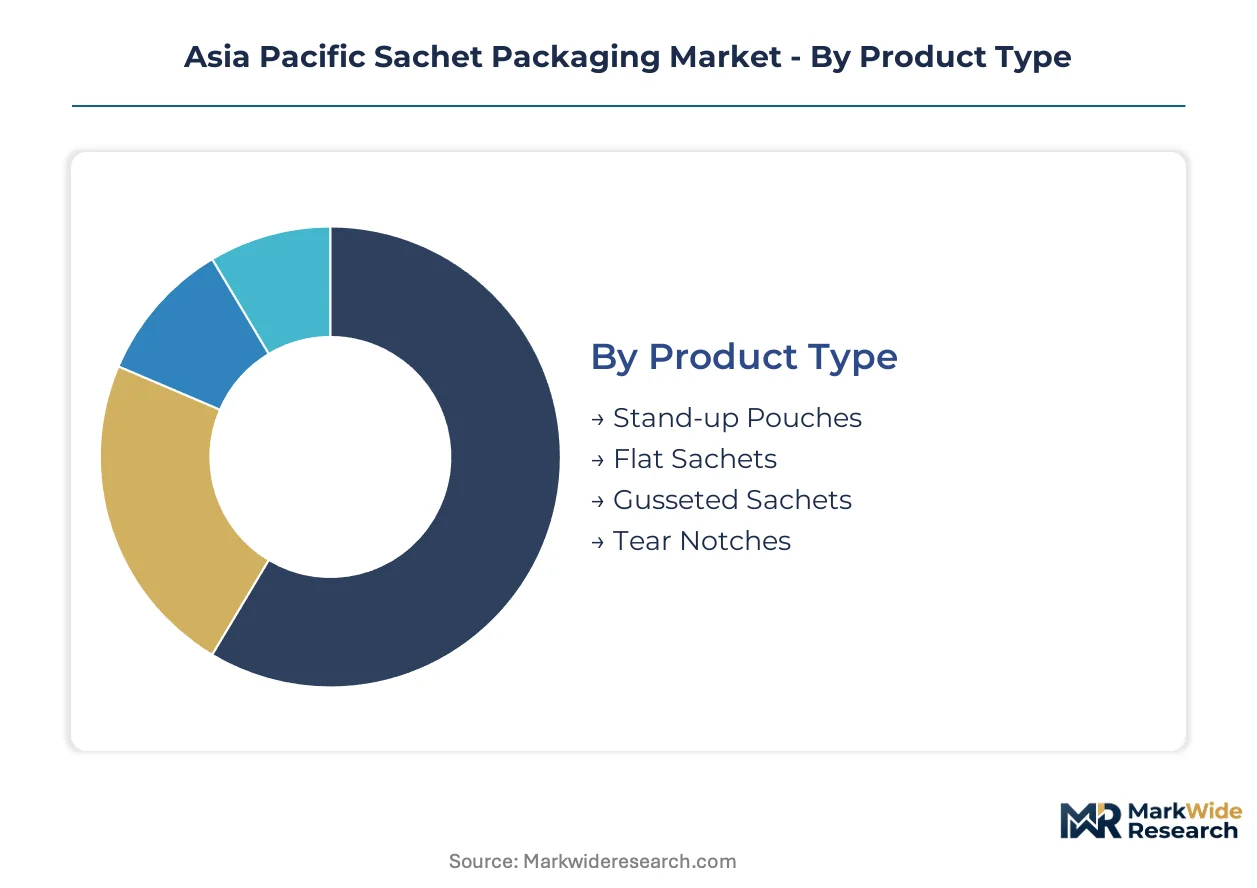
Asia Pacific sachet packaging segments diverge sharply on regulatory burden and margin structure. Pharmaceutical and food-contact applications demand divergent certification pathways across BIS, SAMR, and ASEAN national standards bodies.
Product Type:
Certification requirements cluster around barrier performance specifications that vary by pouch geometry. Stand-up pouches for beverages face India's BIS migration testing, while flat sachets for pharmaceuticals trigger China's GB food-contact material rules.
- Stand-up Pouches:Laminated structures with bottom gusset enable liquid containment for ambient beverages. Indonesian warung networks and Philippine direct-store-delivery channels concentrate demand for 80-120ml formats with spout or tear-notch closure.
- Flat Sachets:Two or three-side seal configurations dominate instant coffee and seasoning applications. Thai and Vietnamese converters optimize horizontal form-fill-seal lines for 5-20g powder doses at widths under 100 millimeters.
- Gusseted Sachets:Side-fold geometries expand volume capacity without width increases. Japanese pharmaceutical exporters specify these for tablet counting compliance under PMDA stability guidelines.
- Tear Notches:Laser-scored or mechanical perforations enable consumer opening without tools. Australian TGA child-resistance rules mandate dual-opening mechanisms for analgesic sachets.
Leading the category by volume: Flat Sachets. Expanding most quickly: Stand-up Pouches.
Material:
Raw material selection determines converter capital allocation and inventory segmentation across tropical humidity zones.
- Plastic:Multilayer coextrusions of polyethylene, polypropylene, and ethylene vinyl alcohol dominate cost-sensitive food applications. Indonesian palm oil processing zones pull blown film capacity toward Java and Sumatra.
- Aluminum Foil:Seven to nine-micron gauges provide absolute oxygen and moisture barriers for pharmaceutical stability. Price volatility on London Metal Exchange forces converters toward metallized PET substitution where specification allows.
- Paper:Grease-resistant kraft laminates serve dry seasoning and confectionery segments with premium tactile positioning. Japanese METI circular economy guidelines favor paper-plastic separable structures for 2030 recyclability targets.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate structures face moisture transmission rate limitations in uncontrolled ASEAN retail environments. Thailand's FDA surveillance protocols currently exclude most biodegradable formats from pharmaceutical shelf placement.
Widest deployment: Plastic. Steepest specification upgrade trajectory: Aluminum Foil.
End User:
Margin pools diverge threefold between commodity food sachets and serialized pharmaceutical formats.
- Food & Beverages:Instant noodle seasoning and coffee powder sachets drive metallized film consumption across Indonesian and Malaysian converter bases. Warung modernization programs embed single-serve formats into daily consumption patterns.
- Personal Care:Shampoo and conditioner sachets concentrate in Philippine and Vietnamese rural distribution networks. SKU proliferation demands digital printing compatibility for short-run production.
- Pharmaceuticals:OTC liquid doses and tablet sachets command specification premiums for serialization and child-resistance compliance. Vietnam's uneven enforcement of track-and-trace mandates creates first-mover windows for compliant barrier suppliers.
- Household Goods:Detergent and fabric softener sachets compete on unit economics with refill pouch formats. India's PLI scheme for packaging machinery reduces form-fill-seal line costs for domestic converters serving this segment.
Deepest margin pool: Pharmaceuticals. Largest volume position: Food & Beverages.
Distribution Channel:
Channel selection determines production run length and converter flexibility requirements.
- Online Retail:E-commerce penetration in urban India and Southeast Asia demands damage-resistant outer packaging for sachet multipacks. Last-mile logistics favor consolidated carton configurations over loose sachet bulk.
- Supermarkets:Modern trade shelf placement requires BIS or GB certification documentation for food-contact materials. Indonesian hypermarket chains specify 12-month shelf life guarantees through high-barrier metallized structures.
- Convenience Stores:Minimart and warung networks in Java and Sumatra pull weekly replenishment cycles with variable SKU mix. Direct-store-delivery models displace traditional distributor warehousing.
- Wholesale:Bulk sachet packs for institutional catering and rural stockists prioritize unit cost over barrier sophistication. Malaysian and Vietnamese cross-border shipments face Thai FDA periodic shelf audit disqualification risks.
Highest throughput concentration: Convenience Stores. Fastest channel shift: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palm oil processing zones in Indonesia and Malaysia anchor raw material supply chains for metallized film converters serving Southeast Asian sachet demand. Tropical humidity resistance specifications drive R&D investments across converter bases in India and China.
Indonesia
Instant coffee and seasoning sachet clusters concentrate converter capacity near Java and Sumatra palm oil zones. The country's national standards body implements periodic market surveillance that disqualifies non-compliant imports from shelf placement. Warung modernization programs and minimart expansion embed single-serve formats into daily consumption patterns across Indonesian convenience retail channels.
India
BIS packaging standards enforce tightening compliance requirements for multilayer barrier structures in food-contact applications. The PLI scheme for packaging machinery reduces import dependence for form-fill-seal lines, accelerating local sachet throughput capacity. Mumbai and Chennai plants anchor South Asian supply chains serving FMCG majors with standardized equipment platforms.
China
GB standards for food-contact materials force multilayer barrier upgrades across Guangdong and Zhejiang converter bases. SAMR migration limits create specification premiums for certified structures in food and beverage applications. Pearl River Delta manufacturing sites sustain production scale for export-oriented sachet formats bound for ASEAN markets.
Thailand
Thai FDA import surveillance tightening fragments cross-border supply reliability for Malaysian and Vietnamese shipments. Pharmaceutical sachet demand for OTC liquid doses concentrates in Bangkok-area converter clusters. Horizontal form-fill-seal line optimization for 5-20g powder doses dominates Thai technical specialization in flat sachet geometries.
Vietnam
Underpenetrated pharmaceutical sachet segments offer first-mover windows for compliant barrier suppliers as serialization mandates remain unevenly enforced. Blown film die adjustment expertise scarcity constrains barrier layer uniformity in Vietnamese converter bases. Cross-border shipments face disqualification risks from Thai FDA periodic shelf audits.
Asia Pacific Sachet Packaging Market Competitive Environment
Global majors compete with regional champions across certification documentation and tropical humidity specification capabilities. The vendor base stratifies around metallized film capacity investments, with vacuum metallization equipment distinguishing premium-tier positioning from commodity foil-laminate workflows. Two strategic archetypes dominate: integrated multinational suppliers with standardized ASEAN manufacturing footprints, and domestic champions leveraging government equipment subsidies to capture local throughput growth. Competitive moves concentrate on backward integration into coextrusion resin compounding and geographic co-location near palm oil processing zones.
Among India-based converters, UFlex Limited and Huhtamaki India Ltd. exemplify the domestic champion archetype leveraging R&D center proximity to tropical humidity specification demand. Amcor plc represents the integrated multinational model with manufacturing scale sustained across multiple ASEAN sites. These three companies anchor the competitive structure through divergent strategic positioning around certification depth versus geographic reach.
| Leading Market Players |
|---|
| Constantia Flexibles |
| UFlex Limited |
| Amcor plc |
| Scientex Berhad |
| Huhtamaki India Ltd. |
| Huhtamaki |
| SCG Packaging |
| TOPPAN Inc. |
| Mondi |
| Others |
Value Chain & Pricing Dynamics
Vacuum metallization equipment adoption across Indonesian and Thai converter bases is simultaneously compressing legacy foil-laminate margins and concentrating supply ownership among capital-intensive operators. This technology transition rewards backward integration into coextrusion resin compounding while penalizing smaller converters dependent on spot aluminum foil purchases.
Pricing Analysis
Warranty and certification bundling separates premium-tier metallized film suppliers from unbundled commodity converters. Three-tier pricing structure across premium, standard, and economy levels reflects BIS and GB certification depth, with pharmaceutical-grade barriers commanding multiples over food-contact specifications. Cost compression in economy tiers is intensifying because Indonesian palm oil zone co-location advantages favor integrated players. Brand owners in Java's instant coffee segment exhibit highest price sensitivity, while Australian TGA-compliant pharmaceutical exporters show least.
Supply Chain Analysis
Direct-to-warung channels handle fragmented replenishment demand across Java and Sumatra minimart networks. Raw material supply concentrates in Indonesia, Malaysia, and China, with blown film resin and vacuum metallization equipment anchoring converter location decisions. The chain draws from palm oil processing zones for coextrusion feedstock and aluminum smelter corridors for barrier metallization. Single-source vulnerability in seven-micron foil gauges exposes converters to London Metal Exchange volatility. Distribution runs through direct-store-delivery networks displacing traditional distributor warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where BIS certification timeline compression and capital-intensive metallization requirements force sub-scale converters toward exit or acquisition.
For Market Incumbents: Hedge aluminum foil exposure through metallized PET substitution programs while securing captive resin compounding capacity in Indonesian palm oil zones. Defensive moves center on locking 12-month shelf life guarantee contracts with instant noodle brand owners and pre-empting Thai FDA surveillance disqualification through advance certification documentation. Vacuum metallization equipment ownership serves as the critical lever against commodity foil-laminate competitors. For New Entrants and Emerging Players: E-commerce platform routes for sachet multipack distribution offer lowest barrier entry into urban India and Southeast Asia. White-space targets concentrate in Vietnam's underpenetrated pharmaceutical serialization segment and Australia's TGA child-resistance sachet formats. Go-to-market execution should prioritize digital printing compatibility for premium seasoning SKU proliferation without plate changeover economics. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated multinational packaging groups seeking ASEAN metallization capacity. Long-term viability favors converters with backward integration into coextrusion resin and demonstrated tropical humidity specification capabilities. Acquisition target archetype: domestic champions with BIS certification depth and Java-based manufacturing footprints. The inflection signal to monitor is Indonesia's national standards body enforcement intensity against non-compliant imports.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Metallization Capacity Expansion | Captures 12-month shelf life specification premiums from Indonesian instant coffee brand owners. |
| Backward Integration into Resin Compounding | Secures tropical humidity resistance formulations proprietary to converter R&D centers. |
| BIS/GB Certification Investment | Unlocks modern trade shelf placement in Indian hypermarkets and Chinese supermarkets. |
| Direct-Store-Delivery Network Partnership | Aligns production runs with warung-level demand signals rather than regional stockpile forecasts. |
| Digital Printing Platform Deployment | Enables variable-data sachet production for premium seasoning SKU proliferation. |
Study Parameters
Document review covered BIS migration testing protocols, GB food-contact material standards, and ASEAN national surveillance guidelines, complemented by interviews with converter plant managers, FMCG procurement leads at Indonesian instant coffee brand owners, flexible packaging R&D directors, and warung network distribution heads. Secondary validation drew from customs trade data, SAMR regulatory filings, and METI circular economy guideline documents. Bottom-up capacity assessments across Guangdong, Zhejiang, Java, and Sumatra converter bases were triangulated against top-down demand estimates from end-use consumption patterns.
Cross-referencing historical capacity installation rates against expert panel inputs on metallization equipment lead times shaped the analytical framework. Segmentation dimensions modeled include pouch geometry, barrier material class, end-use industry, and certification tier across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit specification premiums. Industry-specific inputs incorporated aluminum foil price volatility assumptions and PLI scheme equipment subsidy uptake rates.
The model holds under stable BIS and GB enforcement intensity; deviation in Thai FDA surveillance tightening or Indonesian EPR mandate acceleration would shift converter margin trajectories. Forecasts reflect assumptions regarding metallized PET substitution rates and warung modernization program pacing. Periodic stress-testing of base assumptions against regulatory announcement calendars and LME aluminum futures curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market