
 India Plastic Packaging Market | 2026-2036
India Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Plastic Packaging Market Foresight
Flexible pouch configurations are shifting how FMCG buyers evaluate total cost of ownership versus shelf presence. Uflex Limited leverages its integrated film-to-pouch manufacturing footprint to capture conversion efficiencies across the value chain. Huhtamaki India Limited anchors its position through specialized food-service and retail-ready packaging lines. Essel Propack Limited dominates tube-based dispensing formats for oral care and cosmetics, competing on decoration and barrier precision.
India plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to contain, protect, and present goods across supply chains; specifications include oxygen transmission rates below 0.1 cc/m²/day for retort pouches and seal strengths exceeding 3 N/15mm for aseptic applications. Flexible packaging leads volume due to its material efficiency and logistics advantages in a cost-sensitive economy, while rigid containers command premium placement in pharmaceutical and personal care segments where dimensional stability and child-resistance matter. PET material grades are displacing PVC in beverage and edible-oil applications as recyclability protocols tighten.
BIS mandates food-contact compliance under IS 9845, while FSSAI governs migration limits and safety declarations for plastic materials touching consumables. The Plastic Waste Management Rules, enforced by the Central Pollution Control Board, impose extended producer responsibility obligations that reshape material choices and collection infrastructure investments. SEBI's BRSR disclosure requirements push listed packaging firms to document plastic intensity and recycling targets. Stakeholders must track how state-level single-use bans and emerging chemical recycling certifications will alter sourcing strategies and capital allocation across the forecast window.
Market Dynamics
Extended producer responsibility mandates under the Plastic Waste Management Rules are restructuring capital allocation across India's polymer conversion clusters, forcing processors to integrate collection infrastructure or forfeit access to FMCG procurement pipelines.
Growth Catalysts
- Multilayer flexible pouch adoption:Food and beverage processors are expanding shelf-stable dairy and ready-to-eat meal formats, driving specification upgrades for oxygen barrier performance and seal integrity.
- BIS certification alignment:IS 9845 compliance for food-contact materials is filtering supplier bases, advantaging domestic converters with in-house testing laboratories over import-dependent competitors.
- rPET integration mandates:Brand-owner sustainability commitments are accelerating recycled polyethylene terephthalate qualification programs, creating pull-through demand for post-consumer collection and reprocessing capacity.
Market Restraints
- Feedstock price volatility:Crude-linked polymer resin costs expose converters to margin compression when pass-through clauses lag spot market movements by 60-90 days.
- Western India supply concentration:Maharashtra and Gujarat polymer clusters concentrate 60% of conversion capacity, creating logistics vulnerability for eastern and southern markets.
- Mechanical recycling contamination limits:Multilayer laminate structures defeat standard reprocessing streams, constraining circular economy claims until chemical recycling scales.
Strategic Opportunities
- Peninsular India penetration:Tamil Nadu and Karnataka processed food corridors remain underserved by qualified flexible packaging suppliers, offering first-mover positioning for BIS-certified entrants.
- Pharmaceutical barrier formats:Tropical climate stability requirements for oral solid dosage packaging are expanding demand for high-barrier blister films and desiccant-integrated structures.
- SEBI BRSR disclosure acceleration:Listed packaging firms must document plastic intensity and recycling targets, creating advisory and certification service revenue streams for compliance specialists.
Industry Challenges
- Migration testing capacity bottleneck:FSSAI-mandated specific migration limit verification faces laboratory queue times exceeding 8-12 weeks, delaying new product approvals.
- Multilayer equipment reconfiguration:Retrofitting extrusion lines for recyclable mono-material structures demands capital outlays that stretch mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plastic Packaging Market |
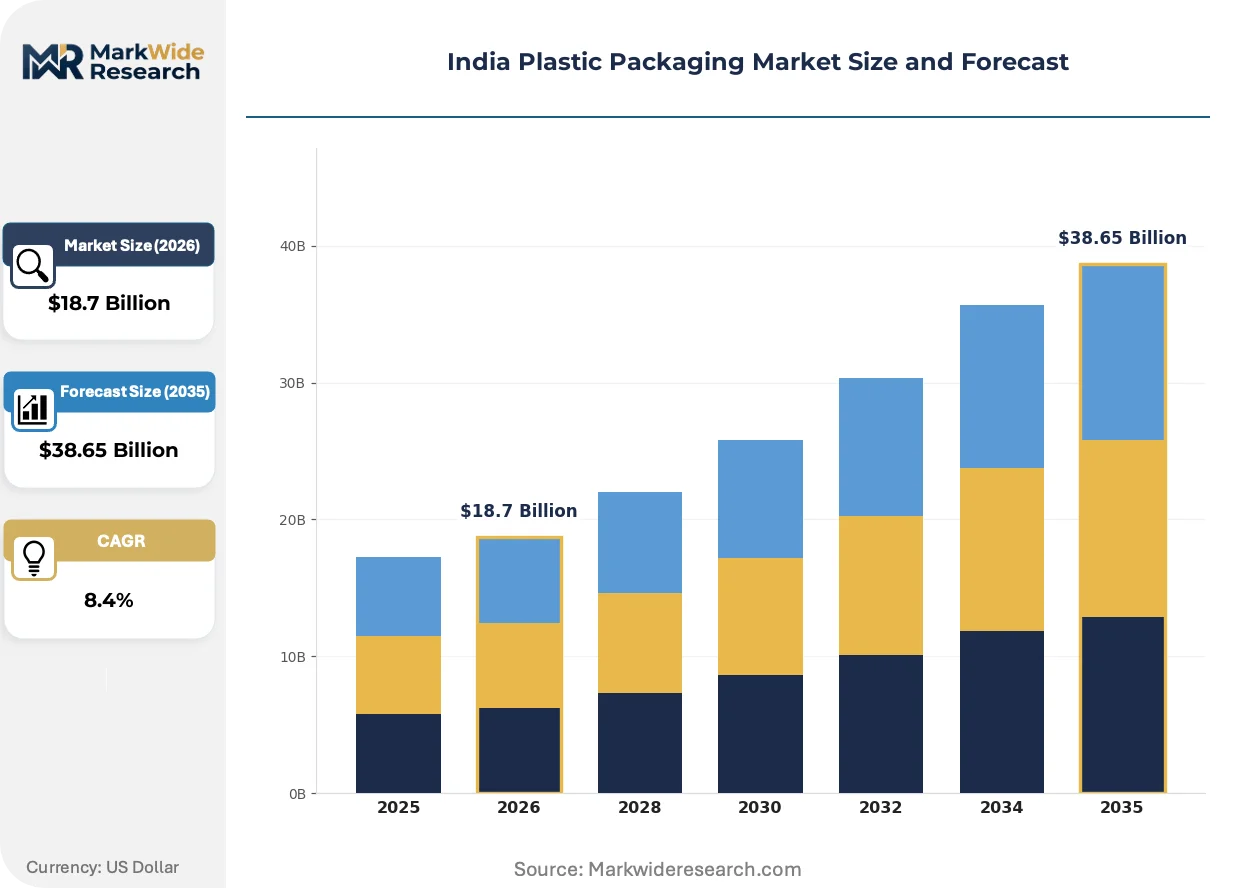
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Rigid Containers, Pouches End User: Food & Beverage, Healthcare, Personal Care, Household Products Material: LDPE, HDPE, PET, PVC Application: Agricultural, Retail, Industrial, Consumer |
| Companies Covered | Essel Propack Limited, Cosmo Films Ltd, Amcor PLC, Sealed Air Corporation, Huhtamaki India Limited, Uflex Limited, Polyplex Corporation Limited, Mold-Tek Packaging Limited, Jindal Poly Films Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plastic Packaging Market Shifts & Advancements
Digital printing and barrier coating technologies are collapsing minimum order quantities while extending shelf-life performance, enabling regional brand owners to compete with national players on packaging sophistication without inventory risk.
Water-based barrier coatings are converging with high-speed gravure printing to replace solvent-based laminations in snack food applications. Mid-tier FMCG brands in Gujarat and Maharashtra are piloting these structures for 6-12 month shelf-life products. The technology is converging with existing converting assets, preserving capital efficiency while meeting FSSAI migration compliance.
FSSAI's tightened specific migration limits for heavy metals and primary aromatic amines are disqualifying legacy import supply chains from Southeast Asia. Domestic converters with captive laboratory infrastructure are capturing specification revisions from multinational food processors. Pharmaceutical and edible oil segments face the steepest reformulation timelines, with some applications requiring 18-month stability revalidation.
Brand-owner sustainability scorecards now weight post-consumer recycled content above price in annual vendor reviews. Large FMCG procurement teams in Mumbai and Delhi are consolidating supplier panels to favor converters with documented EPR collection partnerships. This recalibration is most visible in personal care and home care segments, where shelf aesthetics permit greater material experimentation than food-contact applications.
India Plastic Packaging Market Segmentation
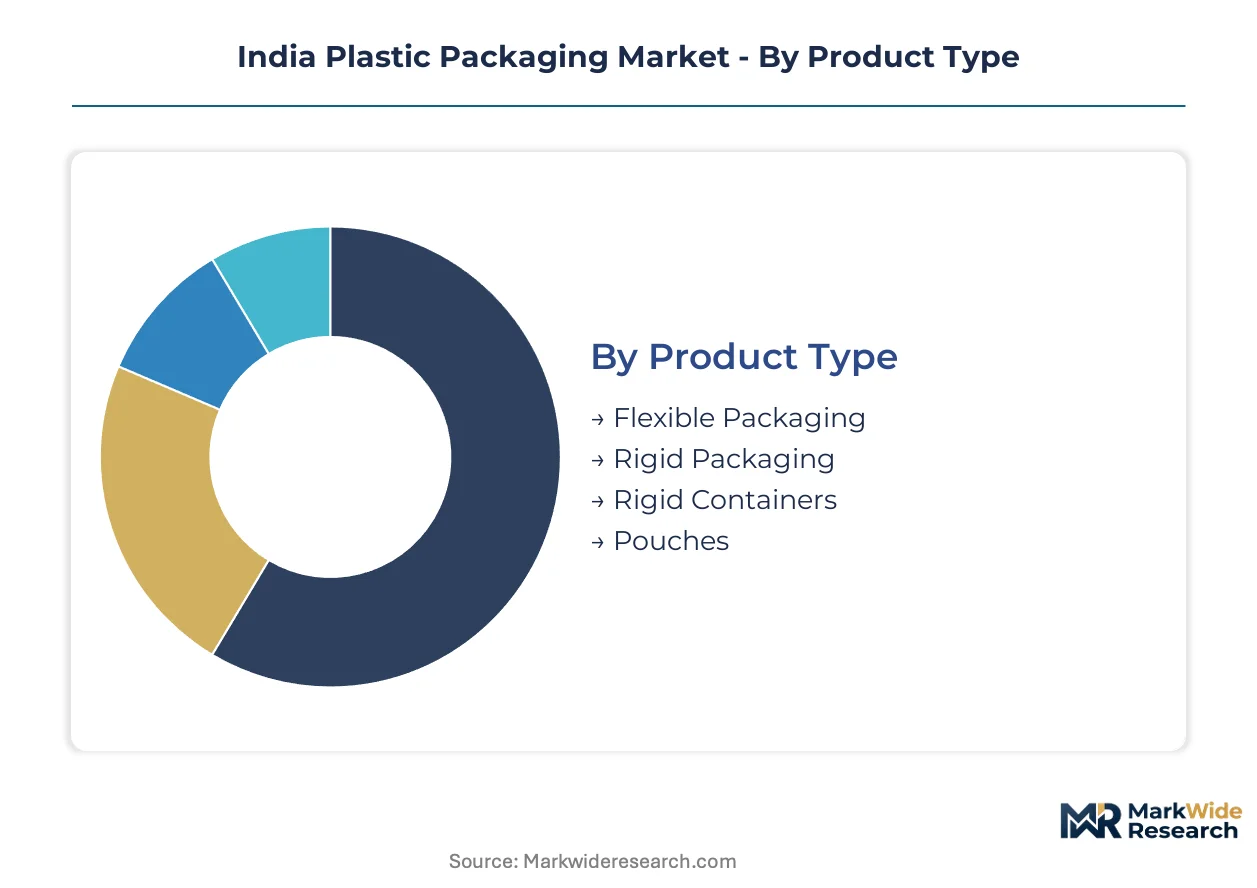
Segmentation in the India plastic packaging market reveals how material specifications, barrier requirements, and regulatory compliance reshape procurement decisions across polymer conversion clusters. Understanding these divides exposes where BIS-certified capacity concentrates versus where supply gaps persist.
Product Type:
Film extrusion and thermoforming technologies create divergent capital intensity profiles across Maharashtra and Gujarat conversion corridors.
- Flexible Packaging:Multilayer coextruded films and laminated structures dominate pouch and sachet production for FMCG applications. Oxygen transmission specifications below 0.1 cc/m²/day are becoming standard for shelf-stable dairy processors in western India, though migration testing bottlenecks delay new product approvals by 8-12 weeks.
- Rigid Packaging:Injection-molded and thermoformed containers serve pharmaceutical blister packs and edible-oil bottles where dimensional stability matters. Tamil Nadu's oral solid dosage corridors drive demand for high-barrier blister films with tropical climate stability requirements.
- Rigid Containers:HDPE and PP jars, bottles, and closures target personal care and household segments. Peninsular India penetration remains limited for qualified suppliers despite processed food corridor expansion in Karnataka.
- Pouches:Stand-up and flat pouch configurations integrate spouts, zippers, and reseal features for ready-to-eat meals. Water-based barrier coatings are replacing solvent laminations in Gujarat snack food pilot programs.
Mature deployment sits with flexible packaging. Newer deployment is concentrated in rigid containers for pharmaceutical barrier formats.
End User:
Customer procurement power varies sharply, with multinational FMCG panels enforcing sustainability scorecards that weight post-consumer recycled content above price.
- Food & Beverage:Shelf-stable dairy, edible oils, and ready-to-eat meals drive multilayer flexible pouch adoption. FSSAI migration limits for heavy metals and primary aromatic amines are disqualifying legacy Southeast Asian import supply chains.
- Healthcare:Blister packs, bottles, and closures for oral solid dosages demand high-barrier films and desiccant-integrated structures. CDSCO registration requirements and tropical stability protocols filter supplier bases toward domestic converters with captive laboratory infrastructure.
- Personal Care:Tubes, bottles, and dispensing formats compete on decoration precision and barrier performance. SEBI BRSR disclosure requirements push listed packaging firms to document plastic intensity targets.
- Household Products:Detergent and cleaner packaging permits greater material experimentation than food-contact applications. Brand-owner consolidation of supplier panels favors converters with documented EPR collection partnerships.
Procurement concentration is heaviest in food and beverage. Fastest specification upgrades are occurring in healthcare.
Material:
Recyclability protocols and EPR obligations are accelerating material substitution away from legacy polymer grades.
- LDPE:Linear low-density films dominate stretch wrap and secondary packaging applications. rPET integration mandates are pulling investment toward collection infrastructure rather than virgin LDPE expansion.
- HDPE:Blow-molded bottles for milk, edible oils, and household chemicals offer established recycling streams. Mechanical recycling contamination limits constrain circular economy claims for multilayer structures.
- PET:Displacing PVC in beverage and edible-oil applications as brand-owner sustainability commitments tighten. Post-consumer recycled content qualification programs are accelerating demand for reprocessing capacity.
- PVC:Retreating to niche pharmaceutical and construction applications amid recyclability pressures. Feedstock price volatility exposes converters to margin compression when pass-through clauses lag spot market movements.
Established volume sits with LDPE. Steepest expansion trajectory belongs to PET.
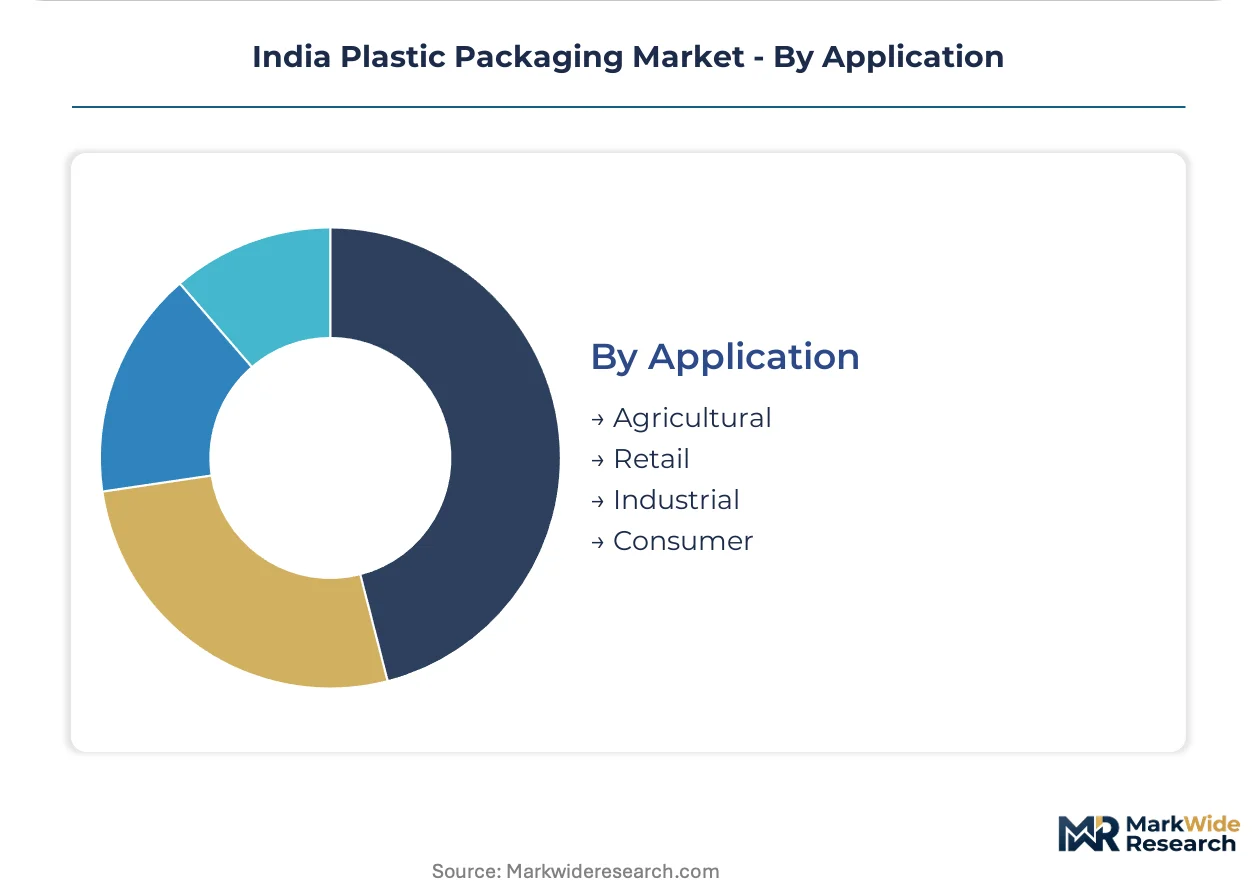
Application:
Channel requirements diverge on order minimums, lead times, and customization depth.
- Agricultural:Mulch films, silage bags, and crop protection sheets prioritize UV stability and cost efficiency. BIS IS 9845 compliance is filtering supplier bases toward domestic converters with in-house testing laboratories.
- Retail:Brand-ready primary packaging demands shelf presence and barrier performance. Digital printing technologies are collapsing minimum order quantities for regional brand owners competing with national players.
- Industrial:Drum liners, intermediate bulk containers, and protective films prioritize durability over aesthetics. Western India supply concentration creates logistics vulnerability for eastern and southern markets.
- Consumer:Direct-to-household formats span food, personal care, and home care segments. Extended producer responsibility mandates are restructuring capital allocation across polymer conversion clusters.
Volume concentration remains in retail. Specification upgrade intensity is highest in agricultural compliance alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India generates surplus conversion capacity while eastern and peninsular markets absorb output through extended logistics networks. Maharashtra and Gujarat polymer clusters concentrate roughly sixty percent of qualified flexible packaging supply. Tamil Nadu and Karnataka processed food corridors remain underserved by BIS-certified converters despite accelerating demand.
Maharashtra
Mumbai-based FMCG procurement panels enforce sustainability scorecards that weight post-consumer recycled content above unit pricing. SEBI BRSR disclosure requirements push listed packaging firms headquartered in the state to document plastic intensity and recycling targets. The Thane-Bhiwandi industrial belt anchors film extrusion and pouch converting operations serving national brand owners.
Gujarat
Edible oil processors and snack food manufacturers drive multilayer flexible pouch specifications with oxygen transmission requirements below 0.1 cc/m²/day. FSSAI migration limits for heavy metals filter supplier bases toward domestic converters with captive laboratory infrastructure. The Ahmedabad-Vadodara corridor hosts integrated film-to-pouch operations piloting water-based barrier coatings to replace solvent laminations.
Tamil Nadu
Oral solid dosage pharmaceutical corridors generate demand for high-barrier blister films with tropical climate stability requirements. CDSCO registration protocols and specific migration limit verification face laboratory queue times exceeding eight weeks, delaying new product approvals. The Sriperumbudur-Oragadam belt attracts pharmaceutical packaging investments from converters seeking proximity to formulation facilities.
Karnataka
Ready-to-eat meal processors and shelf-stable dairy brands expand pouch adoption for retail-ready formats. BIS IS 9845 compliance for food-contact materials advantages domestic converters with in-house testing capabilities over import-dependent competitors. The Bengaluru-Tumkur industrial zone remains underpenetrated by qualified flexible packaging suppliers despite processed food corridor expansion.
West Bengal
Eastern markets rely on western supply clusters for qualified flexible packaging, creating logistics vulnerability and extended lead times. The Plastic Waste Management Rules impose extended producer responsibility obligations that reshape material choices and collection infrastructure investments. The Kolkata-Haldia belt hosts limited BIS-certified conversion capacity relative to regional food processing demand.
India Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward integrated polymer converters with captive film production and in-house regulatory testing infrastructure. Mid-tier specialists compete on decoration precision and barrier performance for pharmaceutical and personal care segments. Three archetypes dominate: integrated film-to-pouch manufacturers, tube-based dispensing specialists, and rigid container molders serving edible oils. Capacity expansion and strategic partnerships with FMCG brand owners constitute the dominant competitive moves.
Among integrated converters, Uflex Limited and Huhtamaki India Limited exemplify the scale-driven archetype with broad film and pouch manufacturing footprints. Essel Propack Limited occupies a distinct position as a tube-based dispensing specialist competing on decoration and barrier precision for oral care and cosmetics applications. These three entities represent the tier of domestic and multinational players best positioned to capture specification upgrades from food and beverage processors, pharmaceutical formulators, and personal care brand owners consolidating supplier panels around documented EPR collection partnerships and post-consumer recycled content qualification programs.
| Leading Market Players |
|---|
| Essel Propack Limited |
| Cosmo Films Ltd |
| Amcor PLC |
| Sealed Air Corporation |
| Huhtamaki India Limited |
| Uflex Limited |
| Polyplex Corporation Limited |
| Mold-Tek Packaging Limited |
| Jindal Poly Films Limited |
| Others |
Supply & Pricing Matrix
Certification-tier divergence between BIS-accredited converters and import-dependent competitors manifests in both pricing premiums and supply chain access. Domestic firms with captive laboratory infrastructure command higher unit prices while securing preferential placement on multinational FMCG procurement panels, whereas uncertified competitors face exclusion from food-contact applications regardless of cost position.
Pricing Analysis
Margin tightening in commodity-grade flexible packaging reflects crude-linked resin volatility and delayed pass-through clauses. Contract-based long-term offtake agreements dominate procurement between Maharashtra polymer clusters and western India food processors, with price differentiation resting on BIS certification tier and volume scale. Brand-owner sustainability scorecards now weight post-consumer recycled content above unit pricing, making EPR-compliant suppliers least price-sensitive while mid-tier converters absorb maximum cost pressure.
Supply Chain Analysis
Dual-sourcing mandates from Mumbai-based FMCG procurement panels force brand owners to qualify multiple converters despite geographic concentration. Polymer resin draws from Saudi Arabia, South Korea, and Singapore, while specialty barrier films hinge on Japanese and German suppliers. Single-source vulnerability persists in high-barrier coating chemistries. Distribution runs through Thane-Bhiwandi warehousing clusters to peninsular and eastern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's plastic packaging market operates as a supply-constrained environment where BIS certification bottlenecks prop pricing power for accredited domestic converters.
For Market Incumbents: Lock in procurement panel positions by accelerating captive collection infrastructure for EPR compliance ahead of Plastic Waste Management Rule enforcement. Extend barrier coating R&D partnerships with snack food processors in Gujarat to preempt water-based technology adoption by competitors. Vertical integration into film extrusion preserves margin control against resin volatility. For New Entrants and Emerging Players: The premium-economy price gap in pharmaceutical blister films creates entry space for Tamil Nadu-based converters with tropical stability expertise. Target oral solid dosage corridors around Sriperumbudur-Oragadam with CDSCO-registered capacity. Lead with rapid migration testing turnaround as the go-to-market wedge against incumbent laboratory queues. For Investors and Strategic Acquirers: Re-rating potential sits with integrated film-to-pouch manufacturers given SEBI BRSR disclosure acceleration forcing listed competitors to document plastic intensity targets. Long-term viability favors converters with backward integration into resin handling and captive recycling partnerships. Watch for chemical recycling certification scale as the inflection signal for multilayer laminate circularity claims.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Maharashtra converters secure margin control against Saudi resin price volatility. |
| BIS IS 9845 Certification Investment | Domestic laboratories capture specification revisions from FSSAI-mandated migration limits. |
| EPR Collection Partnership Formation | FMCG procurement panels consolidate supplier bases around documented recycling infrastructure. |
| Water-Based Barrier Coating Adoption | Gujarat snack food pilots replace solvent laminations under tightened FSSAI compliance. |
| Peninsular India Capacity Expansion | Karnataka and Tamil Nadu corridors address qualified supply gaps for processed food demand. |
Research Methodology
Document review covered BIS certification registries, FSSAI migration limit notifications, and SEBI BRSR disclosure filings, complemented by interviews with polymer plant managers, FMCG procurement leads, pharmaceutical packaging engineers, and regulatory compliance officers. Secondary sources included Central Pollution Control Board enforcement data, customs import records for barrier films, and industry association capacity surveys. Bottom-up segment sizing and top-down macro validation were triangulated against trade flow analysis.
Historical volume trajectories were cross-referenced against converter capacity expansion announcements and brand-owner sustainability commitment timelines. Segmentation modeling spanned product type, material grade, end-use vertical, and regional production cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization assumptions across the analysis window. Feedstock price scenarios and regulatory enforcement intensity served as key sensitivity inputs.
Underlying measurement precision varies by segment; flexible packaging volume estimates carry tighter precision than emerging chemical recycling capacity forecasts. Projections reflect assumptions on EPR enforcement consistency and rPET collection infrastructure buildout. Deviation in FSSAI migration limit stringency or state-level single-use plastic ban implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sachet and Pouch Handling Systems Market