
 Sachet Packaging Market | 2026-2036
Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sachet Packaging Market Intelligence
Asset-light contract manufacturing and third-party leasing of form-fill-seal lines is reshaping competitive entry in sachet packaging. Mondi Group leverages its integrated paper and pulp operations to anchor European supply of fiber-based sachet substrates. Amcor plc sustains global reach through multi-material expertise spanning plastic, aluminum, and composite laminates. Uflex Limited dominates flexible packaging manufacturing across South Asia with extensive film extrusion and printing capabilities.
Sachet packaging denotes small-format sealed pouches, typically holding 1–50 milliliters, constructed from multilayer films or foil laminates via vertical form-fill-seal or horizontal flow-wrap processes, designed for single-use dispensing of liquids, powders, or semisolids. Stand-up pouch configurations command premium positioning in personal care and household segments due to shelf visibility and dispensing convenience. Stick packs represent the fastest-growing product type as pharmaceutical and nutraceutical brands adopt precise unit-dose formats for compliance and portability. Plastic remains the dominant material by volume, though composite and aluminum laminates capture higher margin pools in moisture-sensitive pharmaceutical applications.
FDA regulations on pharmaceutical primary packaging materials and child-resistant closures directly shape sachet design requirements for over-the-counter and prescription unit doses. The EU's REACH framework and F-Gas Regulation constrain solvent-based adhesive chemistries and certain barrier film compositions, pushing converters toward water-based systems and mono-material structures. EMA guidance on extractables and leachables testing adds compliance layers for pharma-grade sachets entering European markets. Stakeholders must monitor evolving extended producer responsibility schemes across multiple geographies, as packaging waste fees increasingly influence material selection and format economics.
Market Dynamics
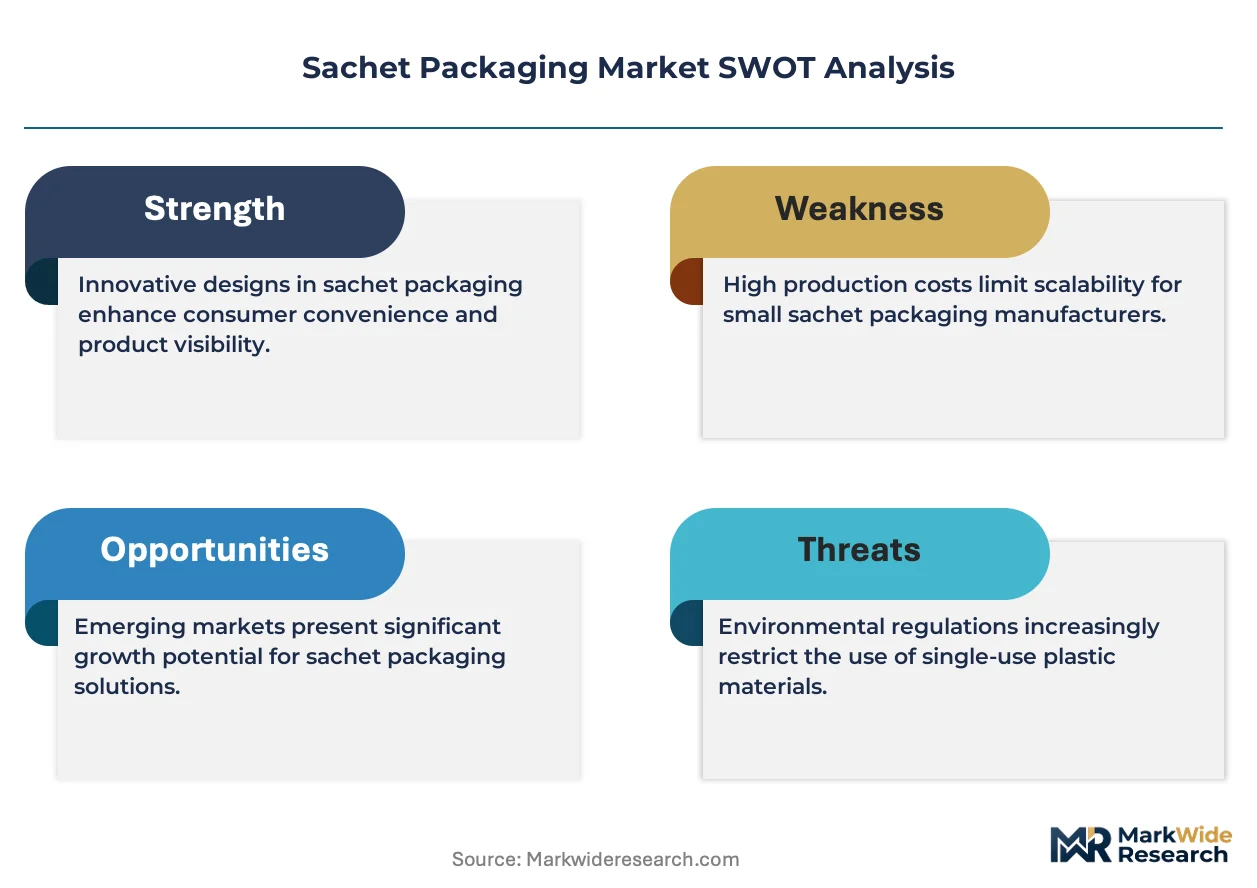
The EU's Single-Use Plastics Directive is forcing converters to abandon multilayer plastic laminates in favor of fiber-based and aluminum alternatives, reshaping material sourcing strategies across European supply chains.
Growth Catalysts
- REACH framework restrictions:The EU's chemical safety mandates are accelerating water-based adhesive adoption, opening contract manufacturing slots for compliant converters.
- Single-serve food formats:Emerging-market urbanization in India and Vietnam is creating organized retail penetration that favors sachet distribution for portion-controlled condiments and beverages.
- Stick pack pharmaceutical demand:Unit-dose compliance requirements in nutraceuticals are pulling precise-dispensing formats into over-the-counter and prescription channels.
Market Restraints
- Aluminum laminate cost volatility:Barrier-grade foil supply concentrates in Chinese and Russian smelter networks, exposing converters to input price swings and sanctions-related disruption.
- Multilayer recycling incompatibility:Current mechanical separation infrastructure cannot process plastic-paper-foil composites, creating landfill liability under extended producer responsibility schemes.
- Mono-material performance gaps:Polyethylene-only structures fail moisture and oxygen barrier requirements for hygroscopic pharmaceuticals, limiting regulatory compliance options.
Strategic Opportunities
- India's PLI scheme for packaging:Domestic manufacturing incentives are attracting film extrusion and printing capacity that reduces import dependence for sachet substrates.
- Pharmaceutical serialization mandates:Track-and-trace regulations in the EU and US are creating demand for integrated sachet-printing lines with variable-data capabilities.
- E-commerce sample distribution:Direct-to-consumer beauty and personal care brands are adopting sachet inserts as low-cost trial formats, bypassing traditional retail slotting fees.
Industry Challenges
- Extractables and leachables validation:EMA guidance requires extensive migration testing for pharma-grade sachets, extending product development timelines by 12-18 months.
- Form-fill-seal technician scarcity:Vertical and horizontal FFS line operation demands specialized mechanical and controls expertise that regional labor markets cannot supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sachet Packaging Market |
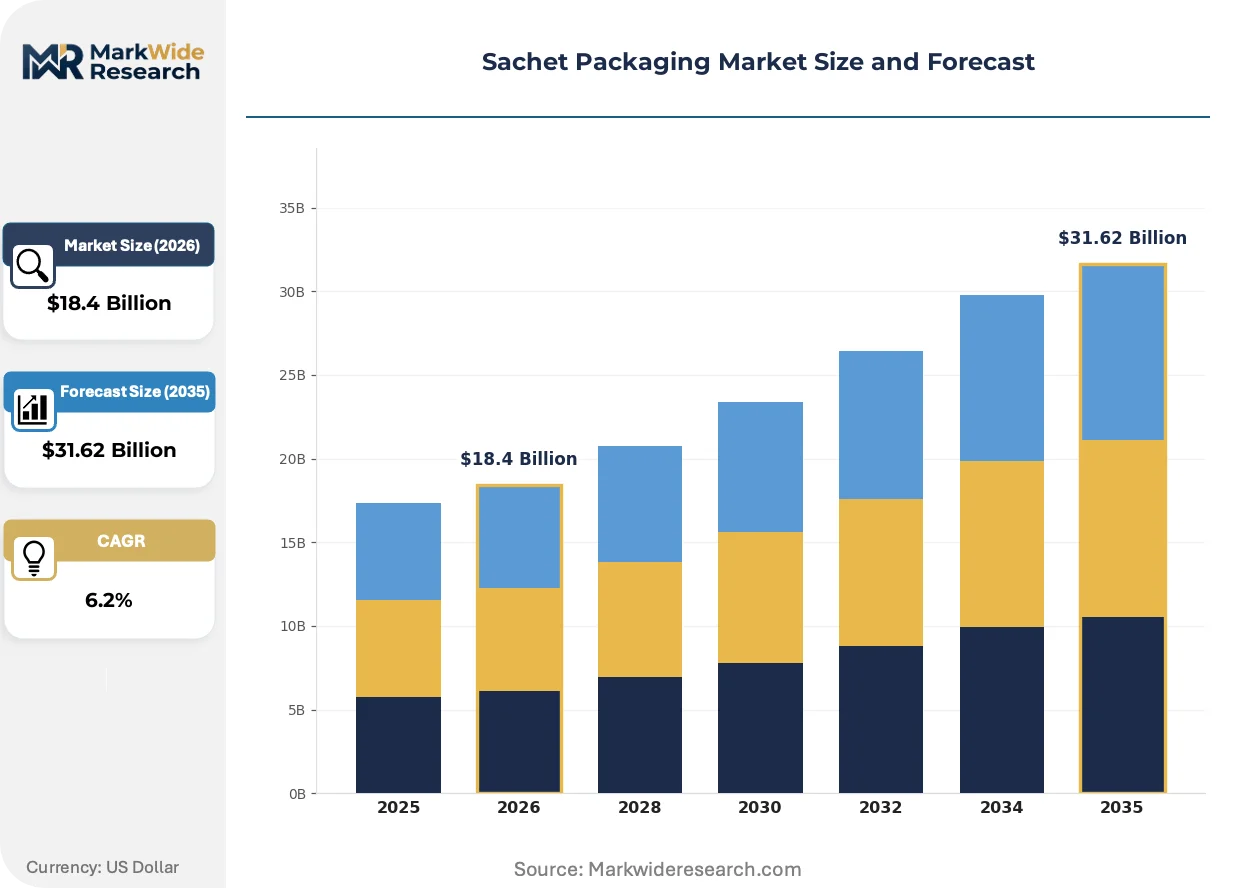
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve, Multi-Use, Stand-Up Pouch, Stick Pack Material: Plastic, Paper, Aluminum, Composites End User: Food & Beverages, Personal Care, Pharmaceuticals, Household Closure Type: Heat Seal, Press-to-Close, Zip Lock, Resealable |
| Companies Covered | ProAmpac Intermediate Inc., Mondi Group, Amcor plc, Graphic Packaging International, LLC, Berry Global Group, Inc., Huhtamaki Oyj, Constantia Flexibles Holding GmbH, Uflex Limited, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sachet Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are converging to redefine substrate specifications, with converters racing to validate alternatives before compliance deadlines eliminate incumbent options.
Barrier coating technology is hybridizing cellulose fiber structures with bio-based polymers to replicate aluminum's moisture protection without metal content. European personal care brands are piloting these substrates for shampoo and conditioner sachets ahead of 2025 plastic reduction targets. The structural consequence is compressing the cost premium between conventional laminates and next-generation fiber solutions from 40% to 15%.
FDA guidance on pharmaceutical container closure integrity is tightening unit-dose validation requirements for moisture-sensitive active ingredients. Manufacturers must now demonstrate 24-month stability data for sachet formats previously accepted with 12-month profiles. Oncology and biologic drug categories face the steepest compliance burden, with many sponsors retreating to blister packs until sachet barrier performance improves.
Brand procurement teams are consolidating supplier relationships from 15-20 regional converters to 3-5 strategic partners capable of multi-material, multi-continent production. This concentration is displacing spot-market purchasing for film laminates and pushing volume commitments with 24-36 month terms. The shift is most visible in North American and European nutraceutical markets, where quality audits and regulatory documentation burdens favor scaled suppliers.
Sachet Packaging Market Segmentation
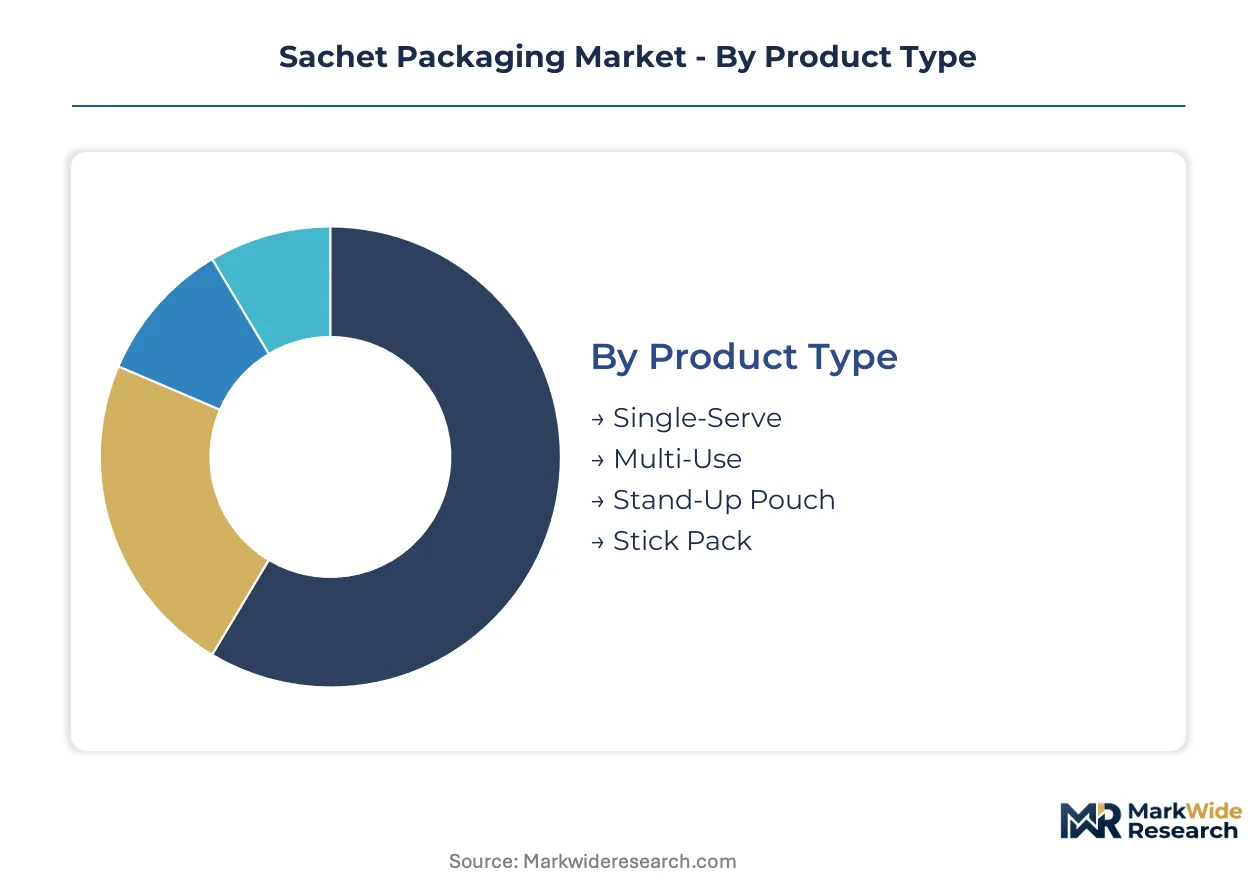
Sachet packaging formats diverge sharply in equipment servicing needs and line-changeover complexity, making segment-specific technical support a decisive procurement factor. Material and closure specifications further stratify converter capabilities and regulatory compliance burdens across end-use applications.
Product Type:
After-sales service intensity varies dramatically across sachet formats, with multi-lane stick pack lines demanding specialized technician deployment and rapid spare parts availability.
- Single-Serve:These 1–50 milliliter pouches deploy vertical form-fill-seal machinery for condiments, sauces, and beverage concentrates. Demand concentrates in Indian and Vietnamese urban retail where organized distribution networks favor portion-controlled pricing for mass-market consumers.
- Stand-Up Pouch:Gusseted bottom structures with spout or cap integration require horizontal flow-wrap or pre-made pouch filling systems with precision sealing controls. Personal care brands in European markets specify these formats for shampoo and conditioner samples where shelf visibility commands premium positioning.
- Multi-Use:Larger capacity sachets with reinforced seams accommodate bulk powder dispensing for industrial and foodservice applications.
- Stick Pack:Narrow rectangular formats with longitudinal sealing enable precise unit-dose dispensing of nutraceutical powders and pharmaceutical granules.
Single-Serve holds the largest share; momentum sits with Stick Pack as pharmaceutical serialization mandates expand.
Material:
Raw material cost tiers separate commodity converters from specialized barrier film suppliers, with aluminum and composite laminates capturing substantially higher margin pools.
- Plastic:Polyethylene and polypropylene mono-materials dominate volume through low-cost extrusion and heat-seal compatibility. Emerging-market food brands in India specify these substrates for condiment sachets where price sensitivity limits material substitution.
- Composites:Multilayer plastic-paper-foil laminates deliver oxygen and moisture barriers for hygroscopic pharmaceuticals. Oncology drug sponsors in EU markets require these structures despite recycling incompatibility under extended producer responsibility schemes.
- Aluminum:Pure foil or foil-polymer laminates provide absolute light and gas barrier for sensitive actives.
- Paper:Fiber-based substrates with bio-based barrier coatings are gaining traction in European personal care trials ahead of plastic reduction deadlines.
Plastic dominates absolute volume; aluminum and composites claim the steepest expansion trajectory as regulatory pressure intensifies.
End User:
Customer type determines validation depth, with pharmaceutical buyers imposing extractables testing and serialization requirements that food brands rarely match.
- Food & Beverages:Single-serve condiments, instant coffee, and cooking oil sachets drive volume through emerging-market retail penetration. Indian organized retail expansion and Vietnam's urban convenience store networks specify these formats for portion-controlled household purchasing.
- Pharmaceuticals:Unit-dose sachets for OTC and prescription drugs require FDA and EMA compliance for container closure integrity and child-resistant features. EMA guidance on leachables testing extends development timelines, pushing sponsors toward validated converter partnerships.
- Personal Care:Shampoo, conditioner, and lotion samples distribute through e-commerce inserts and hotel amenities.
- Household:Detergent and cleaning agent sachets target cost-conscious emerging-market consumers.
Food & Beverages anchors volume; Pharmaceuticals commands the highest technical barrier and pricing power.
Closure Type:
Resealability features differentiate premium positioning from commodity disposal, with zip lock and press-to-close mechanisms adding per-unit cost but extending product utility.
- Heat Seal:Permanent fusion bonding via impulse or constant heat sealing dominates single-serve applications where tamper evidence and hermetic integrity are paramount. Cost-sensitive food brands in India specify this closure for condiment sachets where resealability adds no consumer value.
- Zip Lock:Interlocking plastic profiles enable repeated opening and closing for multi-dose powder or solid products. Nutraceutical brands in North American markets adopt these for protein powder travel packs where portability and reuse convenience justify material cost premiums.
- Press-to-Close:Snap-fit profiles provide intermediate resealability for personal care samples.
- Resealable:Adhesive strip or mechanical systems for specialized pharmaceutical and household applications.
Heat Seal captures the greatest volume; zip lock formats are climbing fastest as e-commerce sample distribution expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in sachet substrates and converting equipment reveal stark regional asymmetries. India and Vietnam run structural deficits in barrier film extrusion capacity, importing polymer resins and metallized substrates from Chinese and Thai suppliers. European converters face export headwinds as the EU's Single-Use Plastics Directive disqualifies multilayer plastic laminates from intra-bloc circulation.
India
Urban convenience store networks in Mumbai and Bangalore are pulling single-serve condiment and beverage concentrate sachets into organized retail channels. The PLI scheme for packaging materials is attracting domestic film extrusion capacity that reduces import dependence for polyethylene substrates. Gujarat's industrial corridor hosts expanding converter operations serving pharmaceutical and food brands with multi-material laminates.
Germany
REACH framework restrictions on solvent-based adhesives are forcing converters toward water-based systems and fiber-based substrates. The country's national pharmaceutical regulator enforces strict extractables and leachables testing protocols for unit-dose sachets entering clinical supply chains. The Rhine-Ruhr manufacturing belt concentrates barrier coating R&D facilities developing cellulose-fiber alternatives to aluminum laminates.
Vietnam
Urbanization in Ho Chi Minh City and Hanoi is creating demand for portion-controlled cooking oil and instant coffee sachets through modern trade channels. The country's national standards body is aligning technical regulations with ASEAN harmonization frameworks for food-contact materials. The northern Red River Delta hosts emerging flexible packaging clusters serving domestic FMCG brands and export-oriented contract manufacturers.
United States
FDA guidance on pharmaceutical container closure integrity is tightening validation requirements for moisture-sensitive active ingredients in unit-dose formats. E-commerce sample distribution by direct-to-consumer beauty brands is pulling sachet inserts into fulfillment center operations. The Midwest industrial corridor maintains concentrated flexible packaging converting capacity serving nutraceutical and personal care markets.
Indonesia
Organized retail penetration in Jakarta and Surabaya is expanding distribution infrastructure for single-serve household and personal care sachets. The national food and drug regulator enforces halal certification requirements for packaging materials in contact with consumable products. Java's manufacturing belt hosts integrated film extrusion and printing operations serving domestic and ASEAN export markets.
Sachet Packaging Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in substrate supply and niche converting equipment. The vendor base stratifies across three tiers: multinational material science conglomerates with integrated pulp-to-pouch operations, mid-scale regional converters with single-site film extrusion and printing capabilities, and asset-light contract manufacturers leasing form-fill-seal capacity. Strategic moves concentrate on backward integration into barrier film production and geographic expansion through distributor partnerships in underserved emerging markets.
Within the integrated material science tier, Mondi Group and Amcor plc exemplify platform breadth spanning fiber-based and polymer substrate portfolios. Uflex Limited occupies a position among South Asia-dominant converters with captive film extrusion and metallization capabilities. These three anchors represent divergent competitive vectors: European fiber-transition leadership, global multi-material coverage, and emerging-market scale manufacturing respectively.
| Leading Market Players |
|---|
| ProAmpac Intermediate Inc. |
| Mondi Group |
| Amcor plc |
| Graphic Packaging International, LLC |
| Berry Global Group, Inc. |
| Huhtamaki Oyj |
| Constantia Flexibles Holding GmbH |
| Uflex Limited |
| Sealed Air Corporation |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam maritime corridor anchors freight cost dynamics for metallized barrier films and aluminum laminates, compressing margins for European converters while amplifying price differentiation between commodity polyethylene sachets and pharmaceutical-grade composites. Supply concentration in Chinese smelter networks and Thai film extrusion clusters feeds downstream tiering, with logistics expenses now separating viable from non-viable procurement relationships across the Atlantic basin.
Pricing Analysis
Industrial OEM buyers anchor transactional pricing structures across plastic mono-material tiers, while pharmaceutical sponsors negotiate contract-based long-term offtakes for validated aluminum laminates. Price differentiation hinges on EMA certification status and volume scale, with barrier-grade foil structures commanding substantial premiums over commodity polyethylene. Pricing pressure stems from aluminum cost volatility linked to sanctions-exposed Russian smelter supply, squeezing mid-tier converters. Emerging-market food brands exhibit highest price sensitivity, limiting material substitution, whereas oncology drug sponsors accept premium positioning for compliance assurance.
Supply Chain Analysis
Tariff exposure between the United States and Chinese aluminum suppliers dominates risk calculations for barrier laminate converters serving EU pharmaceutical markets. Raw material sourcing draws from Chinese metallized film production, Thai polyethylene extrusion, and Indian biaxially oriented polypropylene capacity. Single-source vulnerability concentrates in Chinese foil supply for moisture-sensitive pharmaceutical applications. Distribution runs through regional converter hubs in Gujarat, the Rhine-Ruhr belt, and Vietnam's Red River Delta, with brand procurement teams consolidating supplier relationships to reduce audit burdens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sachet packaging is approaching a platform-economics inflection as pharmaceutical serialization mandates and e-commerce sample distribution converge, requiring interoperability between variable-data printing lines and direct-to-consumer fulfillment systems.
For Market Incumbents: Harden barrier coating R&D capabilities in European fiber-based substrates ahead of EU Single-Use Plastics Directive enforcement, securing first-mover position in aluminum-free pharmaceutical formats. Consolidate form-fill-seal technician training programs to address regional labor scarcity that threatens line utilization rates. Lock in multi-year volume commitments with Indian and Vietnamese film extruders to defend input cost position against spot-market volatility.
For New Entrants and Emerging Players: Build out contract manufacturing capacity in India's PLI-subsidized packaging corridors, targeting domestic pharmaceutical brands seeking reduced import dependence for validated sachet substrates. Capture white-space in e-commerce sample distribution for direct-to-consumer beauty brands, where slotting-fee avoidance creates procurement pull for sachet inserts. Lead with serialized printing capabilities as the go-to-market wedge against incumbent spot converters.
For Investors and Strategic Acquirers: Regional converters with captive metallization and multi-material validation expertise represent the priority acquisition archetype, given pharmaceutical sponsor consolidation toward strategic supplier partnerships. Long-term viability rests on backward integration into barrier film production and geographic footprint spanning EU regulatory compliance and emerging-market scale. Monitor EMA guidance evolution on extractables testing timelines as the signal for validation-burden inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Film Production | Captive metallized substrate supply reduces exposure to Chinese foil price volatility and sanctions risk. |
| Water-Based Adhesive System Conversion | REACH compliance opens contract manufacturing slots previously closed to solvent-based converters. |
| Serialized Sachet Printing Line Deployment | FDA and EMA track-and-trace mandates create demand for variable-data capable equipment. |
| India PLI Corridor Manufacturing Expansion | Domestic film extrusion capacity reduces import dependence for polyethylene substrates serving South Asian markets. |
| Fiber-Based Substrate Validation Programs | European personal care brands pilot cellulose alternatives ahead of plastic reduction deadlines. |
Research Approach
Cross-validation between converter procurement leads and pharmaceutical regulatory affairs directors anchors the qualitative findings, with secondary triangulation against EMA guidance documents and FDA container closure integrity filings. Primary interviews spanned plant managers at flexible packaging facilities, brand procurement heads in nutraceutical and personal care segments, and distribution channel partners in Indian and Vietnamese organized retail. Secondary sources included customs trade data for metallized film imports, SEC 10-K disclosures from integrated material science conglomerates, and BIS technical regulations for food-contact materials. Bottom-up capacity assessments and top-down demand modeling were reconciled to produce volume estimates.
Calibration against historical capacity utilization rates and raw material price indices shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, material substrate, end-use application, closure mechanism, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating urbanization rates in target emerging markets and pharmaceutical serialization mandate implementation timelines. Industry-specific inputs included barrier coating technology adoption curves and extended producer responsibility fee structures.
Practitioners should monitor aluminum tariff policy shifts and EMA extractables testing protocol revisions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Germany Sachet Packaging Market