
 Full Container Shrink Sleeves Market | 2026-2036
Full Container Shrink Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Full Container Shrink Sleeves Market Foresight
Subscription-based design and pre-press services for shrink sleeve artwork is broadening what converters sell beyond commodity film. Berry Global sustains manufacturing scale across multiple polymer platforms for diverse sleeve specifications. Avery Dennison differentiates through adhesive and film technologies that improve print registration and shrink performance. Fuji Seal International dominates the Asian converting landscape with integrated sleeve production and application equipment.
Full container shrink sleeves are polymer-based labels that encase an entire product container and conform tightly through controlled heat application, typically requiring 40-70 percent shrinkage ratios and compatibility with steam or hot-air tunnels. Their primary commercial purpose is to deliver uninterrupted 360-degree graphics, tamper-evident seals, and container bundling in a single packaging step. Polyethylene Terephthalate sleeves command structural attention due to superior clarity and recyclability alignment with circular packaging goals, while Beverage applications anchor volume demand because of high line speeds and premium branding requirements. The Household Chemicals segment occupies a specialized margin pool where chemical resistance and sleeve integrity under harsh contents justify premium pricing.
FDA regulations govern sleeve materials in direct food-contact applications in the United States, while EFSA and REACH frameworks in Europe restrict certain plasticizers and mandate recyclability disclosures for packaging placed on the market. These standards force converters to validate substrate compositions and traceability, raising compliance costs but also creating technical barriers that favor established players with testing infrastructure. Stakeholders must monitor evolving extended producer responsibility schemes and chemical hazard reclassifications that could abruptly disqualify incumbent sleeve formulations.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across the converting base, compressing legacy PVC formulations while opening margin pools for PETG and PLA substrate specialists with validated recyclability credentials.
Growth Catalysts
- 360-Degree Branding Imperative:Beverage bottlers demand uninterrupted graphics coverage for shelf differentiation, pulling sleeve specifications toward higher shrink ratios and photorealistic print registration.
- REACH Compliance Migration:European chemical hazard reclassifications are disqualifying legacy plasticizers, redirecting procurement toward converters with ECHA-validated substrate traceability systems.
- Steam Tunnel Retrofits:Hot-air shrink systems are overtaking steam infrastructure in North American dairy and juice facilities, expanding addressable sleeve specifications for moisture-sensitive applications.
Market Restraints
- Resin Supply Concentration:PETG pellet production clusters in South Korea and Taiwan create input cost volatility for converters without backward-integrated polymer sourcing.
- Application Equipment Lock-In:Proprietary mandrel designs from Fuji Seal and Krones limit sleeve interchangeability, raising switching costs for brand owners.
- Extended Producer Responsibility Schemes:Germany's VerpackG and France's Citeo fee structures impose per-unit compliance costs that compress margins on commodity sleeve grades.
Strategic Opportunities
- India Beverage Expansion:Carbonated soft drink and bottled water volumes in Maharashtra and Gujarat are outpacing label capacity, creating first-mover advantages for sleeve converters establishing local slitting operations.
- Digital Print Convergence:Hybrid electrophotographic-flexo presses enable run-length flexibility down to 5,000 units, collapsing minimum order thresholds for craft spirits and seasonal SKUs.
- Mechanical Recycling Alignment:APR-designated PETG sleeves with density separation compatibility command price premiums from Coca-Cola and PepsiCo sustainability procurement teams.
Industry Challenges
- Pre-Press Talent Scarcity:Distortion correction for high-shrink artwork requires specialized Esko or Hybrid Software expertise that converters struggle to retain.
- Application Line Integration:Sleeve applicator synchronization with existing filler-capper-blocker configurations demands custom engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full Container Shrink Sleeves Market |
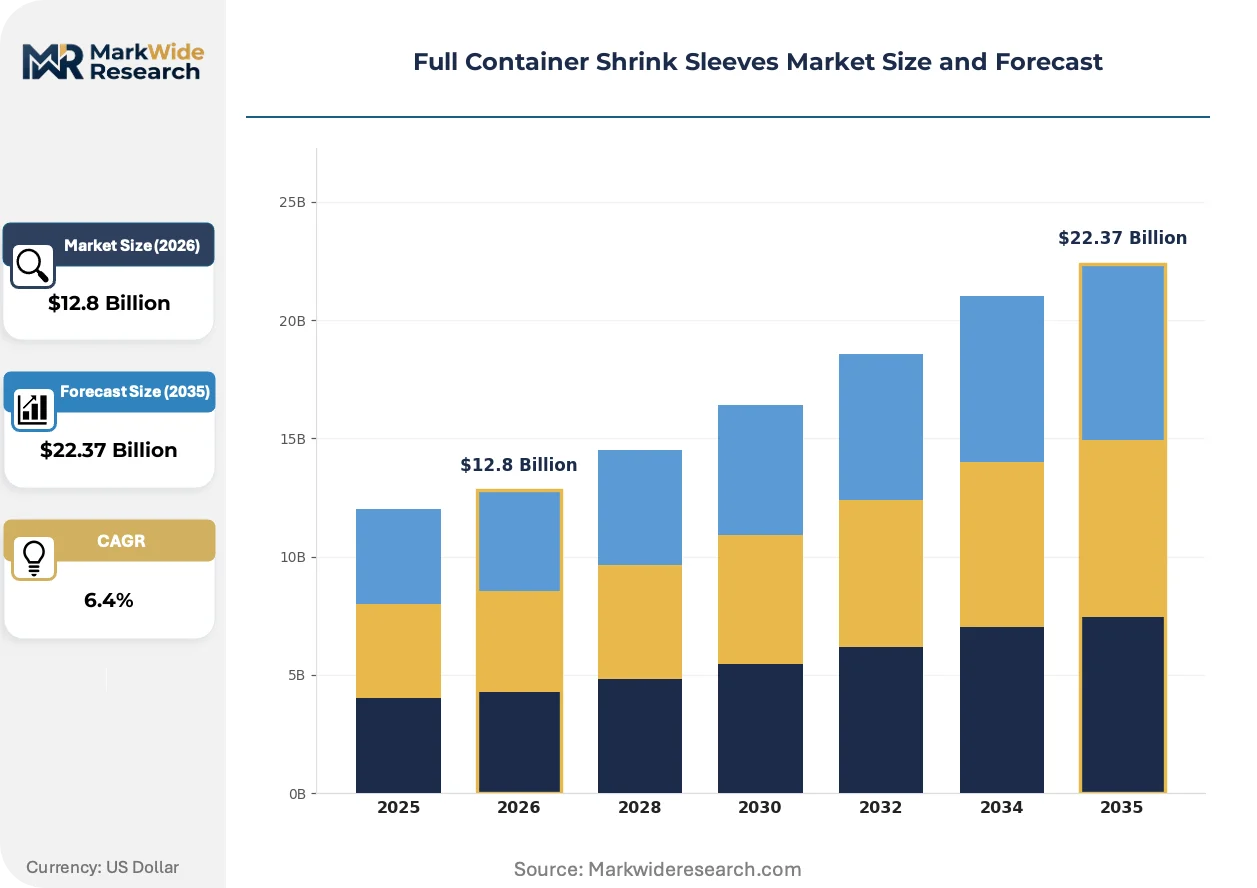
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Chloride, Polyethylene Terephthalate, Polyethylene, Polypropylene, Polystyrene Application: Beverages, Household Chemicals, Personal Care, Pharmaceuticals, Food & Snacks Packaging Type: Bottles, Jars, Cans, Cartons, Tubes End User: Manufacturers, Distributors, Retailers, Private Labels, Contract Packers |
| Companies Covered | Klöckner Pentaplast, Hammer Packaging, Inc., Berry Global, Inc., Paris Art Label Company Inc., Macfarlane Group PLC, Avery Dennison Corporation, Constantia Flexibles, CCL Industries, Fuji Seal International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full Container Shrink Sleeves Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry reclassifications are compressing legacy substrate positions while elevating digital workflow and circular-design capabilities as primary competitive differentiators.
Floatable polyolefin shrink films are overtaking conventional PETG in European beverage applications where sink-float separation systems dominate mechanical recycling infrastructure. Danone and Nestlé Waters procurement specifications now prioritize density below 1.0 g/cm³, compelling converters to reformulate multilayer structures. This substrate rotation is compressing margins for legacy PETG specialists while rewarding polymer scientists with proprietary blend patents.
REACH Annex XVII restrictions on phthalate plasticizers are disqualifying PVC shrink formulations from food-contact applications across EU member states. Converters must validate alternative plasticizer systems through EFSA migration testing protocols, extending new product qualification timelines. The household chemicals segment is absorbing disproportionate compliance burden given aggressive content-sleeve interaction requirements.
Subscription-based artwork management platforms are displacing transactional pre-press relationships as multinational brand owners centralize design asset control. PepsiCo and AB InBev procurement teams now mandate cloud-based approval workflows with version-locked specifications. This operational shift concentrates sleeve design spend with converters offering integrated digital asset management, squeezing standalone graphics houses from the value chain.
Full Container Shrink Sleeves Market Segmentation
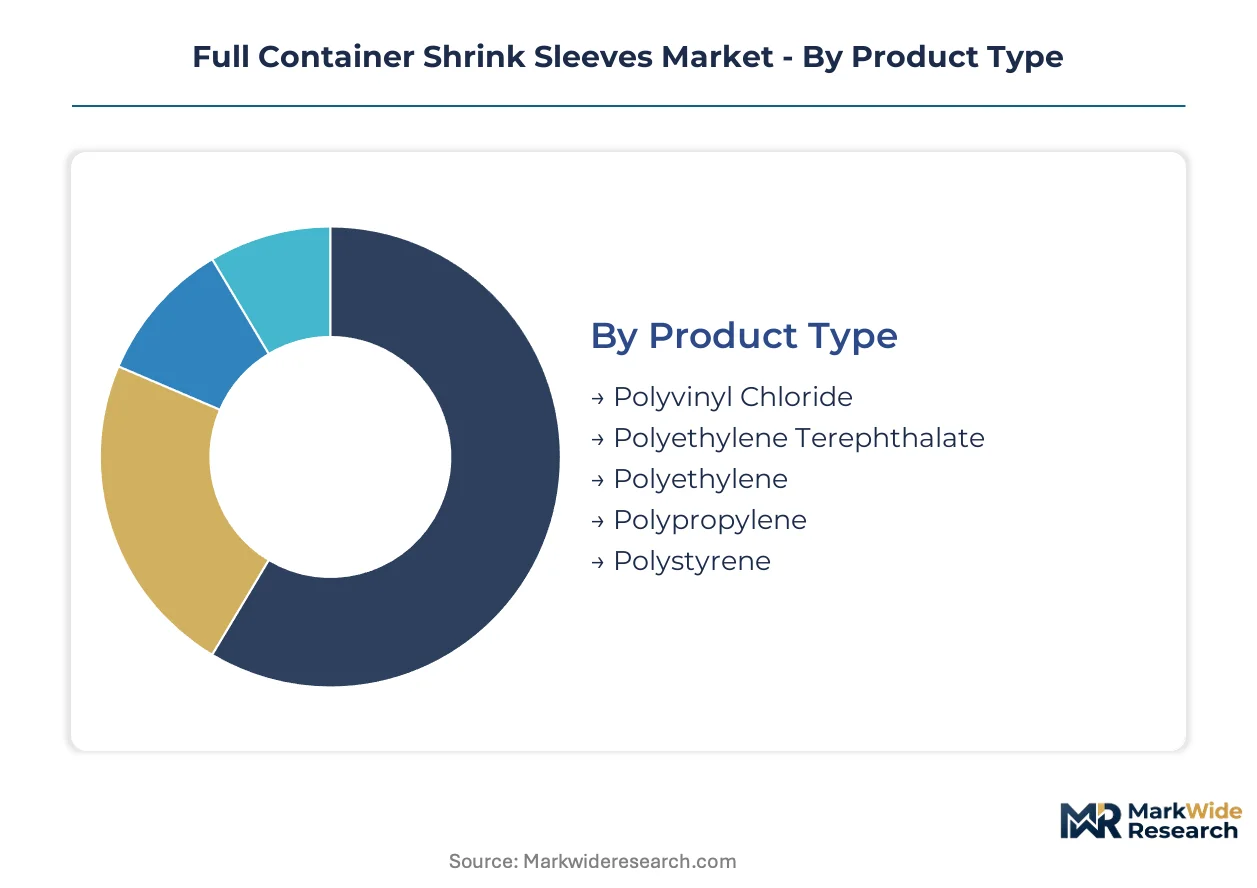
Full container shrink sleeve procurement splits across polymer chemistry, container geometry, and channel position, with each axis demanding distinct converting capabilities and compliance postures. Capital allocation decisions by converters hinge on which segment combinations offer validated recyclability credentials and line-speed compatibility.
Product Type:
Capital intensity peaks with PET resin systems requiring crystallization control and optical-grade extrusion, while commodity polyolefin lines demand lower upfront tooling investment but compress margin pools.
- Polyethylene Terephthalate:PET sleeves deliver superior optical clarity and density separation compatibility with existing beverage recycling streams. Demand concentrates in Coca-Cola and PepsiCo sustainability procurement specifications across the United States and Germany, where APR-designated substrates command price premiums over conventional alternatives.
- Polyvinyl Chloride:Legacy PVC formulations face REACH Annex XVII phthalate restrictions across EU member states, forcing converters toward alternative plasticizer validation through EFSA migration protocols. Household chemicals applications in France and Germany absorb disproportionate compliance burden given aggressive content-sleeve interaction requirements.
- Polyethylene:Floatable PE structures below 1.0 g/cm³ density align with European sink-float separation infrastructure.
- Polypropylene:PP substrates offer chemical resistance for aggressive contents with lower shrink ratios than PET.
- Polystyrene:PS sleeves occupy niche applications requiring rigid pre-shrink handling characteristics.
Most installed capacity flows through Polyethylene Terephthalate. Expansion is steepest in Polyethylene.
Application:
Line speed requirements and branding intensity separate high-volume beverage converters from specialized pharmaceutical and personal care specialists.
- Beverages:Carbonated soft drink and bottled water bottlers drive the highest sleeve throughput globally, with Maharashtra and Gujarat in India outpacing label capacity and creating first-mover advantages for local slitting operations. Steam tunnel retrofits in North American dairy facilities are expanding addressable specifications for moisture-sensitive applications.
- Household Chemicals:Bleach, detergent, and solvent containers demand chemical-resistant substrates with validated integrity under harsh contents, justifying premium pricing tiers. ECHA hazard reclassifications are extending new product qualification timelines for this segment.
- Personal Care:Shampoo and conditioner bottles prioritize 360-degree graphics for shelf differentiation in retail environments.
- Pharmaceuticals:Tamper-evident seals and lot traceability requirements dominate procurement specifications.
- Food & Snacks:FDA direct food-contact compliance governs substrate selection in the United States.
Volume concentration sits with Beverages. Margin expansion is most pronounced in Household Chemicals.
Packaging Type:
Container geometry dictates shrink ratio requirements and applicator mandrel specifications, with cylindrical formats offering the most standardized converting economics.
- Bottles:Cylindrical and contoured beverage bottles anchor global sleeve demand, with 40-70 percent shrinkage ratios enabling uninterrupted graphics coverage. Hot-air shrink systems are overtaking steam infrastructure in North American juice facilities, expanding equipment compatibility requirements.
- Jars:Wide-mouth food and personal care containers require specialized distortion correction for artwork alignment at high shrink ratios.
- Cans:Aluminum beverage cans utilize sleeves for seasonal and promotional branding with rapid changeover requirements.
- Cartons:Rectangular formats demand multi-panel sleeve designs with corner reinforcement.
- Tubes:Squeezable personal care and pharmaceutical tubes require flexible substrate formulations.
Equipment standardization centers on Bottles. Technical complexity is highest for Tubes.
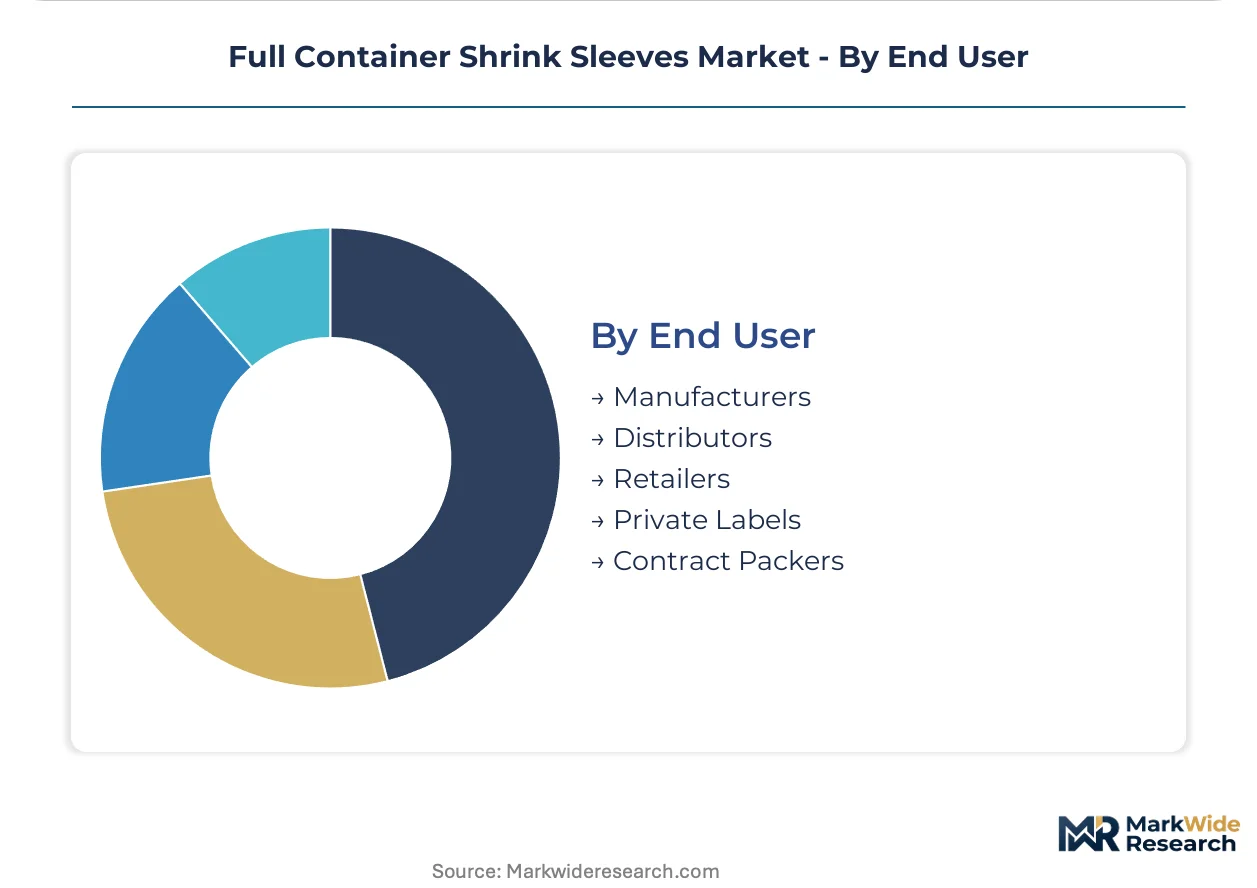
End User:
Procurement scale and design control separate multinational brand owners from fragmented private label and contract packing channels.
- Manufacturers:Procter & Gamble and Unilever procurement teams mandate cloud-based artwork approval workflows with version-locked specifications, concentrating sleeve design spend with converters offering integrated digital asset management. PepsiCo and AB InBev sustainability teams prioritize APR-designated recyclability credentials.
- Private Labels:Retailer-owned brands in Germany and France absorb per-unit compliance costs under VerpackG and Citeo fee structures, compressing margins on commodity sleeve grades.
- Distributors:Regional beverage and chemical distributors aggregate demand across smaller brand portfolios.
- Retailers:Walmart and Carrefour direct sourcing specifications influence substrate selection for store-brand lines.
- Contract Packers:Seasonal and promotional campaigns drive short-run demand requiring digital print flexibility down to 5,000 units.
Design control concentrates with Manufacturers. Run-length flexibility is most critical for Contract Packers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States converters command the largest procurement volumes, while German regulatory frameworks are forcing faster substrate transitions across European operations. China hosts the most extensive domestic converting base outside North America and Europe.
United States
Beverage bottlers in Georgia and Texas are retrofitting hot-air shrink tunnels to replace steam infrastructure, expanding specifications for moisture-sensitive dairy and juice applications. FDA direct food-contact compliance governs substrate selection for Coca-Cola and PepsiCo procurement teams. Converting capacity concentrates in the Midwest and Southeast, where Berry Global and Avery Dennison maintain integrated manufacturing and distribution networks.
Germany
VerpackG extended producer responsibility fees impose per-unit compliance costs that compress margins on commodity sleeve grades for private label brands. ECHA hazard reclassifications under REACH Annex XVII are disqualifying legacy PVC formulations, redirecting procurement toward PETG and PLA specialists. The Rhine-Ruhr and Bavarian industrial corridors host the densest converting clusters, with Constantia Flexibles operating validated traceability systems.
China
Carbonated soft drink and bottled water volumes are outpacing label capacity in coastal provinces, creating first-mover advantages for converters establishing local slitting operations. SAMR packaging regulations and GB standards govern recyclability disclosures for substrates placed on the market. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate domestic sleeve production, with Fuji Seal International anchoring integrated sleeve and applicator equipment supply.
India
Maharashtra and Gujarat beverage markets are absorbing sleeve capacity faster than regional converters can expand, opening procurement windows for foreign equipment suppliers. BIS standards and FSSAI food-contact frameworks regulate substrate composition for domestic and export-bound production. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors are attracting first-stage slitting investments from multinational converters seeking proximity to AB InBev and Coca-Cola bottling partners.
France
Citeo fee structures under extended producer responsibility schemes are reshaping procurement economics for retailer-owned brands in the Île-de-France and Auvergne-Rhône-Alpes regions. ANSM and DGCCRF enforcement of REACH-compliant plasticizer systems is extending qualification timelines for household chemicals applications. Paris Art Label Company exemplifies regional specialists navigating compliance-heavy segments through localized formulation expertise.
Full Container Shrink Sleeves Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational converters commanding sustainability-certification premiums while regional players absorb short-run and seasonal demand. The vendor base organizes into three tiers: integrated polymer-to-sleeve operators, pure-play converting specialists, and equipment-integrated solution providers. Consolidation pressure is accelerating through M&A activity targeting digital print capabilities and backward integration into resin compounding.
Among North American integrated packaging conglomerates, Berry Global and Avery Dennison occupy positions exemplifying polymer-platform breadth and adhesive-technology differentiation respectively. Fuji Seal International anchors the Asia-Pacific equipment-integrated archetype, representing the convergence of sleeve production and applicator manufacturing that limits interchangeability for brand owners. Klöckner Pentaplast sits within the European specialist tier, its German origins aligning with REACH-validated substrate traceability systems that command procurement preference.
| Leading Market Players |
|---|
| Klöckner Pentaplast |
| Hammer Packaging, Inc. |
| Berry Global, Inc. |
| Paris Art Label Company Inc. |
| Macfarlane Group PLC |
| Avery Dennison Corporation |
| Constantia Flexibles |
| CCL Industries |
| Fuji Seal International, Inc. |
| Others |
Supply & Pricing Matrix
APR-designated recyclability certification splits sleeve procurement into premium-validated and commodity-undifferentiated tiers, with certified PETG substrates commanding price premiums from Coca-Cola and PepsiCo sustainability teams while unverified alternatives face margin compression from EPR fee structures in Germany and France. This certification ladder simultaneously reshapes converter capital allocation toward traceability infrastructure and concentrates supply relationships with resin compounders in South Korea and Taiwan.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-grade polyethylene sleeves as local slitting operations absorb regional beverage demand. Three-tier pricing structure across premium, standard, and economy levels differentiates APR-validated PETG from conventional PETG and commodity polyolefin alternatives. Pricing pressure stems from Germany's VerpackG and France's Citeo per-unit compliance costs compressing margins on unverified grades. Private label retailers under EPR schemes exhibit highest price sensitivity; multinational brand owners with sustainability procurement mandates show lowest.
Supply Chain Analysis
India's phased domestic-content mandates for packaging materials are reshaping sourcing patterns for multinational converters seeking proximity to AB InBev and Coca-Cola bottling partners in Maharashtra and Gujarat. PETG pellet production concentrates in South Korea and Taiwan; sleeve converting clusters in the United States, Germany, and China. Raw material dependencies rest on ethylene glycol, terephthalic acid, and specialized plasticizer systems. Single-source vulnerability runs through concentrated PETG resin supply. Distribution runs through converter-direct relationships with beverage bottlers and household chemical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in full container shrink sleeves hinges on substrate certification premiums offsetting EPR compliance costs, with digital print convergence collapsing minimum order thresholds for craft spirits and seasonal SKUs.
For Market Incumbents: Cement APR-designated recyclability credentials through backward integration into resin compounding or exclusive offtake agreements with validated suppliers. Invest in cloud-based artwork management platforms to capture subscription-based design spend from PepsiCo and AB InBev procurement teams. Threat: Fuji Seal equipment-integrated solutions limit sleeve interchangeability and raise switching costs. For New Entrants and Emerging Players: Contract packers serving seasonal and promotional campaigns represent the most penetrable buyer archetype, with run-length flexibility down to 5,000 units enabling digital print convergence without legacy flexo infrastructure. Target craft spirits and regional beverage distributors in India where label capacity lags demand growth. Go-to-market angle: hybrid electrophotographic-flexo presses with rapid changeover capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where digital print capabilities and ECHA-validated substrate traceability systems concentrate procurement preference with multinational brand owners. Long-term viability favors converters with integrated sleeve production and application equipment or validated recyclability credentials. Acquisition target archetype: regional specialists with localized formulation expertise in REACH-heavy segments. Signal to watch: mechanical recycling infrastructure investments by Danone and Nestlé Waters driving floatable polyolefin specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PETG supply secures APR certification and insulates against South Korean pellet volatility. |
| Digital Print Platform Deployment | Hybrid electrophotographic-flexo presses unlock 5,000-unit minimums for craft spirits seasonal SKUs. |
| Cloud-Based Artwork Management Launch | Subscription design services displace standalone graphics houses from PepsiCo value chains. |
| India Slitting Operation Establishment | Proximity to Maharashtra bottlers captures first-mover advantage in capacity-constrained markets. |
| Floatable Polyolefin Formulation Patent | Density below 1.0 g/cm³ aligns with Danone and Nestlé Waters European recycling specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sleeve converter plant managers, beverage procurement leads at Coca-Cola and PepsiCo, ECHA regulatory affairs specialists, and Fuji Seal application equipment engineers with secondary validation from FDA food-contact guidance documents, EFSA migration testing protocols, APR recyclability design guides, and customs trade data on PETG pellet flows. Bottom-up sleeve volume estimates triangulated against top-down packaging spend analysis.
Segment-weighting across polymer chemistry, container geometry, application vertical, and end-user procurement scale drove analytical framework construction over the projection horizon. CAGRs derived from elasticity-adjusted demand modeling incorporating line-speed requirements, regulatory compliance cost pass-through, and substrate substitution dynamics. Industry-specific forecast inputs included steam-to-hot-air tunnel retrofit timelines and EPR fee structure phase-ins.
Underlying measurement precision varies by segment; beverage applications with standardized cylindrical bottles carry tighter precision than household chemicals with aggressive content-sleeve interaction variables. Forecasts reflect assumptions on regulatory enforcement consistency and mechanical recycling infrastructure deployment. Raw material price volatility and REACH Annex XVII plasticizer reclassifications pose revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market