
 Snap Sachets Market | 2026-2036
Snap Sachets Market Size, Share, and Industry Trends Forecast 2026-2036
Snap Sachets Market Analytics
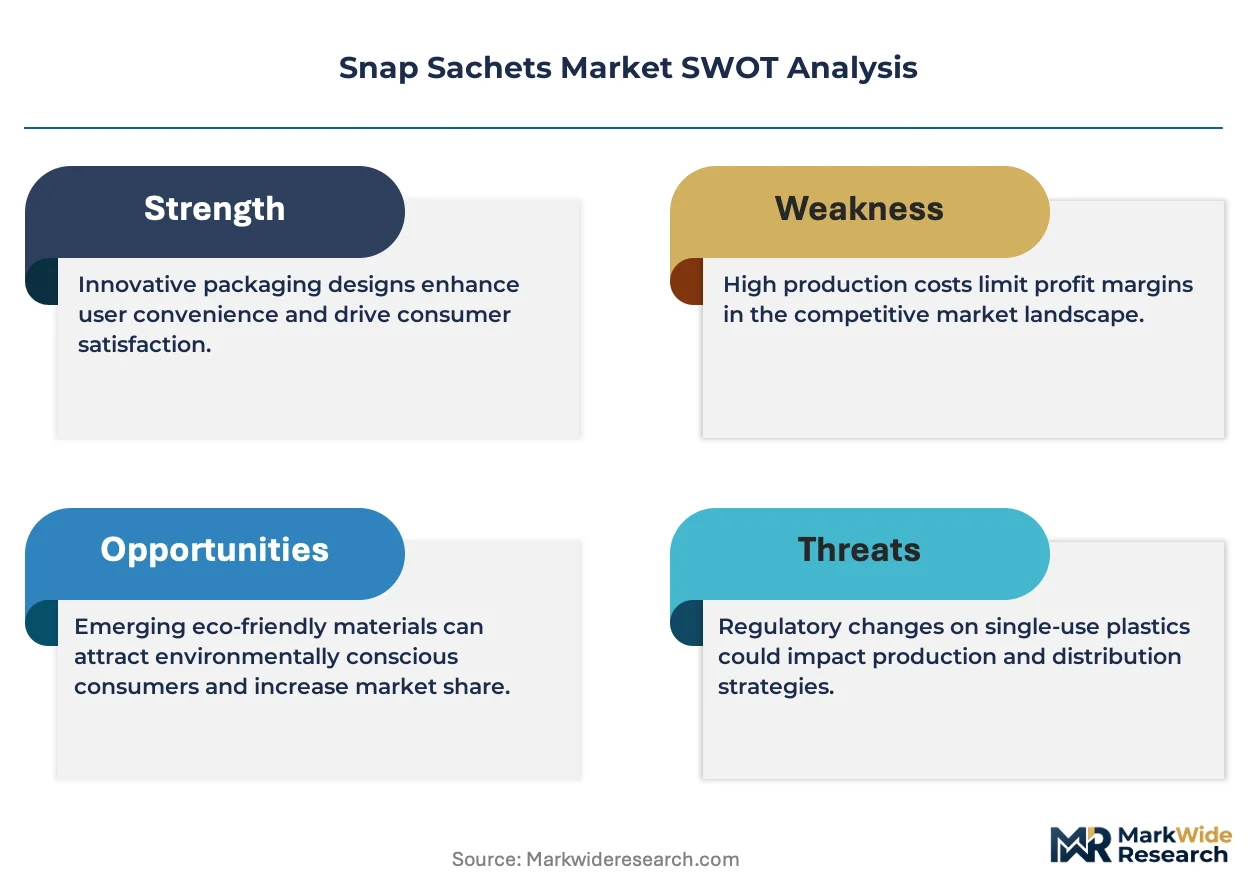
ISO 22000 certification is rotating as the primary gating mechanism for food-contact snap sachet suppliers seeking entry into European retail chains. Berry Global leverages integrated film extrusion and converting assets across North America to sustain cost leadership in high-volume condiment sachets. Amcor Plc anchors its position through pharmaceutical-grade barrier technologies that meet US FDA and EU EMA requirements for unit-dose drug delivery.
Snap sachets are single-dose flexible pouches featuring pre-scored tear notches or snap-seal closures, typically constructed from multilayer laminates of polyethylene, aluminum oxide-coated PET, or oriented polypropylene with sealant layers, designed for controlled dispensing without auxiliary tools. The food and beverage end-use segment dominates current volume, with condiment and liquid applications commanding the widest deployment across quick-service restaurant chains and airline catering. Biodegradable films represent the fastest-growing material category as brand owners respond to extended producer responsibility frameworks in the European Union and select US states, though plastic laminates still capture the majority of margin pools due to established supply chains and proven barrier performance.
The US FDA regulates snap sachets intended for food and pharmaceutical applications through 21 CFR materials compliance, while the EU F-Gas Regulation and REACH restrict certain fluorinated barrier chemistries used in high-performance films. China's SAMR enforces GB standards for food-contact plastics that diverge from Western migration limits, creating separate qualification pathways for multinational converters. Stakeholders must monitor evolving national packaging registry requirements and material substitution timelines to avoid stranded inventory in jurisdictions tightening polymer restrictions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material substitution timelines, forcing converters to requalify entire laminate portfolios before 2030 enforcement windows close.
Growth Catalysts
- Single-serve foodservice formats:Quick-service restaurant chains and airline caterers prioritize portion-controlled condiment dispensing to reduce waste and labor.
- REACH-compliant barrier chemistries:Fluorinated film alternatives meeting EU migration limits unlock pharmaceutical unit-dose applications previously blocked by regulatory uncertainty.
- Biodegradable film R&D:German food processing clusters pilot PLA and PHA laminates under extended producer responsibility frameworks, creating reference sites for compliant scale-up.
Market Restraints
- Aluminum oxide-coated PET supply concentration:Deposition capacity clusters in South Korea and Japan, exposing converters to input bottlenecks during regional trade disruptions.
- Monomaterial barrier performance gaps:Polyethylene-only structures fail to match multilayer oxygen transmission rates required for retort sauces and oil-based dressings.
- GB standard divergence:China's SAMR enforces migration limits stricter than FDA 21 CFR for certain sealant additives, requiring parallel qualification runs for export-bound inventory.
Strategic Opportunities
- Pharmaceutical cold-chain sachets:Temperature-indicating snap seals for unit-dose vaccines address last-mile integrity gaps in sub-Saharan Africa distribution networks.
- EU Green Deal procurement mandates:Public hospital and institutional foodservice tenders now weight biodegradable content at 30% of technical scoring, favoring early-compliant bidders.
- Digital printing convergence:HP Indigo and Xeikon systems enable lot-level traceability QR codes without plate changeover costs, collapsing minimum order quantities for regional sauce brands.
Industry Challenges
- ISO 22000 auditor scarcity:Certification backlogs in Eastern European converting hubs delay supplier qualification for retail chain onboarding.
- Legacy form-fill-seal retrofit costs:Monomaterial sealant layers require jaw temperature and pressure recalibration, stranding capital in equipment less than five years old.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap Sachets Market |
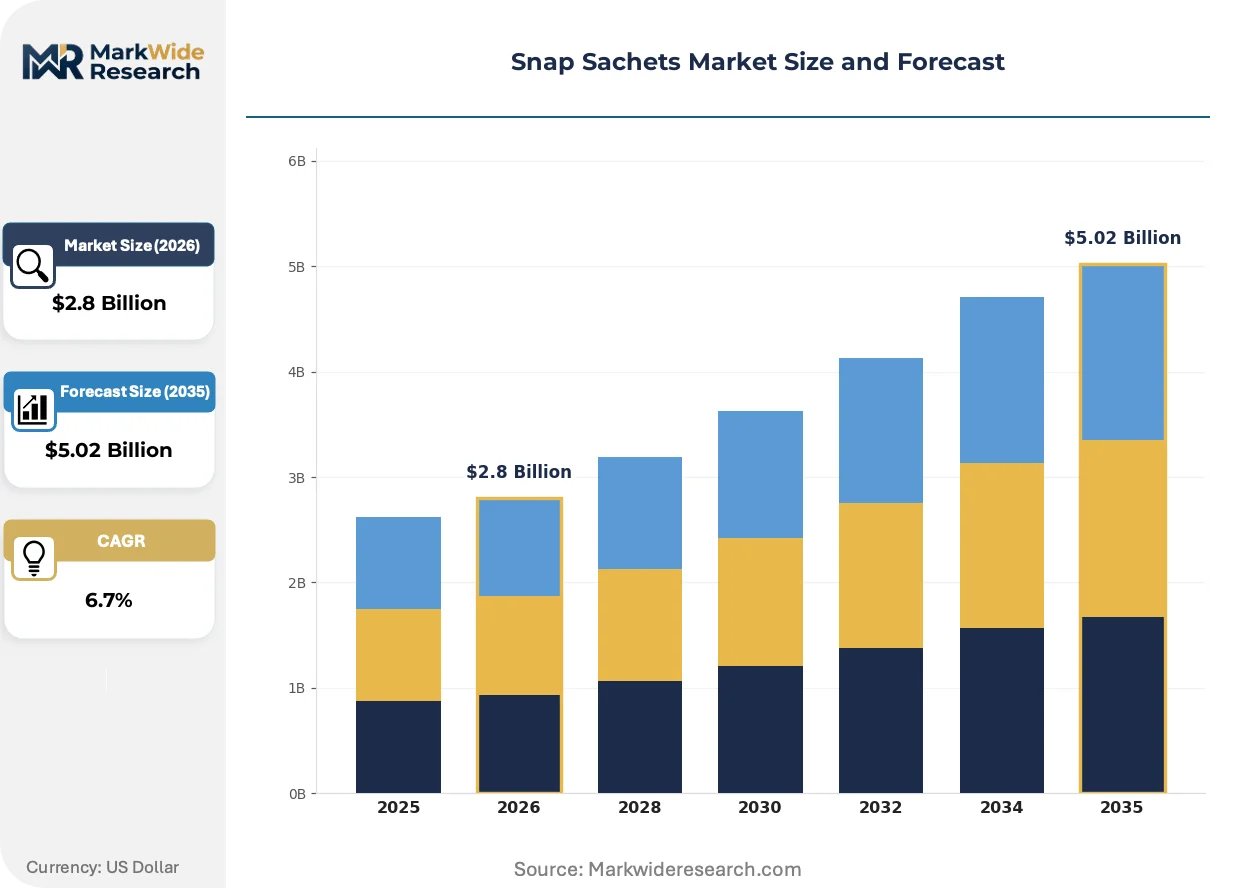
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve, Multi-Serve, Sachet Dispenser, Custom Sachets Material: Plastic, Foil, Paper, Biodegradable Films End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Application: Condiments, Powders, Liquids, Probiotics |
| Companies Covered | Berry Global, Constantia Flexibles, Amcor Plc, ProAmpac, Coveris, Huhtamaki, Glenroy, Winpak, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap Sachets Market Evolving Landscape
Active barrier technologies and regulatory chemistry bans are rewiring material selection protocols, while procurement models compress supplier qualification cycles.
Water-based barrier coatings is decomposing the aluminum oxide deposition bottleneck that has constrained high-volume biodegradable sachet production. European condiment brands in Germany and the Netherlands are piloting these coatings at commercial scale this year. The technology is decomposing the cost premium that previously restricted compostable structures to premium positioning.
The EU F-Gas Regulation is phasing down hydrofluorocarbon production quotas used in certain high-barrier film manufacturing processes. Converters serving pharmaceutical and retort food segments must reformulate or source alternative barrier technologies by mandated step-down dates. German and French packaging suppliers are accelerating partnerships with deposition equipment makers to secure non-fluorinated capacity.
Direct supplier-retailer collaboration is replacing traditional distributor intermediation for compliance-critical categories. Major European grocery chains now mandate material certification documentation at the purchase order level, bypassing wholesale channels that obscured upstream accountability. This pattern is most pronounced in German and Austrian retail systems where private-label condiment sourcing dominates volume.
Snap Sachets Market Segmentation
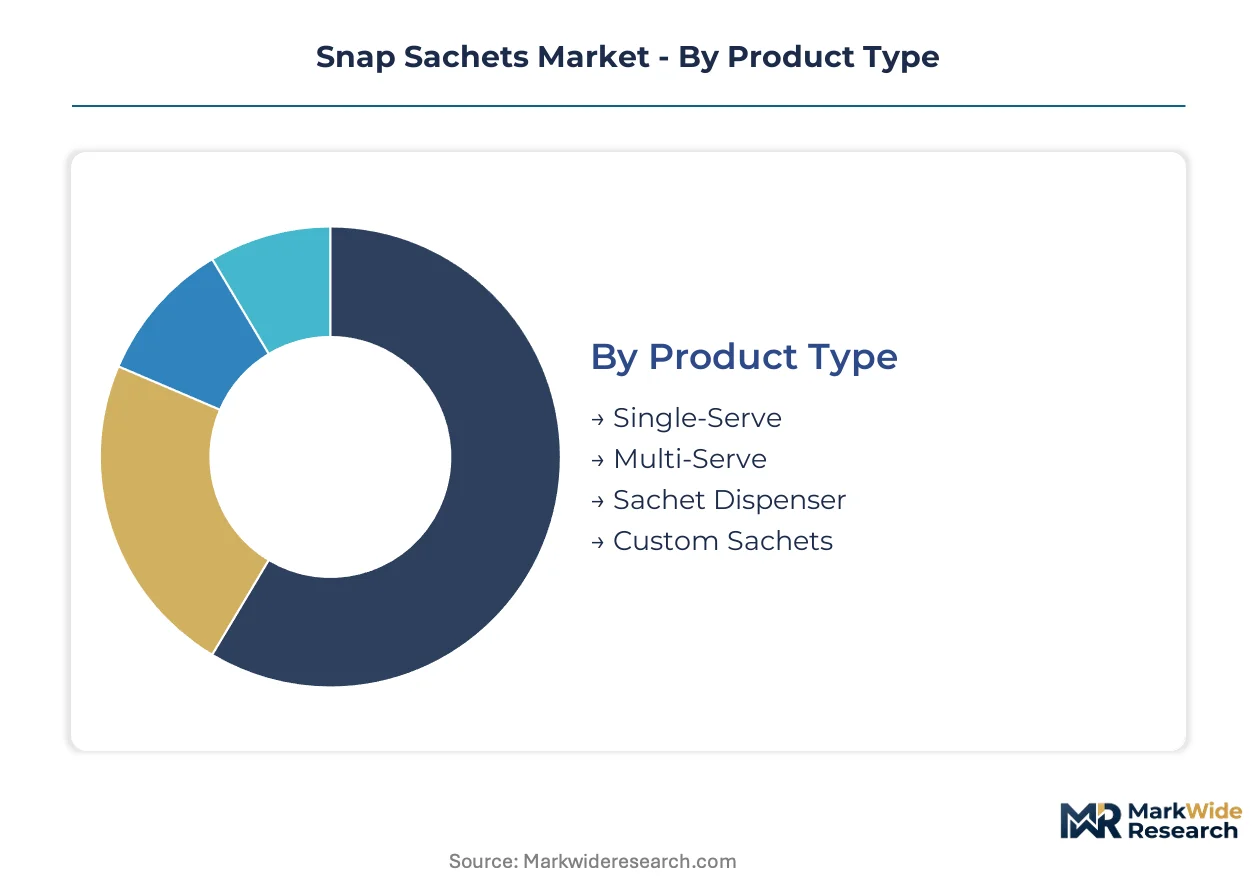
Snap sachet converters configure product portfolios around three axes: regulatory compliance tier, barrier performance requirement, and dispensing mechanism complexity. Material selection and end-use application together determine qualification pathways and margin capture potential.
Product Type:
Single-serve formats dominate domestic foodservice procurement in Germany and the Netherlands, while multi-serve and dispenser systems skew toward export-bound hospitality contracts in Middle Eastern and Southeast Asian markets.
- Single-Serve:Pre-scored tear-notched pouches constructed from multilayer laminates with 5-15ml fill volumes. Quick-service restaurant chains in Germany and airline caterers across the EU mandate these for condiment portion control and hygiene compliance.
- Multi-Serve:Larger-capacity sachets with resealable snap closures, typically 50-200ml. Institutional foodservice operators in Austrian hospitals and Dutch contract catering deploy these for sauce dispensing in high-volume meal preparation environments.
- Sachet Dispenser:Integrated dispensing systems combining refill cartridges with mechanical or sensor-activated delivery. Saudi Arabian and UAE hospitality groups import these for buffet and room-service applications.
- Custom Sachets:Bespoke geometries and printed designs for brand differentiation. Regional sauce brands in Italy and Spain leverage digital printing partnerships to collapse minimum order quantities.
Single-serve commands the established base. The steepest expansion runs through custom sachets as digital printing collapses order minimums.
Material:
Cost tiers separate commodity laminates from certified biodegradable structures, with mid-tier foil hybrids capturing pharmaceutical and retort food applications requiring oxygen barrier performance.
- Plastic:Polyethylene and oriented polypropylene laminates with sealant layers, still capturing majority margin pools due to established extrusion infrastructure and proven barrier performance. FDA 21 CFR and EU 10/2011 compliance documentation is standard.
- Foil:Aluminum-laminated structures for high-barrier pharmaceutical and retort sauce applications. German converters face ECHA scrutiny on fluorinated adhesive chemistries under REACH restrictions.
- Paper:Fiber-based substrates with polymer barrier coatings for dry powder and solid dose applications. French personal care brands pilot these under EU Green Deal procurement weighting.
- Biodegradable Films:PLA and PHA laminates qualifying for industrial composting certification. German food processing clusters pilot these under extended producer responsibility frameworks, creating reference sites for scale-up.
Plastic laminates anchor volume. Biodegradable films are climbing the fastest as EPR frameworks tighten compliance timelines.
End User:
Application maturity varies sharply: food and beverage represents established, price-competitive volume, while pharmaceuticals demands qualification-intensive, premium-positioned supply relationships.
- Food & Beverage:Dominant volume segment spanning condiment, sauce, and liquid packaging. EU F-Gas Regulation and REACH compliance requirements are reshaping material selection for retort applications.
- Personal Care:Single-dose serum and lotion sachets for hospitality amenity programs. Italian and French cosmetics brands drive specification toward premium tactile finishes.
- Pharmaceuticals:Unit-dose drug delivery requiring US FDA and EU EMA barrier validation. Temperature-indicating snap seals address cold-chain integrity gaps in sub-Saharan Africa distribution networks.
- Household Products:Detergent and cleaning agent sachets, concentrated formats reducing shipping weight. German retail chains weight biodegradable content in private-label tender scoring.
Food and beverage holds the volume base. Pharmaceuticals shows the steepest margin expansion as cold-chain applications multiply.
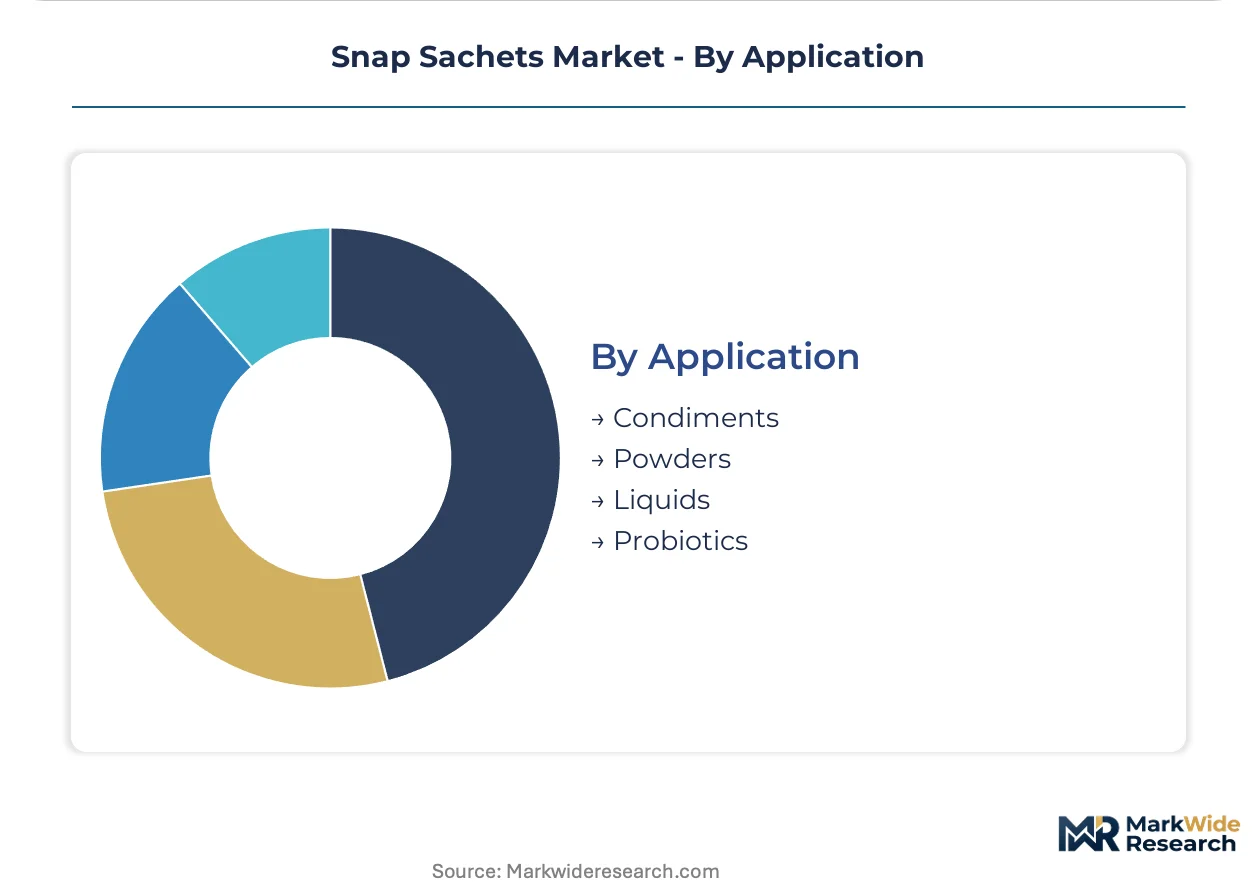
Application:
Fill viscosity and oxygen sensitivity dictate laminate architecture, with liquid and probiotic applications demanding the most sophisticated barrier engineering.
- Condiments:Ketchup, mustard, and mayonnaise sachets in 10-20ml formats. Quick-service restaurant chains specify portion-controlled dispensing to reduce waste and labor.
- Powders:Instant beverage and supplement sachets with moisture barrier requirements. Less demanding barrier specifications enable paper substrate trials.
- Liquids:Oil-based dressings and sauces requiring oxygen and light barrier performance. Monomaterial polyethylene structures fail to match multilayer transmission rates, constraining substitution.
- Probiotics:Live culture preservation demanding ultra-low oxygen transmission and humidity control. Pharmaceutical-grade validation requirements limit qualified supplier pools.
Condiments represent the established volume anchor. Probiotics is gaining share fastest as live-culture preservation requirements multiply qualified supplier premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and airline caterers in Germany concentrate procurement authority for single-serve condiment formats. Hospital foodservice operators in Austria and the Netherlands drive multi-serve dispenser adoption. Pharmaceutical distributors across Western Europe specify cold-chain snap sachets for unit-dose vaccines.
Germany
Food processing clusters in Lower Saxony and Bavaria pilot PLA and PHA laminates under extended producer responsibility frameworks. The EU Packaging and Packaging Waste Regulation compresses material substitution timelines for converters in these regions. Berlin-based retail chains now mandate ISO 22000 certification documentation at purchase order level, bypassing wholesale intermediaries.
United States
Quick-service restaurant chains specify portion-controlled condiment dispensing to reduce waste and labor costs across franchise networks. FDA 21 CFR materials compliance governs food-contact snap sachets, while US EPA frameworks influence biodegradable film procurement in select states. Integrated film extrusion and converting assets sustain cost leadership positions for high-volume producers serving domestic foodservice.
China
SAMR enforces GB standards for food-contact plastics that diverge from Western migration limits, creating separate qualification pathways for export-bound inventory. The country's national packaging regulator monitors evolving polymer restrictions that affect laminate portfolio planning. Yangtze River Delta converting hubs face certification backlogs as ISO 22000 auditor scarcity delays supplier qualification for retail chain onboarding.
France
Public hospital tenders now weight biodegradable content at 30% of technical scoring under EU Green Deal procurement mandates. ANSM oversight extends to pharmaceutical unit-dose applications requiring barrier validation. Lyon and Paris packaging suppliers accelerate partnerships with deposition equipment makers to secure non-fluorinated capacity ahead of F-Gas Regulation step-down dates.
Japan
Aluminum oxide-coated PET deposition capacity clusters expose converters to input bottlenecks during regional trade disruptions. METI guidelines influence barrier technology selection for retort sauce applications. Osaka-based hospitality groups import sachet dispenser systems for buffet and room-service deployments across Southeast Asian affiliate properties.
Snap Sachets Market Competitive Landscape
Player mix skews toward integrated multinational converters with captive film extrusion assets and regional specialists serving compliance-intensive pharmaceutical segments. Tiered competitive structure separates scale-driven commodity producers from certification-heavy barrier technology suppliers. Two dominant archetypes occupy distinct positions: integrated converters leveraging backward integration into polymer supply, and pharmaceutical-grade specialists anchoring premium positioning through regulatory validation. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for biodegradable film R&D scale-up.
Among North American integrated converters, Berry Global and Winpak occupy positions exemplifying scale-driven cost leadership archetypes. Amcor Plc represents the pharmaceutical-grade barrier technology specialist tier, anchoring premium positioning through regulatory validation across US FDA and EU EMA requirements. Constantia Flexibles sits within the European compliance-focused specialist category, serving foodservice and hospitality procurement systems with material certification documentation.
| Leading Market Players |
|---|
| Berry Global |
| Constantia Flexibles |
| Amcor Plc |
| ProAmpac |
| Coveris |
| Huhtamaki |
| Glenroy |
| Winpak |
| Sealed Air |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, creating tiered access where certified converters command premium positioning in German retail chains while uncertified competitors face margin compression from wholesale bypass.
Pricing Analysis
Cost-plus contracts with ethylene and propylene indexation dominate converter-buyer agreements in North American foodservice. Pricing stratifies across pharmaceutical-grade barrier laminates, standard multilayer condiment structures, and economy polyethylene-only formats. Cost compression in biodegradable film tiers is intensifying because PLA and PHA resin supply lags demand expansion. Quick-service restaurant chains exhibit highest price sensitivity, while pharmaceutical distributors accept premium positioning for cold-chain validation.
Supply Chain Analysis
Aluminum oxide deposition capacity clustering in South Korea and Japan exposes converters to input bottlenecks during regional trade disruptions. Raw material sourcing draws from Saudi Arabian ethylene crackers, US Gulf Coast polypropylene facilities, and Thai biopolymer pilot plants. Single-source vulnerability concentrates in high-barrier coating chemistries. Distribution runs through integrated multinational converters with captive film extrusion assets and regional specialists serving compliance-intensive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified barrier technology capabilities are scarce relative to procurement demand, with ISO 22000 auditor backlogs and deposition equipment lead times creating defendable positions for early-compliant suppliers.
For Market Incumbents: Fortify backward integration into polymer supply to secure resin access during biopolymer transition periods. Add deposition capacity partnerships in France and Germany ahead of F-Gas Regulation step-downs. Channel control through direct retailer collaboration replaces distributor intermediation, capturing procurement documentation requirements. For New Entrants and Emerging Players: Certification fast-tracks through German food processing cluster pilot programs unlock reference site status for PLA and PHA laminate scale-up. White-space concentration sits in pharmaceutical cold-chain sachets for sub-Saharan Africa distribution, where temperature-indicating snap seals address last-mile integrity gaps. Digital printing partnerships enable lot-level traceability without plate changeover costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable film extrusion and deposition equipment, favoring asset-light specialists with certification relationships over greenfield capacity builds. Acquisition targets include European compliance-focused converters with EPR framework positioning. Watch water-based barrier coating commercialization rates as inflection signal for compostable structure cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film R&D Partnership | PLA and PHA laminate scale-up under German EPR frameworks creates reference sites for compliant expansion. |
| Non-Fluorinated Deposition Capacity | French and German suppliers secure barrier equipment ahead of EU F-Gas Regulation mandated step-down dates. |
| Direct Retailer Collaboration | Bypassing wholesale channels captures ISO 22000 documentation requirements at purchase order level. |
| Digital Printing Integration | HP Indigo and Xeikon systems collapse minimum order quantities for regional sauce brand customization. |
| Cold-Chain Validation Investment | Temperature-indicating snap seals address vaccine integrity gaps in sub-Saharan Africa distribution networks. |
Research Methodology
Operator-level perspectives from foodservice procurement directors, converting plant managers, pharmaceutical packaging engineers, and retail category buyers anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, FDA 21 CFR materials compliance databases, ECHA REACH substance restrictions, and customs trade data for laminate import flows. Bottom-up volume builds across product type, material, end user, and application segments were triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across regulatory enforcement timing variations and biopolymer cost curve assumptions. The analytical framework modeled product type, material compliance tier, barrier performance requirement, and dispensing mechanism complexity across the projection horizon. CAGRs were derived from segment-level growth rate synthesis. Key inputs included EU EPR framework adoption schedules and pharmaceutical cold-chain infrastructure deployment patterns.
Underlying assumptions cover regulatory enforcement timelines and biopolymer scale-up curves, with deviation risk concentrated in aluminum oxide deposition capacity expansion and ISO 22000 auditor availability. Practitioners should keep alternative scenarios live as EU Packaging and Packaging Waste Regulation material substitution deadlines and F-Gas Regulation step-down dates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Sachet Packaging Machines Market