
 US Sachet Packaging Market | 2026-2036
US Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Sachet Packaging Market Insights
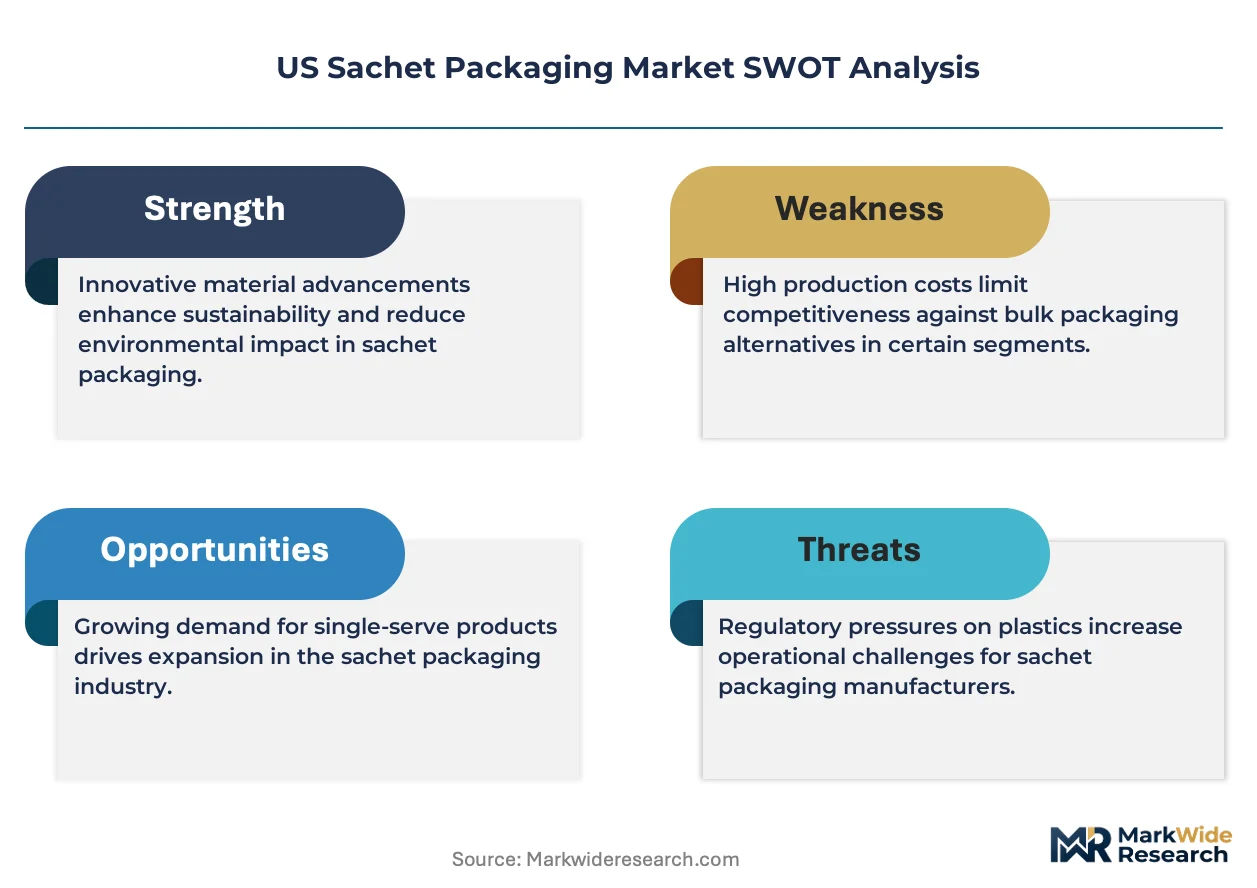
Packaging engineering talent scarcity across the US Midwest is unwinding capacity expansion timelines for several converters. Amcor plc leverages its integrated film extrusion network to sustain material cost advantages in high-volume pharmaceutical sachet programs. ProAmpac competes through specialized retort-compatible laminations that anchor its position in ready-to-eat meal portions. Sonoco Products Company dominates the industrial chemical sachet segment with controlled-atmosphere formats that protect moisture-sensitive agricultural inputs.
US sachet packaging denotes single-dose flexible pouches typically formed from multilayer laminates measuring 5–50 milliliters in fill volume, produced through vertical form-fill-seal or horizontal flow-wrap processes with barrier properties tailored to oxygen and moisture transmission rates. These units serve portion control, sample distribution, and shelf-life extension functions across consumer and industrial supply chains. Plastic laminates lead material demand due to cost scalability, though aluminum composites capture premium pharmaceutical applications where light and oxygen barriers determine product stability. Heat seal closure types occupy the largest share by volume, while tear notch formats gain traction in food service channels where consumer convenience dictates repurchase behavior.
The FDA governs food-contact substance notifications under 21 CFR, while the EPA regulates volatile organic compound emissions from solvent-based adhesive lamination processes that constrain converter site selection and capital planning. OSHA workplace exposure standards for solvent handling further shape operational compliance costs across US production facilities. State-level extended producer responsibility frameworks in California and New York are beginning to mandate recyclability disclosures that will force substrate redesign investments. Stakeholders must monitor how post-consumer recycled content mandates evolve across conflicting federal and state jurisdictions before committing to long-term capital cycles.
Market Dynamics
Single-serve beverage brands are driving format proliferation as convenience packaging penetrates on-the-go consumption occasions, while FDA food-contact material standards simultaneously force substrate redesign cycles across converter networks.
Growth Catalysts
- 21 CFR food-contact notifications:Evolving FDA standards for laminate adhesives and barrier coatings are accelerating substrate innovation investments that differentiate compliant converters from commodity suppliers.
- Ready-to-eat meal portions:Food service channels are expanding sachet adoption for condiment and sauce distribution as portion control requirements intensify in institutional catering contracts.
- Southeastern US manufacturing corridor:Flexible packaging cluster density in Georgia, South Carolina, and North Carolina is reducing logistics costs and shortening converter-to-brand lead times.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for high-volume laminate producers.
- Solvent-based adhesive constraints:EPA volatile organic compound emission limits restrict site selection for new lamination capacity, particularly in non-attainment zones across California and Texas.
- Aluminum foil supply concentration:Domestic foil rolling capacity concentrates among three primary suppliers, creating input bottleneck risk for pharmaceutical-grade barrier laminates.
Strategic Opportunities
- California and New York EPR frameworks:Extended producer responsibility mandates for recyclability disclosures will reward early movers in mono-material substrate development with preferential brand partnerships.
- Industrial chemical sachets:Agricultural input and automotive fluid segments show underpenetrated demand for controlled-atmosphere moisture protection formats.
- Digital printing convergence:Combination of narrow-web flexography and variable-data inkjet enables short-run customization for regional brand launches and promotional sampling campaigns.
Industry Challenges
- Packaging engineering talent scarcity:Midwest converter expansion timelines stretch as polymer science and barrier design expertise concentrates among competing employers in the Southeast.
- Post-consumer recycled content integration:FDA compliance pathways for mechanically recycled polymers in food-contact applications remain unclear, freezing capital commitment to circular substrate lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sachet Packaging Market |
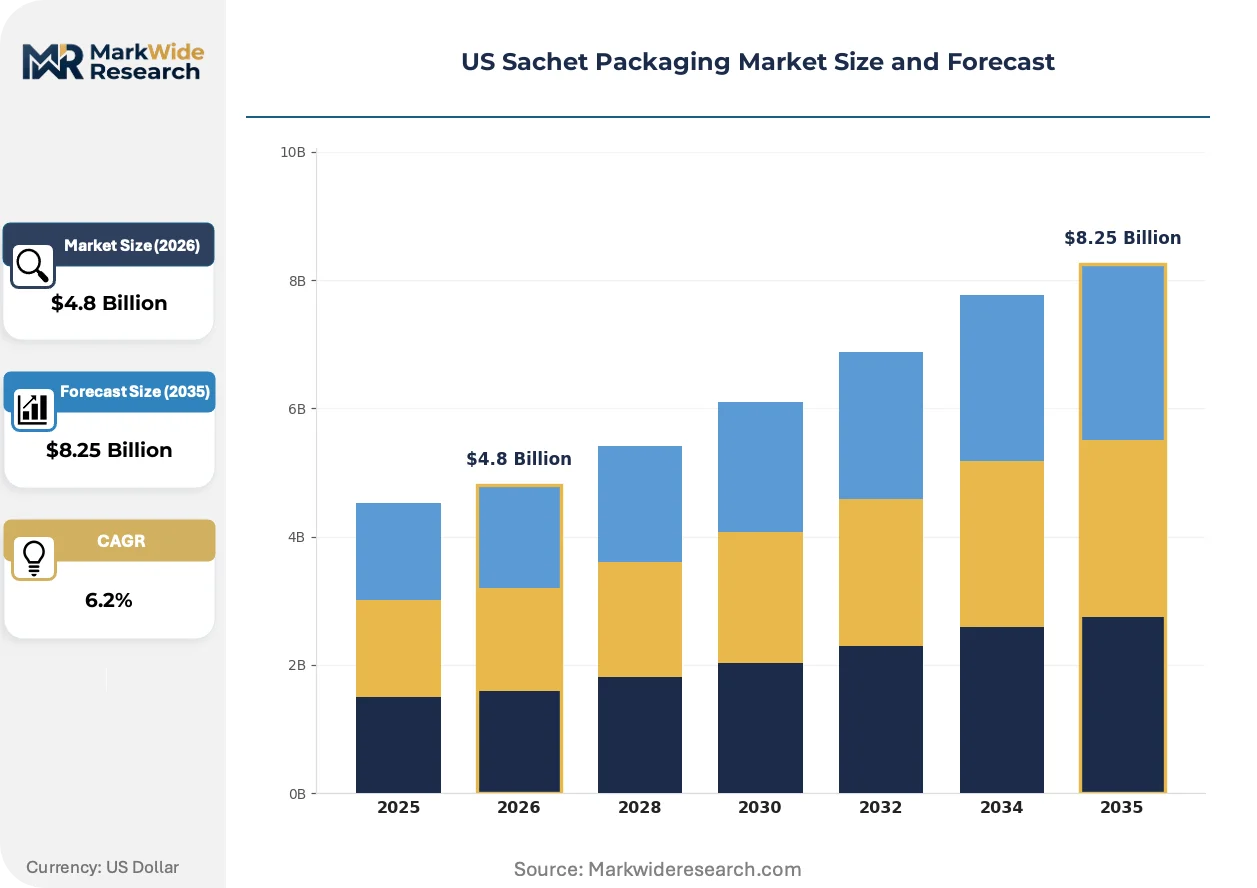
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverage, Personal Care, Pharmaceuticals Material: Plastic, Paper, Aluminum, Composites Closure Type: Zip Lock, Tear Notch, Heat Seal, Pressure Seal End User: Household, Food Service, Retail, Industrial |
| Companies Covered | Amcor plc, Huhtamaki, Constantia Flexibles, Mondi, Graphic Packaging International, LLC, ProAmpac, Sealed Air Corporation, Sonoco Products Company, Berry Global, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sachet Packaging Market Trends and Innovations
Digital printing technologies and mono-material substrate development are converging to reshape converter capabilities, while regulatory pressure on recyclability accelerates format redesign across end-use verticals.
Water-based and UV-curable adhesive systems are replacing solvent-based chemistries in multilayer lamination to meet EPA emission thresholds. Mid-tier converters in Ohio and Illinois are retrofitting existing lines at compressed capital cycles. This transition is miniaturizing the compliant supplier base as smaller operators exit rather than absorb compliance retrofit costs.
OSHA workplace exposure standards for solvent handling are tightening permissible limits in lamination facilities. Converter operational compliance costs rise with ventilation system upgrades and personal protective equipment protocols. Pharmaceutical sachet programs face the steepest cost adjustments due to cleanroom-grade air handling requirements.
Food service distributors are consolidating procurement authority for condiment and sauce sachets under national contract frameworks. Regional brand fragmentation gives way to centralized purchasing at Sysco, US Foods, and broadline operators. Quick-service restaurant chains in the Southwest demonstrate the most aggressive consolidation pace, pressuring converter margins through volume concentration.
US Sachet Packaging Market Segmentation
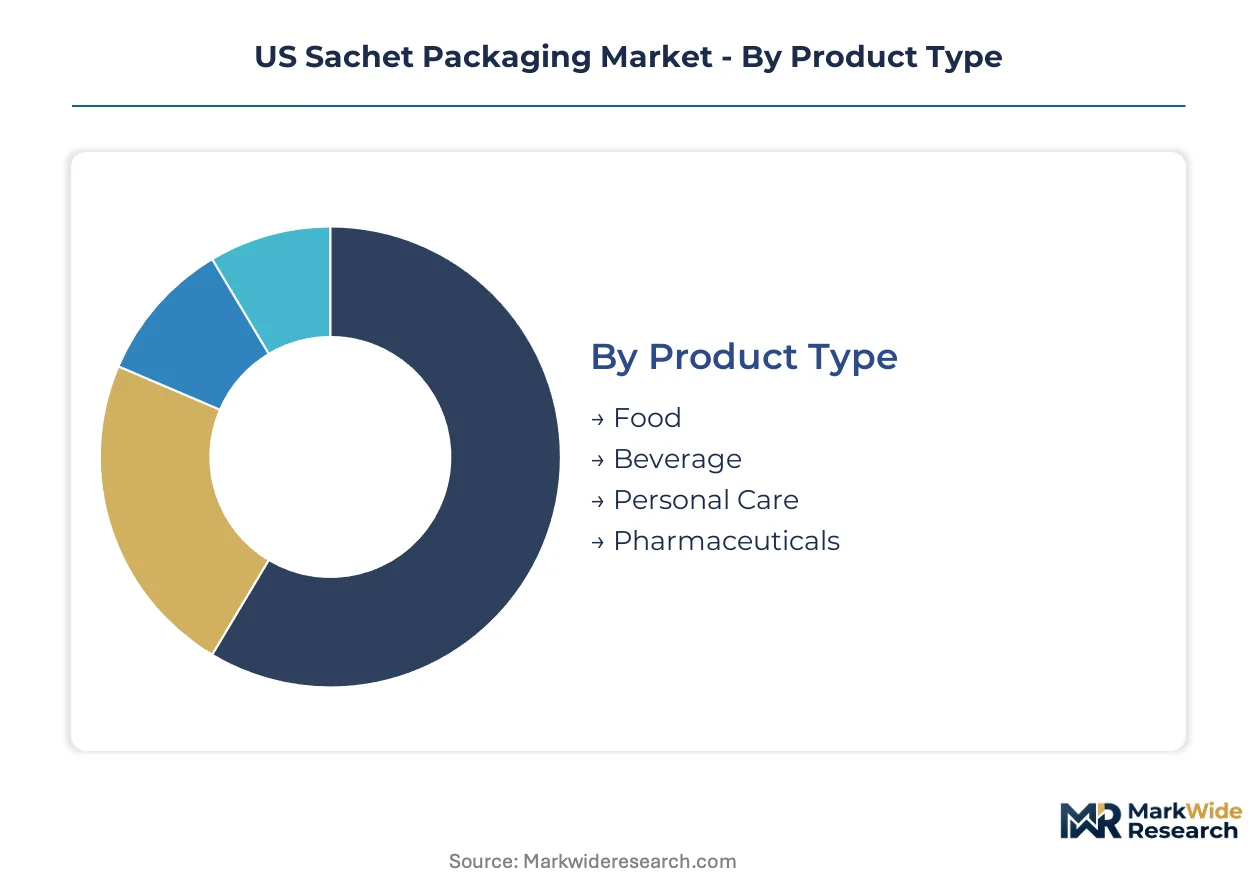
Sachet packaging demand fragments across substrate technologies, closure mechanisms, and end-use channels that each carry distinct regulatory burdens and margin profiles. Understanding these segment boundaries clarifies where converter capital earns differentiated returns versus commodity exposure.
Product Type:
Domestic consumption anchors Food and Beverage demand, while Pharmaceutical sachets serve export-led contract manufacturing for North American and Latin American markets.
- Food:Retort-compatible laminates dominate condiment, sauce, and seasoning portions for quick-service restaurant chains and institutional catering. Demand concentrates in the southeastern manufacturing corridor where converter clusters shorten lead times to Sysco and US Foods distribution networks.
- Beverage:Single-serve powder and liquid concentrates target on-the-go consumption occasions. Powdered drink mixes and electrolyte formulations drive volume, with brands expanding format adoption for gym, travel, and workplace channels.
- Personal Care:Sample-size shampoo, conditioner, and skincare sachets support hotel amenity programs and direct-to-consumer trial distribution. Domestic hospitality procurement dominates, though airline contract manufacturing adds export volume.
- Pharmaceuticals:Unit-dose oral solids and topical applications require aluminum-barrier laminates meeting FDA 21 CFR compliance. Contract packaging organizations in Puerto Rico and domestic facilities supply North American and Caribbean markets.
Food commands the established base. The steepest expansion runs through Pharmaceuticals.
Material:
Cost tier stratification separates commodity substrates from barrier-grade laminates, with regulatory compliance adding premium capture for pharmaceutical-grade materials.
- Plastic:Polypropylene and polyethylene multilayer films lead volume through cost scalability and vertical form-fill-seal compatibility. Petrochemical feedstock volatility compresses margin predictability for high-volume producers.
- Paper:Fiber-based substrates with polymer barrier coatings target sustainability-positioned food service brands. California and New York EPR frameworks accelerate mono-material paper development for recyclability compliance.
- Aluminum:Foil laminates deliver oxygen and light barriers for pharmaceutical stability. Domestic rolling capacity concentrates among three primary suppliers, creating input bottleneck risk.
- Composites:Multilayer plastic-aluminum-paper constructions balance barrier performance with format flexibility. FDA food-contact notification requirements force substrate redesign cycles across converter networks.
Plastic laminates anchor volume leadership. Composites are gaining share fastest in premium pharmaceutical applications.
Closure Type:
Application context dictates convenience requirements, with food service channels driving format innovation while industrial segments prioritize seal integrity over reclosure.
- Heat Seal:Permanent fusion seals dominate high-speed production lines for single-use portions. Cost efficiency and tamper-evidence support broad adoption across food, beverage, and industrial chemical segments.
- Tear Notch:Consumer-facing convenience features gain traction in food service condiment distribution. Quick-service restaurant chains in the Southwest demonstrate aggressive adoption for customer experience differentiation.
- Zip Lock:Reclosure functionality targets multi-dose pharmaceutical and personal care applications. Premium positioning supports margin capture in sample and travel-size formats.
- Pressure Seal:Adhesive-based closures serve low-moisture food and industrial chemical applications. Simplified equipment requirements attract mid-tier converters with compressed capital cycles.
Heat Seal holds the volume base. Tear Notch demonstrates the steepest adoption curve in food service channels.
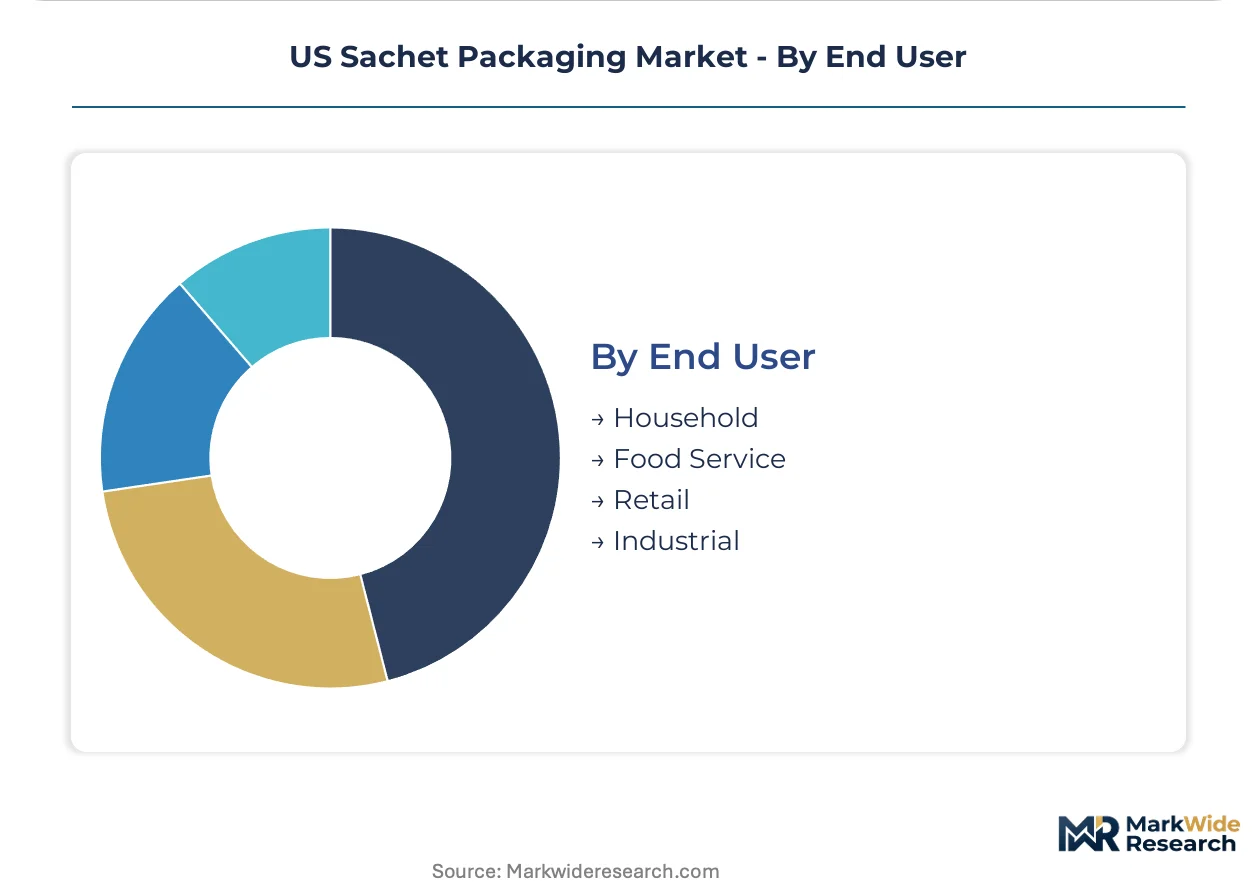
End User:
Customer type concentration shapes procurement power, with national contract frameworks consolidating authority while household channels fragment across retail formats.
- Food Service:National distributors centralize condiment and sauce sachet procurement under multi-year contracts. Converter margins compress through volume concentration at Sysco, US Foods, and broadline operators.
- Retail:Brand-led sampling campaigns and trial-size distribution target grocery, pharmacy, and e-commerce channels. Digital printing convergence enables short-run regional customization.
- Household:Direct consumer purchases concentrate in bulk warehouse clubs and dollar store formats. Price sensitivity favors standard plastic laminates over barrier-grade substrates.
- Industrial:Agricultural inputs, automotive fluids, and chemical additives require controlled-atmosphere moisture protection. Underpenetrated demand in precision agriculture and specialty lubricants offers expansion opportunity.
Food Service captures procurement consolidation benefits. Industrial shows the steepest expansion trajectory in controlled-atmosphere formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern US manufacturing corridor consumes sachet packaging differently than other domestic regions, with food service procurement concentrating around institutional catering networks rather than retail brand fragmentation. California and New York markets prioritize sustainability-positioned substrates under emerging extended producer responsibility mandates. Industrial chemical applications show geographic dispersion across agricultural belts and automotive manufacturing zones.
Southeast
Georgia, South Carolina, and North Carolina host dense flexible packaging clusters that shorten converter-to-brand lead times for Sysco and US Foods distribution networks. FDA 21 CFR food-contact notifications drive substrate redesign investments among regional converters. Atlanta and Charlotte anchor lamination capacity expansion as national food service distributors consolidate procurement authority.
California
Sustainability-positioned food service brands drive mono-material paper substrate development for recyclability compliance. The state's extended producer responsibility framework mandates recyclability disclosures that force substrate redesign investments. Los Angeles and Central Valley converters face compressed margins as petrochemical feedstock volatility intersects with compliance retrofit costs.
Texas
Industrial chemical sachet demand concentrates around agricultural input distribution and automotive fluid packaging. EPA volatile organic compound emission limits restrict new lamination capacity in non-attainment zones, particularly along the Gulf Coast. Houston and Dallas-Fort Worth converters navigate solvent-based adhesive constraints while serving moisture-sensitive agricultural protection formats.
Midwest
Packaging engineering talent scarcity stretches converter expansion timelines as polymer science expertise concentrates among competing employers. OSHA workplace exposure standards for solvent handling tighten operational compliance costs across Illinois, Ohio, and Michigan facilities. Chicago and Detroit industrial corridors see mid-tier operators exit rather than absorb compliance retrofit costs for water-based adhesive transitions.
Northeast
New York's extended producer responsibility framework accelerates recyclability disclosure requirements that reward early movers in mono-material development. Pharmaceutical sachet contract manufacturing concentrates in Puerto Rico and domestic facilities supplying North American markets. Boston and New York Metro clusters face steepest cost adjustments for cleanroom-grade air handling under OSHA ventilation upgrade mandates.
US Sachet Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with material cost advantages separating high-volume laminate producers from regional niche operators. The market structure favors converters with captive film extrusion networks or specialized barrier capabilities over commodity suppliers exposed to resin price volatility. Two strategic archetypes dominate: integrated multinationals with backward control over substrate supply, and mid-tier specialists with retort-compatible or pharmaceutical-grade certifications. Competitive moves concentrate on M&A for geographic coverage and capacity expansion in compliant manufacturing zones.
Among integrated multinationals, Amcor plc and Sonoco Products Company exemplify the scale-driven archetype with material network advantages, while ProAmpac occupies a position within the specialist tier focused on differentiated lamination capabilities. These three entities represent the competitive spectrum from high-volume pharmaceutical programs to controlled-atmosphere industrial formats, with each anchoring distinct margin profiles based on substrate complexity and regulatory compliance depth.
| Leading Market Players |
|---|
| Amcor plc |
| Huhtamaki |
| Constantia Flexibles |
| Mondi |
| Graphic Packaging International, LLC |
| ProAmpac |
| Sealed Air Corporation |
| Sonoco Products Company |
| Berry Global |
| Others |
Pricing and Supply Chain Analysis
Water-based adhesive substitution for solvent-based chemistries is redrawing converter site economics across Ohio and Illinois while compressing capital recovery timelines for compliant operators. This input transition simultaneously concentrates production geography in EPA-attainment zones and widens pricing spreads between retrofitted and legacy facilities.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between national food service distributors and southeastern converters, though spot purchasing persists for short-run promotional campaigns. Three-tier pricing structure across pharmaceutical-grade barrier laminates, retort-compatible food formats, and commodity plastic films reflects FDA certification depth and volume scale. Pricing pressure stems from petrochemical feedstock volatility as polypropylene and polyethylene resin costs fluctuate with crude benchmarks. Household channels through warehouse clubs exhibit the highest price sensitivity, while pharmaceutical contract packaging organizations prioritize barrier performance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast petrochemical complexes to Midwest lamination facilities have intensified margin pressure as container availability constraints persist on domestic rail corridors. Raw material supply draws from domestic polypropylene producers, South Korean polyethylene exporters, and concentrated domestic aluminum foil rolling capacity among three primary suppliers. Single-source vulnerability in pharmaceutical-grade foil laminates creates bottleneck risk for oxygen-barrier applications. Distribution runs through Sysco and US Foods national networks for food service channels, with direct-to-brand relationships dominating pharmaceutical and personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sachet packaging market sits in a cyclical recovery phase as post-pandemic food service normalization restarts institutional procurement cycles. Converter capacity utilization is tightening across the southeastern manufacturing corridor.
For Market Incumbents: Secure captive film extrusion capacity or backward integration into substrate supply to defend margin position against resin price volatility. Prioritize FDA 21 CFR compliance investments that differentiate from commodity converters facing substrate redesign costs. Expand lamination footprint in Georgia and the Carolinas to capture Sysco and US Foods procurement consolidation.
For New Entrants and Emerging Players: Lead with mono-material paper substrate development targeting California and New York EPR recyclability mandates as a white-space entry point. Target industrial chemical sachets for agricultural inputs and automotive fluids where controlled-atmosphere formats remain underpenetrated. Pursue digital printing capabilities for short-run regional brand launches to bypass volume concentration at national distributors.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors converters with specialized barrier certifications over commodity laminate producers. Long-term viability over the next decade hinges on regulatory compliance depth and geographic positioning within EPA-attainment zones. Monitor California and New York EPR implementation timelines as the primary inflection signal for substrate redesign investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene supply insulates Amcor and Sonoco from resin price volatility. |
| Mono-Material Substrate Development | Paper-based barrier formats position ProAmpac for California EPR recyclability compliance. |
| Retort-Compatible Lamination Certification | Specialized thermal processing capabilities anchor food service condiment contracts. |
| Digital Printing Capability Expansion | Variable-data inkjet enables short-run customization for regional beverage brand launches. |
| Industrial Chemical Format Diversification | Controlled-atmosphere sachets capture agricultural input moisture protection demand. |
Research Methodology
Operator-level perspectives from plant managers at flexible packaging converters, procurement leads at Sysco and US Foods, polymer science R&D directors, and FDA regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, Flexible Packaging Association industry reports, EPA emission inventory data, and customs records for resin and aluminum foil trade flows. Bottom-up capacity modeling and top-down demand triangulation from end-use consumption patterns were reconciled to produce volume and value estimates.
Sensitivity analysis tested forecast robustness across petrochemical price scenarios, regulatory implementation timelines, and food service procurement consolidation trajectories. The analytical framework segmented demand by substrate technology, closure mechanism, end-use channel, and regional manufacturing cluster across the projection horizon. CAGRs were derived from segment-level growth drivers including FDA compliance investment cycles, EPR mandate rollout schedules, and digital printing adoption curves. Forecast inputs incorporated converter capacity expansion announcements, resin producer supply plans, and distributor procurement consolidation patterns.
Forecasts assume regulatory continuity in FDA 21 CFR food-contact notifications and EPA VOC emission limits; material policy shifts would require re-modeling of substrate redesign timelines and site selection economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market