
 Japan Sachet Packaging Market | 2026-2036
Japan Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Sachet Packaging Market Insights
Skilled flexographic press operator availability is collapsing across Kansai and Kanto manufacturing belts, forcing converters toward automated digital print sachet lines. Toyo Seikan Group Holdings Ltd. leverages its integrated steel-to-package metallurgy expertise to dominate retort-compatible sachet supply for prepared meals. Rengo Co., Ltd. sustains market presence through captive pulp-to-paperboard operations that stabilize input costs for paper-based pharmaceutical sachets. Takigawa Corporation specializes in precision multi-layer extrusion for moisture-sensitive nutraceutical stick packs.
Sachet packaging denotes sealed, small-format flexible pouches typically fabricated from laminated films or foil-paper composites, with fill volumes under 50 milliliters, designed for single-use dispensing of liquids, powders, or semisolids. Heat-seal layer coextrusion and cold-seal adhesive patterning determine barrier integrity against oxygen and water vapor transmission. Plastic material laminates anchor the largest volume share due to polyethylene terephthalate and oriented polypropylene cost-performance ratios in food and cosmetics applications. Stick form configurations represent the fastest-expanding segment, driven by pharmaceutical unit-dose compliance packaging and on-the-go nutraceutical consumption in Japan's dense urban corridors.
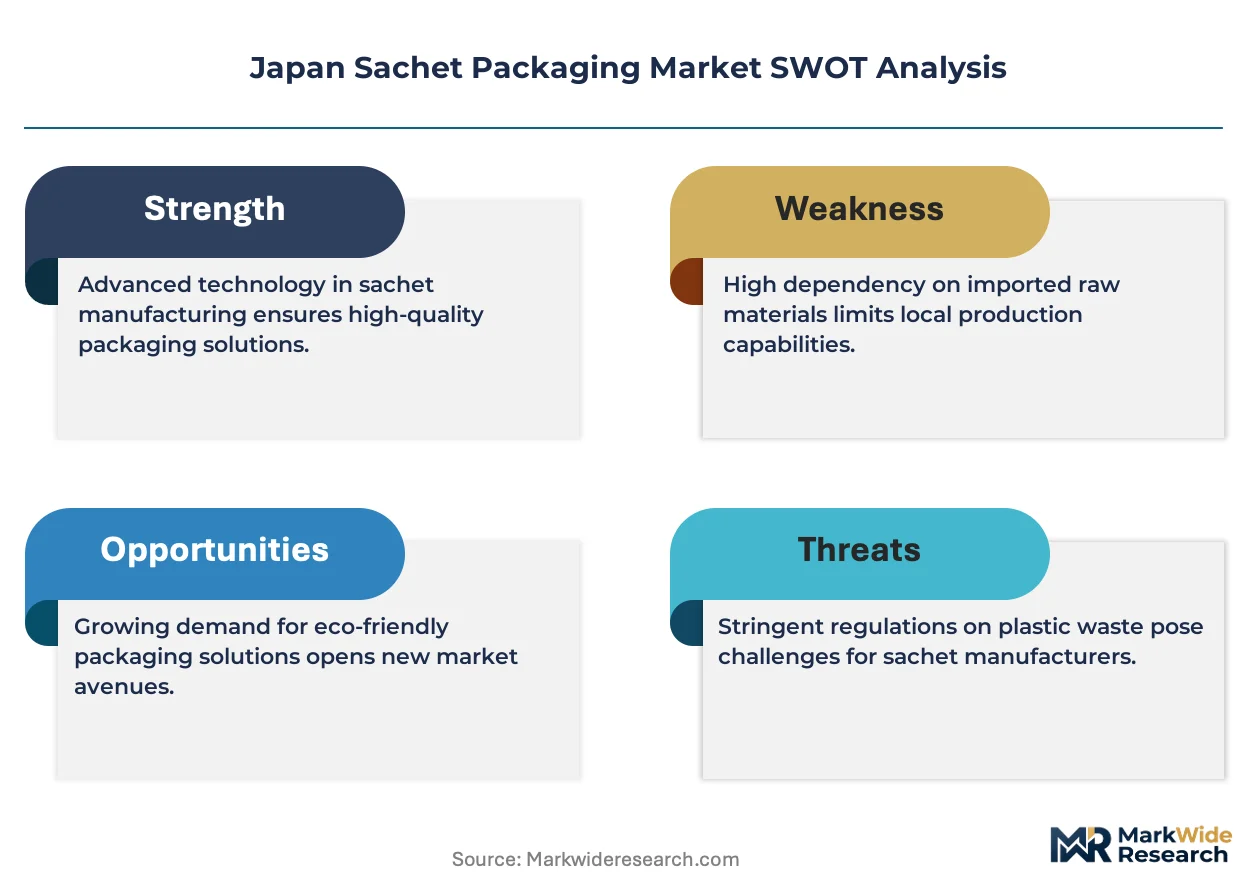
METI's resource circulation policies and the Containers and Packaging Recycling Law enforce minimum recycled content thresholds and extended producer responsibility for flexible packaging waste. PMDA's good manufacturing practice guidelines for pharmaceutical packaging materials mandate extractables testing and batch-level traceability for primary sachet structures. JIS standards for food-contact materials limit specific migration of plasticizers and heavy metals into fatty food simulants. Stakeholders must monitor evolving bioplastic certification pathways under the Japan Bioplastics Association labeling scheme to secure premium positioning ahead of regulatory tightening.
Market Dynamics
Japan's sachet packaging sector faces a structural labor shortage in flexographic press operations across the Kansai and Kanto manufacturing belts, accelerating capital redeployment toward automated digital print lines and reshaping competitive capability requirements.
Growth Catalysts
- Pharmaceutical serialization mandates:The Ministry of Health, Labour and Welfare's unit-dose tracking requirements are expanding compliant stick-pack demand for prescription and over-the-counter medications.
- Retort-compatible metallurgy advances:Integrated steel-to-package expertise enables higher-temperature sterilization protocols for prepared meal sachets serving Japan's aging single-person households.
- Moisture-sensitive nutraceutical formats:Precision multi-layer extrusion technology supports probiotic and enzyme stability in humid subtropical storage conditions.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene terephthalate and oriented polypropylene resin prices fluctuate with naphtha cracking economics, compressing converter margins on long-term supply contracts.
- Recycled content thresholds:METI's resource circulation policies mandate minimum post-consumer recycled plastic in flexible laminates, constraining optical clarity and heat-seal performance in high-barrier applications.
- Aluminum foil substitution pressure:Mono-material polyethylene structures for chemical recycling compatibility threaten multi-layer foil-paper composites in non-retort food segments.
Strategic Opportunities
- Hokkaido and Tohoku regional penetration:Underdeveloped pharmaceutical contract packaging infrastructure in northern prefectures offers greenfield capacity for serialization-compliant stick-pack lines.
- Bioplastic certification pathways:Early alignment with Japan Bioplastics Association labeling standards secures premium positioning ahead of anticipated regulatory tightening on fossil-derived films.
- Cold-chain nutraceutical distribution:Direct-to-consumer subscription models for temperature-sensitive collagen and hyaluronic acid sachets bypass traditional wholesale pharmacy channels.
Industry Challenges
- Extractables testing capacity:PMDA good manufacturing practice guidelines for pharmaceutical packaging materials require specialized analytical chemistry expertise that outstrips current laboratory availability.
- Digital print integration with legacy slitting:Converters face mechanical incompatibility between new inkjet web systems and existing folder-gluer equipment for pharmaceutical folding cartons.
- Batch-level traceability implementation:Serialization database architecture demands IT infrastructure investment that mid-tier converters struggle to finance without equipment vendor partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Sachet Packaging Market |
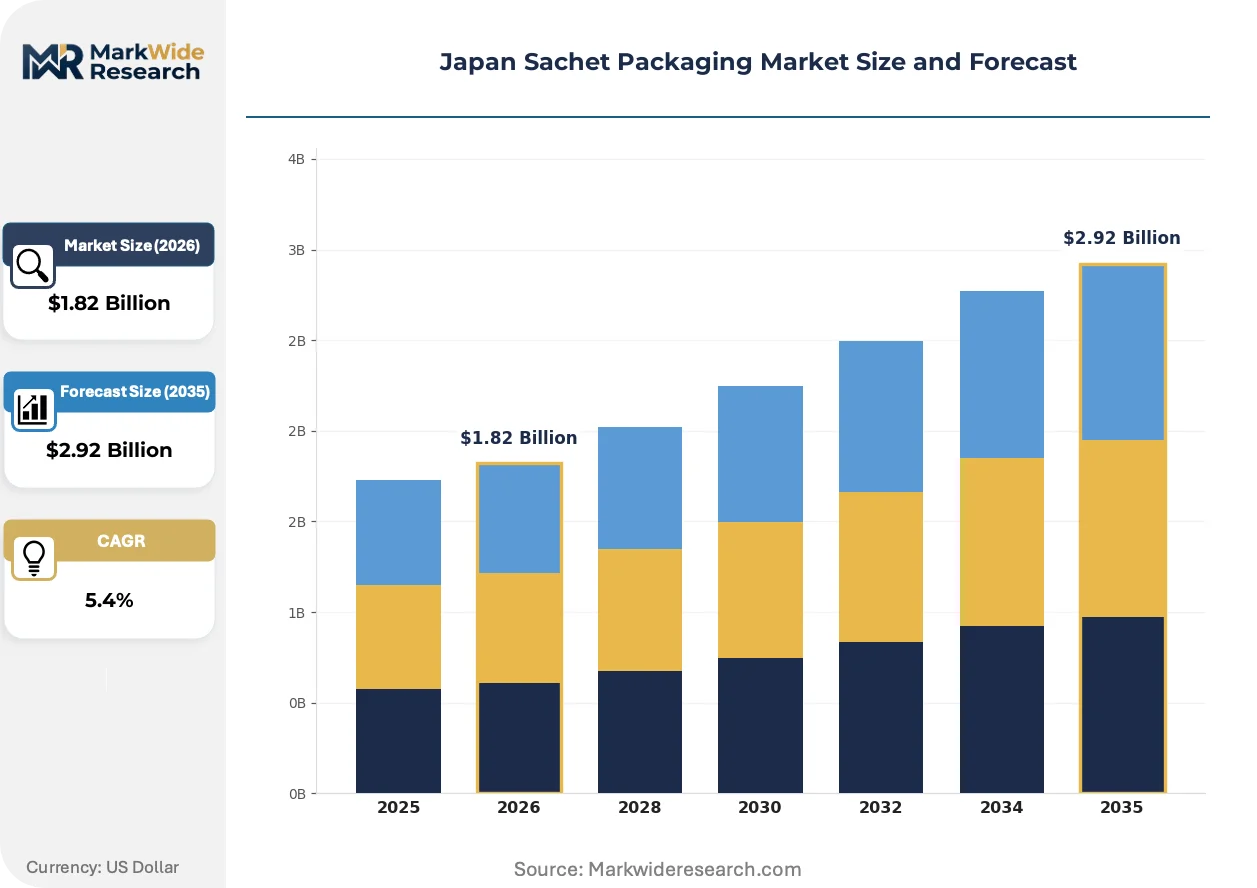
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Pharmaceuticals, Cosmetics, Nutraceuticals Material: Plastic, Paper, Aluminium, Composites Form: Single-serve, Multi-pack, Stick, Pillow End Use Industry: Consumer Goods, Healthcare, Food & Beverage, Industrial Supplies |
| Companies Covered | Amcor Plc, Sonoco Products Company, Toyo Seikan Group Holdings Ltd., Rengo Co., Ltd., Toppan Package Products Co., Ltd., Howa Sangyo Co., Ltd., Sealed Air Corporation, Constantia Flexibles, Takigawa Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Sachet Packaging Market Trends and Innovations
Active digitization of print workflows and regulatory tightening on material circularity are converging to reshape technical capability requirements across Japan's converter base, with automation investments outpacing organic labor supply recovery.
Digital inkjet web printing is fragmenting traditional flexographic dominance in short-run pharmaceutical sachet production. Regional drug manufacturers in the Tokyo-Osaka corridor are adopting print-on-demand workflows for clinical trial materials and niche generic launches. This technology compression enables lot sizes below 10,000 units without plate costs, collapsing minimum economic order quantities and fragmenting volume concentration among large-format rotogravure houses.
METI's Containers and Packaging Recycling Law amendments are tightening extended producer responsibility obligations for flexible packaging waste streams. Brand owners must now fund collection infrastructure proportionate to primary packaging weight placed on market. Pharmaceutical and cosmetics segments are responding with mono-material polyethylene trials to qualify for mechanical recycling streams, accepting compromised oxygen barrier performance in non-critical applications.
Single-serve consumption patterns are rotating demand toward stick-form configurations in dense urban corridors. Young professionals in Tokyo and Osaka are substituting bottled supplements with portable unit-dose nutraceuticals for commuter consumption. This behavioral pivot concentrates volume growth in 5-10 milliliter fill capacities, displacing traditional 30-50 milliliter flat pouch formats in vitamin and mineral categories.
Japan Sachet Packaging Market Segmentation
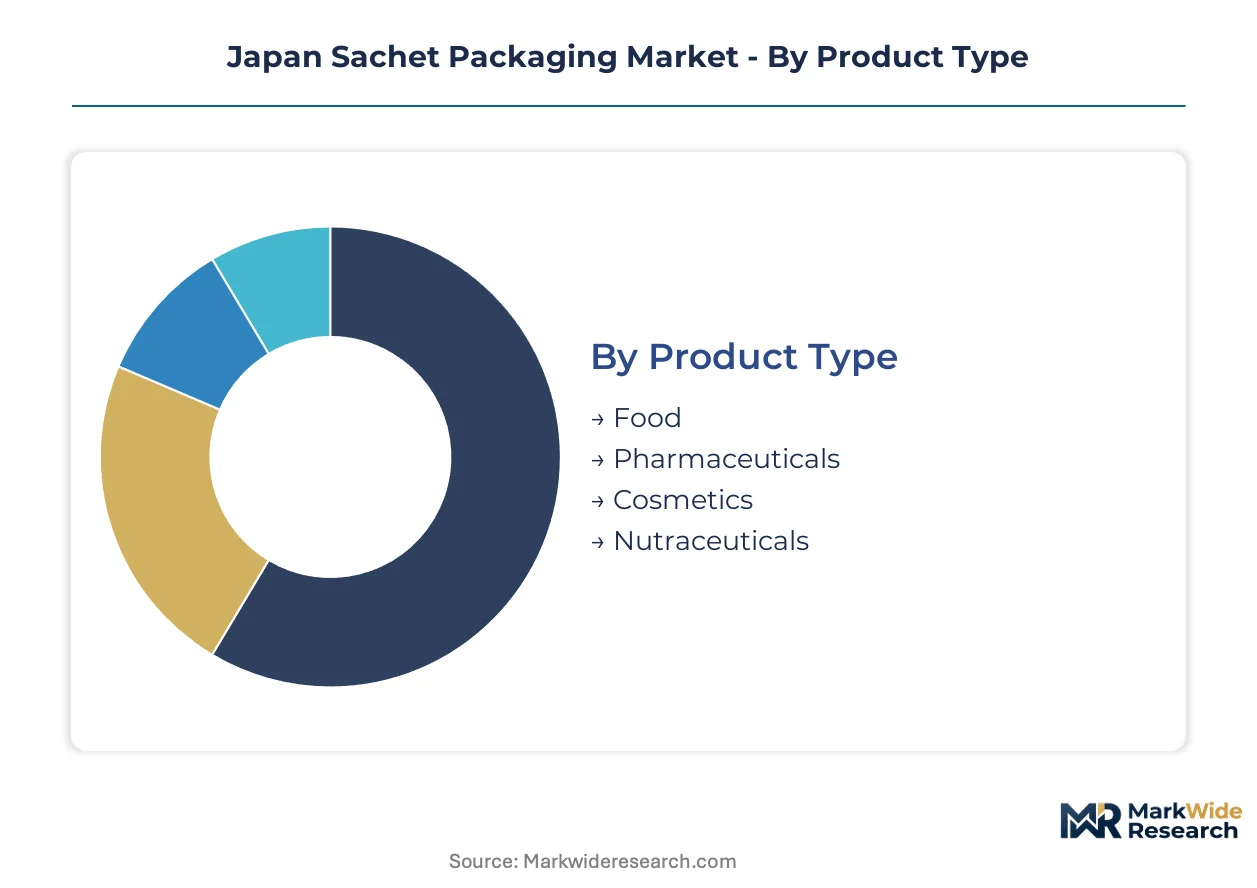
Segmentation reveals how Japan's sachet packaging demand fragments across distinct technical requirements and regulatory environments. Each dimension exposes different competitive dynamics, from pharmaceutical serialization compliance to retort sterilization protocols.
Product Type:
Domestic consumption anchors food and pharmaceutical sachet demand, while cosmetics and nutraceuticals serve export markets across East Asia. Kanto and Kansai manufacturing belts concentrate production for both channels.
- Food:Retort-compatible laminates withstand 121°C sterilization for prepared meal sachets. Tokyo-Osaka corridor converters supply Japan's aging single-person households with shelf-stable rice and curry portions.
- Pharmaceuticals:Unit-dose stick packs incorporate 2D serialization codes per Ministry of Health, Labour and Welfare mandates. Osaka-based contract packagers dominate prescription compliance packaging.
- Cosmetics:Premium essence and serum sachets target duty-free retail at Narita and Kansai International airports.
- Nutraceuticals:Probiotic and collagen stick packs stabilize active ingredients against humid subtropical storage.
Food commands the established base. The steepest expansion runs through pharmaceuticals.
Material:
Cost tiering separates commodity polyethylene applications from high-barrier metallized structures. Raw material volatility drives converter margin pressure across all tiers.
- Plastic:Polyethylene terephthalate and oriented polypropylene laminates balance optical clarity with heat-seal performance. Mono-material trials qualify for mechanical recycling under METI's resource circulation policies.
- Aluminium:Foil-paper composites provide oxygen and moisture barriers for moisture-sensitive pharmaceuticals. Substitution pressure from chemical-recyclable polyethylene structures threatens non-retort food applications.
- Paper:Pharmaceutical folding cartons integrate with sachet blisters for elderly-friendly unit-dose dispensing.
- Composites:Multi-layer extrusions combine ethylene vinyl alcohol and nylon for high-barrier nutraceutical protection.
Plastic laminates anchor volume leadership. Aluminium structures face the sharpest substitution risk.
Form:
Customer type differentiation separates industrial bulk buyers from direct-to-consumer subscription channels. Urban density shapes format preference across consumption occasions.
- Stick:5-10 milliliter fill capacities enable commuter consumption of vitamins and minerals. Young professionals in Tokyo and Osaka substitute bottled supplements with portable unit-dose formats.
- Single-serve:Flat pouches under 50 milliliters serve on-the-go food sauces and condiments. Convenience store chains in dense metropolitan corridors drive replenishment frequency.
- Multi-pack:Bundled configurations reduce per-unit logistics costs for e-commerce pharmacy fulfillment.
- Pillow:Traditional gusseted pouches persist in industrial supply applications with lower barrier requirements.
Stick formats gain share fastest. Pillow configurations stagnate in mature industrial segments.
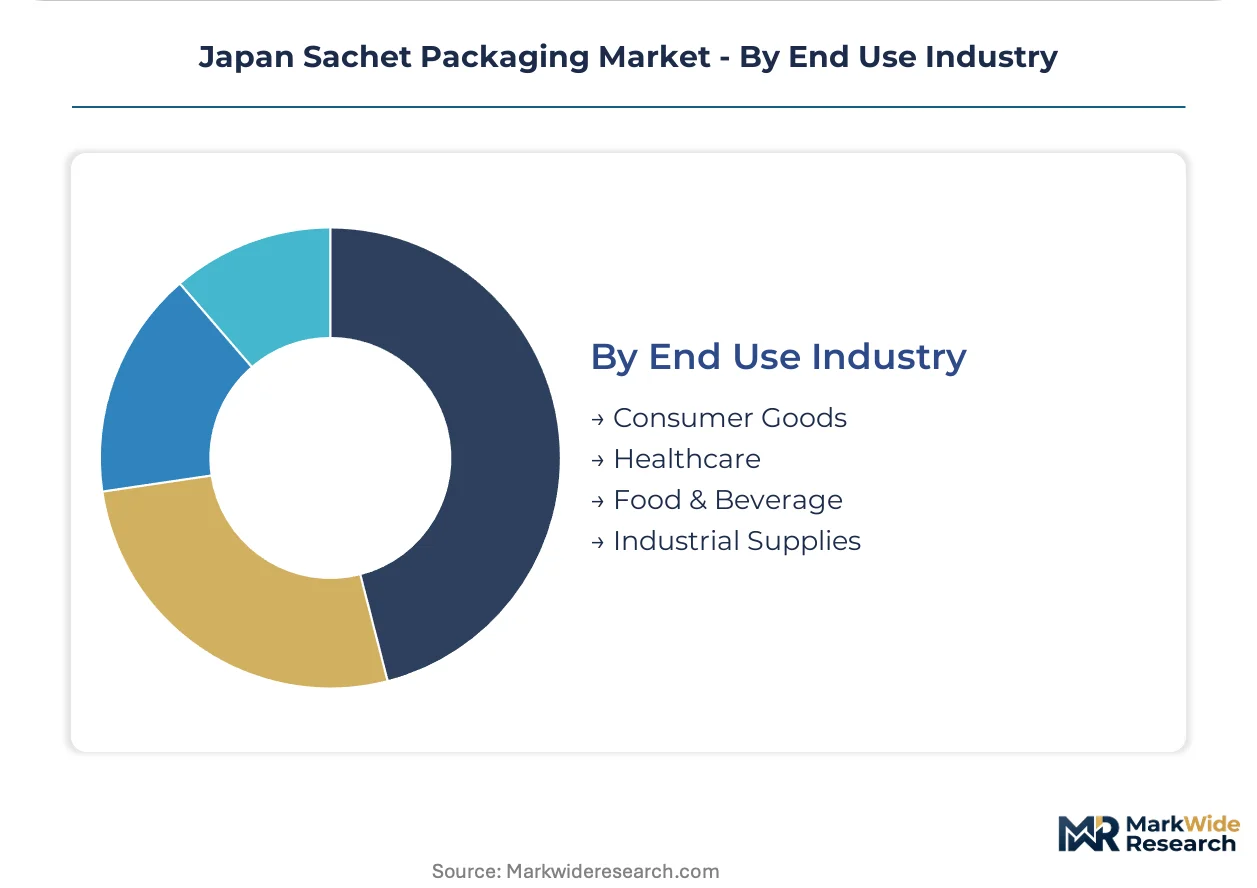
End Use Industry:
Application maturity varies from regulated healthcare to fragmented consumer goods. PMDA oversight creates entry barriers that commodity consumer segments lack.
- Healthcare:Pharmaceutical and medical device sachets require extractables testing and batch-level traceability. PMDA good manufacturing practice guidelines constrain supplier qualification.
- Food & Beverage:Retort meal sachets and beverage concentrates serve aging demographics with limited cooking capacity. JIS food-contact standards limit plasticizer migration into fatty simulants.
- Consumer Goods:Cosmetics and personal care sachets compete on shelf impact in saturated retail environments.
- Industrial Supplies:Lubricant and adhesive sachets tolerate lower barrier specifications than consumer-facing formats.
Healthcare commands premium pricing power. Food and beverage delivers volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's sachet packaging consumption tilts heavily toward pharmaceutical and prepared meal applications, diverging from export-oriented cosmetics demand that dominates peer markets in South Korea and Southeast Asia.
Kanto/Tokyo
Pharmaceutical serialization compliance and aging-single-household meal solutions drive stick-pack and retort sachet demand. METI's resource circulation policies enforce recycled content thresholds on flexible laminates produced in the corridor. Tokyo-based contract packagers dominate prescription unit-dose packaging for the Ministry of Health, Labour and Welfare's track-and-trace mandates.
Kansai/Osaka
Osaka anchors nutraceutical stick-pack production for humid-climate probiotic stability. PMDA good manufacturing practice guidelines constrain supplier qualification for primary pharmaceutical sachet structures. Sakai and Amagasaki manufacturing belts concentrate multi-layer extrusion capacity for moisture-sensitive enzyme formulations.
Chubu/Nagoya
Automotive supplier networks spill over into industrial adhesive and lubricant sachet demand. JIS food-contact standards limit plasticizer migration into fatty simulants for local soy sauce and condiment processors. Toyota-adjacent packaging converters supply just-in-time logistics for manufacturing consumables.
Kyushu
Fukuoka's pharmaceutical cluster generates serialization-compliant contract packaging demand for generic drug exports. The region's subtropical humidity accelerates moisture-barrier specification requirements for nutraceutical distribution. Kitakyushu industrial zones host specialty chemical sachet converters serving semiconductor fabrication supply chains.
Hokkaido and Tohoku
Underdeveloped pharmaceutical contract packaging infrastructure creates greenfield opportunities for serialization-compliant capacity. Cold-chain requirements for temperature-sensitive collagen and hyaluronic acid products favor direct-to-consumer subscription models. Sapporo and Sendai logistics hubs enable bypass of traditional wholesale pharmacy channels.
Japan Sachet Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with metallurgy-to-package and pulp-to-paperboard backward integration distinguishing the upper layer from commodity converters. The mid-market fragments across regional pharmaceutical contract packagers and food-service laminators. Two strategic archetypes dominate: steel-industry descendants with retort metallurgy expertise, and paper-industry survivors with captive pulp supply. Competitive moves concentrate on automation redeployment to offset flexographic operator shortages, and mono-material polyethylene trials to qualify for METI's mechanical recycling streams.
Among Japan-based integrated groups, Toyo Seikan Group Holdings Ltd. and Rengo Co., Ltd. exemplify the metallurgy and pulp vertical-control archetypes respectively, while Takigawa Corporation occupies a position within the precision extrusion specialist tier. These three anchors illustrate how domestic competitive advantage derives from upstream material command rather than downstream brand ownership.
| Leading Market Players |
|---|
| Amcor Plc |
| Sonoco Products Company |
| Toyo Seikan Group Holdings Ltd. |
| Rengo Co., Ltd. |
| Toppan Package Products Co., Ltd. |
| Howa Sangyo Co., Ltd. |
| Sealed Air Corporation |
| Constantia Flexibles |
| Takigawa Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Tokyo-Osaka corridor converters shapes both supply concentration and price floors for pharmaceutical stick-packs, with serialization-compliant lines commanding premium positioning over commodity food laminates.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical sachet supply, insulating converters from naphtha cracking volatility while spot pricing prevails in food-service laminates. Three-tier pricing structure across premium serialization-compliant, standard retort-compatible, and economy mono-material tiers reflects certification investment and barrier performance. Cost compression in standard-tier laminates is intensifying because METI's recycled content mandates degrade optical clarity and heat-seal consistency. Generic drug manufacturers exhibit highest price sensitivity, while cosmetics brand owners absorb premiums for duty-free retail packaging.
Supply Chain Analysis
Inventory cycles for polyethylene terephthalate and oriented polypropylene resins stretch 8-12 weeks, tethering converter margins to petrochemical feedstock timing. Raw material sourcing draws from South Korean resin producers, domestic naphtha crackers, and Chinese additive suppliers. Single-source vulnerability concentrates in specialized cold-seal adhesive patterning equipment from German and Italian OEMs. Distribution runs through pharmaceutical contract packagers in Osaka and Tokyo, with direct-to-consumer subscription channels bypassing traditional wholesale pharmacy networks for nutraceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in extractables testing and serialization database architecture are expanding faster than base sachet production, creating recurring-revenue layers that outpace hardware margins.
For Market Incumbents: Compound defensive positioning through backward integration into metallized film substrates and captive pulp supply for pharmaceutical paperboard. Aluminum foil substitution pressure from mono-material polyethylene trials threatens multi-layer composite margins. Prioritize automation redeployment to offset Kansai flexographic operator shortages. For New Entrants and Emerging Players: Differentiate on cold-chain nutraceutical distribution capabilities for Hokkaido and Tohoku greenfield capacity. Underdeveloped pharmaceutical contract packaging infrastructure in northern prefectures offers the most penetrable white space. Pursue direct-to-consumer subscription models bypassing traditional wholesale channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision multi-layer extrusion specialists with PMDA qualification track records. Long-term viability hinges on regulatory compliance capability rather than commodity scale. Watch bioplastic certification pathway acceleration under Japan Bioplastics Association standards as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization-Compliant Capacity Expansion | Pharmaceutical contract packagers in Osaka secure Ministry of Health, Labour and Welfare mandate compliance. |
| Mono-Material Polyethylene Trials | Converters qualify for METI mechanical recycling streams despite compromised oxygen barrier performance. |
| Digital Print Line Automation | Kanto manufacturers offset Kansai flexographic operator shortages with inkjet web system deployment. |
| Cold-Chain Distribution Partnership | Nutraceutical brands enable direct-to-consumer collagen and hyaluronic acid subscription fulfillment. |
| Bioplastic Certification Alignment | Early adopters secure premium positioning ahead of anticipated fossil-derived film regulatory tightening. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with flexographic press operators, pharmaceutical contract packaging executives, and METI regulatory affairs specialists; and secondary validation through PMDA good manufacturing practice filings, JIS food-contact standard revisions, and Japan Bioplastics Association certification databases. Bottom-up volume modeling triangulated against top-down converter capacity assessments across Kanto, Kansai, and Chubu manufacturing belts.
Across the analysis window, forecasts segmented by product type, material tier, form configuration, and end-use industry captured differential growth trajectories. CAGRs derived from elasticity-adjusted demand projections incorporated pharmaceutical serialization mandate implementation pace and retort meal single-household consumption patterns. Scenario weighting reflected petrochemical feedstock volatility and labor automation substitution curves.
The analysis sits within stated boundaries; outcomes outside sustained METI policy enforcement or PMDA qualification timelines would require recalibration. Forecasts reflect documented assumptions regarding serialization compliance adoption and bioplastic certification penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
North America Sachet Packaging Market