
 India Sachet Packaging Market | 2026-2036
India Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Sachet Packaging Market Insights
Western India's flexible packaging cluster is broadening output for single-serve pouches serving price-sensitive consumers. Uflex Limited leverages backward integration into film extrusion to control resin costs across its Gujarat and Noida plants. Mondi Group anchors European technical standards within Indian operations, competing on barrier specifications for pharmaceutical sachets. Constantia Flexibles specializes in aluminum-laminate structures for oral rehydration salts, dominating hospital procurement channels.
Sachet packaging denotes sealed, small-format flexible containers typically holding 1–20 milliliters of liquid, powder, or semi-solid product, formed from multi-layer films comprising polyethylene, polyester, or aluminum foil through form-fill-seal or pre-made pouch filling processes. These units enable affordable unitization for low-income consumers while preserving shelf stability against moisture and oxygen ingress. The food segment leads volume throughput, driven by spice and sauce sachets distributed through kirana stores, while the pharmaceutical category commands premium margins due to stringent barrier requirements for effervescent and pediatric doses. Plastic materials occupy the dominant share by tonnage, though paper-based alternatives are gaining traction in personal care trial packs as brands respond to Extended Producer Responsibility obligations.
BIS mandates migration limits for food-contact plastics under IS 9833, while FSSAI enforces labeling and shelf-life declarations that shape sachet dimensions and print area requirements. The Plastic Waste Management Rules impose EPR targets that push converters toward mono-material designs compatible with existing recycling infrastructure. Stakeholders must monitor evolving state-level bans on single-use plastics that could abruptly redefine permissible substrate combinations.
Market Dynamics
Plastic Waste Management Rules are compressing substrate choices across India's sachet packaging value chain, forcing converters toward mono-material architectures compatible with mechanical recycling infrastructure.
Growth Catalysts
- Rural FMCG penetration:Maharashtra's kirana networks are expanding single-serve shampoo and condiment formats to price-sensitive consumers in tier-3 and tier-4 towns.
- BIS IS 9833 migration limits:Tightening food-contact specifications are accelerating adoption of barrier-coated polyester films over conventional multi-layer laminates.
- Gujarat chemical belt concentration:Proximity to resin production and film extrusion capacity is lowering logistics costs for western Indian converters.
Market Restraints
- Resin price volatility:Crude-linked polyethylene and polypropylene input costs create margin compression for non-integrated converters lacking captive extrusion.
- Aluminum foil supply concentration:Dependence on limited domestic rolling capacity and import exposure creates vulnerability in high-barrier pharmaceutical sachet production.
- Recycling infrastructure gaps:Inadequate collection and sorting systems for multi-material laminates limit circular economy claims under EPR obligations.
Strategic Opportunities
- Karnataka food processing corridors:Spice and sauce packaging demand from Bangalore-Mysore industrial zones offers volume expansion for regional converters.
- Paper-based personal care trials:Extended Producer Responsibility pressures are opening substitution pathways for plastic sachets in cosmetic sample packs.
- PLI scheme for specialty chemicals:Domestic production incentives for barrier coatings and adhesives could reduce import dependence for critical film components.
Industry Challenges
- Formulation chemist scarcity:Shortage of professionals skilled in solvent-free adhesive systems and high-speed lamination is slowing plant modernization timelines.
- CDSCO pharmaceutical sachet certification:Extended stability testing and documentation requirements create 18-24 month approval cycles for oral rehydration salt formats.
- Legacy gravure cylinder inventory:Capital sunk in rotogravure tooling creates resistance to transitioning toward digital print for short-run customized sachets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Sachet Packaging Market |
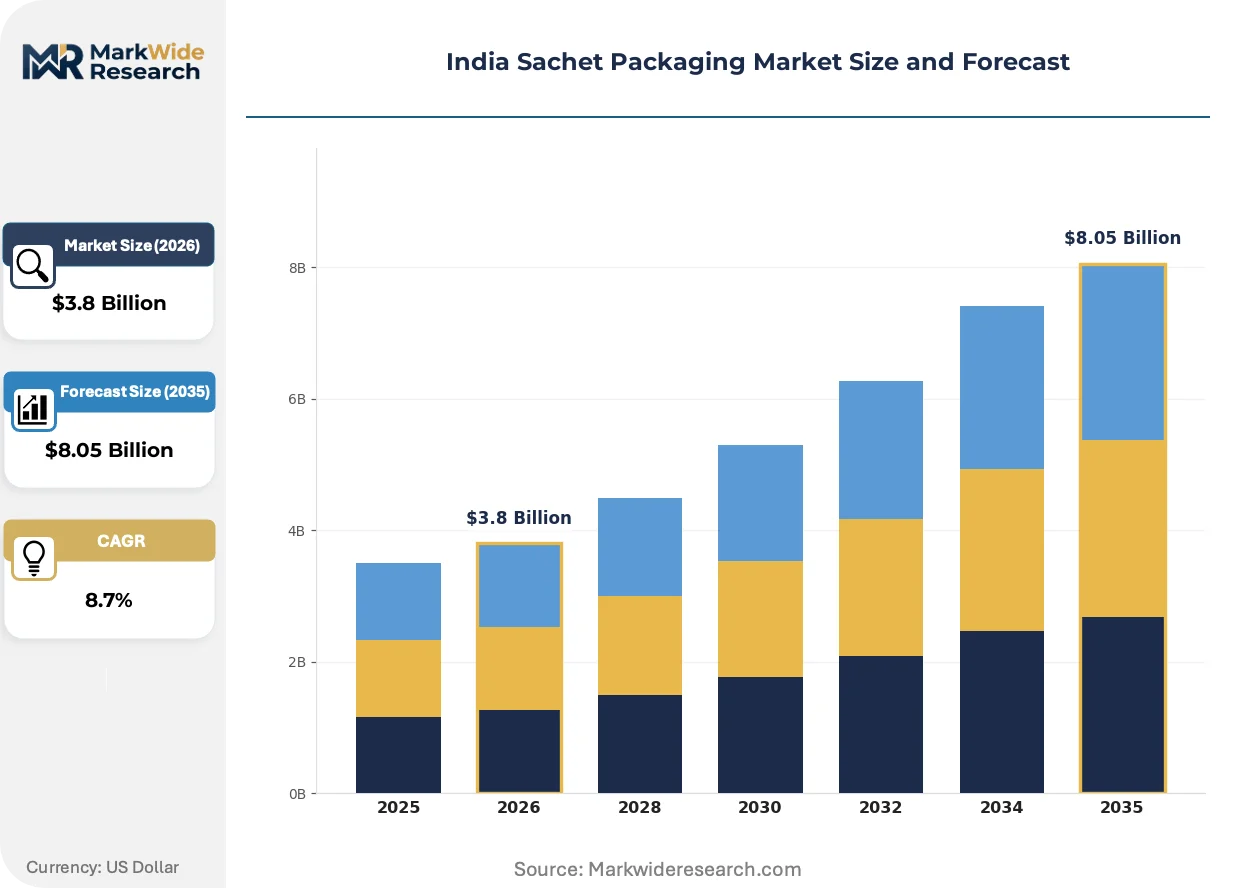
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Personal Care, Household, Pharmaceutical Material: Plastic, Paper, Aluminum, Glass End User: Retail, E-commerce, Hospitality, Healthcare Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Amcor, Sealed Air, Mondi Group, Berry Global, Constantia Flexibles, Huhtamaki, Sonoco Products, Uflex Limited, Paras Printpack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Sachet Packaging Market Trends and Innovations
Digital print integration and mono-material film architectures are reshaping production economics across India's sachet packaging sector. These shifts respond simultaneously to regulatory pressure and brand demand for shorter runs with regional customization.
High-barrier mono-material polyethylene structures are consolidating market share among converters serving FSSAI-regulated food applications. Mid-tier packaging houses in Ahmedabad and Vadodara are retrofitting form-fill-seal lines to process these substrates at speeds approaching conventional laminates. This transition is consolidating supplier relationships around resin producers capable of certifying full recyclability under IS 17088 standards.
FSSAI labeling mandates for shelf-life declarations and nutritional facts are expanding minimum print area requirements on sachet formats. Brands must now accommodate larger information panels without sacrificing shelf visibility or unit economics. Pharmaceutical sachet producers face the most acute redesign pressure, as CDSCO pediatric dosing regulations demand both child-resistant features and expanded contraindication text.
Kirana store networks are fragmenting procurement patterns for condiment and spice sachets, replacing consolidated distributor orders with direct-to-retailer shipments from regional converters. Brand procurement teams are responding with SKU proliferation strategies targeting hyperlocal taste preferences. This pattern is most visible in Maharashtra's Nashik-Solapur corridor, where regional masala brands command shelf space through customized 5-gram sachet formats.
India Sachet Packaging Market Segmentation
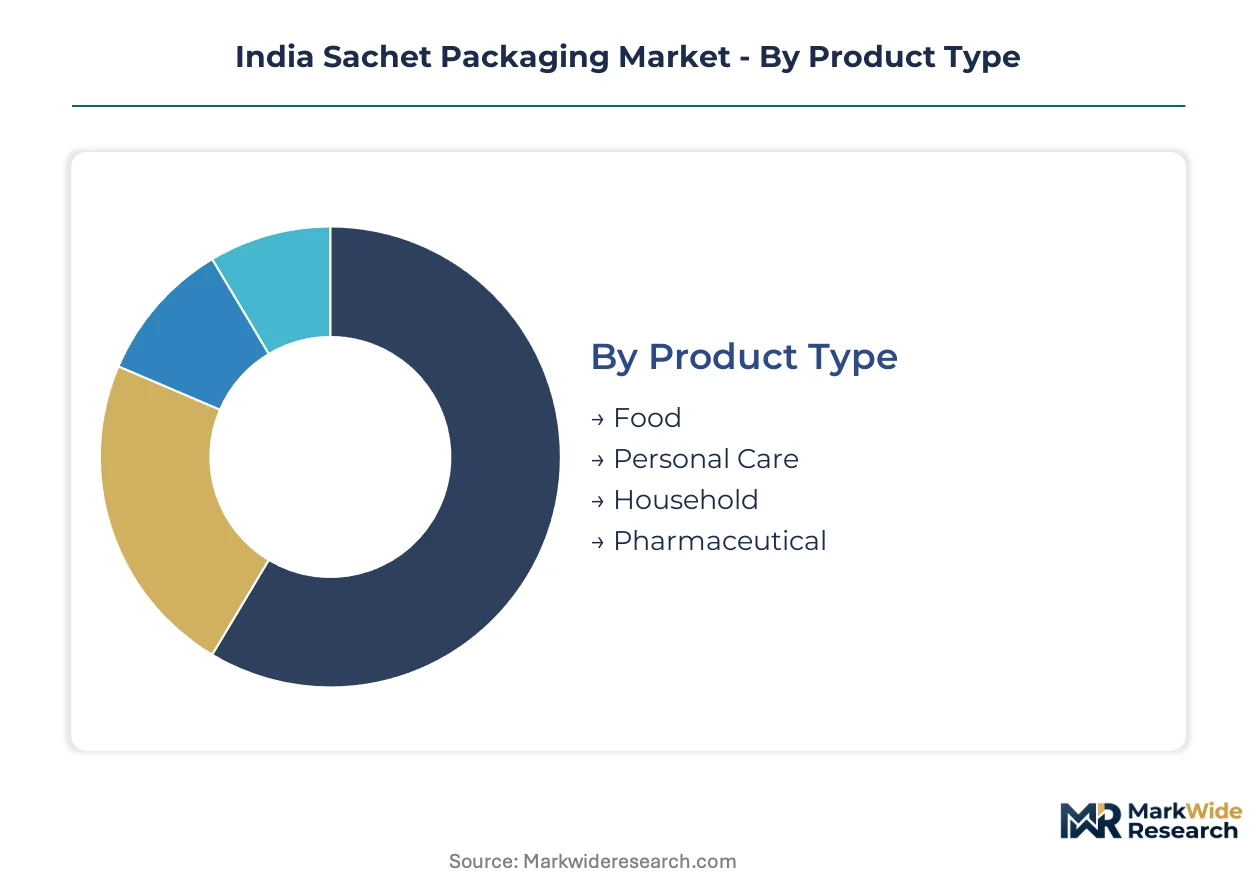
Sachet packaging in India spans divergent technical requirements across food safety, pharmaceutical stability, and personal care aesthetics. Each segment demands distinct barrier specifications, print tolerances, and regulatory compliance pathways that shape converter capabilities and capital allocation.
Product Type:
Customization intensity varies sharply across this category, from standardized condiment formats to highly specialized pediatric drug delivery systems.
- Food:Multi-layer polyethylene-polyester laminates with moisture barriers dominate spice and sauce sachets distributed through kirana networks in Maharashtra and Gujarat. FSSAI migration limits under IS 9833 are accelerating shifts toward barrier-coated mono-material structures in Nashik-Solapur corridor processing facilities.
- Pharmaceutical:Aluminum-laminate structures with child-resistant features serve oral rehydration salts and effervescent doses, requiring CDSCO stability testing cycles of 18-24 months. Hospital procurement channels in Karnataka demand the highest barrier specifications, creating premium margin tiers distinct from retail pharmaceutical sachets.
- Personal Care:Shampoo and conditioner sachets utilize oriented polypropylene with metallized layers for shelf appeal in tier-3 and tier-4 towns.
- Household:Detergent and cleaner sachets employ cost-optimized polyethylene structures with basic print registration for price-sensitive rural markets.
Leading the category by volume: Food. Expanding most quickly: Pharmaceutical.
Material:
Cost tiers separate commodity substrates from engineered barrier films, with recyclability mandates now disrupting traditional multi-layer economics.
- Plastic:Polyethylene and polypropylene films constitute the dominant tonnage, with Gujarat's chemical belt providing resin proximity advantages for western Indian converters. EPR obligations under Plastic Waste Management Rules are forcing retrofits toward mono-material polyethylene architectures compatible with mechanical recycling.
- Aluminum:Foil laminates deliver oxygen and moisture barriers essential for pharmaceutical stability, though limited domestic rolling capacity creates supply vulnerability. Import dependence for pharmaceutical-grade foil concentrates procurement risk among CDSCO-certified converters.
- Paper:Barrier-coated paperboard is gaining traction in cosmetic trial packs as brands respond to Extended Producer Responsibility pressures.
- Glass:Miniature glass ampoules serve high-value pharmaceutical samples requiring absolute inertness, occupying negligible volume but commanding extreme premium positioning.
Plastic holds volume dominance. Paper-based alternatives are climbing the fastest amid EPR compliance timelines.
End User:
Distribution channel structure determines run length economics and geographic service radius requirements for converter operations.
- Retail:Kirana store networks fragment procurement into hyperlocal SKU proliferation, demanding short-run digital print capabilities and direct-to-retailer logistics from regional converters in Maharashtra's tier-3 towns.
- Healthcare:Hospital and clinic procurement channels concentrate volume for pharmaceutical sachets, requiring batch traceability and CDSCO documentation that favors larger converters with quality management infrastructure.
- Hospitality:Hotels and restaurants source standardized condiment and amenity sachets through consolidated distributor relationships.
- E-commerce:Direct-to-consumer trial packs demand customized short runs with regional language variants for platform-specific promotional campaigns.
Retail channels absorb the greatest volume. Healthcare procurement shows the steepest expansion trajectory as hospital networks penetrate tier-2 cities.
Thickness:
Performance requirements and material cost trade-offs stratify this category across protection level and unit economics.
- Thin:Sub-50 micron structures serve single-use condiment and shampoo sachets where cost minimization overrides durability requirements.
- Medium:50-100 micron laminates balance puncture resistance with material efficiency for standard food and personal care applications.
- Thick:100-150 micron constructions protect aggressive chemical formulations in household cleaner sachets.
- Extra Thick:Above-150 micron structures accommodate pharmaceutical stability demands and child-resistant opening features.
Medium thickness dominates unit volume. Extra thick formats are gaining share fastest in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene resin production clusters in western India anchor the national sachet packaging value chain. Gujarat's chemical belt supplies feedstock to film extrusion plants serving converters across Maharashtra and Karnataka. BIS certification requirements and FSSAI labeling mandates shape regional specialization patterns.
Maharashtra
Kirana store networks in Nashik and Solapur drive single-serve shampoo and condiment sachet demand. FSSAI shelf-life declaration rules expand minimum print area requirements on 5-gram spice formats. Pune-Ahmednagar industrial corridors host mid-tier converters retrofitting form-fill-seal lines for mono-material polyethylene.
Gujarat
Proximity to Reliance Industries' polyethylene plants reduces resin logistics costs for Vadodara and Ahmedabad converters. BIS IS 9833 migration limits accelerate barrier-coated polyester adoption over multi-layer laminates. Ankleshwar chemical complexes supply solvent-free adhesives for high-speed lamination upgrades.
Karnataka
Bangalore-Mysore food processing corridors generate spice and sauce packaging demand from regional masala brands. CDSCO pharmaceutical sachet certification cycles concentrate hospital procurement volumes in Bengaluru's healthcare networks. Mysuru industrial zones attract converters serving both retail kirana and institutional channels.
Tamil Nadu
Chennai's pharmaceutical formulation units create downstream demand for aluminum-laminate oral rehydration salt sachets. Import dependence for pharmaceutical-grade foil concentrates procurement risk among CDSCO-certified converters. Coimbatore packaging machinery manufacturers supply retrofit equipment for mono-material transitions.
Telangana
Hyderabad's bulk drug manufacturing base generates specialized sachet requirements for effervescent and pediatric doses. PLI scheme incentives for specialty chemicals attract barrier coating producers to Genome Valley pharmaceutical clusters. Regional converters develop capabilities serving both export-oriented formulation units and domestic retail channels.
India Sachet Packaging Market Competitive Landscape
Global majors compete with regional champions across barrier specification tiers and regulatory certification depth. The market structure separates into three layers: multinational converters with pharmaceutical-grade infrastructure, integrated Indian film producers with captive resin access, and regional specialists serving kirana distribution networks. Two strategic archetypes dominate competitive positioning: backward-integrated resin-to-sachet operators and technology-licensed barrier film specialists. Capacity expansion in Gujarat and Karnataka accompanies M&A activity targeting CDSCO-certified pharmaceutical packaging capabilities.
Among India-based integrated producers, Uflex Limited anchors the resin-integrated tier with film extrusion assets in Gujarat and Noida. Mondi Group represents European technical standard adoption within Indian operations, competing on barrier specifications for pharmaceutical applications. Constantia Flexibles exemplifies aluminum-laminate specialization for oral rehydration salts, occupying hospital procurement channels with extended stability documentation.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air |
| Mondi Group |
| Berry Global |
| Constantia Flexibles |
| Huhtamaki |
| Sonoco Products |
| Uflex Limited |
| Paras Printpack |
| Others |
Pricing and Supply Chain Analysis
Polyethylene resin costs cascade from Reliance Industries' Jamnagar crackers through three distinct pricing tiers for sachet converters, with backward-integrated players capturing margin advantages that non-integrated competitors cannot match in Gujarat's chemical belt.
Pricing Analysis
CDSCO certification documentation and stability testing warranties separate premium pharmaceutical sachet pricing from unbundled economy tiers serving kirana condiment markets. Price differentiation hinges on barrier specification grade and FSSAI migration compliance tier under IS 9833, with hospital procurement channels showing lowest price sensitivity versus rural retail networks. Pricing pressure intensifies in standard food-grade laminates as mono-material retrofits compress converter margins without corresponding brand price premiums.
Supply Chain Analysis
Dual-sourcing mandates from FMCG procurement teams require qualification of both domestic and import film suppliers, with pharmaceutical-grade aluminum foil drawing from limited domestic rolling capacity and South Korean import channels. Raw material dependencies center on polyethylene resins, polyester films, and solvent-free adhesive systems. Single-source vulnerability concentrates in pharmaceutical-grade foil supply. Distribution runs through regional converter networks directly servicing Maharashtra's tier-3 kirana clusters and Karnataka's hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India sachet packaging market reads as a cost-of-compliance story where BIS IS 9833 migration certification creates a barrier-to-entry moat that rewards incumbent converters with documented quality infrastructure.
For Market Incumbents: Acquire CDSCO-certified pharmaceutical packaging assets to consolidate hospital procurement relationships before specialty chemical PLI incentives attract new barrier-film competitors. Retrofit existing Gujarat and Noida extrusion lines for mono-material polyethylene architectures to preempt EPR enforcement tightening. Channel control through direct-to-retailer logistics investments defends position against regional kirana specialists in Maharashtra's Nashik-Solapur corridor. For New Entrants and Emerging Players: The 40-60% price-point gap between premium pharmaceutical sachets and economy condiment formats offers white-space targeting in mid-tier personal care trial packs. Karnataka's Bangalore-Mysore food processing corridors present the most penetrable geography given fragmented regional masala brand procurement. Paper-based barrier coating capabilities aligned with EPR timelines provide a differentiated go-to-market angle for cosmetic sample pack contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor solvent-free adhesive specialists in Ankleshwar chemical complexes facing formulation chemist scarcity headwinds. Long-term viability over the next decade hinges on mono-material transition completion before state-level single-use plastic bans accelerate. Watch CDSCO approval cycle compression as the signal indicating pharmaceutical sachet capacity shortage inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polyethylene supply from Reliance Industries' Gujarat crackers secures resin cost advantages. |
| CDSCO Certification Investment | Hospital procurement channels in Bengaluru demand 18-24 month stability documentation for oral rehydration salts. |
| Mono-Material Line Retrofit | Mechanical recycling compatibility under IS 17088 satisfies Plastic Waste Management Rules EPR obligations. |
| Regional Converter Acquisition | Maharashtra tier-3 kirana network access enables hyperlocal SKU proliferation for spice brands. |
| Barrier Coating R&D Partnership | PLI scheme incentives for specialty chemicals reduce import dependence on Korean adhesive suppliers. |
Research Methodology
Document review covered BIS certification registries, FSSAI labeling compliance filings, and CDSCO pharmaceutical packaging approvals, complemented by interviews with plant managers at western Indian converters, procurement leads at FMCG brand houses, distribution channel partners in Maharashtra kirana networks, and regulatory affairs specialists navigating IS 9833 migration limits. Secondary validation drew from customs trade data on polyethylene resin imports, SEC filings of integrated packaging producers, and state-level plastic waste management notifications. Bottom-up volume estimates from individual converter capacity assessments triangulated against top-down resin consumption figures from Gujarat chemical belt production statistics.
Segmented outputs across food, pharmaceutical, personal care, and household product categories combined with material-tier splits in plastic, aluminum, paper, and glass substrates generated volume and value trajectories across the projection horizon. CAGRs derived from regression analysis of historical resin price elasticity, regulatory implementation timelines, and rural FMCG penetration rates modeled through the forecast period. Industry-specific inputs included CDSCO approval cycle durations, EPR compliance cost curves, and kirana store network expansion patterns in tier-3 towns.
Inputs from BIS certification databases and FSSAI compliance registries were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term volume estimates. Deviation in state-level single-use plastic ban implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
Canada Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market