
 Single Cell Multiomics Market | 2026-2036
Single Cell Multiomics Market Size, Share, and Industry Trends Forecast 2026-2036
Single Cell Multiomics Market Intelligence
A shift from outsourced sequencing services toward in-house multi-omics platforms is hardening across pharmaceutical and academic buyers. 10x Genomics leverages its Chromium controller ecosystem to dominate droplet-based transcriptome profiling. Illumina sustains instrument placement through bundled reagent contracts and reference genome partnerships. Bio-Rad Laboratories anchors its position with ddSEQ microfluidics that competes on per-cell cost for high-plex studies.
Single cell multiomics integrates simultaneous genomic, transcriptomic, epigenetic, and proteomic readouts from individual cells using barcoded microfluidic capture, combinatorial indexing, or split-pool ligation to resolve cellular heterogeneity missed by bulk assays. Sequencing kits generate recurring revenue as run volume scales faster than instrument sales. Microfluidics devices capture margin pools through consumable lock-in, while analysis software segments by subscription tier and compute intensity. Next-Generation Sequencing leads technology adoption, with Mass Spectrometry growing fastest for proteome co-detection workflows.
FDA oversees clinical translation of multi-omics signatures under in vitro diagnostic and LDT frameworks, while ISO 15189 and CAP accreditation shape service lab market access. EMA's IVDR recalibration demands stronger analytical validation for cell-based assay kits sold into European clinical research. China's NMPA accelerates review pathways for innovative sequencing instruments under its medical device reform. Stakeholders must monitor regulatory divergence between jurisdictions as multi-omics assays migrate from discovery toward regulated diagnostic endpoints.
Market Dynamics
Pharmaceutical buyers are consolidating sequencing workflows under single-vendor ecosystems to compress validation overhead and accelerate CRISPR-compatible assay deployment. This vendor consolidation pressure is restructuring procurement patterns across discovery and clinical translation stages.
Growth Catalysts
- Precision medicine mandates:National initiatives in the United States, Germany, and China are funding sequencing infrastructure expansion that directly consumes multi-omics kits and instruments.
- ISO 13485 quality harmonization:Standardized quality management systems are shortening vendor qualification cycles for kit manufacturers seeking dual research-clinical positioning.
- CRISPR integration:Gene editing workflows are deepening assay complexity and expanding per-study reagent consumption in pharmaceutical R&D laboratories.
Market Restraints
- Consumable cost concentration:Microfluidic cartridge pricing locks laboratories into recurring expenditure structures that scale linearly with sample volume.
- Supply chain geographic concentration:Critical reagent manufacturing clusters in specific coastal Chinese provinces create single-point vulnerability for international kit distributors.
- FDA 21 CFR Part 11 compliance friction:Electronic records requirements impose validation burdens that delay software-enabled instrument deployments by 6-18 months.
Strategic Opportunities
- Clinical diagnostic migration:LDT framework expansion under FDA oversight is opening reimbursed testing pathways for multi-omics signatures in oncology.
- Mass spectrometry convergence:Proteome co-detection workflows are creating instrument bundling opportunities that transcriptome-only vendors cannot match.
- Cloud-based analysis platforms:Subscription-tiered bioinformatics services are capturing margin pools from laboratories lacking in-house computational infrastructure.
Industry Challenges
- Bioinformatics talent scarcity:Computational biology skill gaps constrain interpretation throughput even where sequencing capacity expands.
- Multi-modal data integration complexity:Harmonizing genomic, transcriptomic, and proteomic outputs from single cells requires specialized pipeline architecture that most facilities lack.
- CAP accreditation timelines:Service laboratory certification processes create revenue gaps during qualification periods for newly established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Cell Multiomics Market |
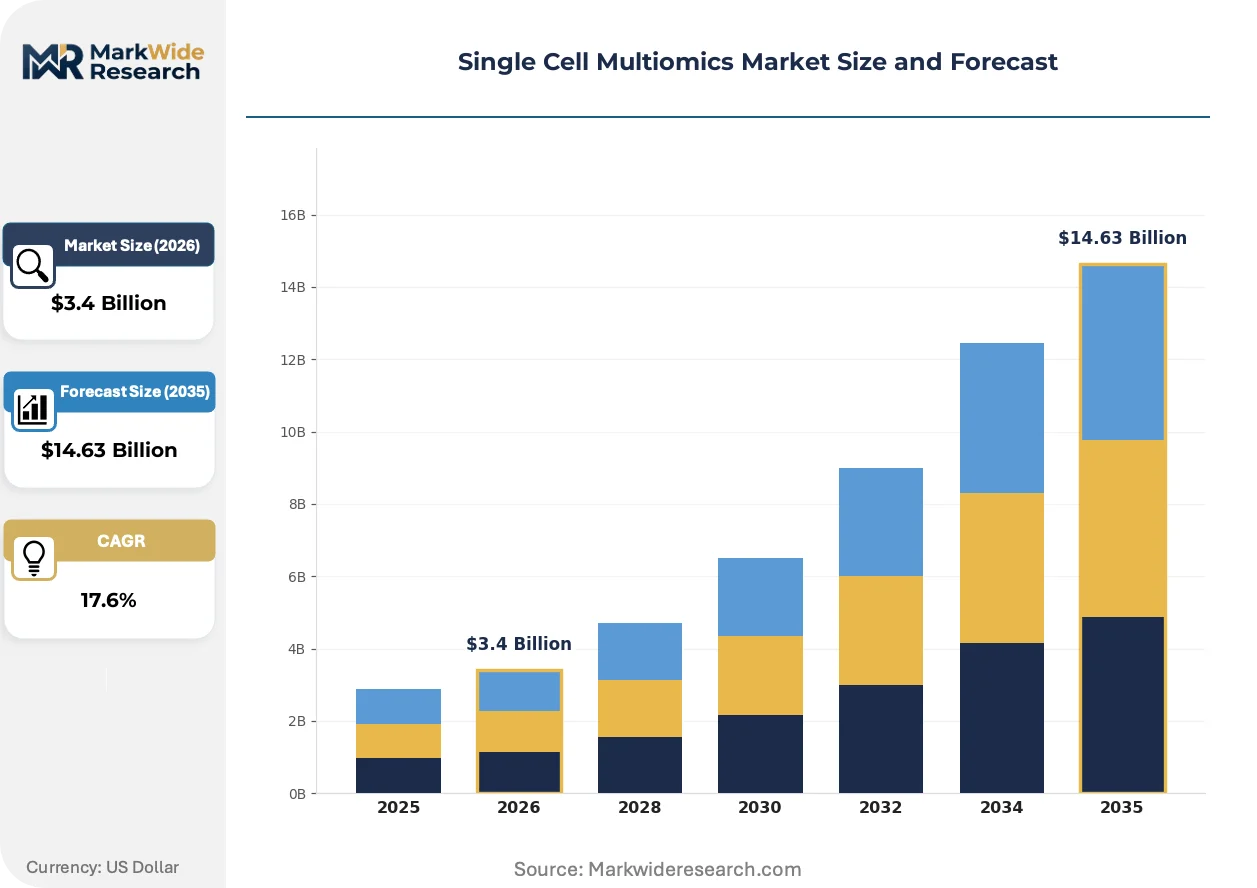
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $14.63 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Kits, Analysis Software, Microfluidics Devices, Sample Preparation Tools End User: Research Institutes, Pharmaceutical Companies, Biotech Firms, Academic Laboratories Technology: Next-Generation Sequencing, PCR, Mass Spectrometry, Flow Cytometry Application: Drug Discovery, Genomics Research, Disease Profiling, Personalized Medicine |
| Companies Covered | 10x Genomics, Illumina, Bio-Rad Laboratories, BD, QIAGEN, Fluidigm, Takara Bio, NanoString Technologies, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Cell Multiomics Market Strategic Shifts & Innovations
Combinatorial indexing and split-pool ligation chemistries are displacing earlier barcoding approaches as throughput demands scale beyond droplet microfluidics limits. These methodological shifts are compressing per-cell cost curves and enabling million-cell studies previously constrained by capture efficiency.
Combinatorial indexing is expanding into high-plex immunology screening where pharmaceutical sponsors require immune repertoire profiling across thousands of clinical samples. Bristol Myers Squibb and Roche are deploying these workflows for checkpoint inhibitor biomarker discovery. The technology is expanding into applications previously served by lower-resolution bulk RNA-seq, compressing the addressable market for traditional transcriptome methods.
EMA's IVDR recalibration is demanding stronger analytical validation for cell-based assay kits sold into European clinical research, forcing manufacturers to restructure quality documentation. Kit vendors must now demonstrate traceable cell line authentication and batch-to-batch consistency metrics absent from research-use-only specifications. German and French CROs are responding by consolidating supplier relationships around vendors with established notified body engagement.
Academic core facilities are unbundling sequencing services from analysis support, selling raw data generation while referring interpretation to specialized bioinformatics boutiques. This channel fragmentation is displacing bundled service contracts that previously captured full workflow value. The pattern is most visible in United States research universities where indirect cost recovery pressures favor equipment utilization over labor-intensive downstream support.
Single Cell Multiomics Market Segmentation
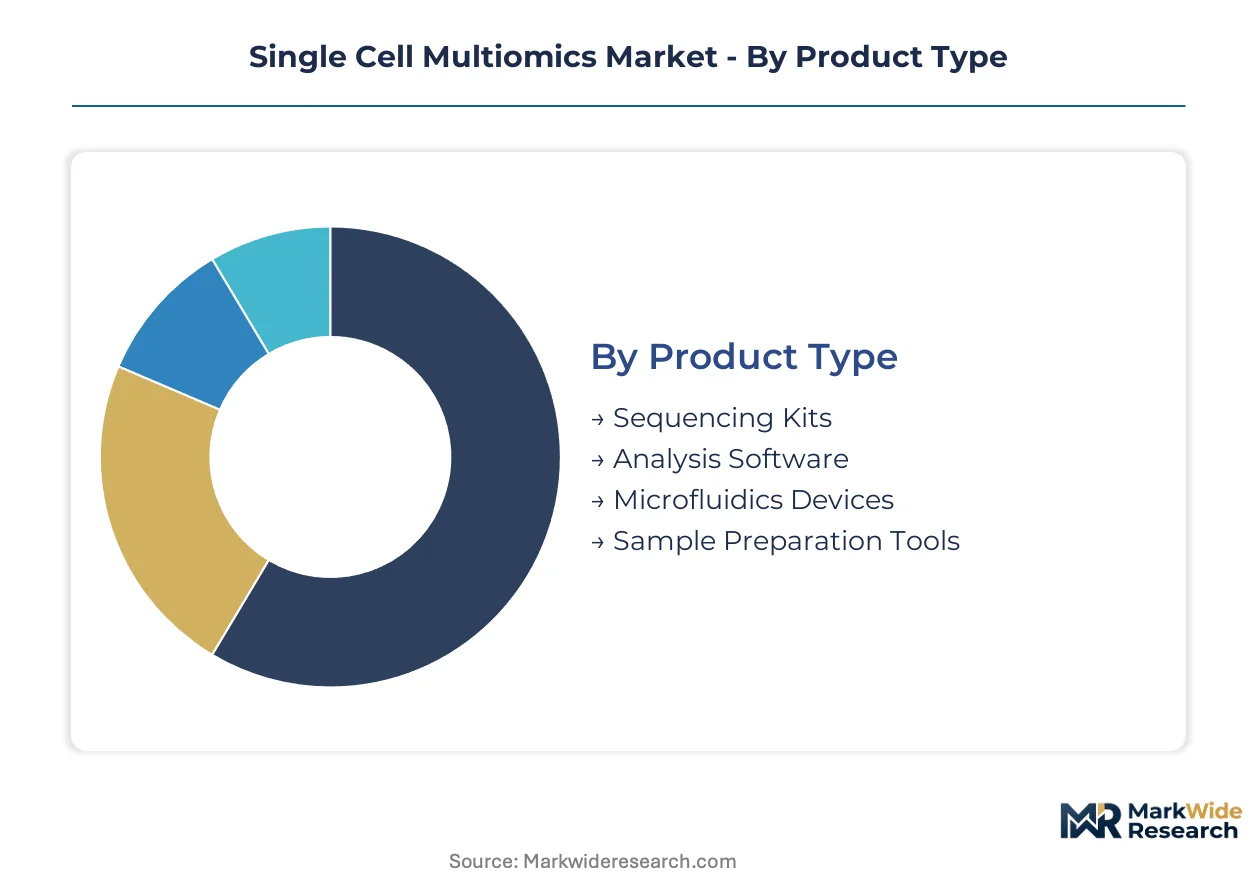
Segmentation in single cell multiomics reveals how vendor revenue pools concentrate in consumable-heavy workflows versus instrument placements. Product mix and end-user procurement patterns determine margin durability as laboratories scale from pilot studies to production-scale screening.
Product Type:
Upgrade cycles in single cell multiomics favor consumable platforms over capital equipment, with laboratories prioritizing per-run cost predictability in high-volume operations.
- Sequencing Kits:Barcoded reagent chemistries generate recurring revenue through fixed per-cell consumption rates. Pharmaceutical companies in the United States and Germany now specify CRISPR-compatible kit formulations in multi-year procurement contracts.
- Microfluidics Devices:Droplet-based capture cartridges lock laboratories into vendor ecosystems through proprietary chip architectures. China's NMPA-cleared instruments are displacing research-use-only devices in clinical research settings.
- Analysis Software:Cloud-based bioinformatics platforms segment by compute intensity and sample throughput tiers.
- Sample Preparation Tools:Nuclei isolation and cell sorting accessories complete workflow integration for core facilities.
Sequencing Kits sits at the top of the volume ranking, with Microfluidics Devices climbing the fastest as throughput demands scale beyond manual protocols.
End User:
Procurement authority in single cell multiomics has shifted toward pharmaceutical buyers consolidating vendor relationships to compress validation overhead.
- Pharmaceutical Companies:Internal multi-omics platforms now replace outsourced sequencing for CRISPR screening workflows. ISO 13485-qualified kit vendors capture preferred supplier status through dedicated field application support.
- Research Institutes:National precision medicine initiatives in Germany and China fund instrument placements at flagship facilities. EMA's IVDR recalibration is forcing these institutes to segregate research and clinical-grade reagent inventories.
- Biotech Firms:Venture-backed developers prioritize per-cell cost efficiency in high-plex immunology screening.
- Academic Laboratories:Indirect cost recovery pressures favor equipment utilization over labor-intensive downstream analysis support.
Pharmaceutical Companies commands the largest procurement volume, with Biotech Firms gaining share fastest as checkpoint inhibitor biomarker discovery accelerates.
Technology:
Technology selection in single cell multiomics tracks the convergence of transcriptome profiling with proteome co-detection capabilities.
- Next-Generation Sequencing:Short-read platforms dominate droplet-based transcriptome workflows through bundled reagent contracts. FDA 21 CFR Part 11 compliance requirements delay software-enabled instrument deployments by validated timelines.
- Mass Spectrometry:Proteome co-detection workflows are expanding fastest for multi-modal studies requiring simultaneous protein quantification. Bristol Myers Squibb and Roche are deploying these platforms for immune repertoire profiling.
- PCR:Targeted amplification methods retain niche positioning for low-input samples.
- Flow Cytometry:Index sorting integration enables downstream multi-omics linkage for rare cell populations.
Next-Generation Sequencing holds the installed base leadership, with Mass Spectrometry expanding most quickly as proteome integration becomes standard.
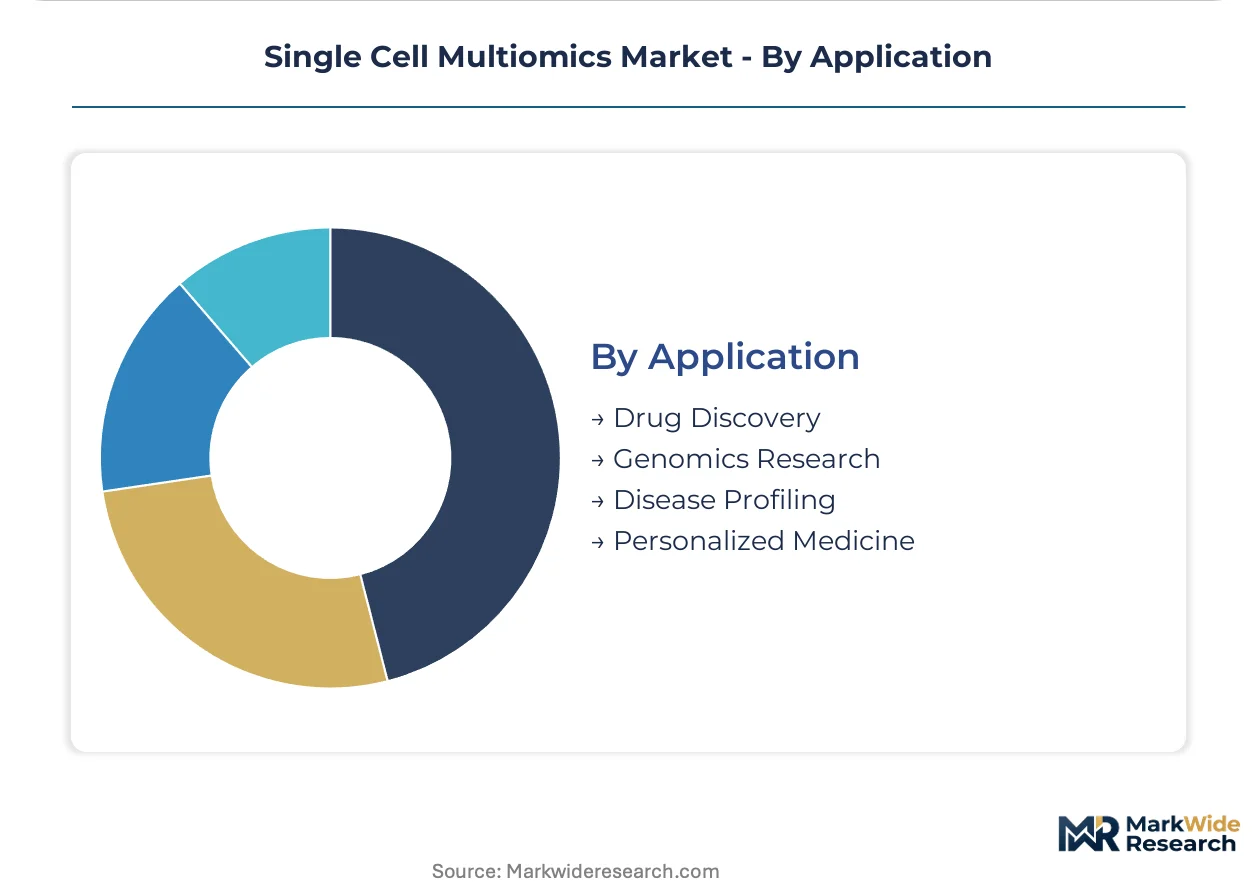
Application:
Application demand in single cell multiomics follows the migration from discovery biology toward regulated diagnostic endpoints.
- Drug Discovery:CRISPR-based screening workflows deepen assay complexity and expand per-study reagent consumption. Combinatorial indexing chemistries displace earlier barcoding approaches as pharmaceutical sponsors require million-cell study capabilities.
- Personalized Medicine:LDT framework expansion under FDA oversight is opening reimbursed testing pathways for multi-omics signatures in oncology. CAP accreditation shapes service lab market access for clinical translation.
- Genomics Research:Academic core facilities unbundle sequencing services from analysis support, selling raw data generation while referring interpretation to specialized boutiques.
- Disease Profiling:Cell-based assay kits for autoimmune and infectious disease monitoring require batch-to-batch consistency metrics.
Drug Discovery maintains the highest absolute spending, with Personalized Medicine showing the steepest expansion trajectory as regulatory pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates multi-omics instrument deployment as pharmaceutical sponsors internalize sequencing workflows. National precision medicine programs in Germany and China are accelerating kit procurement through dedicated infrastructure funding.
United States
FDA's LDT framework expansion is opening reimbursed testing pathways for oncology multi-omics signatures. The agency's 21 CFR Part 11 compliance requirements delay software-enabled instrument deployments by validated timelines. Greater Boston anchors CRISPR-compatible assay development as Bristol Myers Squibb and Roche deploy combinatorial indexing for immune repertoire profiling.
Germany
EMA's IVDR recalibration demands stronger analytical validation for cell-based assay kits sold into European clinical research. The country's national precision medicine initiative funds instrument placements at flagship facilities in Heidelberg and Munich. German CROs are consolidating supplier relationships around vendors with established notified body engagement.
China
NMPA accelerates review pathways for innovative sequencing instruments under its medical device reform. Critical reagent manufacturing clusters in coastal provinces create supply concentration for international kit distributors. Beijing and Shanghai research institutes are segregating research and clinical-grade reagent inventories under dual-track quality systems.
United Kingdom
The country's national pharmaceutical regulator shapes service lab market access through CAP-equivalent accreditation timelines. London and Oxford core facilities are unbundling sequencing services from analysis support, selling raw data generation while referring interpretation to specialized boutiques. Academic indirect cost recovery pressures favor equipment utilization over labor-intensive downstream support.
Japan
PMDA oversight of clinical translation creates structured pathways for multi-omics diagnostic endpoints. The Tokyo-Yokohama corridor hosts venture-backed biotech developers prioritizing per-cell cost efficiency in high-plex immunology screening. METI funding supports mass spectrometry convergence for proteome co-detection workflows.
Single Cell Multiomics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue mass spectrometry convergence and cloud-based analysis platforms. The vendor structure concentrates around consumable-heavy workflows versus instrument placements, with microfluidic cartridge pricing locking laboratories into recurring expenditure structures. Three archetypes dominate: ecosystem bundlers anchoring end-to-end workflows, technology specialists commanding niche proteome integration, and reagent-scale suppliers competing on per-cell cost efficiency. Consolidation pressure is restructuring procurement patterns through vendor ecosystem consolidation and strategic partnerships for CRISPR-compatible assay deployment.
Within the ecosystem bundler tier, 10x Genomics and Illumina exemplify platform-centric positioning through controller ecosystems and bundled reagent contracts respectively. Bio-Rad Laboratories occupies a position among microfluidics specialists competing on per-cell cost for high-plex studies. These three companies represent contrasting approaches to consumable lock-in and instrument placement strategies across pharmaceutical and academic buyer segments.
| Leading Market Players |
|---|
| 10x Genomics |
| Illumina |
| Bio-Rad Laboratories |
| BD |
| QIAGEN |
| Fluidigm |
| Takara Bio |
| NanoString Technologies |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
Pharmaceutical procurement consolidation under single-vendor ecosystems concentrates pricing power among ISO 13485-qualified kit manufacturers, compressing per-cell cost curves through multi-year reagent contracts while locking laboratories into consumable-heavy expenditure structures.
Pricing Analysis
Microfluidic cartridge manufacturing costs pass through to end-users via proprietary chip architectures that enforce consumable lock-in. Pricing stratifies across CRISPR-compatible premium formulations, standard research-grade chemistries, and economy-tier legacy barcoding kits. Cost compression in high-plex screening workflows intensifies as biotech developers benchmark per-cell economics against combinatorial indexing alternatives. Academic laboratories exhibit highest price sensitivity due to indirect cost recovery pressures, while pharmaceutical buyers prioritize validation overhead reduction over unit cost minimization.
Supply Chain Analysis
ISO 13485 certification and FDA 21 CFR Part 11 qualification gates restrict vendor eligibility for clinical research procurement, concentrating approved supplier relationships among notified body-engaged manufacturers. Critical reagent production clusters in coastal Chinese provinces, Massachusetts, and Baden-Württemberg feed international distribution networks. Supply chain vulnerability stems from single-source dependency on specialized polymer substrates for droplet microfluidics. Distribution runs through direct field application support for pharmaceutical accounts and academic core facility aggregators for research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EMA IVDR recalibration and FDA LDT framework expansion are shifting procurement criteria toward analytically validated, batch-traceable reagent tiers.
For Market Incumbents: Anticipate margin compression from mass spectrometry convergence by deepening proteome co-detection capabilities through strategic platform partnerships. Defensive consolidation of CRISPR-compatible assay portfolios will offset threat from cloud-native bioinformatics entrants seeking to unbundle analysis services from consumable revenue pools. For New Entrants and Emerging Players: Launch via subscription-tiered bioinformatics services targeting academic laboratories lacking in-house computational infrastructure. White-space concentration in immune repertoire profiling for checkpoint inhibitor biomarker discovery offers lowest competitive density, with German and Chinese precision medicine initiatives providing funded instrument placement pathways for validated kit vendors. For Investors and Strategic Acquirers: Pharmaceutical ecosystem bundlers are the most active acquirer in this space, seeking consumable-heavy workflows that compress validation timelines for CRISPR screening deployment. Long-term viability hinges on clinical diagnostic migration under FDA LDT oversight, with acquisition target archetypes spanning ISO 13485-qualified microfluidics specialists and CAP-accredited service laboratories. Signal to watch: NMPA-cleared instrument placements displacing research-use-only devices in Chinese clinical research settings.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Compatible Kit Formulation | Pharmaceutical procurement contracts now specify gene editing workflow compatibility as mandatory qualification criterion. |
| Notified Body Engagement | EMA IVDR compliance documentation accelerates European clinical research market access for validated vendors. |
| Mass Spectrometry Platform Integration | Proteome co-detection capabilities create instrument bundling opportunities unavailable to transcriptome-only competitors. |
| Cloud-Based Analysis Tiering | Subscription compute-intensity segmentation captures margin pools from laboratories lacking bioinformatics infrastructure. |
| CAP Accreditation Pathway | Clinical laboratory certification enables reimbursed testing under FDA LDT framework for oncology signatures. |
Research Approach
Bottom-up pharmaceutical and academic procurement modeling reconciled against top-down instrument placement and reagent consumption tracking forms the analytical core. Primary interviews with drug development executives, core facility directors, regulatory affairs leads, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov protocol specifications, and NMPA medical device registration databases.
Input-output matrices map sequencing kit volumes, microfluidic cartridge throughput, and software subscription tiers against end-user segmentation dimensions including CRISPR workflow adoption stage, clinical versus research quality grade requirements, and regional regulatory cluster alignment. CAGRs derive from modeled run-volume scaling curves and per-cell cost compression trajectories across the projection horizon, with mass spectrometry convergence rates and cloud platform adoption velocity as key sensitivity inputs.
Several conditions sit outside the modeled scope, including speculative therapeutic approval timelines for multi-omics signatures and unannounced regulatory guidance revisions. Forecasts reflect documented assumptions regarding precision medicine funding continuity and reagent manufacturing cluster stability. A model refresh is warranted upon material change in FDA LDT reimbursement determinations or NMPA medical device reform implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Neoantigen Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Global Ligation Market