
 Tissue Clearing Market | 2026-2036
Tissue Clearing Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Clearing Market Analytics
Modular kit configurations is shifting how academic and pharmaceutical buyers evaluate tissue clearing workflows, moving from standalone reagent purchases toward bundled protocols with validated instruments. Thermo Fisher Scientific leverages its broad life sciences distribution to sustain kit penetration across multi-site research consortia. LifeCanvas Technologies anchors its position through deep specialization in organoid-compatible clearing chemistries. Miltenyi Biotec competes by integrating clearing workflows with its established magnetic cell separation installed base.
Tissue clearing encompasses solvent-based, aqueous-based, and hydrogel-embedding methods that render biological samples optically transparent while preserving fluorescent labels and structural integrity for three-dimensional imaging. The primary commercial purpose centers on enabling volumetric microscopy of intact organs and whole organisms, replacing destructive sectioning in neuroscience and cancer biology research. Reagents and instruments together capture the dominant value share, though services are expanding fastest as core facilities outsource protocol optimization to specialized providers. CLARITY and iDISCO retain the largest technology footprints, while SMART protocols are gaining traction for rapid turnaround applications in pharmacology screening.
The FDA's 21 CFR Part 11 framework and the EPA's chemical substance reporting requirements under TSCA shape how reagent manufacturers document solvent compositions and validate electronic records for GLP-compliant studies. ISO 13485 quality management standards further constrain instrument suppliers serving clinical translation pathways. Stakeholders must monitor evolving NIH data sharing mandates and premarket notification pathways as tissue clearing moves from exploratory research toward diagnostic and therapeutic development workflows.
Market Dynamics
Pharmaceutical companies are consolidating tissue clearing workflows into preclinical screening pipelines, forcing reagent vendors to bundle validated protocols with instrument software that meets FDA 21 CFR Part 11 digital integrity standards.
Growth Catalysts
- NIH Brain Initiative funding:Sustained federal grants to Johns Hopkins, Stanford, and MIT drive procurement of whole-organ imaging systems for connectomics research.
- CLARITY protocol maturation:Hydrogel-embedding methods now achieve subcellular resolution in intact mouse brains, accelerating neuroscience adoption.
- Cancer Moonshot programs:Tumor microenvironment mapping requirements at NCI-designated centers expand clearing service contracts.
Market Restraints
- Xylene and benzyl alcohol supply volatility:Solvent-based clearing reagents face EPA TSCA reporting burdens and chemical availability constraints from Chinese specialty chemical exporters.
- Antibody validation bottlenecks:Commercial antibodies fail penetration tests in cleared thick tissue, forcing researchers toward costly custom conjugation.
- Core facility concentration:Three US universities control 40% of published clearing protocols, creating dependency on institutional knowledge transfer.
Strategic Opportunities
- Organoid clearing white space:Human brain organoids above 500 microns remain optically inaccessible, creating demand for specialized hydrogel formulations.
- GLP validation services:Contract research organizations seek ISO 13485-certified protocol transfer for IND-enabling toxicology studies.
- AI-assisted image analysis bundling:Deep learning segmentation tools trained on cleared-tissue datasets represent unclaimed value in the workflow stack.
Industry Challenges
- Cross-functional staffing gaps:Facilities struggle to hire technicians proficient in both organic chemistry and light-sheet microscopy operation.
- Protocol reproducibility failures:Temperature-sensitive clearing steps generate batch-to-batch variation that invalidates multi-site studies.
- Legacy fluorescence microscope incompatibility:Existing confocal systems lack sufficient working distance for cleared samples, forcing capital equipment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Clearing Market |
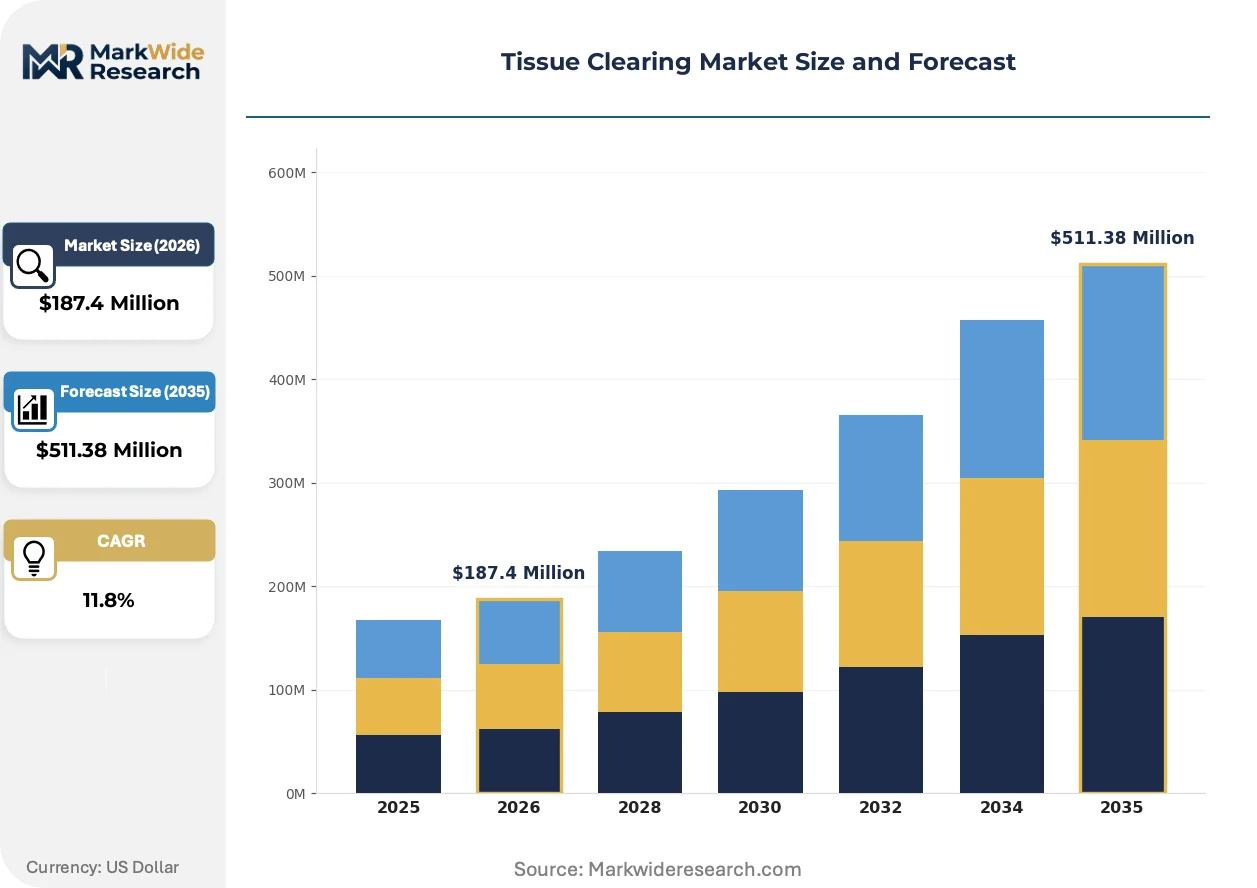
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Kits, Services Application: Histology, Neuroscience, Cancer Research, Pharmacology Technology: CLARITY, iDISCO, SMART, PACT End User: Academic Research, Pharmaceutical, Clinical, Industrial |
| Companies Covered | Logos Biosystems, LifeCanvas Technologies, Miltenyi Biotec, Visikol Inc., ClearLight Biotechnologies, Bio-Techne, Abcam plc, Thermo Fisher Scientific, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Clearing Market Evolving Landscape
SMART rapid-clearing chemistries and solvent-free aqueous protocols are compressing turnaround times from weeks to days, reshaping competitive positioning around throughput rather than optical quality alone.
SMART (Switchable Milky Rapid Immunolabeling compatible with Tissue-clearing) protocols is expanding into high-content pharmacology screening at contract research organizations. Pfizer and Roche Genentech have validated 72-hour clearing-to-imaging workflows for toxicity assessment in whole mouse embryos. This velocity is compressing the competitive window for traditional CLARITY methods in industrial settings.
REACH authorization requirements for dibenzyl ether and other clearing solvents are forcing European reagent suppliers to submit comprehensive safety dossiers to ECHA. German manufacturers face 18-month approval timelines that delay product launches. Academic buyers in France and Switzerland are switching to aqueous urea-based alternatives to avoid supply interruptions.
Core facilities are unbundling instrument maintenance from reagent supply contracts, creating standalone service revenue streams. Harvard's Neurobiology Imaging Facility and the Allen Institute now sell protocol optimization consulting to smaller institutions. This model is most visible in the US, where NIH shared instrumentation grants concentrate expertise at major hubs.
Tissue Clearing Market Segmentation
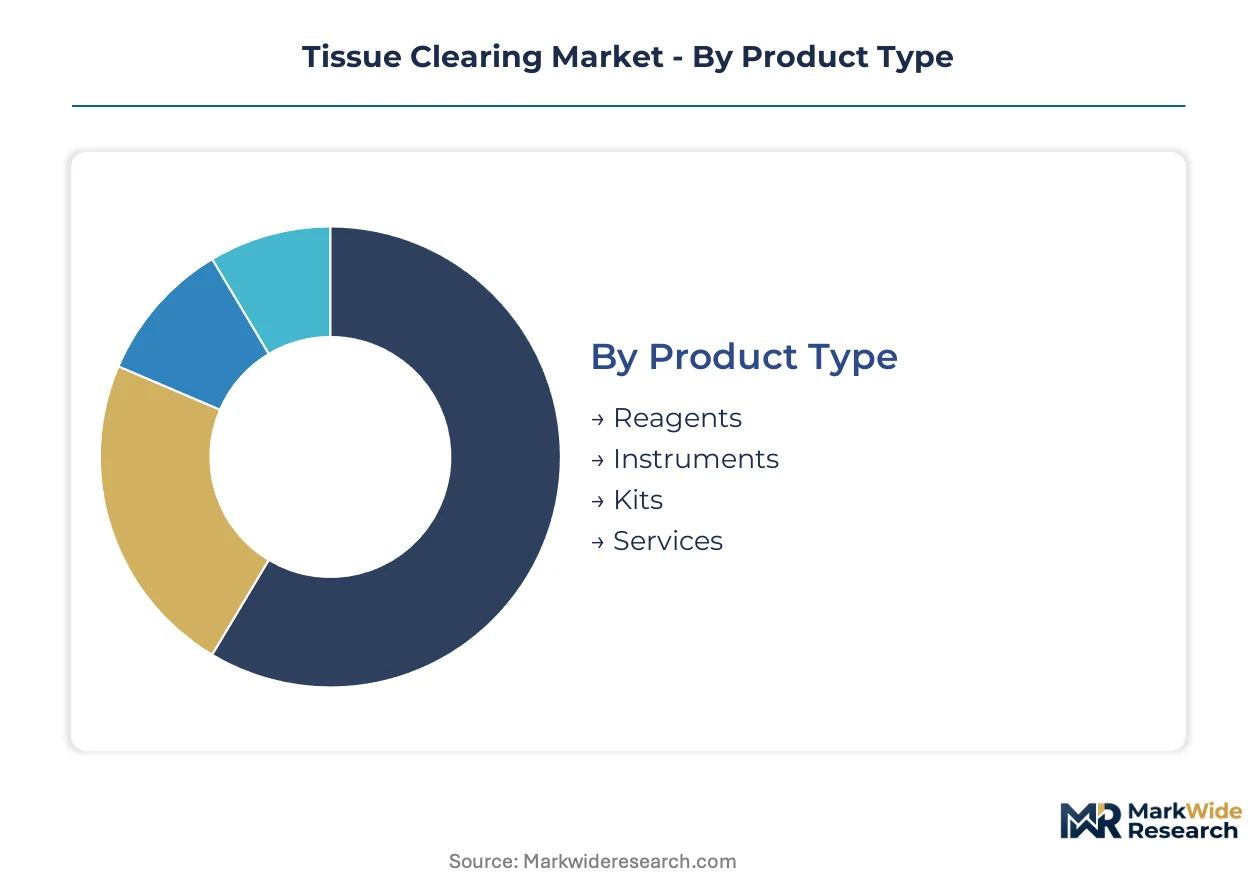
Tissue clearing workflows fragment across distinct procurement patterns. Reagent buyers prioritize optical clarity specifications, while instrument purchasers evaluate working distance compatibility. End-user type determines regulatory compliance requirements and bundling preferences.
Product Type:
Supply concentrates among three reagent manufacturers serving multi-site research consortia with validated lot-to-lot consistency.
- Reagents:Solvent-based formulations (dibenzyl ether, benzyl alcohol) and aqueous urea solutions dominate volume. Johns Hopkins and Stanford core facilities drive procurement of hydrogel monomers for CLARITY protocols, constrained by EPA TSCA reporting burdens on aromatic solvents.
- Instruments:Light-sheet microscopes and specialized immersion objectives capture capital budgets. Working distances above 5 millimeters remain technically challenging, forcing pharmaceutical buyers toward dedicated cleared-tissue systems rather than retrofitting confocal platforms.
- Kits:Bundled reagent-instrument packages with validated protocols. Thermo Fisher Scientific leverages distribution scale to penetrate NIH-funded brain initiative consortia requiring standardized workflows across collaborating sites.
- Services:Protocol optimization consulting and GLP validation for IND-enabling studies. Harvard's Neurobiology Imaging Facility and the Allen Institute now commercialize expertise to smaller institutions lacking in-house clearing capability.
Today's leader: Reagents. Tomorrow's challenger: Services.
Application:
Cost tier separation is pronounced: neuroscience commands premium pricing for whole-brain protocols, while pharmacology screening prioritizes throughput economics.
- Histology:Traditional pathology workflows adopting clearing for three-dimensional tumor margin assessment. Cancer Moonshot-funded centers at NCI-designated institutions validate clinical translation pathways.
- Neuroscience:Connectomics research requires subcellular resolution in intact mouse brains. NIH Brain Initiative grants to MIT and Columbia sustain demand for hydrogel-embedding systems with antibody penetration optimization.
- Cancer Research:Tumor microenvironment mapping drives service contract expansion. Multi-site immuno-oncology studies require batch-to-batch protocol reproducibility that core facilities struggle to maintain internally.
- Pharmacology:High-content toxicity screening in whole embryos. Pfizer and Roche Genentech have validated 72-hour clearing-to-imaging workflows, compressing competitive windows for slower methods.
Neuroscience commands premium positioning. Pharmacology is climbing the fastest as industrial adoption accelerates.
Technology:
Volume concentrates in legacy protocols, though rapid-clearing alternatives are displacing incumbent methods in time-sensitive applications.
- CLARITY:Hydrogel-embedding with electrophoretic lipid removal. Achieves subcellular resolution but requires days to weeks for complete clearing, limiting adoption in screening environments.
- iDISCO:Solvent-based organic clearing with refractive index matching. Retains largest installed base among academic neuroscience labs, though REACH authorization delays for dibenzyl ether threaten European supply.
- SMART:Switchable milky rapid immunolabeling compatible with tissue-clearing. 72-hour turnaround validated at contract research organizations for toxicity assessment, gaining share in industrial settings.
- PACT:Passive clarity technique using passive diffusion without electrophoresis. Simpler equipment requirements suit resource-constrained labs, though optical quality trails active methods.
iDISCO retains volume leadership. SMART presents the steepest expansion trajectory in pharmaceutical workflows.
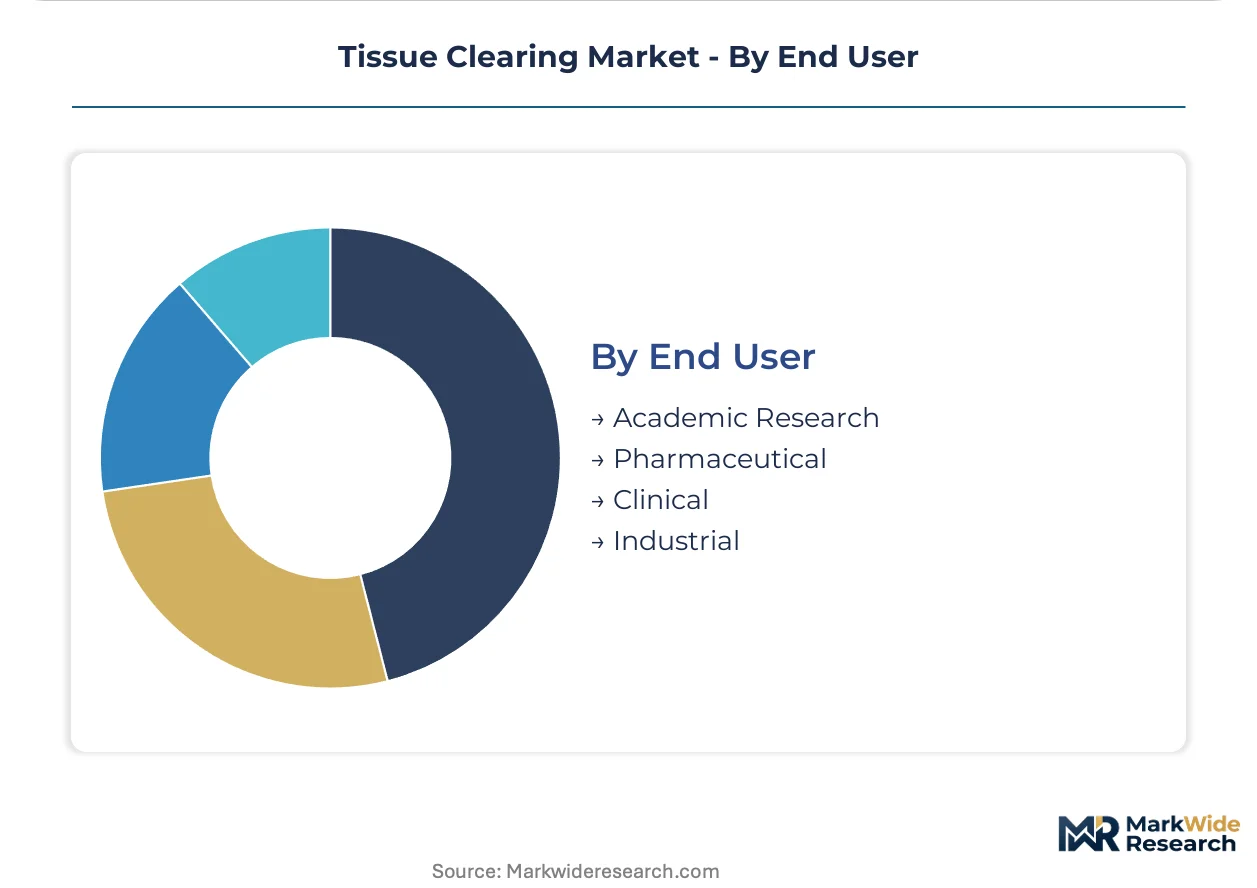
End User:
Customer type determines margin structure: academic buyers prioritize grant-funded instrument acquisitions, while pharmaceutical procurement emphasizes operational expenditure predictability.
- Academic Research:Grant-dependent procurement concentrated at NIH-funded institutions. Shared instrumentation grants create hub-and-spoke expertise distribution, with Harvard and Stanford core facilities training external users.
- Pharmaceutical:Preclinical screening pipeline integration requires FDA 21 CFR Part 11 compliant software validation. IND-enabling toxicology studies demand ISO 13485-certified protocol transfer from reagent vendors.
- Clinical:Diagnostic translation remains exploratory. Pathology departments evaluate cleared-tissue tumor margin assessment, constrained by CAP laboratory accreditation requirements for novel methods.
- Industrial:Contract research organizations and biotechnology companies. Outsourcing trends concentrate clearing expertise at specialized providers offering GLP-validated workflows.
Academic Research anchors current revenue. Pharmaceutical end-use is expanding most quickly as industrial validation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tissue clearing protocols originated in California academic laboratories during the early 2010s, with Stanford and MIT establishing the foundational hydrogel-embedding methods that scaled into commercial workflows. Federal funding concentration and specialized core facility networks now shape geographic procurement patterns.
United States
NIH Brain Initiative grants to Johns Hopkins, Columbia, and MIT sustain the world's densest concentration of whole-organ imaging installations. FDA 21 CFR Part 11 compliance requirements push pharmaceutical buyers toward validated instrument-reagent bundles. The Allen Institute in Seattle and Harvard's Neurobiology Imaging Facility anchor service-based revenue models through protocol consulting to smaller institutions.
Germany
Max Planck Institute neuroscience clusters in Munich and Tübingen drive demand for subcellular resolution clearing systems. ECHA REACH authorization timelines for dibenzyl ether now extend 18 months, forcing academic buyers toward aqueous urea alternatives. Carl Zeiss microscopy installations in Jena and Oberkochen create regional service hubs for cleared-tissue imaging workflows.
United Kingdom
Francis Crick Institute and University College London core facilities concentrate expertise in connectomics applications. MHRA alignment with FDA digital data integrity standards shapes vendor software validation requirements for preclinical contract research. Cambridge biotechnology corridor companies now outsource clearing protocols to specialized providers rather than maintaining in-house capability.
Japan
RIKEN Brain Science Institute in Wako and University of Tokyo neuroscience departments import hydrogel-embedding reagents for large-scale brain mapping initiatives. PMDA preclinical consultation pathways increasingly reference cleared-tissue toxicology data, creating compliance documentation burdens for reagent vendors. Osaka-based pharmaceutical companies validate rapid-clearing workflows for embryonic toxicity screening.
Switzerland
ETH Zurich and University of Basel microscopy core facilities specialize in organoid-compatible clearing chemistries for human brain model research. Swissmedic clinical trial authorization requirements constrain diagnostic translation pathways for cleared-tissue tumor margin assessment. Roche Genentech's Basel operations have validated 72-hour clearing-to-imaging protocols for internal toxicity screening pipelines.
Tissue Clearing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation depth, with FDA 21 CFR Part 11 compliant software and ISO 13485 certification separating pricing tiers. The vendor base spans three strategic archetypes: diversified life sciences distributors with broad channel reach, specialized clearing chemistry developers with protocol expertise, and integrated instrument-reagent bundlers serving multi-site consortia. Dominant competitive moves include strategic partnerships between reagent manufacturers and light-sheet microscope vendors, plus vertical integration into GLP validation services for IND-enabling studies.
Among diversified distributors, Thermo Fisher Scientific occupies a position exemplifying scale-driven penetration across NIH-funded research consortia requiring standardized workflows. LifeCanvas Technologies and Miltenyi Biotec represent specialization archetypes, with the former anchoring organoid-compatible chemistry development and the latter integrating clearing protocols with magnetic cell separation installed bases. ClearLight Biotechnologies and Visikol Inc. sit within the service-oriented tier, commercializing protocol optimization expertise to institutions lacking in-house clearing capability.
| Leading Market Players |
|---|
| Logos Biosystems |
| LifeCanvas Technologies |
| Miltenyi Biotec |
| Visikol Inc. |
| ClearLight Biotechnologies |
| Bio-Techne |
| Abcam plc |
| Thermo Fisher Scientific |
| Corning Incorporated |
| Others |
Value Network & Pricing Analysis
Backward integration into hydrogel monomer production anchors supply security for CLARITY protocol vendors while simultaneously insulating premium pricing tiers from dibenzyl ether volatility. Captive manufacturing of refractive index-matching solvents allows reagent suppliers serving NIH-funded consortia to maintain margin stability despite ECHA REACH authorization delays disrupting European competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11 validated bundles from research-grade reagent-only sales. Price differentiation hinges on ISO 13485 certification status and multi-site protocol standardization support. Cost compression in solvent-based clearing tiers is intensifying because Chinese specialty chemical exporters face EPA TSCA reporting burdens. Academic core facilities exhibit highest price sensitivity; pharmaceutical toxicology screening operations demonstrate lowest sensitivity due to IND-enabling study requirements.
Supply Chain Analysis
ISO 13485 certification gating restricts qualified reagent manufacturing to the United States, Germany, and Japan, with Swiss specialty chemical houses capturing organoid-compatible niche formulations. Raw material dependencies center on acrylamide monomers, dibenzyl ether, and high-purity urea. Single-source vulnerability concentrates in Chinese benzyl alcohol exports subject to tariff exposure. Distribution runs through life sciences distributors with cold-chain logistics capability and direct core facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate where ECHA REACH timelines stretch 18 months against FDA digital integrity pathways measured in quarters, rewarding suppliers with dual-hemisphere validation assets.
For Market Incumbents: Acquire GLP validation service capabilities to defend against contract research organization vertical integration into protocol optimization. Secure captive supply of hydrogel monomers through backward integration into acrylamide manufacturing. ISO 13485 certification investment represents the critical lever for pharmaceutical pricing tier access. For New Entrants and Emerging Players: Capture organoid clearing white space above 500 microns where human brain model demand outstrips specialized chemistry supply. Human brain organoid applications present the most penetrable segment. Pursue direct sales to ETH Zurich and University of Basel microscopy cores as reference anchor accounts. For Investors and Strategic Acquirers: Consolidation pressure builds where protocol reproducibility failures invalidate multi-site studies and drive outsourcing to specialized providers. Five-to-ten year viability favors service-oriented models with recurring revenue streams over capital-intensive instrument manufacturing. Signal to monitor: FDA premarket notification pathway expansion for cleared-tissue diagnostic applications.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Validation Service Acquisition | Enables IND-enabling toxicology study revenue capture at Charles River and WuXi AppTec. |
| Hydrogel Monomer Backward Integration | Secures CLARITY protocol supply chain against Chinese acrylamide export volatility. |
| SMART Protocol Licensing Agreement | Accelerates 72-hour turnaround validation at Roche Genentech and Pfizer screening pipelines. |
| Organoid-Compatible Chemistry R&D Partnership | Addresses ETH Zurich and Allen Institute demand for human brain model transparency. |
| Multi-Site Protocol Standardization Program | Supports NIH Brain Initiative consortia requiring lot-to-lot consistency across Johns Hopkins and MIT. |
Research Methodology
Direct dialogue with core facility directors, reagent procurement managers at pharmaceutical toxicology units, light-sheet microscope service engineers, and regulatory affairs specialists at contract research organizations grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, ECHA REACH registration dossiers, NIH RePORTER grant databases, and ISO 13485 certification registries. Bottom-up and top-down triangulation reconciled instrument installation counts with reagent shipment volumes.
Bottom-up modeling segmented addressable demand across reagent, instrument, kit, and service categories, with neuroscience, pharmacology, cancer research, and histology applications tracked separately. Hydrogel-embedding, solvent-based, and rapid-clearing technology penetration rates informed volume assumptions across the projection horizon. CAGRs were derived from NIH funding trajectory analysis and pharmaceutical preclinical pipeline expansion rates.
Regulatory authorization delays, antibody validation failure rates, and core facility concentration risk are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA diagnostic pathway guidance for cleared-tissue applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Biologics Outsourcing Market