
 Multiomics Market | 2026-2036
Multiomics Market Size, Share, and Industry Trends Forecast 2026-2036
Multiomics Market Analytics
Pharmaceutical end-user demand is pivoting toward integrated multi-platform workflows that unify genomic, proteomic, and metabolomic data streams. Thermo Fisher Scientific leverages its Orbitrap mass spectrometry portfolio to anchor high-throughput proteomics workflows for drug discovery labs. Illumina competes by extending its sequencing dominance into multi-modal assay development through its cloud-native analysis environment. QIAGEN differentiates with sample-to-insight automation that reduces hands-on time in clinical translation settings.
Multiomics denotes the simultaneous measurement and integrative analysis of multiple molecular layers—DNA, RNA, proteins, and metabolites—typically requiring mass spectrometry resolution below 5 ppm, next-generation sequencing depth exceeding 30x coverage, and bioinformatics pipelines capable of cross-omic statistical modeling. Its primary purpose is to generate systems-level biological insight for therapeutic target validation and patient stratification. Genomics retains the largest revenue share as the foundational data layer, yet metabolomics represents the fastest-expanding segment due to its proximity to phenotypic endpoints and diagnostic utility. Mass spectrometry technology commands premium pricing in proteomics and metabolomics applications, while bioinformatics emerges as the critical margin pool where recurring software licensing outpaces instrument sales cycles.
The FDA regulates multiomics-based companion diagnostics through its in vitro diagnostic pathway, while the EMA's In Vitro Diagnostic Regulation enforces clinical analytical validity standards across European markets. China's NMPA accelerates review timelines for innovative multi-omic diagnostic products under its breakthrough device designation. Stakeholders must monitor how divergent data localization requirements and cross-border genomic sample transfer restrictions reshape platform deployment strategies and partnership architectures.
Market Dynamics
Pharmaceutical procurement teams now mandate unified data architectures that collapse genomic, proteomic, and metabolomic analysis into single vendor relationships, compressing traditional multi-supplier workflows and reshaping competitive positioning around platform breadth rather than point-solution performance.
Growth Catalysts
- Breakthrough device pathways:China's NMPA accelerates review timelines for multi-omic diagnostics, pulling clinical translation timelines forward by 12-18 months for domestic innovators.
- Cloud-native bioinformatics:AI-driven data integration platforms reduce analysis cycles from weeks to days, enabling pharmaceutical discovery teams to iterate target validation faster.
- National biobank infrastructure:Germany's National Cohort and the US All of Us Research Program generate standardized sample repositories that anchor multiomics demand.
Market Restraints
- Mass spectrometer supply concentration:High-resolution Orbitrap and triple-quadrupole instruments depend on three specialized manufacturing clusters in Germany, Massachusetts, and California.
- Cross-border sample transfer restrictions:GDPR genomic data localization requirements and China's biosecurity law fragment global clinical trial workflows.
- Specialized talent scarcity:Computational biologists capable of cross-omic statistical modeling command compensation premiums that inflate operational overhead.
Strategic Opportunities
- Clinical metabolomics expansion:Proximity to phenotypic endpoints positions metabolite profiling for companion diagnostic partnerships in oncology and metabolic disease.
- Sample-to-insight automation:Integrated liquid-handling and analysis platforms reduce hands-on time in hospital pathology labs, opening clinical adoption beyond academic centers.
- India's PLI scheme:Production-linked incentives for medical device manufacturing attract multiomics instrument assembly and reagent formulation to domestic facilities.
Industry Challenges
- Interoperability standards lag:Absence of unified file formats for cross-omic data integration forces custom pipeline development for each pharmaceutical partner.
- ISO 15189 accreditation timelines:Clinical laboratories face 18-24 month validation cycles for multi-omic test menus, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiomics Market |
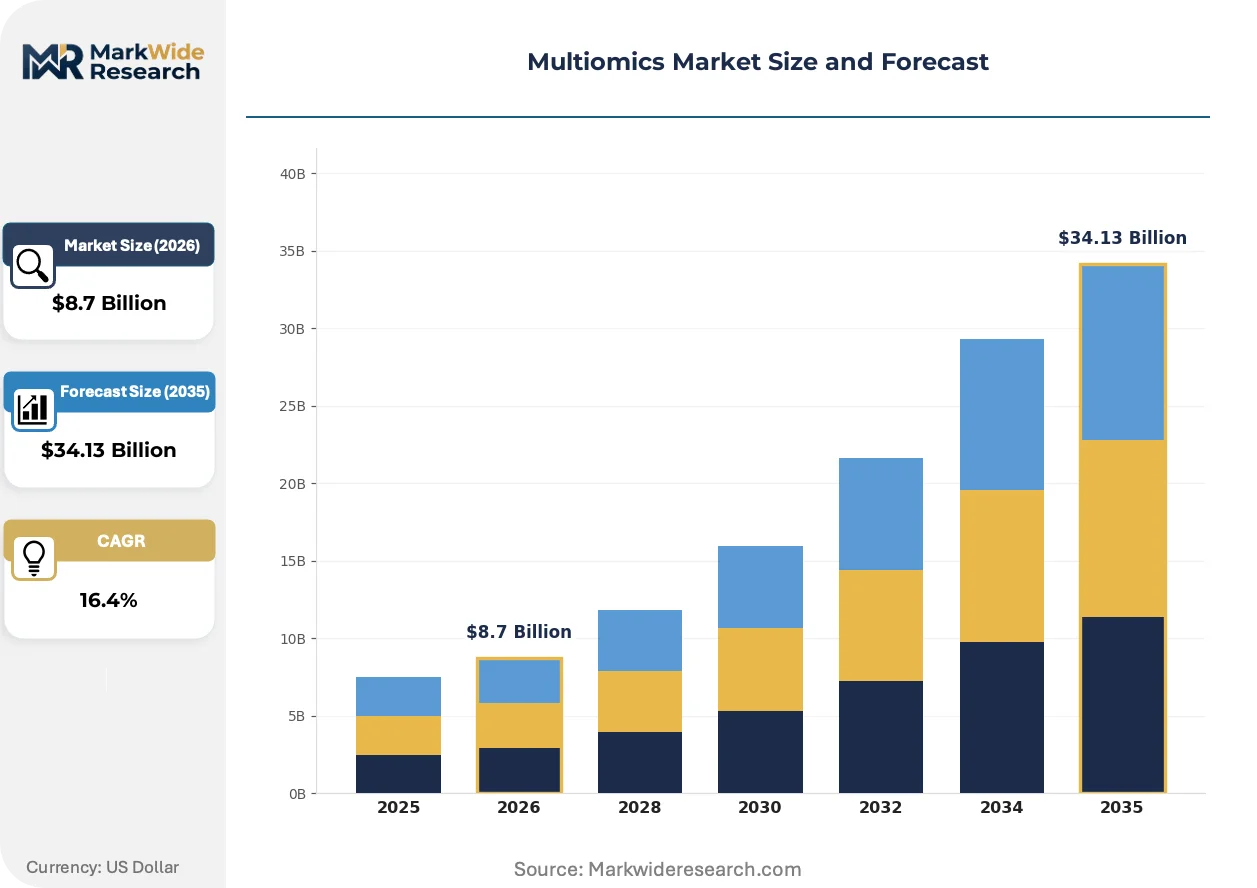
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genomics, Transcriptomics, Proteomics, Metabolomics Technology: Next-Generation Sequencing, Microarrays, Mass Spectrometry, Bioinformatics End User: Pharmaceutical Companies, Academic Research Institutes, Contract Research Organizations, Biotechnology Companies Application: Drug Discovery, Biomarker Identification, Personalized Medicine, Disease Diagnosis |
| Companies Covered | Thermo Fisher Scientific, Illumina, Agilent Technologies, QIAGEN, Bruker Corporation, BD, Danaher, BGI Genomics, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiomics Market Evolving Landscape
Artificial intelligence architectures trained on multi-modal biological data are compressing target identification timelines and forcing reagent suppliers to embed predictive analytics directly into instrument control software.
Single-cell multi-omic sequencing platforms are rewriting how pharmaceutical discovery teams validate therapeutic hypotheses. Large-molecule biologics pipelines at Sanofi and Roche deploy these systems to map tumor microenvironment heterogeneity. The technology is compressing preclinical target validation from multi-year programs into 6-9 month iterations.
The FDA's in vitro diagnostic pathway now explicitly addresses multi-omics-based companion diagnostics through pre-submission meetings that clarify analytical validity requirements. European markets face parallel EMA In Vitro Diagnostic Regulation enforcement that demands clinical evidence packages spanning multiple molecular layers. Oncology therapeutic areas absorb the heaviest compliance burden as sponsors navigate divergent evidentiary standards.
Pharmaceutical procurement teams now unbundle instrument purchases from reagent supply agreements, forcing vendors to compete on per-sample consumable economics rather than capital equipment financing. Thermo Fisher and Illumina respond with outcome-based service contracts that guarantee throughput metrics. This behavior shift concentrates in the United States and Germany where centralized procurement functions possess sufficient volume leverage.
Multiomics Market Segmentation
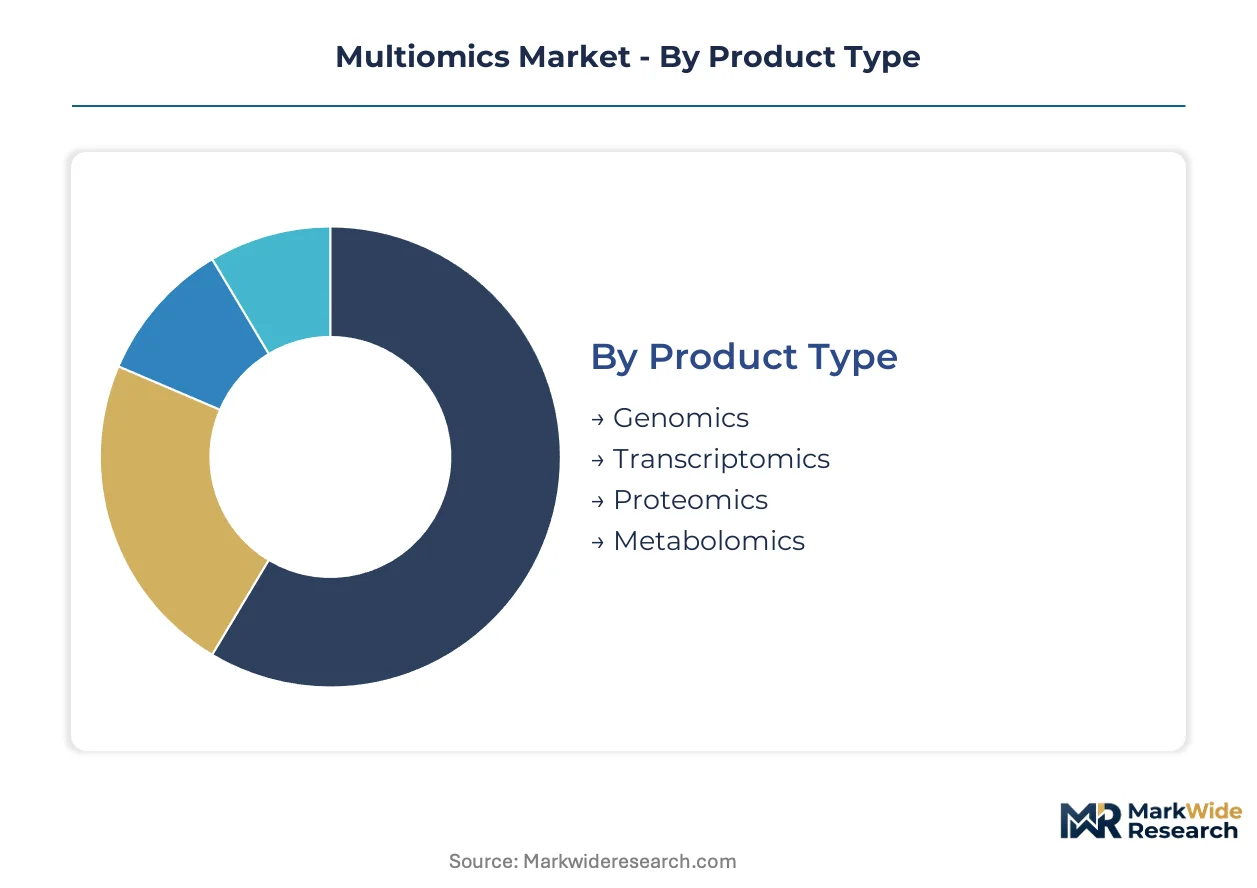
Multiomics market segmentation reveals how pharmaceutical procurement teams prioritize platform breadth over point-solution performance. Vendors must align product architectures with unified data architectures that compress genomic, proteomic, and metabolomic workflows into single vendor relationships.
Product Type:
Standardization dominates genomics and transcriptomics, while proteomics and metabolomics retain customization intensity due to sample preparation variability and analytical complexity.
- Genomics:DNA sequencing and variant analysis form the foundational data layer for multiomic integration. Pharmaceutical companies in the United States and Germany anchor demand through precision medicine pipelines requiring high-throughput genomic infrastructure.
- Proteomics:Mass spectrometry-based protein quantification demands specialized sample preparation and instrument calibration. Academic research institutes in China drive procurement of high-resolution platforms for translational research programs.
- Transcriptomics:RNA sequencing captures gene expression dynamics across disease states. Contract research organizations leverage standardized RNA-seq workflows to compress project timelines for pharmaceutical clients.
- Metabolomics:Small-molecule profiling offers proximity to phenotypic endpoints for diagnostic applications. Biotechnology companies in Germany concentrate demand for clinical metabolomics platforms targeting companion diagnostic development.
Leading the category by volume: Genomics. Expanding most quickly: Metabolomics.
Technology:
Instrument capital intensity separates sequencing and mass spectrometry from software-only bioinformatics solutions, creating divergent margin structures and sales cycles.
- Next-Generation Sequencing:High-throughput DNA and RNA analysis platforms achieve depth exceeding 30x coverage for clinical-grade variant detection. China's NMPA breakthrough device pathway accelerates regulatory clearance for domestic sequencing innovators.
- Mass Spectrometry:Orbitrap and triple-quadrupole systems deliver sub-5 ppm resolution for proteomic and metabolomic applications. Manufacturing concentration in Germany, Massachusetts, and California creates supply vulnerability for global pharmaceutical procurement.
- Microarrays:Hybridization-based detection offers cost-effective expression profiling for targeted gene panels. Academic centers with constrained capital budgets retain microarray infrastructure for routine screening applications.
- Bioinformatics:Cloud-native analysis platforms enable cross-omic statistical modeling without local compute investment. Recurring software licensing outpaces instrument sales cycles as pharmaceutical teams prioritize AI-driven data integration.
Dominating revenue contribution: Next-Generation Sequencing. Steepest expansion trajectory: Bioinformatics.
End User:
Procurement sophistication varies sharply—pharmaceutical companies mandate outcome-based contracts while academic institutes prioritize capital financing flexibility.
- Pharmaceutical Companies:Integrated multi-platform workflows unify genomic, proteomic, and metabolomic data streams for target validation. Centralized procurement functions in the United States and Germany unbundle instrument purchases from reagent supply agreements.
- Academic Research Institutes:National biobank initiatives in Germany's National Cohort and the US All of Us Research Program generate standardized sample repositories. Grant-funded procurement favors modular platforms with upgrade pathways.
- Contract Research Organizations:Sample-to-insight automation reduces hands-on time to compete for pharmaceutical outsourcing contracts. ISO 15189 accreditation timelines of 18-24 months constrain clinical service expansion.
- Biotechnology Companies:Single-cell multi-omic sequencing platforms compress preclinical target validation timelines. Venture-backed firms in Massachusetts and California concentrate demand for flexible instrument financing.
Commanding largest procurement volume: Pharmaceutical Companies. Gaining share fastest: Contract Research Organizations.
Application:
Regulatory pathway complexity stratifies applications—companion diagnostics face FDA and EMA evidentiary demands while research-use-only discovery operates with lighter compliance burdens.
- Drug Discovery:Systems-level biological insight accelerates therapeutic target validation through cross-omic statistical modeling. Sanofi and Roche deploy single-cell platforms to map tumor microenvironment heterogeneity in 6-9 month iteration cycles.
- Personalized Medicine:Patient stratification requires clinical analytical validity across multiple molecular layers. EMA In Vitro Diagnostic Regulation enforcement demands evidence packages spanning DNA, RNA, protein, and metabolite measurements.
- Biomarker Identification:Multi-omic signature development supports companion diagnostic partnerships in oncology. GDPR genomic data localization requirements fragment European clinical trial workflows.
- Disease Diagnosis:Metabolite profiling proximity to phenotypic endpoints positions clinical metabolomics for metabolic disease applications. China's biosecurity law restricts cross-border sample transfer for diagnostic development.
Generating highest revenue concentration: Drug Discovery. Climbing the fastest: Personalized Medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square biotech corridor and China's Zhangjiang Hi-Tech Park concentrate multiomics R&D investment through tax-advantaged zones purpose-built for life sciences infrastructure. National genomic medicine programs in Germany and the United States anchor demand through centralized procurement of integrated platforms.
United States
The All of Us Research Program generates standardized biobank repositories that drive instrument demand across academic medical centers. FDA breakthrough device designation pathways compress regulatory timelines for multi-omic companion diagnostics. Greater Boston and San Francisco Bay Area clusters concentrate venture-backed biotechnology firms deploying single-cell sequencing for tumor microenvironment mapping.
Germany
The National Cohort initiative anchors Europe's largest standardized population biobank, generating sustained demand for high-resolution mass spectrometry. EMA In Vitro Diagnostic Regulation enforces clinical analytical validity standards across proteomic and metabolomic applications. Munich and Heidelberg industrial clusters concentrate precision medicine startups targeting companion diagnostic development.
China
Zhangjiang Hi-Tech Park in Shanghai offers ten-year tax holidays for medical device R&D operations, concentrating domestic sequencing platform development. NMPA breakthrough device pathways accelerate review timelines by 12-18 months for innovative multi-omic diagnostics. Beijing and Shenzhen clusters host BGI Genomics and emerging competitors scaling cloud-native bioinformatics platforms.
India
Production-Linked Incentive schemes for medical device manufacturing attract multiomics instrument assembly to domestic facilities. CDSCO regulatory harmonization with ICH guidelines streamlines clinical trial approvals for genomic diagnostics. Hyderabad and Bengaluru biotech corridors concentrate contract research organizations offering ISO 15189-accredited multi-omic testing services.
United Kingdom
The UK Biobank's genomic and phenotypic data repository supports academic and commercial multiomics research programs. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for innovative diagnostics. Cambridge and Oxford clusters concentrate spin-out companies commercializing single-cell transcriptomics platforms for drug discovery.
Multiomics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium pricing in pharmaceutical procurement while modular suppliers serve academic grant-funded budgets. Market structure tilts toward consolidation at the instrument layer—mass spectrometry and sequencing hardware—while bioinformatics software retains fragmentation. Three archetypes dominate: diversified life sciences conglomerates with cross-omic portfolios, pure-play sequencing specialists, and sample-to-insight automation vendors. Competitive moves center on unbundling instrument-reagent contracts and outcome-based service guarantees that lock in multi-year pharmaceutical relationships.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher exemplify platform-breadth strategies that collapse genomic, proteomic, and metabolomic workflows into single vendor relationships. Illumina occupies a sequencing-dominant position extending into multi-modal assay development through cloud-native environments. QIAGEN represents the sample-to-insight automation archetype, reducing hands-on time in clinical translation settings through integrated liquid-handling and analysis platforms. These three anchors illustrate how procurement sophistication now favors unified data architectures over point-solution performance.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Agilent Technologies |
| QIAGEN |
| Bruker Corporation |
| BD |
| Danaher |
| BGI Genomics |
| Bio-Rad Laboratories |
| Others |
Value Network & Pricing Analysis
EMA In Vitro Diagnostic Regulation compliance gates qualified supply access for premium-tier multiomics platforms, forcing pharmaceutical procurement teams to pay certification premiums for clinical-grade mass spectrometry and sequencing instruments while filtering out uncertified economy-tier alternatives.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, compressing margins for manufacturers holding spot inventory of Orbitrap mass spectrometers and next-generation sequencers. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 15189 accreditation status and after-sales service bundling. Pricing pressure stems from pharmaceutical procurement teams unbundling instrument-reagent contracts to force consumable-only economics. Academic research institutes exhibit highest price sensitivity due to grant-funded capital constraints, while centralized pharmaceutical procurement functions leverage volume for outcome-based service guarantees.
Supply Chain Analysis
India's Production-Linked Incentive scheme for medical device manufacturing reshapes sourcing patterns by mandating domestic-content thresholds for multiomics instrument assembly and reagent formulation. Manufacturing gravity centers on Germany for precision mass spectrometry components, Massachusetts for sequencing platform final assembly, and California for cloud-native bioinformatics development. Supply chains draw from specialized rare-earth magnet suppliers, high-purity solvent manufacturers, and semiconductor foundries producing detector arrays. Single-source vulnerability concentrates in ion trap manufacturing for Orbitrap systems. Distribution runs through direct pharmaceutical procurement channels, academic purchasing consortia, and contract research organization vendor qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometer manufacturing capacity constraints prop pricing power for qualified suppliers, as three specialized production clusters in Germany, Massachusetts, and California cannot scale to match pharmaceutical demand acceleration.
For Market Incumbents: Acquire cloud-native bioinformatics platforms to anchor recurring revenue streams against instrument sales cyclicality. Consolidate reagent supply agreements through outcome-based throughput guarantees that lock in multi-year pharmaceutical relationships. Defend against emerging sample-to-insight automation specialists by embedding predictive analytics directly into instrument control software. Prioritize ISO 15189 certification investment to maintain premium-tier access under EMA enforcement. For New Entrants and Emerging Players: Contract research organizations represent the most penetrable channel partner type for bypassing capital-intensive instrument manufacturing. Target India's PLI-subsidized manufacturing zones for reagent formulation and consumables production to avoid direct competition with established hardware vendors. Exploit clinical metabolomics white space in metabolic disease companion diagnostics where regulatory pathways remain less crowded than oncology. Deploy AI-driven data integration as the primary go-to-market differentiator against legacy platform vendors. For Investors and Strategic Acquirers: NMPA breakthrough device approvals for domestic Chinese multi-omic diagnostics is the leading indicator that regulatory arbitrage opportunities are compressing and capital should rotate toward platform-integrated players. Five-to-ten year viability favors diversified conglomerates with cross-omic portfolios over pure-play sequencing specialists facing margin erosion. Acquisition target archetype: sample-to-insight automation vendors with ISO 15189-accredited clinical service infrastructure. Watch for FDA pre-submission meeting volume for multi-omics companion diagnostics as the inflection signal for regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Bioinformatics Acquisition | Recurring software licensing outpaces instrument sales cycles at Thermo Fisher and Illumina. |
| ISO 15189 Accreditation Expansion | Clinical laboratories in Germany and the United States compress 18-24 month validation timelines. |
| India PLI Manufacturing Localization | Domestic assembly of mass spectrometry components reduces tariff exposure for global vendors. |
| AI-Driven Data Integration Partnership | Pharmaceutical discovery teams iterate target validation from weeks to days through predictive analytics. |
| Single-Cell Multi-Omic Platform Launch | Sanofi and Roche deploy tumor microenvironment mapping in 6-9 month preclinical cycles. |
Research Methodology
SEC 10-K filings, FDA 510(k) clearance databases, and EMA In Vitro Diagnostic Regulation guidance documents formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with pharmaceutical procurement executives, clinical laboratory directors, regulatory affairs specialists, and bioinformatics platform engineers validated demand assumptions and pricing dynamics. Bottom-up triangulation across instrument shipment data, reagent consumption patterns, and software licensing disclosures converged with top-down analysis of national biobank program budgets and precision medicine initiative funding.
Historical trendline analysis of genomics, proteomics, transcriptomics, and metabolomics segment revenue trajectories established baseline growth patterns across the projection horizon. The analytical framework modeled technology type, end-user procurement sophistication, application regulatory burden, and regional reimbursement pathway maturity as core segmentation dimensions. CAGRs derived from fitted growth curves incorporated pharmaceutical pipeline expansion rates, cloud-native platform adoption velocity, and clinical metabolomics diagnostic validation timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen GDPR enforcement actions restricting cross-border genomic data transfer, abrupt NMPA policy shifts affecting breakthrough device eligibility, and supply chain disruptions from rare-earth magnet export restrictions. Forecasts reflect documented assumptions regarding regulatory pathway stability and manufacturing cluster operational continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Gene Amplification Technologies Market
Genomics
Reproductive Genetics Market
Genomics
Nutrigenomics Testing Market
Genomics
Next Generation Sequencing Market
Genomics
Microarray Biochips Market
Genomics
Genomics Personalized Health Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Agrigenomics Market
Genomics
Cytogenetic Systems Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Genotyping Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Digital Genome Market
Genomics
Genomic Biomarkers Market