
 Japan Gene Editing Market | 2026-2036
Japan Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Gene Editing Market Insights
The capability gap between capital-heavy platform developers and lean service providers is collapsing as gene editing commoditizes. Takara Bio Inc. leverages its domestic manufacturing footprint to control reagent supply chains. Merck KGaA anchors its position through integrated CRISPR licensing and synthetic biology workflows. Thermo Fisher Scientific, Inc. competes by extending its sequencing-to-editing instrument ecosystem into Japanese research institutions.
Gene editing encompasses programmable nuclease systems that introduce site-specific DNA modifications through engineered molecular machinery, with CRISPR-Cas9 complexes requiring guide RNA design and protospacer-adjacent motif recognition for functional targeting. The technology serves therapeutic development, crop trait engineering, and microbial strain optimization across industrial bioprocessing. CRISPR product lines dominate current revenue given their experimental accessibility and multiplexing capacity. Therapeutics application segments attract premium R&D allocations as allogeneic cell therapy pipelines mature. Delivery systems technology represents the fastest-evolving capability layer, with lipid nanoparticle and viral vector platforms determining clinical translation success.
PMDA review timelines and METI industrial biotechnology incentives jointly shape commercialization pathways for domestic developers. JIS standards for biomanufacturing quality and the Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices establish compliance thresholds for clinical-grade materials. Stakeholders must monitor regulatory harmonization between PMDA and FDA gene therapy guidelines, as divergence in insertional mutagenesis risk assessment could fragment trial design strategies.
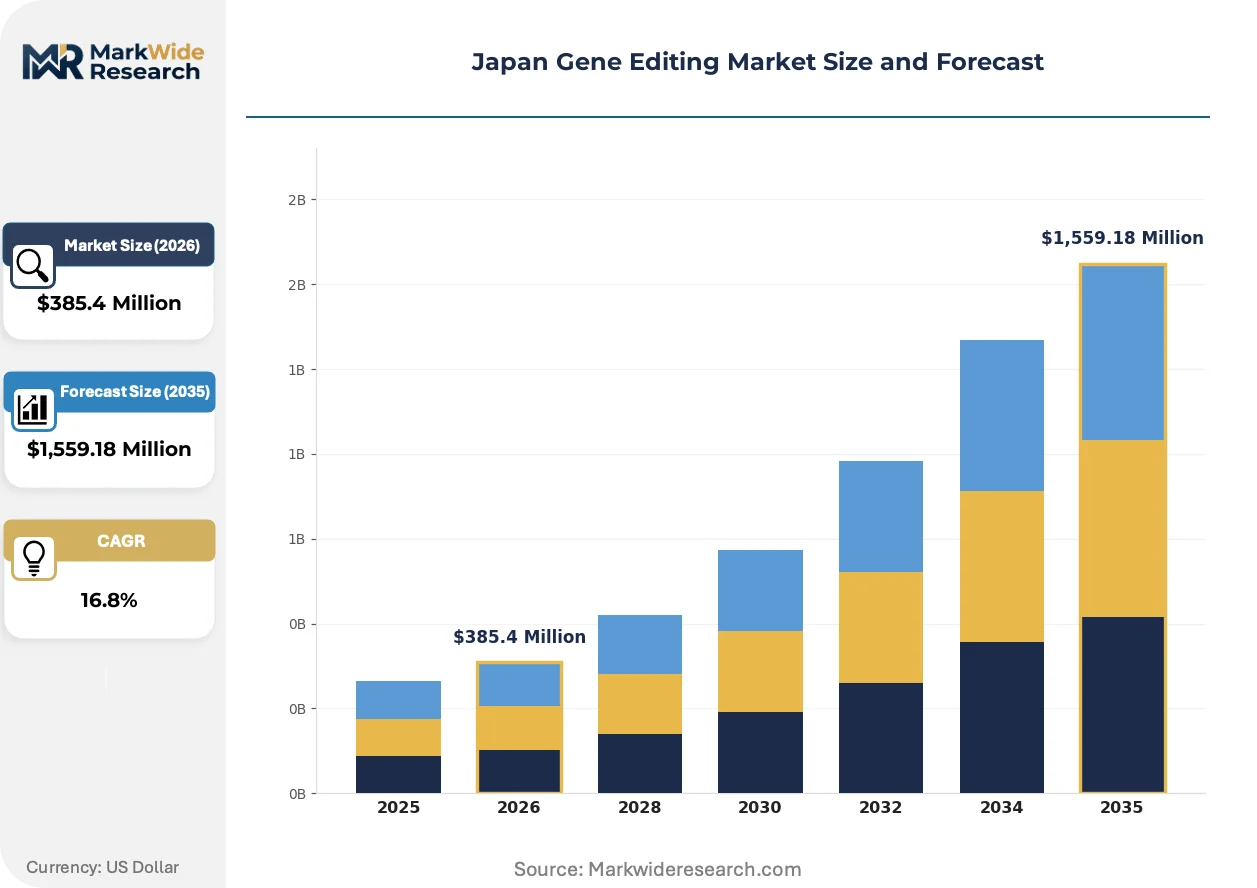
Market Dynamics
Base editing and prime editing platforms are compressing the capability advantage once held by first-generation CRISPR-Cas9 systems, forcing platform developers to defend differentiation through delivery technology rather than nuclease architecture alone.
Growth Catalysts
- PMDA streamlined review pathways:Japan's revised Act on Regulation of Human Cloning Techniques accelerates IND timelines for gene-edited cell therapies, cutting preclinical-to-Phase I intervals for domestic sponsors.
- Oncology pipeline maturation:Allogeneic CAR-T developers in the Kanto region are scaling GMP manufacturing for CRISPR-edited donor cells, creating pull-through demand for clinical-grade reagents.
- METI industrial biotechnology incentives:Tax credits for microbial strain optimization projects drive adoption of multiplexed editing in precision fermentation and enzyme engineering.
Market Restraints
- Guide RNA synthesis cost volatility:Phosphoramidite raw material prices fluctuate with semiconductor foundry demand, squeezing margins for high-throughput screening services.
- Supply concentration in viral vectors:AAV manufacturing capacity concentrates among three contract developers globally, creating bottlenecks for in vivo therapeutic candidates.
- Insertional mutagenesis risk assessment divergence:PMDA and FDA guidelines differ on off-target analysis stringency, fragmenting trial design for sponsors pursuing parallel filings.
Strategic Opportunities
- Underserved agricultural applications:Gene-edited crop traits face lighter regulatory burden than transgenics under Japan's Cartagena Protocol implementation, opening avenues for domestic seed developers.
- Base editing convergence with mRNA delivery:Combining cytosine or adenine base editors with lipid nanoparticle platforms enables transient editing without permanent nuclease expression.
- University hospital channel expansion:Direct partnerships with Tokyo and Osaka academic medical centers bypass distributor markups for research-use reagents.
Industry Challenges
- Bioinformatics talent scarcity:Guide RNA design and off-target prediction require computational biology expertise that outpaces domestic training pipeline output.
- GMP facility certification timelines:JIS Q 13485 compliance for cell therapy manufacturing extends facility qualification periods, delaying revenue recognition for CDMO projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Gene Editing Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,559.18 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, TALEN, ZFN, RNAi Application: Medical Research, Agricultural Biotechnology, Therapeutics, Industrial Biotechnology End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Academic Centers Technology: Sequencing, Gene Synthesis, Vector Development, Delivery Systems |
| Companies Covered | Takara Bio Inc., Merck KGaA, Takeda Pharmaceutical Company, Fujifilm Corp., Astellas Pharma Inc., Revvity, Inc., Danaher Corporation, GenScript, Thermo Fisher Scientific, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Gene Editing Market Trends and Innovations
Prime editing systems are compressing the editing precision gap with base editors while expanding the range of possible modifications beyond single-nucleotide changes. Three developments are restructuring competitive positioning.
Prime editing is displacing conventional HDR-dependent knock-in methods for precise gene correction. Pharmaceutical developers in the Tokyo-Osaka corridor are adopting prime editor ribonucleoprotein complexes for rare disease pipeline targets. The technology is displacing reliance on donor template DNA, simplifying regulatory pathways for clinical-grade editing.
METI's 2023 revision to the Act on Regulation of Human Cloning Techniques clarified the regulatory status of mitochondrial replacement therapies and germline editing research. Industrial sponsors now navigate a bifurcated approval track separating somatic cell therapies from reproductive applications. The clarification most affects allogeneic iPSC-derived product developers seeking clarity on donor cell editing scope.
Academic medical centers are consolidating procurement authority through shared purchasing consortia. The University of Tokyo Hospital and Osaka University Hospital now coordinate reagent sourcing through centralized tenders, displacing individual PI-driven purchasing. This concentration most visibly compresses pricing power for mid-tier reagent suppliers serving the Kansai region.
Japan Gene Editing Market Segmentation
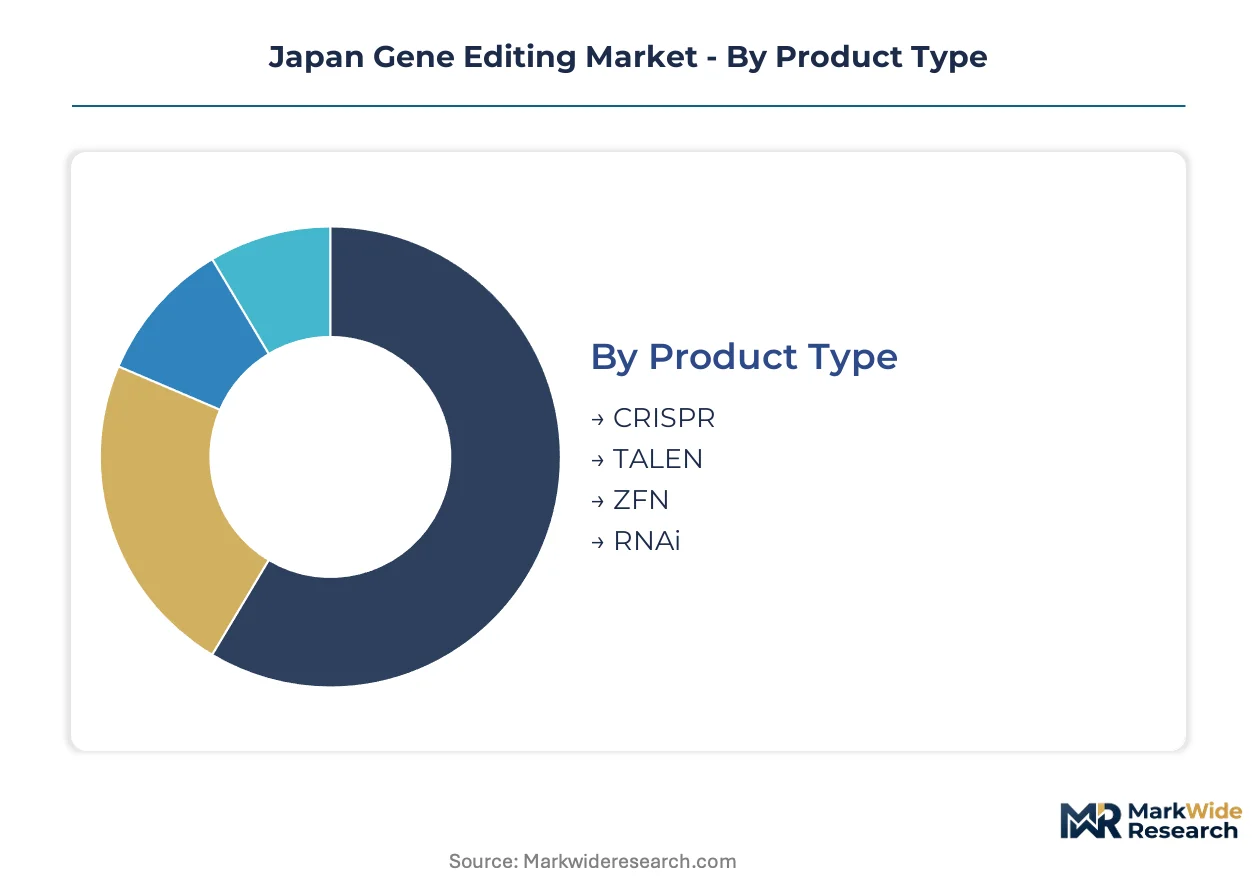
Gene editing market segmentation in Japan reflects divergent margin structures across platform technologies and application maturity. Product categories capture reagent economics while application segments determine regulatory pathway complexity and reimbursement potential.
Product Type:
CRISPR systems command premium pricing through IP licensing and guide RNA customization services, while legacy nuclease platforms defend position in therapeutic manufacturing contracts.
- CRISPR:CRISPR-Cas9 and derived systems (base editors, prime editors) dominate research procurement through accessible experimental design and multiplexing capability. Tokyo-Osaka academic medical centers concentrate demand for clinical-grade ribonucleoprotein complexes as allogeneic cell therapy pipelines advance. PMDA's streamlined IND pathways for gene-edited therapeutics reinforce CRISPR's central position in sponsor R&D budgets.
- TALEN:Transcription activator-like effector nucleases retain manufacturing relevance for therapeutic applications requiring reduced off-target liability. Kanto-region CDMOs specify TALEN architectures for GMP-grade cell engineering where regulatory stringency outweighs reagent cost considerations. The platform's protein-DNA recognition mechanism avoids guide RNA synthesis dependencies that fluctuate with phosphoramidite raw material markets.
- ZFN:Zinc finger nucleases persist in legacy therapeutic programs and certain viral vector manufacturing workflows where validated master cell banks limit platform switching costs.
- RNAi:RNA interference systems occupy a parallel therapeutic modality with distinct regulatory classification, serving applications where transient gene suppression suffices.
CRISPR holds installed capacity across Japanese research institutions. TALEN is rotating up the share rankings in clinical manufacturing specifications.
Application:
Volume concentration differs sharply from value concentration, with research applications driving unit sales while therapeutics capture multi-year contract values.
- Therapeutics:Gene-edited cell therapies and in vivo editing applications attract concentrated investment from pharmaceutical sponsors navigating PMDA review timelines. Allogeneic CAR-T developers in the Kanto region scale GMP manufacturing for donor-derived products, creating sustained demand for clinical-grade reagents and analytical validation services. METI biotechnology incentives further direct capital toward therapeutic translation.
- Medical Research:Academic and institutional research generates high-throughput demand for CRISPR screening libraries and functional genomics tools. University hospital consortia in Tokyo and Osaka now coordinate centralized procurement, compressing pricing power for mid-tier suppliers while expanding volume commitments to tier-one platform providers.
- Industrial Biotechnology:Microbial strain optimization for precision fermentation and enzyme engineering drives multiplexed editing adoption. Tax credits under METI industrial policy accelerate implementation.
- Agricultural Biotechnology:Gene-edited crop traits face lighter regulatory burden than transgenics under Japan's Cartagena Protocol implementation, creating openings for domestic seed developers.
Medical Research generates the highest transaction frequency. Therapeutics is climbing the fastest in revenue contribution per project.
End User:
Procurement authority centralization distinguishes institutional buyers from distributed academic purchasing, reshaping vendor channel strategies.
- Pharmaceutical Companies:Integrated drug developers in the Tokyo-Osaka corridor pursue captive editing capabilities or long-term CDMO partnerships for pipeline assets. These sponsors negotiate enterprise licensing for CRISPR platforms and invest in proprietary delivery technologies.
- Research Institutions:National research institutes and university-affiliated centers constitute high-volume, price-sensitive demand for research-use reagents. Shared purchasing consortia now aggregate procurement authority.
- Biotech Firms:Venture-backed developers concentrate in Kanto biotech clusters, outsourcing editing workflows to specialized service providers rather than building internal platforms.
- Academic Centers:Individual principal investigators retain limited direct purchasing authority as hospital systems consolidate reagent sourcing.
Pharmaceutical Companies anchor contract value. Research Institutions are expanding fastest in consolidated procurement volume.
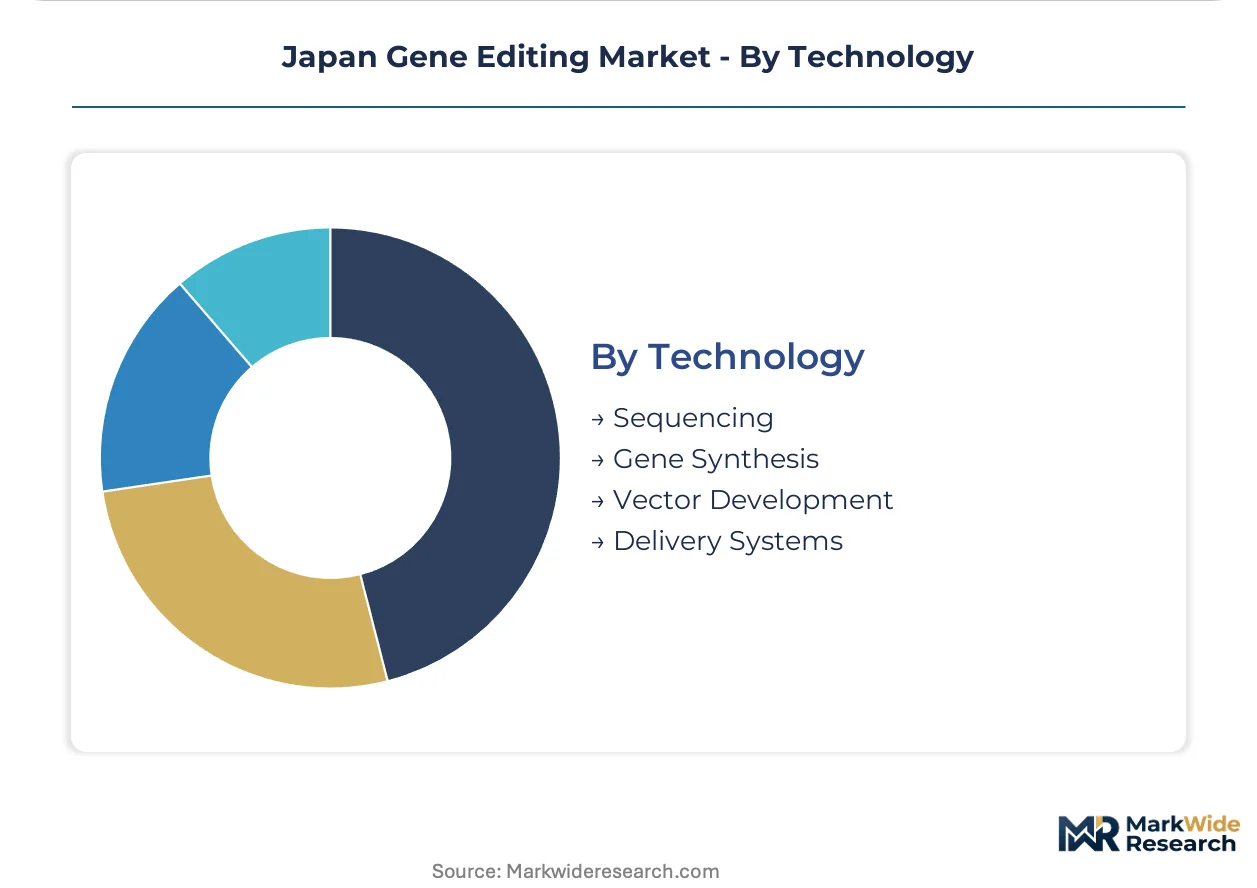
Technology:
Capability layering separates commodity reagent supply from differentiated platform integration, with delivery systems commanding the steepest technical premiums.
- Delivery Systems:Lipid nanoparticle and viral vector platforms determine clinical translation success for in vivo and ex vivo applications. AAV manufacturing capacity concentration among global contract developers creates supply bottlenecks that Japanese sponsors navigate through early partnership commitments.
- Sequencing:Next-generation sequencing integration with editing workflows enables high-throughput validation and off-target analysis. Thermo Fisher extends instrument ecosystems into Japanese research institutions.
- Gene Synthesis:Custom DNA manufacturing supports donor template production and guide library construction.
- Vector Development:Plasmid and viral vector engineering services underpin therapeutic manufacturing pipelines.
Sequencing holds installed capacity across analytical workflows. Delivery Systems is gaining share fastest as clinical candidates advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research institutions in Japan's peripheral prefectures exhibit acute price sensitivity to CRISPR reagent costs, while pharmaceutical sponsors in metropolitan clusters absorb premium pricing for clinical-grade materials without volume elasticity.
Kanto/Tokyo
The University of Tokyo Hospital and RIKEN institutes drive concentrated demand for high-throughput screening libraries. PMDA's streamlined IND pathways under the revised Act on Regulation of Human Cloning Techniques accelerate sponsor timelines. The Tsukuba Science City biotech cluster anchors GMP manufacturing partnerships for allogeneic cell therapy developers.
Kansai/Osaka
Osaka University Hospital coordinates centralized procurement consortia that aggregate reagent demand across multiple academic medical centers. METI biotechnology incentives direct capital toward therapeutic translation projects. The Osaka Bio Headquarters district concentrates venture-backed gene editing service providers serving pharmaceutical outsourcing contracts.
Chubu/Nagoya
Industrial biotechnology applications dominate regional demand, with precision fermentation developers leveraging multiplexed editing for microbial strain optimization. JIS Q 13485 certification requirements extend facility qualification timelines for local CDMO projects. The Nagoya pharmaceutical manufacturing corridor hosts contract developers integrating editing workflows into existing biologics infrastructure.
Kyushu
Agricultural biotechnology research generates demand for gene-edited crop trait development under lighter regulatory burden than transgenics. The country's Cartagena Protocol implementation distinguishes edited products from GMO classification. Fukuoka's startup ecosystem attracts seed developers targeting domestic rice and vegetable variety improvement.
Hokkaido
Marine biotechnology and cold-climate agricultural applications create niche demand for specialized editing platforms. Regional research institutes focus on fish breeding and dairy livestock trait optimization. Sapporo-based university hospitals maintain limited but growing procurement for research-use reagents in functional genomics programs.
Japan Gene Editing Market Competitive Landscape
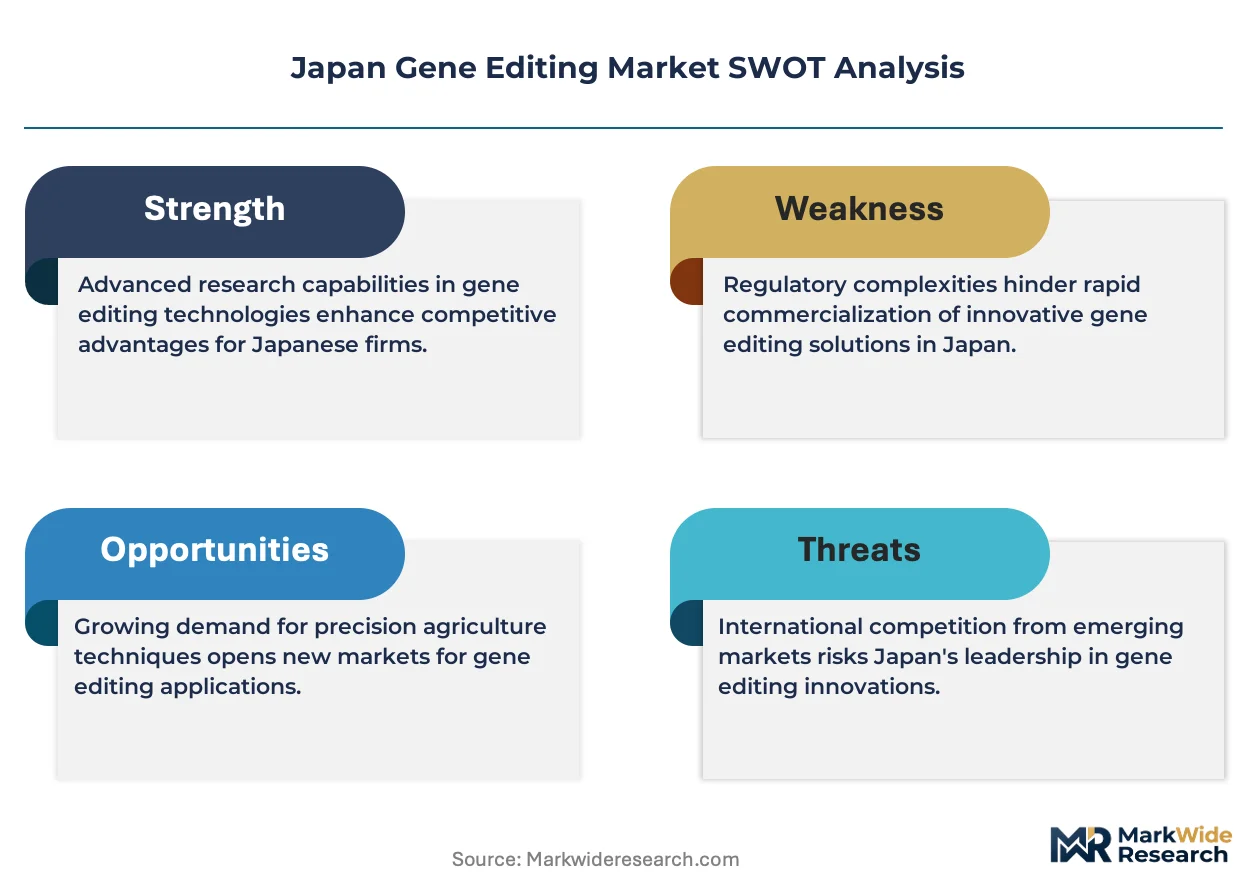
Technology leadership and cost leadership are held by different player archetypes, with platform developers commanding premium licensing fees while reagent manufacturers compete on domestic supply chain efficiency. The market structure consolidates around three tiers: integrated life science conglomerates, specialized gene editing platform providers, and regional service laboratories. Two strategic archetypes dominate—domestic manufacturers leveraging JIS-compliant production and multinational instrument ecosystem providers. Competitive moves center on procurement authority consolidation through hospital consortia and early partnership commitments for AAV manufacturing capacity.
Among Japan-based suppliers, Takara Bio Inc. and Fujifilm Corp. occupy positions representing domestic manufacturing archetypes, while Thermo Fisher Scientific, Inc. anchors the multinational instrument ecosystem tier. Merck KGaA exemplifies integrated platform licensing strategy. These three names illustrate the competitive structure without exhausting participant categories.
| Leading Market Players |
|---|
| Takara Bio Inc. |
| Merck KGaA |
| Takeda Pharmaceutical Company |
| Fujifilm Corp. |
| Astellas Pharma Inc. |
| Revvity, Inc. |
| Danaher Corporation |
| GenScript |
| Thermo Fisher Scientific, Inc. |
| Others |
Pricing and Supply Chain Analysis
Ribonucleoprotein complexes replacing viral vector delivery simultaneously concentrates supply geography among domestic GMP manufacturers and compresses pricing premiums for clinical-grade reagents. PMDA's streamlined IND pathways accelerate this substitution, rewarding sponsors who source edited cell products from JIS Q 13485-certified facilities in the Tokyo-Osaka corridor.
Pricing Analysis
Service contract extensions and analytical validation packages drive lifetime value for platform providers. Three-tier pricing structure across premium, standard, and economy levels segments the market by GMP certification grade and guide RNA customization depth. Cost compression in research-use reagents intensifies because university hospital consortia aggregate procurement authority. Academic medical centers exhibit acute price sensitivity, while pharmaceutical sponsors absorb premium pricing for clinical-grade materials without volume elasticity.
Supply Chain Analysis
Inbound logistics costs from trans-Pacific phosphoramidite shipments fluctuate with semiconductor foundry demand cycles, squeezing margins for guide RNA manufacturers. Supply concentrates in Japan, the United States, and Germany for CRISPR reagents, with raw material dependencies on phosphoramidite chemistries, viral vector substrates, and synthetic DNA. Single-source vulnerability in AAV manufacturing capacity creates bottlenecks for in vivo therapeutic candidates. Distribution runs through direct partnerships with academic medical centers and specialized CDMO networks serving Kanto-region pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procurement authority centralization through hospital consortia creates niches for specialized service providers. The shift from individual PI-driven purchasing to centralized tenders opens white-space for vendors offering integrated editing-to-analytical workflows.
For Market Incumbents: Compound platform differentiation through captive delivery technology development rather than nuclease architecture alone. Takara Bio and Merck KGaA should deepen backward integration into guide RNA synthesis to offset phosphoramidite cost volatility. Securing early partnership commitments for AAV manufacturing capacity anchors long-term therapeutic pipeline relationships against emerging CDMO competitors.
For New Entrants and Emerging Players: Anchor in agricultural biotechnology applications where Japan's Cartagena Protocol implementation creates lighter regulatory burden than transgenics. The Kyushu region offers the most penetrable geography for gene-edited crop trait developers. A direct-to-seed-company service model bypasses consolidated hospital procurement channels entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed platform developers in the Osaka Bio Headquarters district that have validated base editing or prime editing capabilities but lack manufacturing scale. Long-term viability hinges on differentiation through delivery systems rather than commoditized nuclease IP. Watch PMDA-FDA harmonization progress on insertional mutagenesis risk assessment as the signal for parallel filing feasibility and valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PMDA streamlined IND pathways accelerate gene-edited cell therapy timelines for domestic sponsors. |
| Manufacturing Scale-Up | GMP facility certification under JIS Q 13485 extends qualification periods but locks in CDMO relationships. |
| Licensing Agreement | CRISPR platform IP from Merck KGaA anchors integrated synthetic biology workflows in Japanese institutions. |
| Pipeline Diversification | Base editing convergence with mRNA delivery enables transient editing without permanent nuclease expression. |
| Regulatory Approval Pathway | METI's Act on Regulation of Human Cloning Techniques clarification bifurcates somatic from germline tracks. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork encompassed gene therapy development executives, PMDA regulatory affairs leads, university hospital procurement managers, and CDMO operations directors. Secondary sources included PMDA approval databases, METI industrial policy documents, ClinicalTrials.gov entries, and JIS standards publications. Bottom-up reagent demand modeling and top-down therapeutic pipeline valuation triangulate market size estimates.
Sensitivity analysis tests forecast robustness across alternative scenarios for PMDA review timeline compression and METI incentive renewal. The analytical framework segments by product type, application, end user, and technology across the projection horizon. CAGRs derive from fitted growth curves calibrated to disclosed pipeline advancement rates and procurement volume trends. Inputs include allogeneic CAR-T manufacturing capacity expansion plans and phosphoramidite raw material price trajectories.
Underlying assumptions cover continued PMDA-FDA regulatory convergence, stable METI biotechnology tax credit policy, and sustained AAV manufacturing capacity constraints, with deviation risk concentrated in insertional mutagenesis guideline divergence and guide RNA synthesis cost volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market