
 Antenna Switch Module Market | 2026-2036
Antenna Switch Module Market Size, Share, and Industry Trends Forecast 2026-2036
Antenna Switch Module Market Outlook
A shortage of RF design engineers with compound semiconductor expertise is reorganizing how antenna switch module suppliers allocate talent across development centers. Skyworks Solutions leverages its captive GaAs fabrication infrastructure to sustain margin control across premium smartphone sockets. Murata Manufacturing anchors its position through ceramic packaging integration that competitors struggle to replicate at equivalent yield rates.
An antenna switch module is a solid-state RF component that routes high-frequency signals between multiple antennas and transceiver chains, typically operating from sub-6 GHz through mmWave bands with insertion loss below 1 dB and isolation exceeding 30 dB. The device enables dynamic band selection in multi-standard wireless systems where spatial efficiency and power handling are critical constraints. RF Switch products dominate unit volume due to their ubiquity in handset architectures, while GaN-based technologies capture the fastest expansion as base station OEMs prioritize thermal resilience at elevated output powers. PIN Diode variants retain cost advantages in legacy telecommunications infrastructure where switching speed requirements remain modest.
The FCC equipment authorization framework and ETSI harmonized standards for radio spectrum equipment shape product development cycles by mandating specific spurious emission limits and intermodulation performance thresholds. China's MIIT radio transmission equipment type approval process adds a parallel compliance layer for modules destined for domestic 5G base station deployments. Stakeholders must monitor how regional divergences in mmWave spectrum allocation reshape module specification requirements across major supply contracts.
Market Dynamics
Smartphone OEMs are consolidating RF component procurement around suppliers with captive GaAs fabrication, compressing vendor lists and elevating technical qualification thresholds for antenna switch module qualification.
Growth Catalysts
- 5G-Advanced Deployment:Base station OEMs in China are expanding orders for multi-band switch modules to support 256-element massive MIMO arrays. MIIT's accelerated 5G spectrum allocation timelines compress procurement cycles.
- FCC Transmit Power Rules:The FCC's tightened equipment authorization requirements for RF devices mandate higher efficiency thresholds, forcing module upgrades across US-bound handset portfolios.
- GaN-on-SiC Maturation:Compound semiconductor foundries are extending thermal resilience specifications for base station applications, opening premium sockets previously served by silicon LDMOS alternatives.
Market Restraints
- GaAs Wafer Supply Concentration:Six-inch GaAs substrate production clusters in Taiwan and Japan create geographic vulnerability for switch module die sourcing during fab allocation disputes.
- Insertion Loss Floor:SOI-based switch technologies hit theoretical minimums near 0.4 dB at sub-6 GHz, constraining further performance differentiation without material platform shifts.
- ETSI Spurious Emission Limits:Harmonized European standards for radio spectrum equipment impose testing burdens that extend certification timelines by 8-14 weeks for non-EU suppliers.
Strategic Opportunities
- India PLI Scheme:India's production-linked incentive scheme for telecom equipment manufacturing offers 4-6% duty credit offsets for domestic RF module assembly, attracting contract manufacturers from China and Vietnam.
- Automotive V2X Integration:C-V2X roadside unit deployments require automotive-grade switch modules with AEC-Q100 qualification, a specification tier currently underpenetrated by consumer-electronics-focused suppliers.
- AI-Driven RF Front-End Optimization:Machine learning algorithms for real-time impedance matching are converging with switch control logic, enabling predictive band selection in adaptive antenna systems.
Industry Challenges
- Compound Semiconductor Talent Scarcity:RF design engineers with GaAs HBT and pHEMT process expertise command 40-60% compensation premiums, constraining R&D scaling at mid-tier module suppliers.
- Multi-Domain Certification Overlap:Modules must simultaneously satisfy FCC Part 15, ETSI EN 301 908, and MIIT type approval requirements, creating documentation conflicts when regional test methodologies diverge on intermodulation measurement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antenna Switch Module Market |
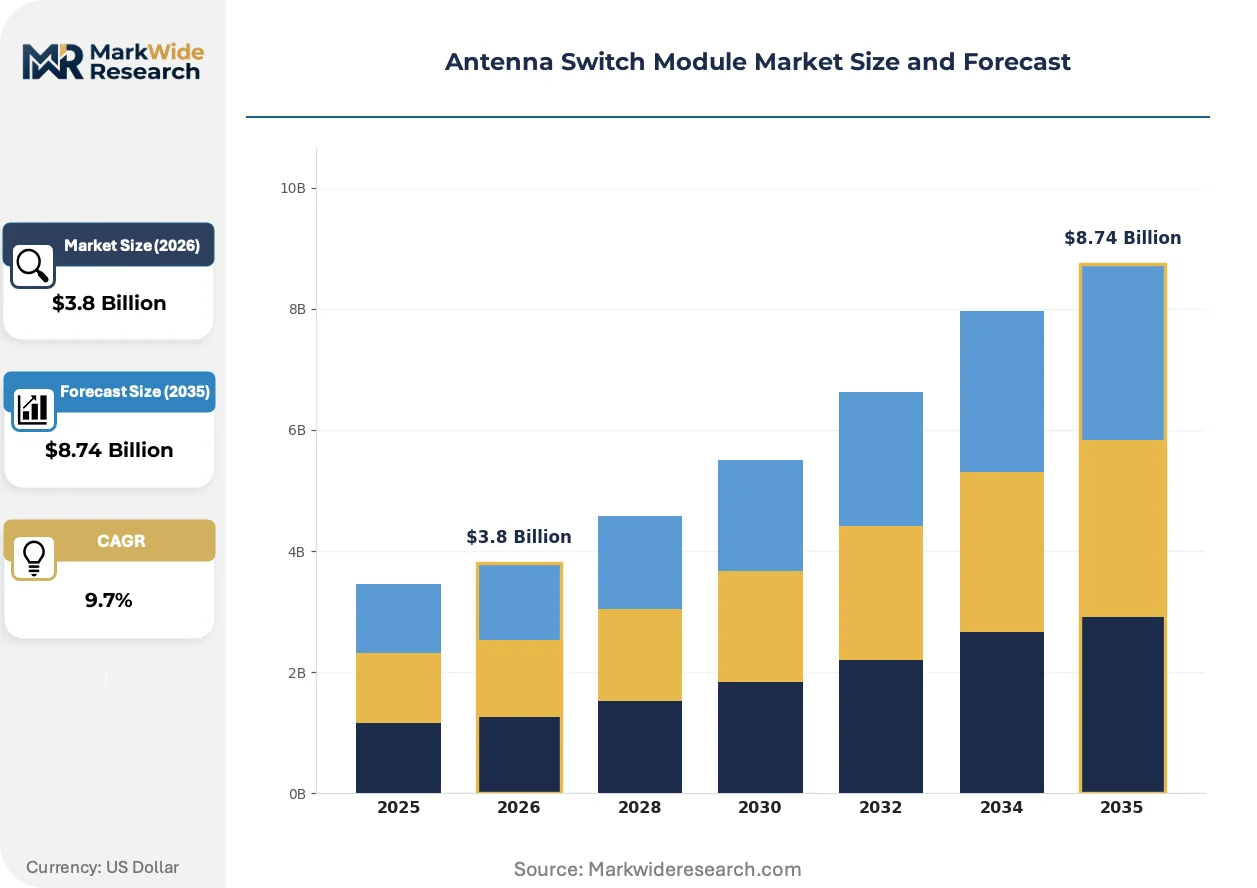
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Switch, RF Filter, Duplexer, RF Combiner Technology: MEMS, RF MEMS, PIN Diode, GaN Application: Telecommunications, Satellite Communication, Automotive, IoT Devices End User: Telecom Operators, Device Manufacturers, Research Institutes, System Integrators |
| Companies Covered | Skyworks Solutions, Murata Manufacturing, Infineon Technologies, Qorvo, NXP Semiconductors, TDK Electronics, Analog Devices, STMicroelectronics, YAGEO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antenna Switch Module Market Strategic Shifts
Antenna switch architectures are bifurcating between handset-optimized SOI integration and base station-grade GaN discrete solutions, with packaging innovation becoming the primary differentiation vector.
Silicon-on-insulator switch technology is supplanting traditional GaAs pHEMT alternatives in sub-7 GHz smartphone applications. Tier-one handset OEMs have completed platform transitions to SOI-based antenna tuning and switching for 2024-2025 flagship cycles. This migration compresses bill-of-material costs by 15-25% while enabling tighter integration with CMOS baseband controllers.
ETSI's harmonized standards for radio spectrum equipment are mandating stricter spurious emission masks above 26 GHz. Module suppliers must retest mmWave portfolios against revised intermodulation thresholds before EU market entry. Premium smartphone SKUs destined for European distribution are absorbing the bulk of compliance-driven redesign costs.
Consolidated procurement contracts now bundle antenna switch modules with filter and LNA components into single-source RF front-end agreements. Distributor-led spot purchasing for discrete switches is retreating as OEMs negotiate multi-year master service agreements directly with integrated solution providers. This concentration is most visible in China's handset export supply chains, where vertical integration between module vendors and baseband chipset suppliers has eliminated independent component distributors from tier-one sockets.
Antenna Switch Module Market Segmentation
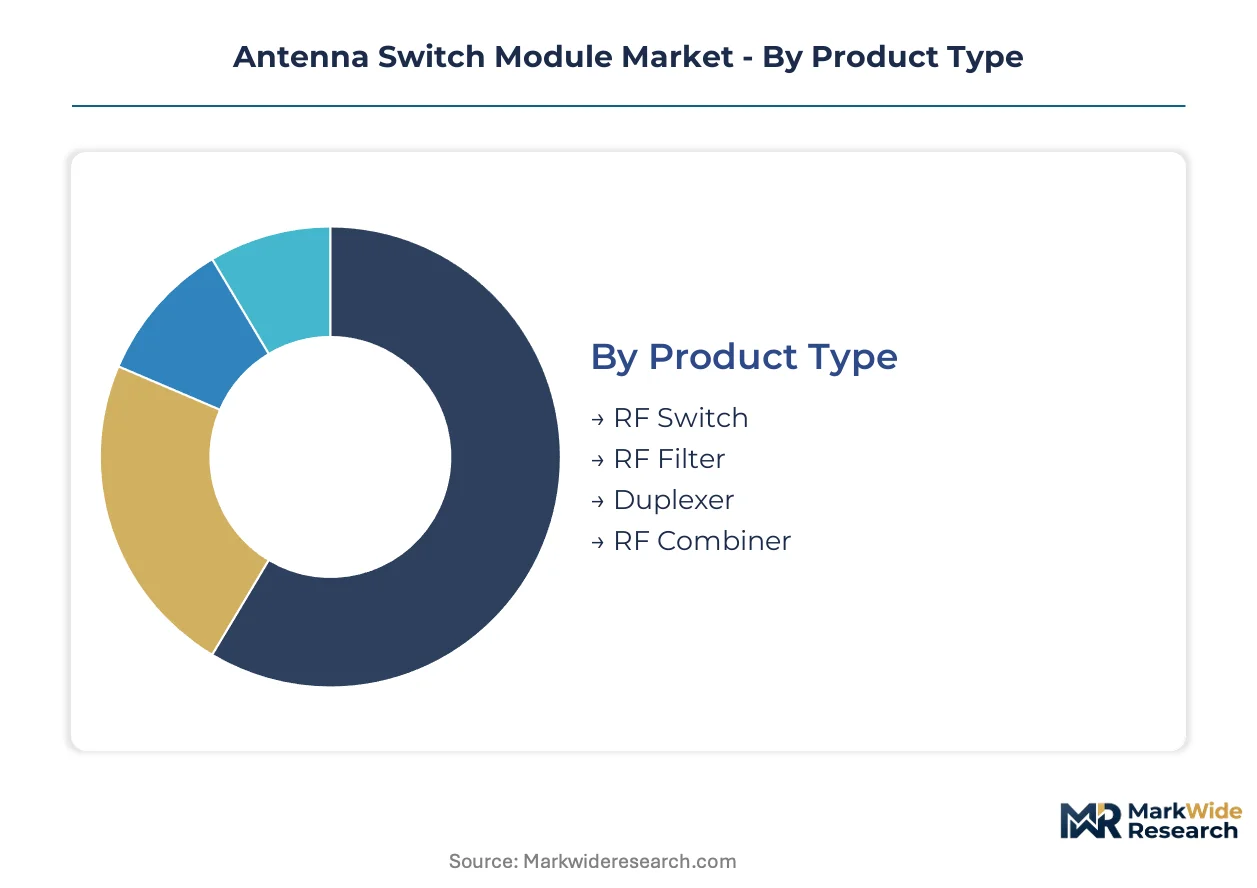
Antenna switch module procurement patterns diverge sharply across product architectures and end-use certifications. Regulatory frameworks from the FCC, ETSI, and China's MIIT impose distinct performance thresholds that reshape how suppliers prioritize segment development.
Product Type:
FCC Part 15 equipment authorization rules differentiate insertion loss requirements between discrete switching elements and integrated front-end modules, compressing vendor qualification timelines for certain form factors.
- RF Switch:Solid-state signal routing components operating from sub-6 GHz through mmWave bands with isolation exceeding 30 dB. Smartphone OEMs in China consolidate procurement around suppliers with captive GaAs fabrication for these high-volume sockets. Skyworks Solutions leverages its in-house foundry infrastructure to sustain margin control across premium handset designs.
- RF Filter:Frequency-selective components that suppress unwanted harmonics and adjacent channel interference. Base station OEMs in China expanding 256-element massive MIMO arrays drive multi-band filter orders, with MIIT's accelerated 5G spectrum timelines compressing procurement cycles.
- Duplexer:Bidirectional filtering devices enabling simultaneous transmit and receive operation on shared antenna infrastructure.
- RF Combiner:Multi-port passive components aggregating multiple carrier signals into common transmission paths.
RF Switch handles the majority of throughput; RF Filter is gaining share fastest on 5G-Advanced base station deployment.
Technology:
Cost tier differentiation separates mature silicon platforms from compound semiconductor alternatives, with thermal resilience specifications determining socket access in base station versus handset applications.
- MEMS:Microelectromechanical switching elements fabricated on silicon substrates with electrostatic actuation. Automotive C-V2X roadside unit deployments in Europe require AEC-Q100 qualified MEMS variants, a specification tier underpenetrated by consumer-electronics-focused suppliers.
- RF MEMS:Optimized microelectromechanical structures for high-frequency signal paths with near-ideal linearity. Research institutes in Germany and Japan evaluate RF MEMS for satellite communication payloads where power consumption constraints override cost considerations.
- PIN Diode:Semiconductor switching devices retaining cost advantages in legacy telecommunications infrastructure.
- GaN:Wide-bandgap compound semiconductor technology capturing premium sockets in thermal-critical applications.
PIN Diode maintains volume leadership in established infrastructure; GaN shows the steepest expansion trajectory on base station thermal resilience priorities.
Application:
Customer type concentration varies by certification burden, with automotive and telecommunications verticals demanding divergent documentation protocols.
- Telecommunications:Core infrastructure and consumer handset deployments requiring multi-band compatibility. Device manufacturers in China's export supply chains bundle antenna switch modules with filter and LNA components into single-source RF front-end agreements, eliminating independent distributors from tier-one sockets.
- Satellite Communication:Geostationary and low-earth-orbit payload systems demanding radiation-hardened specifications. System integrators in the United States and France negotiate multi-year master service agreements directly with integrated solution providers for these specialized requirements.
- Automotive:C-V2X and connected vehicle platforms requiring AEC-Q100 qualification.
- IoT Devices:Low-power wide-area network endpoints with simplified switching requirements.
Telecommunications absorbs the dominant share of module output; Satellite Communication is climbing fastest on constellation deployment schedules.
End User:
Supply concentration patterns reorganize around procurement scale, with large-volume device manufacturers extracting preferential terms unavailable to fragmented research and integration channels.
- Telecom Operators:Network infrastructure owners specifying module performance for base station and core equipment. China's MIIT radio transmission equipment type approval process adds a parallel compliance layer for modules destined for domestic 5G deployments, extending documentation requirements.
- Device Manufacturers:Handset and terminal OEMs consolidating RF component procurement around suppliers with captive fabrication. India's PLI scheme for telecom equipment manufacturing offers duty credit offsets attracting contract manufacturers from China and Vietnam.
- Research Institutes:Academic and government laboratories evaluating emerging switch architectures.
- System Integrators:Defense and aerospace contractors assembling specialized communication platforms.
Device Manufacturers command the largest procurement volumes; System Integrators are expanding most quickly on defense communication modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antenna switch module consumption patterns diverge sharply by geography. China integrates these components into export-bound handsets and domestic base stations, while the United States and Germany concentrate demand in telecommunications infrastructure and automotive certification tiers.
China
MIIT's accelerated 5G spectrum allocation compresses procurement cycles for 256-element massive MIMO arrays. Domestic base station deployment and handset export volumes absorb the majority of global module output. Shenzhen and Dongguan manufacturing clusters house vertically integrated RF front-end assembly operations serving tier-one smartphone OEMs.
United States
FCC equipment authorization rules for RF devices mandate stricter transmit power efficiency thresholds, forcing module upgrades across US-bound handset portfolios. Defense communication modernization programs expand System Integrator procurement volumes. Greater Boston and Silicon Valley R&D centers concentrate compound semiconductor design talent.
Germany
ETSI harmonized standards for radio spectrum equipment impose extended certification timelines for mmWave portfolios above 26 GHz. Automotive C-V2X roadside unit deployments require AEC-Q100 qualified modules. Bavaria's automotive electronics cluster drives qualification demand for RF components in connected vehicle platforms.
Japan
METI industrial policy supports domestic compound semiconductor fabrication for thermal-critical base station applications. GaN-on-SiC foundry investments target premium sockets in telecommunications infrastructure. Kyushu and Nagoya manufacturing regions concentrate ceramic packaging and RF component production.
India
TRAI spectrum management frameworks and the PLI scheme for telecom equipment manufacturing attract contract manufacturers from China and Vietnam. Duty credit offsets of 4-6% incentivize domestic RF module assembly. Karnataka and Tamil Nadu electronics manufacturing corridors expand surface-mount assembly capacity.
Antenna Switch Module Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in antenna switch module supply. The upper tier commands premium sockets through captive fabrication and packaging integration, while mid-scale suppliers compete on spot-market availability and distributor relationships. Three archetypes dominate: GaAs foundry-integrated module houses, ceramic packaging specialists, and fabless RF design firms licensing process technology. Consolidation pressures intensify as smartphone OEMs compress vendor lists, while strategic partnerships between base station OEMs and compound semiconductor foundries reshape upstream allocation.
Within the foundry-integrated tier, Skyworks Solutions and Murata Manufacturing exemplify divergent moat strategies. Skyworks anchors its position through in-house GaAs fabrication infrastructure sustaining margin control across premium smartphone sockets. Murata occupies a position defined by ceramic packaging integration that competitors struggle to replicate at equivalent yield rates. Qorvo represents the fabless-specialist archetype, licensing process technology to access compound semiconductor capacity without capital-intensive fabrication commitments.
| Leading Market Players |
|---|
| Skyworks Solutions |
| Murata Manufacturing |
| Infineon Technologies |
| Qorvo |
| NXP Semiconductors |
| TDK Electronics |
| Analog Devices |
| STMicroelectronics |
| YAGEO Corporation |
| Others |
Value Chain & Pricing Dynamics
FCC Part 15 equipment authorization rules gate both supplier qualification and price differentiation, compressing vendor lists to foundry-integrated houses while forcing premium pricing for certified modules. Buyers face stark cost escalations when sourcing US-bound portfolios, as transmit power efficiency mandates eliminate low-cost alternatives.
Pricing Analysis
Long-term master service agreements dominate procurement, with smartphone OEMs negotiating multi-year offtake directly with integrated RF front-end providers. Price differentiation stems from certification tier—FCC Part 15 versus MIIT type approval—and captive GaAs fabrication scale. Cost compression in SOI-based smartphone sockets intensifies as tier-one OEMs complete platform transitions. Device manufacturers in China's export supply chains exhibit highest price sensitivity, while base station OEMs prioritize thermal resilience over unit economics.
Supply Chain Analysis
Six-inch GaAs substrate production clusters in Taiwan and Japan create a chokepoint for switch module die sourcing during fab allocation disputes. The supply chain draws from compound semiconductor foundries in Taiwan, ceramic packaging specialists in Japan, and assembly operations in China and Vietnam. Single-source vulnerability concentrates in GaAs wafer supply during regional trade friction. Distribution runs through vertically integrated RF front-end agreements that have eliminated independent component distributors from tier-one sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antenna switch module market sits in early-cycle expansion, with 5G-Advanced deployment accelerating penetration of multi-band architectures across base station and handset applications.
For Market Incumbents: Consolidate procurement relationships by deepening captive GaAs fabrication capacity in Taiwan or Japan, insulating against wafer supply concentration risk. Expand ceramic packaging yield rates to defend margin position against SOI-based challengers in sub-7 GHz smartphone sockets. Prioritize FCC Part 15 pre-certification investments to compress qualification timelines for US-bound portfolios.
For New Entrants and Emerging Players: AEC-Q100 automotive certification fast-track opens underpenetrated sockets in C-V2X roadside unit deployments across Germany and the United States. Target India's PLI scheme corridors in Karnataka and Tamil Nadu for duty credit-offset assembly operations. Pursue fabless RF design partnerships with compound semiconductor foundries to bypass capital-intensive fabrication barriers.
For Investors and Strategic Acquirers: MIIT's accelerated 5G spectrum allocation reshapes the acquisition landscape toward base station-grade GaN module suppliers with thermal-critical specifications. Five-to-ten year viability favors foundry-integrated houses over fabless specialists exposed to capacity allocation volatility. Monitor GaAs HBT and pHEMT engineering talent scarcity as the inflection signal for R&D scaling constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaAs Foundry Expansion | Skyworks Solutions sustains margin control through in-house six-inch wafer production. |
| Ceramic Packaging Yield Enhancement | Murata Manufacturing anchors market position through integrated LTCC substrate expertise. |
| AEC-Q100 Automotive Certification | Suppliers unlock C-V2X roadside unit procurement in Bavaria and Michigan corridors. |
| India PLI Scheme Assembly Migration | Contract manufacturers capture 4-6% duty credit offsets in Karnataka electronics zones. |
| SOI Platform Transition Completion | Tier-one handset OEMs compress bill-of-material costs 15-25% versus GaAs alternatives. |
Study Parameters
Initial hypotheses were tested against primary input from RF front-end procurement managers, compound semiconductor foundry executives, base station OEM platform engineers, and MIIT certification specialists, then refined through secondary validation. Bottom-up triangulation incorporated FCC equipment authorization databases, ETSI harmonized standards documentation, MIIT type approval registries, and customs trade flow records. Top-down cross-checks applied semiconductor industry association capacity reports and smartphone OEM supply chain disclosures.
Variance decomposition across the projection horizon isolates volume drivers by product architecture, technology platform, application vertical, and end-user procurement scale. CAGRs derive from segment-level unit economics and value-per-unit trajectories modeled across RF switch, filter, duplexer, and combiner categories. Forecast inputs incorporate GaN-on-SiC thermal resilience specifications, SOI insertion loss floor constraints, and regional certification timeline differentials.
Decision-makers should treat outputs as directional under assumptions of sustained 5G-Advanced deployment momentum and stable GaAs wafer supply allocation; material deviation in compound semiconductor foundry capacity or spectrum allocation timelines would warrant model refresh. Practitioners should keep alternative scenarios live as ETSI spurious emission limits and FCC transmit power rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Low Voltage Disconnect Switch Market
Switches
Touchpad Market
Switches
Safety Limit Switches Market
Switches
Membrane Switch Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Push Button Dropper Market
Switches
DC Switchgear Market
Switches
Vibration Level Switch Market
Switches
Rotary Limit Switches Market
Switches
Asia Pacific Reed Sensors Switches Market
Switches
Global Push Buttons and Signalling Devices Market
Switches
Intelligent Power Switches Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
North America Medium Voltage Switchgear Market
Switches
DC Circuit Breaker Market
Switches
North America MV Switchgear Market