
 MEMS Combo Sensors Market | 2026-2036
MEMS Combo Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Combo Sensors Market Foresight
Direct procurement channels between automotive tier-one suppliers and MEMS foundries is reshaping how combo sensors reach end-users. Bosch Sensortec leverages captive wafer capacity in Germany to sustain pricing power on high-g accelerometer-gyroscope combinations. STMicroelectronics anchors its position through deep partnerships with European smartphone OEMs, while TDK competes aggressively in wearable device applications with ultra-thin package formats.
MEMS combo sensors integrate multiple transduction mechanisms—typically capacitive or piezoelectric—within a single silicon die or stacked package, enabling simultaneous measurement of acceleration, angular rate, pressure, or temperature in footprints below 3 x 3 mm. Their primary purpose is reducing board area, power draw, and calibration overhead in space-constrained electronics. Accelerometer-gyroscope combinations dominate unit volumes in smartphones and wearable devices, where Analog Devices specializes in low-noise designs for industrial robotics. Pressure-temperature hybrids command premium pricing in aerospace and automotive under-the-hood applications, a segment where Honeywell International leads on hermetic packaging reliability. Digital-output combo sensors are displacing analog interfaces in home automation and robotics, driven by tighter microcontroller integration requirements.
FDA oversight of wearable medical devices and NHTSA crashworthiness sensor mandates in the United States, alongside REACH material restrictions and CE marking requirements in Europe, are elevating qualification barriers for new entrants. Japan's METI energy-efficiency standards and South Korea's MFDS biocompatibility rules for health-monitoring wearables add further compliance layers across major demand centers. Stakeholders must monitor how automotive functional-safety certifications propagate from ISO 26262 into consumer electronics supply chains, as this convergence will determine which foundry partnerships survive the next qualification cycle.
Market Dynamics
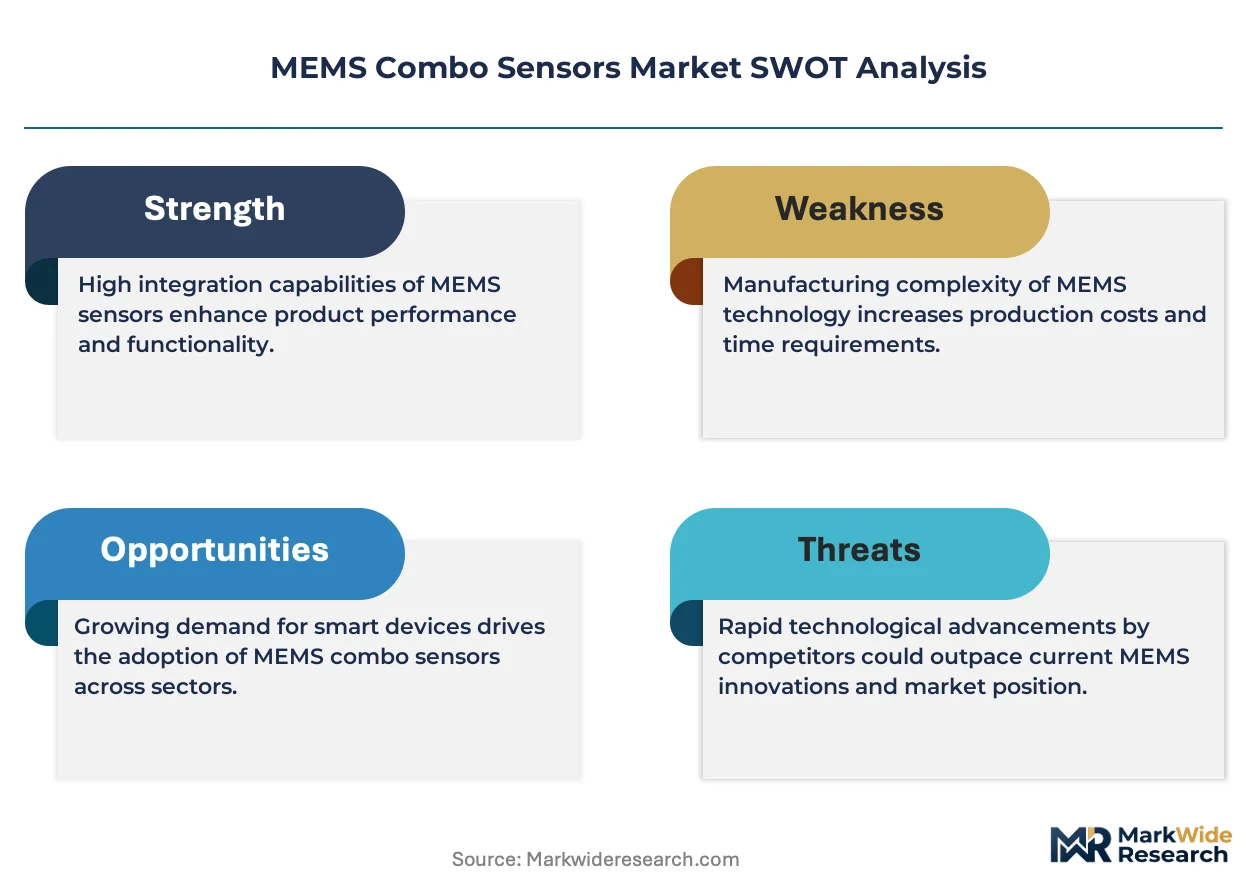
Automotive functional-safety mandates from NHTSA and Euro NCAP are compressing qualification cycles, forcing foundries to accelerate ISO 26262 certification timelines while smartphone OEMs simultaneously demand thinner packages with lower power budgets.
Growth Catalysts
- Vehicle Safety Mandates:NHTSA and Euro NCAP crashworthiness requirements are accelerating the shift from discrete sensors to integrated accelerometer-gyroscope packages in advanced driver-assistance systems.
- East Asian Manufacturing Concentration:South Korean and Taiwanese procurement clusters co-locating smartphone OEMs and tier-one automotive suppliers are reducing logistics friction and compressing delivery lead times.
- Capacitive Transduction Advances:Multi-axis inertial measurement units leveraging capacitive sensing architectures now achieve noise floors suitable for industrial robotics and precision navigation.
Market Restraints
- Wafer Supply Concentration:Captive foundry capacity at Bosch Sensortec in Germany and select Taiwanese pure-play MEMS foundries limits second-source options for high-g combinations.
- Hermetic Packaging Costs:Pressure-temperature hybrids for aerospace and automotive under-the-hood applications require gold-tin sealing processes that inflate unit economics.
- REACH Material Restrictions:ECHA substance limitations on lead-based solders and certain piezoelectric ceramics are forcing reformulation of established transduction stacks.
Strategic Opportunities
- Digital-Output Convergence:SPI and I3C interfaces are displacing analog voltage outputs in home automation and robotics, enabling tighter microcontroller integration without external ADCs.
- Wearable Biocompatibility:South Korea's MFDS health-monitoring wearable rules are creating certified-supplier preference lists that reward early compliance investment.
- Ultra-Thin Package Formats:TDK's aggressive push into sub-2mm z-height stacks for earables and smart rings is opening form factors previously inaccessible to combo sensors.
Industry Challenges
- ISO 26262 Certification Bottlenecks:Automotive functional-safety documentation requirements are extending qualification timelines to 18-24 months, freezing foundry capacity commitments.
- Multi-Physics Simulation Talent:The scarcity of engineers proficient in coupled electromechanical-thermal finite element analysis is delaying custom sensor development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Combo Sensors Market |
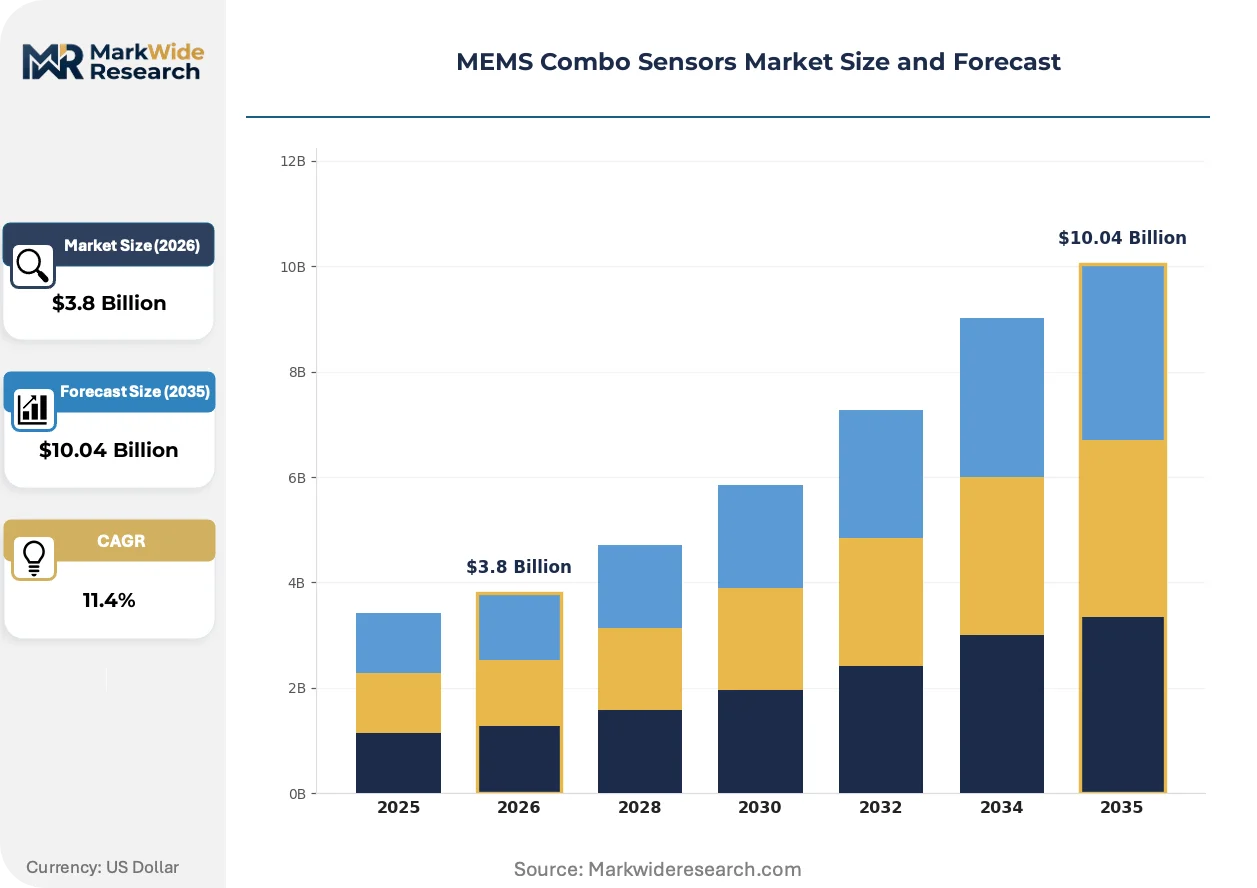
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
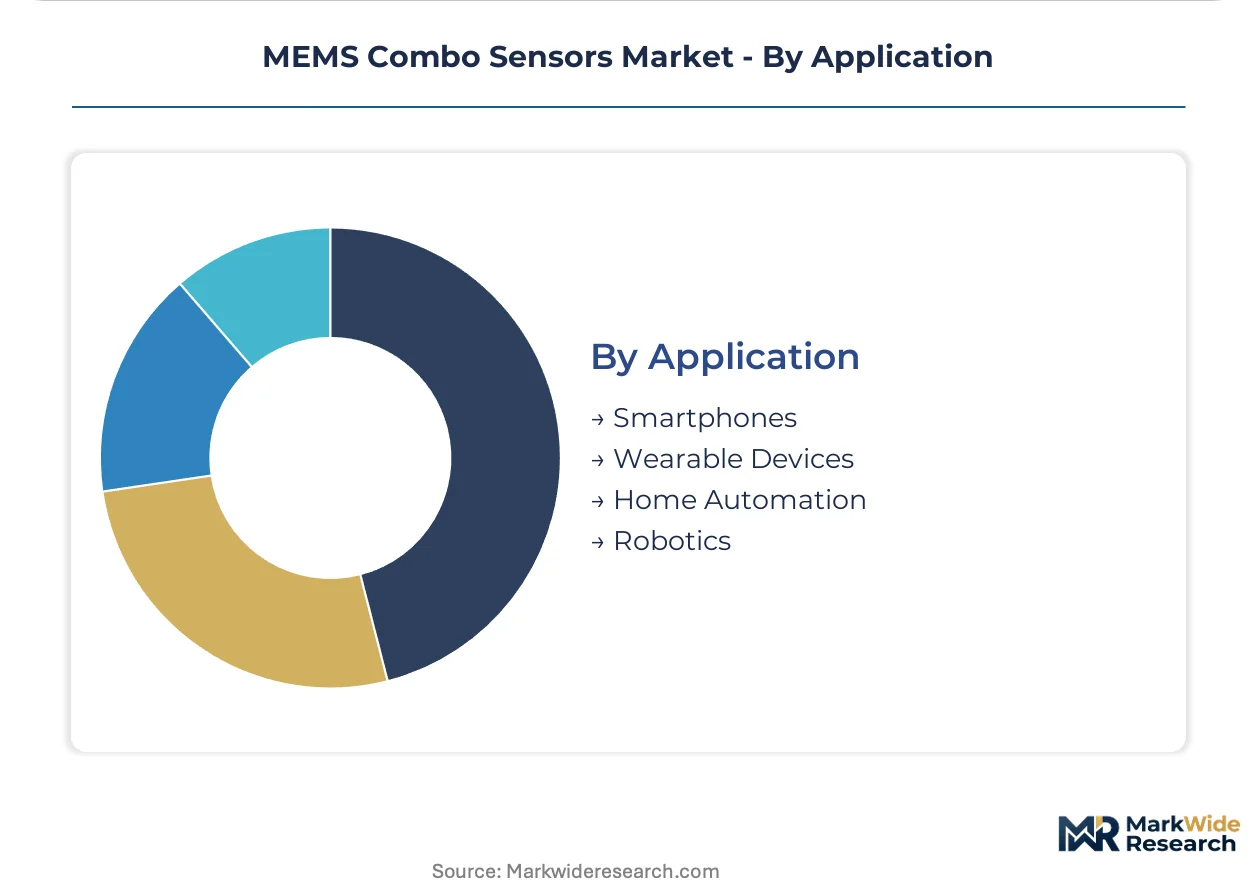
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Accelerometers, Gyroscopes End User: Consumer Electronics, Automotive, Aerospace, Industrial Automation Technology: Analog, Digital, MEMS, Hybrid Application: Smartphones, Wearable Devices, Home Automation, Robotics |
| Companies Covered | Murata Manufacturing, STMicroelectronics, Honeywell International, Panasonic Corporation, InvenSense, Bosch Sensortec, TDK, NXP Semiconductors, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Combo Sensors Market Shifts & Advancements
Monolithic integration of transduction elements with CMOS signal conditioning is collapsing package footprints while digital interfaces are severing the analog signal chain entirely.
Wafer-level vacuum encapsulation using silicon-silicon direct bonding is rendering obsolete traditional ceramic lid-and-seal approaches for gyroscope inertial elements. Automotive tier-one suppliers in Germany and Japan are qualifying these processes for 125°C continuous operation. The elimination of hermetic feedthroughs is compressing die sizes below 2 x 2 mm for six-axis combinations.
REACH substance restrictions and RoHS recast directives in Europe are forcing migration from lead-zirconate-titanate to aluminum nitride and scandium-doped aluminum nitride for piezoelectric transduction. MEMS foundries in France and Germany are requalifying process flows around these alternative materials. Pressure sensor hybrids for automotive manifold applications face 18-month material revalidation cycles.
Direct RFQ channels between automotive tier-one suppliers and MEMS foundries are bypassing traditional distribution. Bosch Sensortec and STMicroelectronics now field dedicated automotive application engineering teams at customer design centers in Stuttgart and Toyota City. This disintermediation is compressing pricing transparency and accelerating custom specification cycles.
MEMS Combo Sensors Market Segmentation
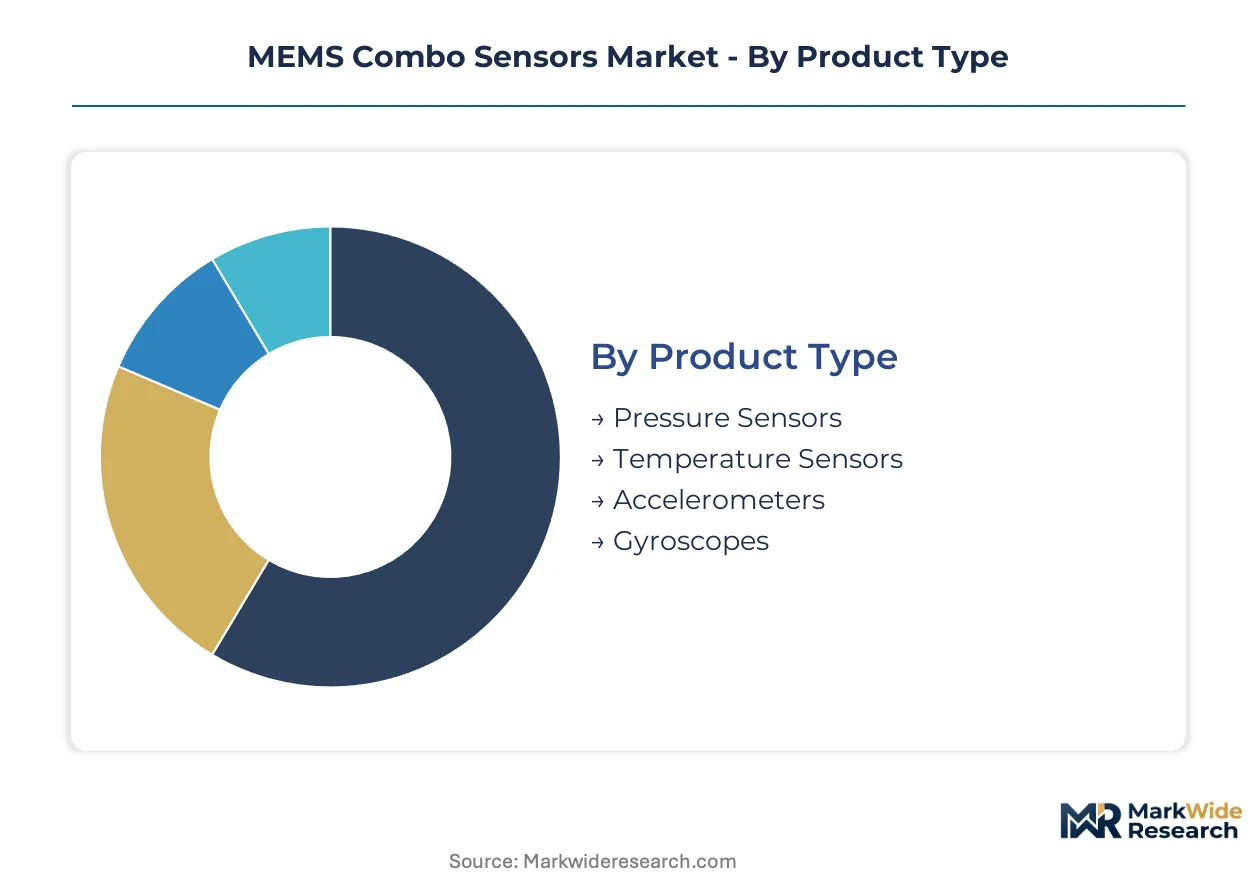
Segmentation in MEMS combo sensors determines procurement complexity, calibration service requirements, and foundry capacity allocation. Each dimension—product type, end user, technology, and application—carries distinct after-sales-service intensity profiles that shape vendor profitability and customer lock-in.
Product Type:
After-sales-service intensity varies sharply across product types, with high-g accelerometer-gyroscope combinations demanding ongoing calibration support while discrete pressure sensors require minimal field intervention.
- Pressure Sensors:These devices measure absolute, gauge, or differential pressure through piezoresistive or capacitive transduction, typically integrating temperature compensation on-die. Demand concentrates in automotive manifold applications across Germany and Japan, where Bosch Sensortec and Denso mandate annual recalibration protocols for safety-critical deployments.
- Accelerometers:Capacitive and piezoelectric architectures detect linear acceleration across single to tri-axis configurations, with noise floors now reaching sub-100 µg/√Hz in industrial-grade variants. Smartphone OEMs in South Korea and Taiwan drive procurement volumes, though wearable device manufacturers in Shenzhen are expanding low-g specifications for fall-detection features.
- Temperature Sensors:Integrated thermopiles or bandgap references provide thermal compensation for companion transducers, rarely deployed as standalone combo elements. Automotive under-the-hood applications in Stuttgart and Toyota City specify these as secondary outputs within pressure-accelerometer hybrids.
- Gyroscopes:Coriolis-effect vibratory structures measure angular rate with drift specifications critical to navigation-grade performance. Aerospace qualification programs in Toulouse and Seattle require hermetic packaging with 15-year service life guarantees, elevating aftermarket support obligations.
By volume, Accelerometers lead. By growth pace, Gyroscopes are gaining share fastest in automotive ADAS integrations.
End User:
Cost tier stratification separates premium-certified automotive and aerospace demand from price-sensitive consumer electronics procurement, with industrial automation occupying a mid-tier reliability band.
- Consumer Electronics:Smartphone and wearable OEMs prioritize sub-1mm z-height packages with minimal power draw, accepting relaxed accuracy specifications for cost optimization. South Korean and Taiwanese procurement clusters dominate this tier, with Foxconn and Pegatron consolidating orders across multiple foundry sources.
- Automotive:Tier-one suppliers in Germany and Japan require ISO 26262 functional-safety documentation, hermetic sealing, and 125°C continuous operation ratings. NHTSA crashworthiness mandates and Euro NCAP scoring protocols are compressing qualification timelines to 18-24 months, freezing foundry capacity commitments for qualified sources.
- Aerospace:Honeywell International and Collins Aerospace specify radiation-hardened variants with MIL-STD-883 screening, commanding 10-15x consumer electronics pricing. Hermetic packaging using gold-tin sealing processes inflates unit economics but ensures 20-year operational lifespans in avionics bays.
- Industrial Automation:Analog Devices and TE Connectivity target vibration monitoring and precision positioning with extended temperature ranges and IP67 ingress protection. Demand clusters around German manufacturing automation hubs and Japanese robotics corridors, with service contracts covering predictive maintenance sensor swaps.
Consumer Electronics generates the highest unit volumes. Aerospace delivers the steepest margin expansion trajectory despite limited shipment counts.
Technology:
Interface architecture determines microcontroller integration complexity, with digital outputs displacing analog signal chains across robotics and home automation applications.
- Digital:SPI and I3C interfaces enable direct microcontroller attachment without external ADCs, collapsing board area and simplifying firmware development. Home automation OEMs in Shenzhen and robotics startups in Boston are standardizing on these variants for rapid prototyping cycles.
- Analog:Voltage-output devices persist in legacy industrial equipment and cost-constrained automotive subsystems where microcontroller upgrades lag. Japanese automotive suppliers in Toyota City maintain analog sourcing for backward compatibility with 2015-2020 platform designs.
- MEMS:Monolithic silicon processes integrating transduction and CMOS conditioning dominate unit economics, with wafer-level vacuum encapsulation rendering ceramic lid approaches obsolete. Bosch Sensortec's captive Reutlingen foundry anchors European supply security.
- Hybrid:Stacked die configurations combining MEMS transducers with ASIC signal processing enable heterogeneous material integration, such as aluminum nitride piezoelectrics with silicon CMOS. TDK's ultra-thin packages for earables exemplify this architecture's form-factor advantages.
MEMS technology commands the dominant production share. Digital interface variants are climbing fastest as SPI and I3C adoption accelerates.
Application:
Customer type fragmentation separates high-volume smartphone procurement from emerging wearable and robotics segments with divergent specification tolerances.
- Smartphones:Six-axis accelerometer-gyroscope combinations in sub-3mm footprints represent the baseline combo sensor configuration, with Apple and Samsung driving annual specification escalations. East Asian manufacturing clusters in Taiwan and South Korea compress delivery lead times through co-located foundry and assembly operations.
- Wearable Devices:Ultra-thin sub-2mm z-height stacks for smartwatches and earables demand biocompatibility certification under South Korea's MFDS rules, creating preference lists that reward early compliance investment. TDK competes aggressively in this segment with specialized package formats.
- Home Automation:Environmental sensing hubs integrate pressure-temperature-accelerometer triplets for HVAC optimization and intrusion detection, with digital outputs displacing analog interfaces to reduce external component counts.
- Robotics:Industrial arms and autonomous mobile robots require low-noise inertial measurement units for precision positioning, with Analog Devices specializing in designs targeting sub-0.1-degree angular accuracy over extended operational periods.
Smartphones anchor current volume leadership. Wearable Devices are expanding most quickly as health-monitoring form factors proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German captive foundry capacity commands 15-20% pricing premiums over Taiwanese pure-play alternatives, while South Korean procurement clusters compress logistics costs through co-located smartphone OEM and tier-one automotive supplier operations.
Germany
Automotive tier-one suppliers in Stuttgart and Reutlingen drive accelerometer-gyroscope demand for advanced driver-assistance systems. Euro NCAP crashworthiness mandates accelerate ISO 26262 qualification timelines for integrated sensor packages. Bosch Sensortec anchors European supply security through captive wafer capacity serving BMW and Mercedes-Benz design centers.
United States
NHTSA vehicle safety mandates push discrete-to-integrated sensor transitions in Detroit and Austin automotive corridors. FDA oversight of wearable medical devices elevates qualification barriers for health-monitoring form factors. Honeywell International maintains aerospace qualification programs in Phoenix and Seattle with MIL-STD-883 screening requirements.
Japan
Automotive manufacturers in Toyota City expand multi-axis inertial measurement unit procurement for collision-avoidance systems. METI energy-efficiency standards shape sensor power-draw specifications for consumer electronics integration. Denso and Panasonic Corporation anchor manufacturing automation in Chubu and Kansai industrial belts.
South Korea
Smartphone OEMs in Seoul Capital Area consolidate six-axis combo sensor orders through Foxconn and Pegatron procurement channels. MFDS biocompatibility rules for health-monitoring wearables create certified-supplier preference lists. Samsung Electronics and LG Innotek co-locate design centers with foundry partners in Suwon and Pyeongtaek.
Taiwan
Pure-play MEMS foundries in Hsinchu Science Park serve dual smartphone and automotive customer bases with compressed delivery lead times. TSMC ecosystem spillover accelerates wafer-level vacuum encapsulation process adoption. MediaTek and ASE Group anchor packaging innovation clusters in Taichung and Kaohsiung.
MEMS Combo Sensors Market Competitive Landscape
Captive foundry operators and fabless design houses split the market along vertical-integration fault lines. European automotive-tier specialists maintain pricing power through in-house wafer capacity, while Asian diversified electronics conglomerates compete on package miniaturization and volume scale. Three strategic archetypes dominate: captive-integrated sensor divisions, fabless MEMS design specialists, and diversified semiconductor conglomerates with MEMS product lines. Capacity expansion and strategic partnerships represent the dominant competitive moves, with foundry partnerships and automotive qualification co-development agreements reshaping supplier-customer relationships.
Among diversified semiconductor conglomerates, STMicroelectronics, NXP Semiconductors, and Analog Devices exemplify the fabless-to-hybrid spectrum. STMicroelectronics occupies a position emphasizing European smartphone OEM partnerships. NXP Semiconductors sits within the automotive-functional-safety tier. Analog Devices anchors the industrial-automation specialization vector with low-noise design capabilities.
| Leading Market Players |
|---|
| Murata Manufacturing |
| STMicroelectronics |
| Honeywell International |
| Panasonic Corporation |
| InvenSense |
| Bosch Sensortec |
| TDK |
| NXP Semiconductors |
| Analog Devices |
| Others |
Supply & Pricing Matrix
Captive wafer capacity at Bosch Sensortec's Reutlingen foundry anchors premium pricing for ISO 26262-certified automotive combos, while Taiwanese pure-play alternatives serve price-sensitive consumer electronics procurement. German automotive tier-one suppliers accept 15-20% cost premiums for functional-safety documentation and hermetic packaging reliability that Asian foundries struggle to replicate at scale.
Pricing Analysis
Configured-to-order pricing for aerospace-qualified gyroscopes with MIL-STD-883 screening commands 10-15x premiums over standard consumer electronics variants. Pricing stratifies across automotive functional-safety tiers, industrial IP67-rated variants, and economy smartphone specifications. Cost compression in wearable device segments is intensifying because TDK and InvenSense compete aggressively on sub-2mm z-height package miniaturization. Smartphone OEMs in South Korea exhibit highest price sensitivity, while aerospace primes in Toulouse and Seattle demonstrate lowest elasticity due to 20-year service life guarantees.
Supply Chain Analysis
Foxconn, Pegatron, and ASE Group concentrate contract manufacturing capacity for MEMS combo sensor packaging across Taiwan, South Korea, and Shenzhen clusters. Silicon wafer supply draws from TSMC ecosystem partners in Hsinchu and Bosch Sensortec's captive Reutlingen facility, with aluminum nitride piezoelectric materials substituting for REACH-restricted lead-zirconate-titanate formulations. Single-source vulnerability persists for wafer-level vacuum encapsulation equipment qualified to automotive 125°C standards. Distribution runs through direct RFQ channels between automotive tier-one suppliers and foundries, bypassing traditional semiconductor distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS combo sensors are approaching a platform-economics inflection where I3C interface standardization and wearable health-monitoring interoperability will determine which foundry partnerships capture recurring specification cycles.
For Market Incumbents: Pre-empt fabless design house encroachment by accelerating ISO 26262 certification timelines below 18 months through captive capacity expansion in Germany or Taiwan. Lock in BMW and Mercedes-Benz design centers with co-located application engineering teams before NHTSA mandates compress qualification windows further. Prioritize backward integration into wafer-level vacuum encapsulation equipment to defend margin position against Asian cost competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in South Korean wearable biocompatibility certification under MFDS rules, where early compliance investment creates preference list advantages before TDK consolidates earables and smart ring formats. Target industrial robotics low-noise specifications where Analog Devices' dominance remains penetrable through specialized vibration monitoring applications. Lead with digital-output SPI/I3C variants to bypass entrenched analog interface incumbencies in home automation. For Investors and Strategic Acquirers: Capital is best deployed toward fabless MEMS design specialists with automotive functional-safety certification momentum and deep partnerships with European smartphone OEMs. Long-term viability hinges on foundry partnership survival through the next ISO 26262 qualification cycle. Monitor I3C interface adoption rates in robotics and home automation as the signal indicating which digital-output architectures will standardize across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Vacuum Encapsulation Scale-Up | Bosch Sensortec and TSMC ecosystem partners are rendering ceramic lid approaches obsolete for automotive gyroscope reliability. |
| Automotive Functional-Safety Certification | ISO 26262 documentation investments by STMicroelectronics and NXP Semiconductors freeze foundry capacity commitments for 18-24 month cycles. |
| Wearable Biocompatibility Compliance | MFDS-certified suppliers in South Korea secure preference lists before TDK consolidates ultra-thin earables and smart ring formats. |
| Digital Interface Standardization | SPI and I3C adoption by Shenzhen home automation OEMs and Boston robotics startups collapses external ADC requirements. |
| Piezoelectric Material Substitution | Aluminum nitride and scandium-doped variants replace REACH-restricted lead-zirconate-titanate in French and German foundry requalifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, automotive production databases, and MEMS foundry capacity disclosures. Interviews with tier-one supplier procurement managers, OEM platform engineers, biomedical device regulatory leads, and pure-play foundry operations directors combined with bottom-up shipment triangulation against top-down value estimates. Secondary validation drew from NHTSA crashworthiness filings, Euro NCAP scoring protocols, and REACH substance restriction updates.
Forecast inputs span capacitive versus piezoelectric transduction adoption, interface architecture migration from analog to digital, and automotive functional-safety certification propagation into consumer electronics supply chains across the analysis window. Segmentation dimensions modeled include product type, end-user certification tier, technology interface, and application form factor, with CAGRs derived from shipment-volume elasticity to specification escalations by Apple and Samsung. Industry-specific inputs incorporate wafer-level vacuum encapsulation yield learning curves and aluminum nitride piezoelectric material revalidation timelines.
Sensitivities concentrate around ISO 26262 certification bottlenecks extending beyond 24 months, REACH substance restriction scope expansions affecting piezoelectric ceramics, and I3C interface standardization timing in robotics. Forecasts reflect assumptions regarding automotive tier-one supplier design center consolidation and wearable health-monitoring regulatory harmonization. Quarterly review of NHTSA mandate updates, MFDS biocompatibility rule revisions, and foundry capacity expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Window Sensors Market