
 Singapore Ready-To-Eat Food Market | 2026-2036
Singapore Ready-To-Eat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Ready-To-Eat Food Market Analytics
Subscription-based meal replenishment is decoupling Singapore ready-to-eat food from traditional retail dependency. Nestlé S.A. leverages its global R&D network to localize flavors for Singaporean palates. Prima Limited anchors its position through backward integration into sauce manufacturing and noodle production. NTUC Fairprice Co-operative Ltd. controls shelf access through its dominant supermarket footprint across the island.
Ready-to-eat food comprises pre-processed meals requiring minimal or no preparation beyond heating, typically shelf-stable for six to eighteen months through retort processing, blast freezing, or controlled-atmosphere packaging. These products serve time-constrained consumers seeking caloric and nutritional intake without cooking infrastructure. Frozen meals command the deepest margin pools due to cold-chain logistics barriers that limit competitor entry. Online retail represents the fastest-growing distribution channel as platform economics reshape grocery procurement habits among digital-native customer segments.
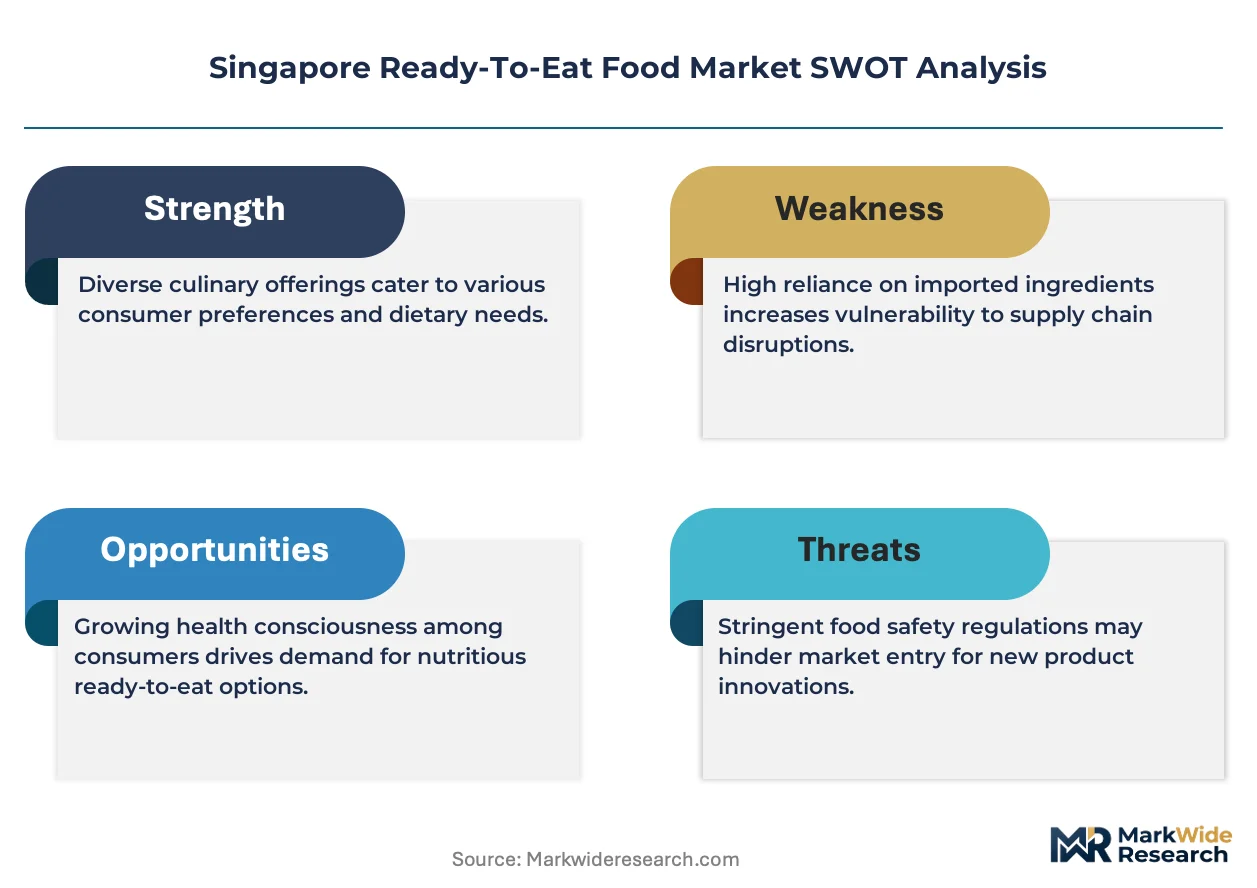
Singapore's Agri-Food and Veterinary Authority enforces strict preservative limits and labeling transparency that elevate compliance costs for imported ready-to-eat products. The Health Promotion Board's Nutri-Grade labeling system shapes consumer perception and manufacturer reformulation priorities. Enterprise Singapore's standards development initiatives align local production with ASEAN harmonization frameworks. Stakeholders must monitor how tightening sodium and sugar regulations will force portfolio restructuring before compliance deadlines crystallize.
Market Dynamics
Singapore's ready-to-eat food sector faces structural compression from dual regulatory vectors: the Agri-Food and Veterinary Authority's tightening preservative ceilings and the Health Promotion Board's Nutri-Grade labeling mandates. These frameworks force simultaneous reformulation of legacy portfolios and transparent disclosure of sodium and sugar content.
Growth Catalysts
- Urban time poverty:Working professionals in Singapore's Central Region face compressed meal preparation windows, creating sustained demand for shelf-stable caloric solutions.
- Cold-chain infrastructure maturation:Blast freezing and controlled-atmosphere packaging technologies extend product viability while preserving nutritional density.
- Enterprise Singapore standards alignment:ASEAN harmonization frameworks reduce technical barriers for local manufacturers exporting to neighboring markets.
Market Restraints
- Input cost volatility:Wheat and palm oil price fluctuations squeeze margin structures for retort-processed meal producers.
- Regulatory friction:The Agri-Food and Veterinary Authority's strict preservative limits elevate compliance costs for imported ready-to-eat products entering Singapore.
- Substitution threat:Food delivery platforms offer immediate meal access without inventory carrying costs, diverting demand from shelf-stable formats.
Strategic Opportunities
- Subscription replenishment models:Platform economics enable direct-to-consumer channels that bypass traditional supermarket gatekeepers.
- Regulatory tailwind:Nutri-Grade labeling creates first-mover advantage for manufacturers achieving A/B grade ratings before mandatory compliance deadlines.
- Technology convergence:Smart packaging integrating time-temperature indicators with mobile applications is rewriting consumer trust mechanisms.
Industry Challenges
- Reformulation capex intensity:Sodium and sugar reduction requires investment in alternative flavor systems and processing equipment.
- Talent scarcity in food science:Singapore's limited pipeline of formulation chemists specializing in clean-label preservation constrains innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Ready-To-Eat Food Market |
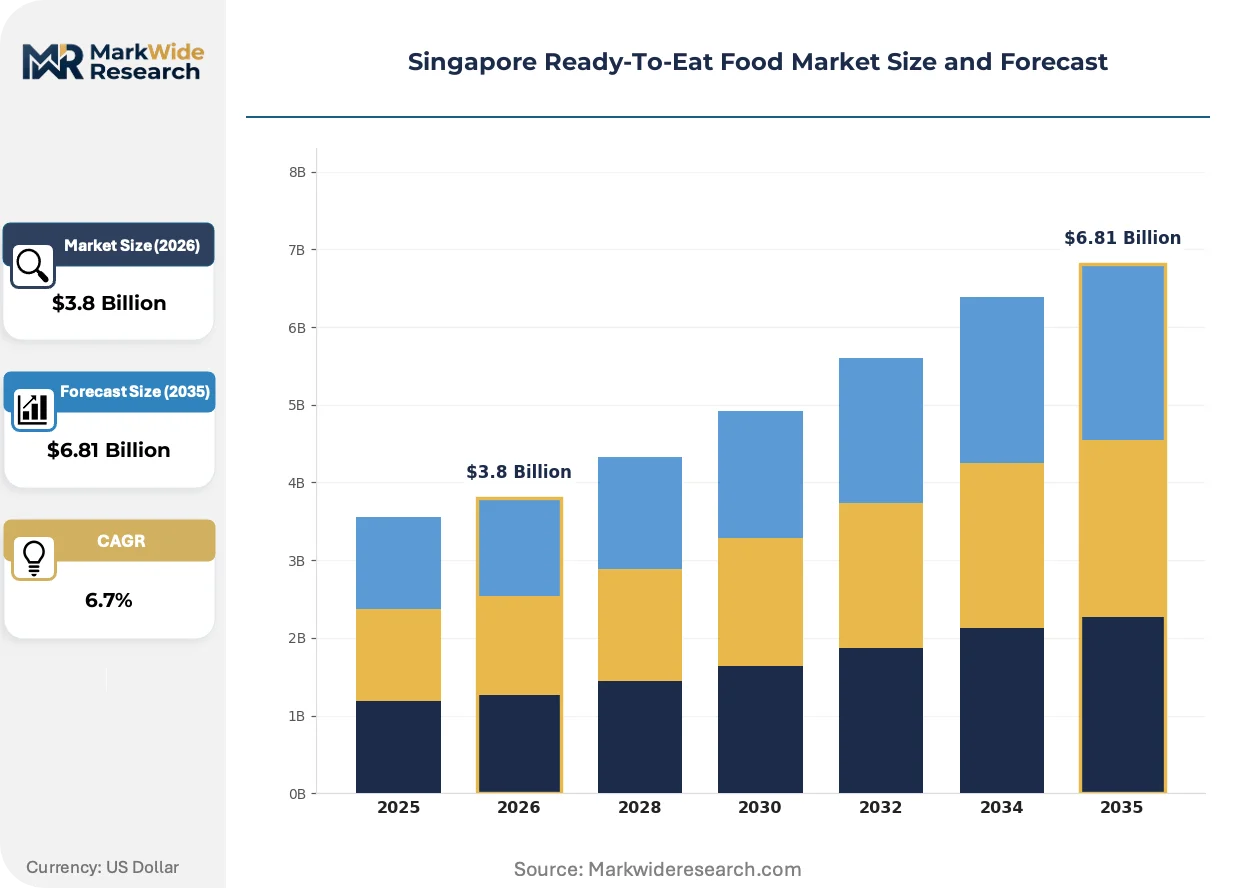
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Food, Frozen Meals, Dried Snacks, Instant Noodles Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Customer Type: Working Professionals, Students, Families, Elderly Packaging Type: Bags, Boxes, Trays, Pouches |
| Companies Covered | Nestlé S.A., PepsiCo Inc., General Mills Inc., Kellanova, Prima Limited, NTUC Fairprice Co-operative Ltd., 7-Eleven Inc., Nissin Foods Co. Inc., Pondok Abang, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Ready-To-Eat Food Market Evolving Landscape
Three vectors are compressing Singapore's ready-to-eat food value chain: smart packaging transparency, regulatory disclosure mandates, and platform-mediated procurement. These forces collectively shift competitive advantage from shelf-space control to formulation agility and direct consumer relationships.
Smart packaging integrating time-temperature indicators and QR-code traceability is rewriting consumer confidence in shelf-stable products. Young professionals in Singapore's Central Region scan packaging to verify cold-chain integrity before purchase. This technology compresses the information asymmetry that previously favored established brands with reputation capital.
The Health Promotion Board's Nutri-Grade labeling system mandates front-of-pack disclosure for sodium and sugar content. Manufacturers must reformulate legacy recipes or accept C/D grade placement that triggers consumer avoidance. Frozen meal producers face the steepest compliance curves given their reliance on sodium for preservation and palatability.
Platform economics now governs replenishment behavior among Singapore's digital-native workforce. Subscription-based meal services displace episodic supermarket purchasing with algorithmic restocking cycles. This channel shift concentrates demand forecasting risk with manufacturers while fragmenting brand loyalty across multiple competing platforms.
Singapore Ready-To-Eat Food Market Segmentation
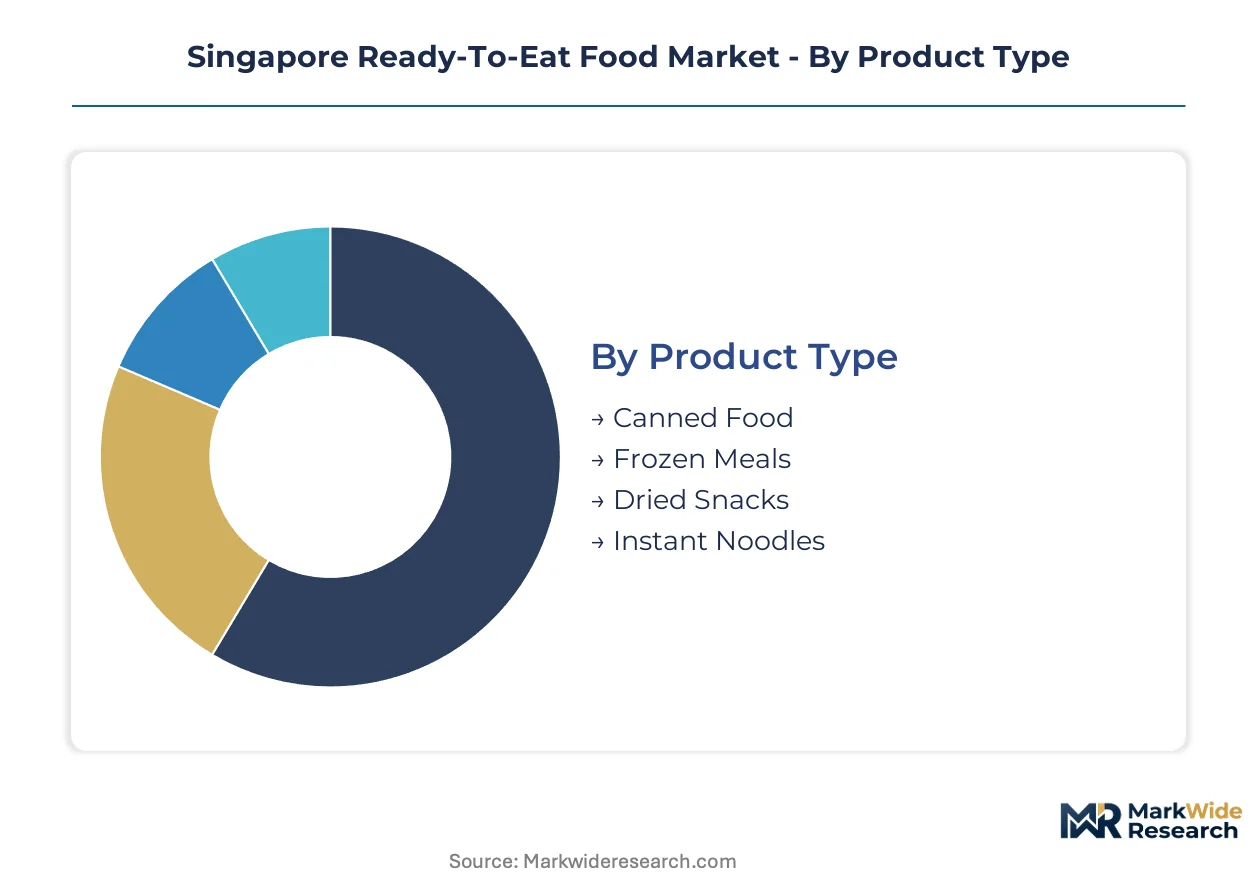
Singapore's ready-to-eat food market fragments across four distinct dimensions. Product type and distribution channel determine margin capture, while customer type and packaging format shape reformulation priorities under Nutri-Grade mandates.
Product Type:
Frozen meals command premium shelf space and deeper margin pools, while instant noodles anchor volume throughput across mass retail channels.
- Frozen Meals:Blast-frozen proteins and vegetable combinations packaged in controlled-atmosphere trays. Demand concentrates in Singapore's Central Region among working professionals seeking restaurant-quality caloric intake without preparation infrastructure. Cold-chain logistics barriers protect incumbent positions.
- Instant Noodles:Wheat-based alkaline noodles paired with dehydrated seasoning sachets and oil packets. Families in Housing Development Board estates drive volume procurement through bulk purchasing patterns. Sodium content forces aggressive reformulation ahead of Nutri-Grade compliance deadlines.
- Canned Food:Retort-processed proteins and vegetables in metal containers with shelf stability exceeding twelve months.
- Dried Snacks:Dehydrated fruit, meat jerky, and seafood variants requiring no thermal preparation before consumption.
Mature deployment sits with instant noodles. Newer deployment is concentrated in frozen meals.
Distribution Channel:
Supermarket chains control physical shelf access, while platform economics accelerate online retail penetration among digital-native segments.
- Supermarkets:Climate-controlled retail environments with dedicated frozen and ambient aisles. NTUC Fairprice's island-wide footprint dominates procurement patterns in residential zones. Slotting fees and promotional calendars structure manufacturer cash flow cycles.
- Online Retail:Algorithmic replenishment platforms with same-day or next-day cold-chain fulfillment. Working professionals in the Central Region drive subscription adoption for frozen meal restocking. Platform commission structures compress net margins versus traditional wholesale.
- Convenience Stores:Limited SKU count with emphasis on immediate consumption and impulse purchasing.
- Food Service:B2B supply to cafes, food courts, and institutional catering operations requiring bulk formats.
Channel investment concentrates with supermarkets. Fastest channel expansion is occurring through online retail.
Customer Type:
Time poverty varies sharply across demographic segments, dictating price tolerance and preparation convenience requirements.
- Working Professionals:Compressed meal windows between commercial commitments. Central Region office corridors generate concentrated demand for premium frozen formats. Disposable income supports subscription replenishment models.
- Families:Multi-person households with heterogeneous taste preferences and bulk procurement economics. Housing Development Board heartland supermarkets anchor purchasing patterns. Value-engineered instant noodle multipacks dominate basket composition.
- Students:Budget-constrained segments prioritizing caloric density per dollar over nutritional optimization.
- Elderly:Texture-modified and nutritionally fortified formats addressing chewing difficulty and dietary restrictions.
Established demand patterns align with families. Emerging demand concentration is shifting toward working professionals.
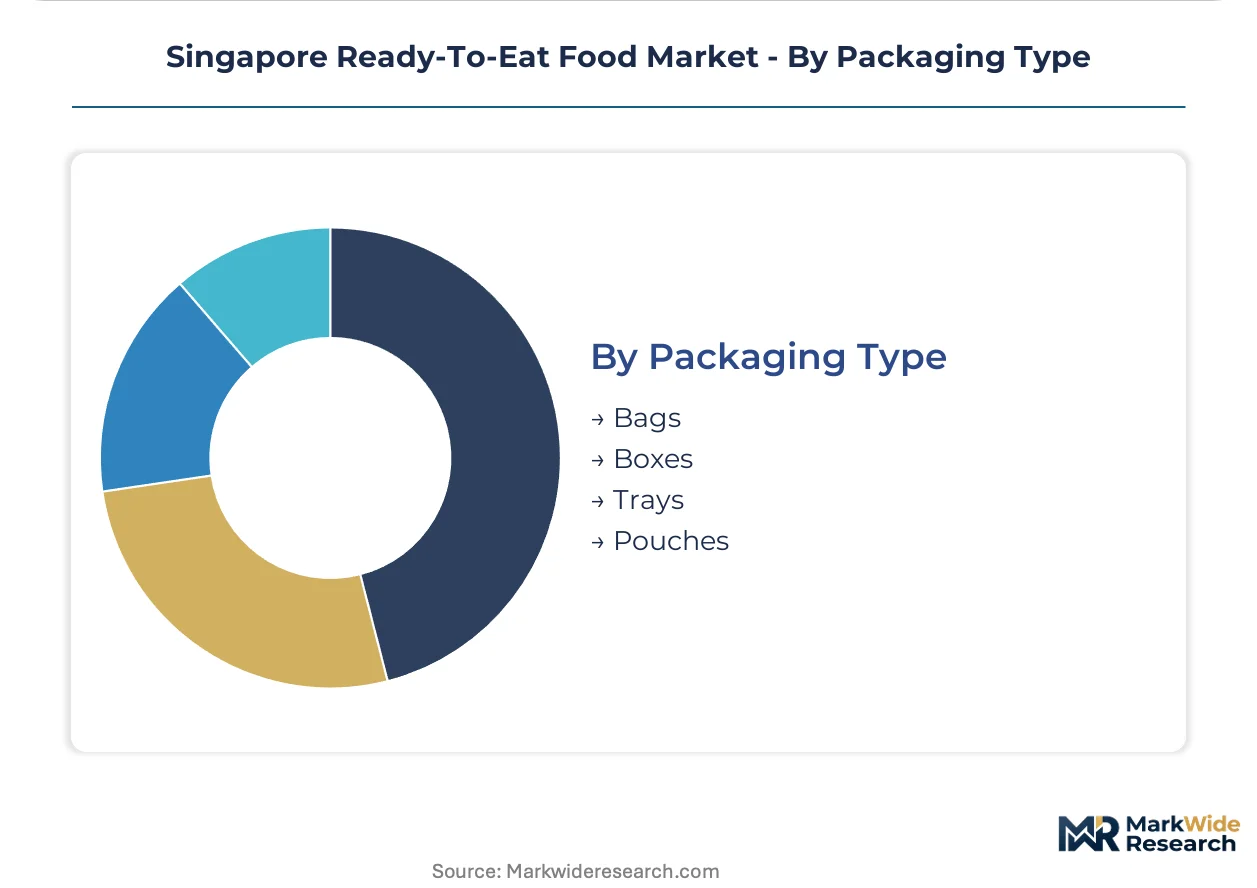
Packaging Type:
Material selection balances shelf visibility, thermal performance, and Agri-Food and Veterinary Authority compliance costs.
- Trays:Rigid plastic or aluminum containers with lidding film for frozen meal presentation. Central Region premium supermarkets favor this format for visual merchandising. Controlled-atmosphere sealing extends frozen shelf life.
- Pouches:Flexible laminated films with retort compatibility for ambient-stable proteins and sauces. Food service channels prefer this format for storage efficiency and portion control. Stand-up configurations improve shelf differentiation.
- Bags:Polyethylene or polypropylene structures for dried snacks and dehydrated components.
- Boxes:Paperboard outer shells with inner pouch protection for instant noodle bundles.
Format standardization is strongest in trays. Innovation investment is concentrating in pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore imports the majority of its ready-to-eat food inputs, creating a structural reliance on Malaysian manufacturing corridors and Indonesian agricultural supply zones. Domestic production concentrates in Jurong and Woodlands industrial estates where cold-chain infrastructure supports final-stage processing and packaging operations.
Central Region
Office towers in Raffles Place and Marina Bay generate concentrated demand for premium frozen meals among time-constrained professionals. The Health Promotion Board's Nutri-Grade labeling mandates shape purchasing decisions in supermarket chains throughout the CBD. Cold-chain logistics providers cluster in Tanjong Pagar to serve same-day replenishment cycles for subscription meal services.
Jurong Industrial Estate
Blast-freezing facilities and controlled-atmosphere packaging lines anchor Singapore's domestic manufacturing capacity for ready-to-eat proteins. Enterprise Singapore's standards development initiatives align local production with ASEAN harmonization frameworks for cross-border distribution. Food science talent scarcity constrains reformulation velocity for sodium-reduced product lines.
Woodlands Regional Centre
Proximity to the Johor-Singapore Causeway enables just-in-time sourcing of fresh ingredients from Malaysian suppliers. NTUC Fairprice distribution hubs coordinate island-wide replenishment for frozen and ambient meal formats. Smart packaging integration with mobile traceability applications is piloting in this logistics corridor.
Tampines and Eastern Towns
Housing Development Board heartland estates drive volume procurement of instant noodles and value-engineered meal solutions. Families in Bedok and Pasir Ris prioritize bulk purchasing economics over premium positioning. Nutri-Grade C/D ratings trigger consumer avoidance, forcing manufacturers to accelerate reformulation timelines.
Singapore Ready-To-Eat Food Market Competitive Landscape
Top-tier vendors anchor shelf-stable and frozen meal categories, while mid-tier specialists compete on localized flavor adaptation and platform-native distribution. The market structure reflects dual gatekeeping power: supermarket chains control physical access, while subscription platforms fragment brand loyalty through algorithmic replenishment. Three archetypes dominate—multinational CPG conglomerates with global R&D networks, regional Asian food specialists with backward integration into sauce manufacturing, and retailer-owned brands leveraging captive shelf space. Competitive intensity concentrates on portfolio reformulation for Nutri-Grade compliance and direct-to-consumer channel development bypassing traditional wholesale.
Within the multinational tier, Nestlé S.A. and General Mills Inc. exemplify global scale advantages in flavor localization and preservation technology. Prima Limited and NTUC Fairprice Co-operative Ltd. occupy positions reflecting Singapore-specific supply chain control—Prima through upstream integration into noodle and sauce production, Fairprice through dominant retail footprint across the island. These four entities represent the competitive poles around which smaller specialists and platform-native brands must position.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo Inc. |
| General Mills Inc. |
| Kellanova |
| Prima Limited |
| NTUC Fairprice Co-operative Ltd. |
| 7-Eleven Inc. |
| Nissin Foods Co. Inc. |
| Pondok Abang |
| Others |
Value Network & Pricing Analysis
Working professionals in Singapore's Central Region concentrate purchasing power for premium frozen meals, anchoring a subscription-based pricing model that displaces traditional per-unit supermarket transactions. Their demand for algorithmic replenishment compresses margin structures for manufacturers while rewarding platform intermediaries with recurring revenue streams.
Pricing Analysis
Margin tightening in frozen meals reflects cold-chain logistics costs and Nutri-Grade reformulation investments. Three-tier pricing structure across premium, standard, and economy levels separates subscription-native brands from supermarket incumbents and value-engineered instant noodle multipacks. Pricing pressure intensifies as food delivery platforms offer immediate meal access without inventory carrying costs. Families in Housing Development Board estates exhibit highest price sensitivity, while Central Region professionals tolerate premium positioning for convenience.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian manufacturing corridors for sauce components and Indonesian agricultural zones for palm oil inputs. Singapore's domestic production draws from Jurong blast-freezing facilities and Woodlands distribution hubs tethered to cross-border Causeway logistics. Supply chain risk centers on Agri-Food and Veterinary Authority preservative restrictions that disrupt imported product flows. Distribution runs through NTUC Fairprice's island-wide supermarket footprint and algorithmic online retail platforms with same-day cold-chain fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's ready-to-eat food sector is transitioning from shelf-space competition to direct-to-consumer platform economics, with smart packaging and subscription algorithms displacing traditional retail gatekeeping.
For Market Incumbents: Deepen backward integration into sauce manufacturing and controlled-atmosphere packaging production to defend margin position against platform commission structures. Prioritize Nutri-Grade A/B certification investment ahead of mandatory compliance deadlines to capture first-mover perception advantage. Lock in exclusive replenishment partnerships with subscription platforms to fragment competitor access.
For New Entrants and Emerging Players: Smart packaging integration with mobile traceability applications offers the most penetrable wedge for establishing consumer trust without legacy brand equity. Target elderly consumers in Tampines and Eastern heartland estates with texture-modified, nutritionally fortified formats underserved by current portfolios. Launch through direct-to-consumer channels bypassing NTUC Fairprice slotting fee barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier specialists with localized flavor adaptation capabilities and platform-native distribution infrastructure in Singapore. Long-term viability hinges on reformulation agility under tightening sodium and sugar regulations. Watch for Health Promotion Board enforcement acceleration as the inflection signal for portfolio restructuring urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Nutri-Grade A/B Certification Investment | Front-of-pack ratings from Singapore's Health Promotion Board trigger consumer avoidance of C/D grades. |
| Direct-to-Consumer Platform Launch | Subscription algorithms bypass NTUC Fairprice shelf access control and fragment brand loyalty. |
| Smart Packaging Integration | Time-temperature indicators with QR traceability rewrite confidence mechanisms for Central Region professionals. |
| Backward Integration into Sauce Manufacturing | Prima Limited's upstream control over noodle and sauce production anchors cost position. |
| ASEAN Harmonization Alignment | Enterprise Singapore standards enable cross-border distribution to neighboring markets. |
Research Methodology
Independent corroboration across food science executives, supermarket category buyers, cold-chain logistics operators, and Agri-Food and Veterinary Authority compliance consultants underwrites the qualitative findings. Secondary validation draws from Enterprise Singapore standards documentation, Health Promotion Board Nutri-Grade guidelines, customs import records, and Nielsen retail audit data. Bottom-up demand modeling triangulates with top-down market sizing across product type, distribution channel, customer segment, and packaging format dimensions.
Comparable-period anchoring to historical consumption patterns establishes baseline trajectory assumptions across the analysis window. Segmentation modeling incorporates product type, distribution channel, customer archetype, and packaging material dimensions with cold-chain infrastructure maturity as an industry-specific overlay. CAGRs derive from trend extrapolation adjusted for regulatory intervention timelines and platform economics penetration curves. Forecast inputs include working professional population growth in the Central Region and Nutri-Grade compliance deadline proximity.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to sodium ceilings, disruptive platform acquisition or consolidation events, and macroeconomic shocks to wheat and palm oil commodity markets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Dried Soup Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Sausage Casing Market