
 Asia-Pacific Ready-To-Eat Food Market | 2026-2036
Asia-Pacific Ready-To-Eat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ready-To-Eat Food Market Outlook
Food service buyer concentration is restructuring procurement patterns across the Asia-Pacific Ready-To-Eat Food Market. Nestlé S.A. leverages its frozen meal expertise to anchor supply contracts with institutional kitchens in Japan and South Korea. CJ CheilJedang Corp. dominates the instant noodle segment through captive distribution networks and localized flavor R&D. Ajinomoto Co. Inc. specializes in umami-based ready meals that sustain premium positioning in Thai and Indonesian retail channels.
Ready-to-eat food encompasses thermally processed, pre-cooked meals preserved through retorting, blast freezing, or controlled-atmosphere packaging to achieve shelf stability without consumer preparation. These products typically maintain moisture content below sixty percent for ambient stability or employ IQF protocols at minus forty degrees Celsius for frozen formats, serving commercial food service and time-constrained household consumption. Frozen meals command the largest value pool due to higher per-unit pricing and established cold chain infrastructure across Japan and South Korea, while instant noodles generate the highest unit volumes through mass-market penetration in Indonesia, Vietnam, and the Philippines. Flexible packaging absorbs disproportionate innovation investment as brands seek extended shelf life with reduced material cost and improved microwave compatibility.
FSSAI in India enforces additive limits and labeling transparency that elevate compliance costs for imported formulations. China's SAMR and GB standards mandate nutritional disclosure and restrict preservative categories in pre-packaged meals. Japan's METI promotes shelf-life extension technologies through applied research grants. Stakeholders must monitor divergence between national safety protocols and harmonization pressures under regional trade frameworks to optimize manufacturing footprint and registration timelines.
Market Dynamics
Urban household density across Southeast Asian megacities is compressing meal preparation time budgets and forcing retail assortment toward single-serve ambient formats. Cold chain infrastructure gaps in secondary Indian and Indonesian cities simultaneously constrain frozen segment expansion while creating protected niches for retort-pouched alternatives.
Growth Catalysts
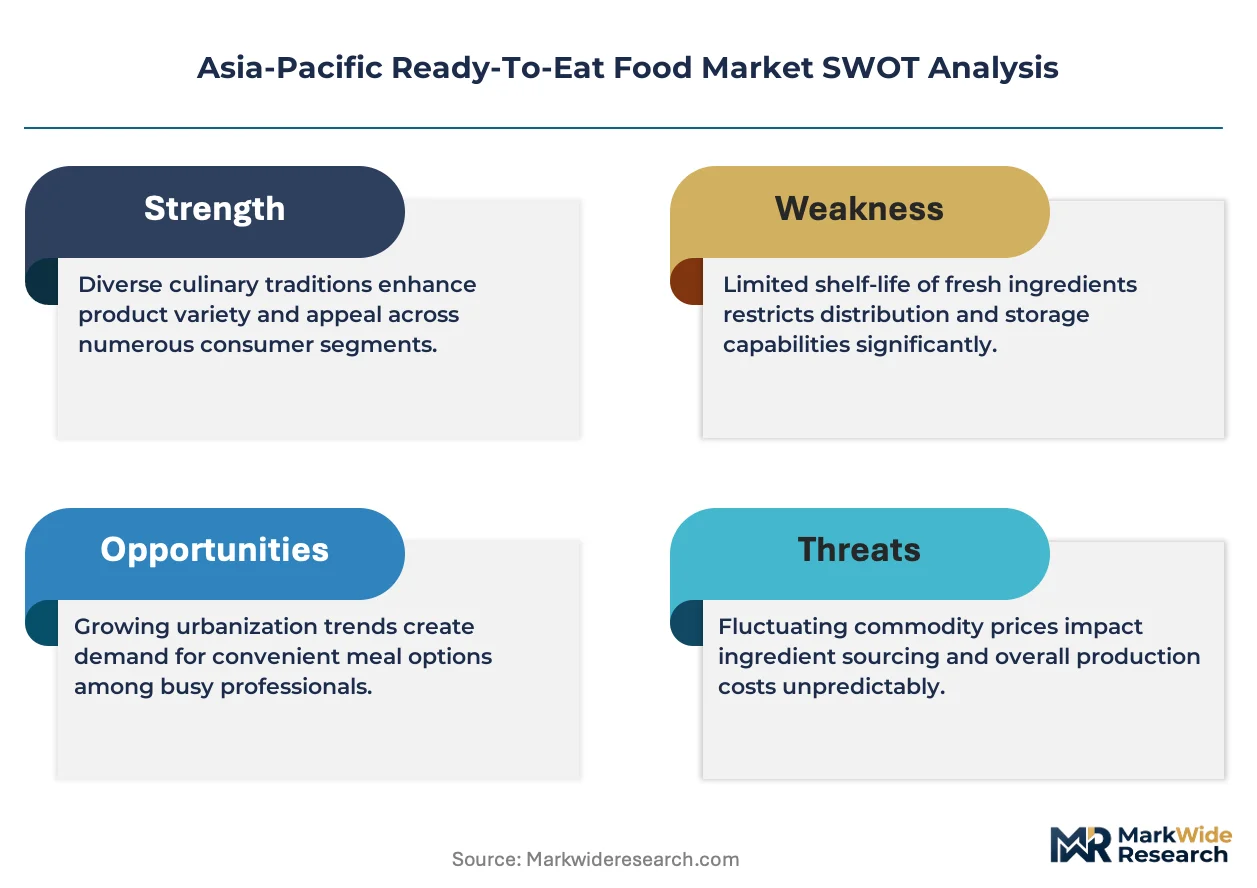
- FSSAI additive transparency mandates:India's 2021 labeling reforms forced domestic and imported brands to reformulate preservative portfolios, accelerating clean-label R&D investment across Mumbai and Delhi NCR manufacturing clusters.
- Dual-income household penetration:Working couples in Bangkok, Jakarta, and Ho Chi Minh City now represent the core weekly purchaser demographic for shelf-stable dinner solutions.
- Retort pouch barrier technology:Multi-layer polymer developments extending ambient shelf life to eighteen months without refrigeration are unlocking distribution into Philippine archipelago regions lacking reliable cold storage.
Market Restraints
- Palm oil price volatility:Instant noodle seasoning oil inputs fluctuate with Malaysian and Indonesian commodity markets, compressing margin buffers for mass-market producers.
- GB standards preservative restrictions:China's SAMR maintains narrower approved additive lists than ASEAN harmonized standards, forcing separate production runs for cross-border brands.
- Frozen format cold chain dependency:Japan and South Korea's refrigerated logistics density does not replicate across Vietnam, Cambodia, or Myanmar, capping addressable market for IQF meals.
Strategic Opportunities
- India tier-two and tier-three cities:Kolkata, Pune, and Ahmedabad exhibit underpenetrated modern trade coverage relative to saturated Mumbai and Bangalore corridors.
- E-commerce direct-to-pantry subscription:Platform logistics integration in China and South Korea enables recurring delivery of ambient meal kits bypassing traditional retail slotting fees.
- METI shelf-life extension grants:Japan's applied research funding for modified atmosphere packaging creates technology transfer potential for ASEAN contract manufacturers.
Industry Challenges
- Food technologist talent scarcity:Retort process optimization and accelerated shelf-life testing expertise concentrates in Japan and South Korea, constraining Vietnamese and Indonesian plant expansion timelines.
- Halal certification complexity:Divergent JAKIM (Malaysia), MUI (Indonesia), and MUIS (Singapore) standards force redundant facility audits for brands seeking pan-ASEAN distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ready-To-Eat Food Market |
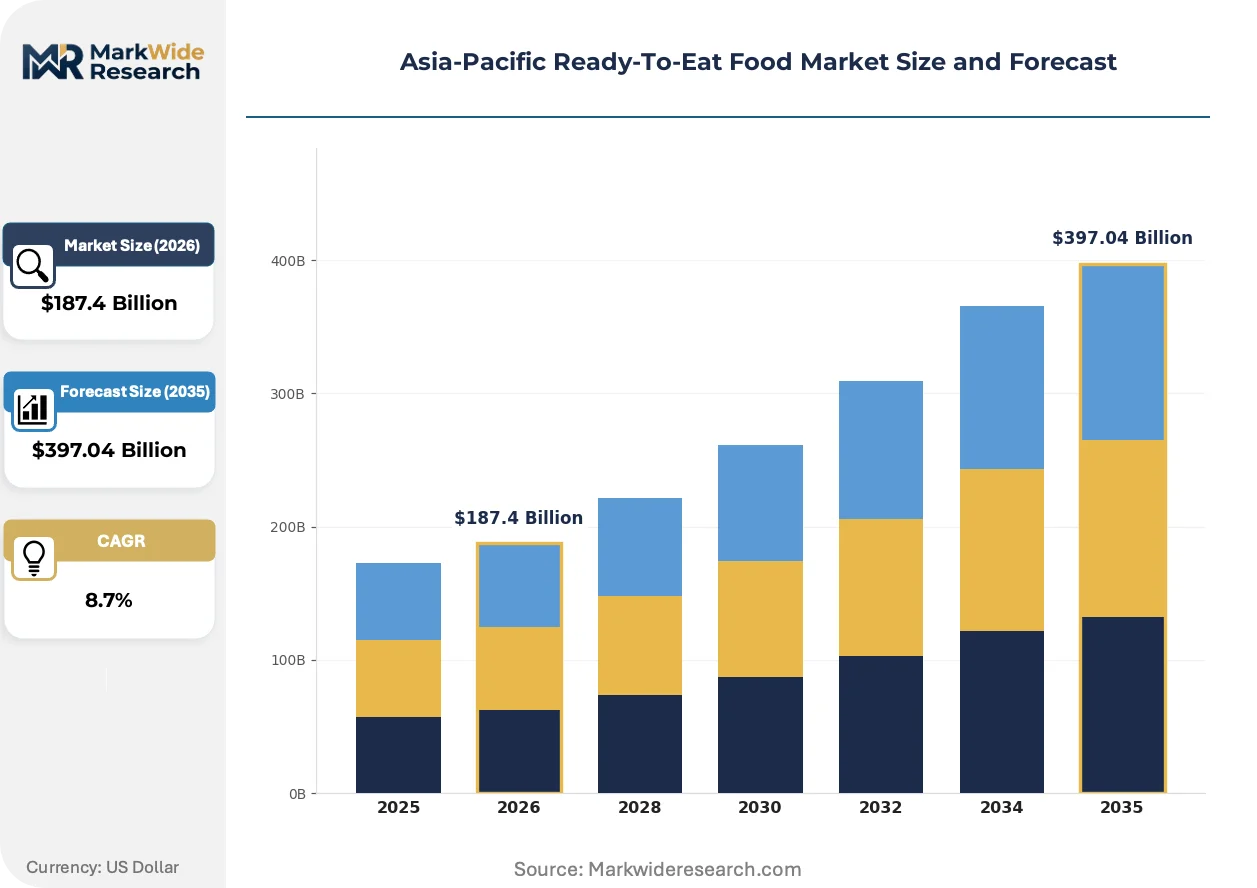
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Foods, Frozen Meals, Dried Snacks, Instant Noodles End User: Households, Institutions, Food Service, Retailers Packaging Type: Flexible Packaging, Rigid Packaging, Vacuum Sealed, Tray Sealed Distribution Channel: Offline Stores, Online Retail, Supermarkets, Convenience Stores |
| Companies Covered | PepsiCo Inc., Nestlé S.A., Unilever PLC, Kellanov, General Mills Inc., McCain Foods Ltd., Ajinomoto Co. Inc., CJ CheilJedang Corp., Kraft Heinz Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ready-To-Eat Food Market Strategic Shifts
Processing technology convergence and packaging material science are collapsing the traditional trade-off between shelf stability and sensory quality. Regulatory disclosure requirements are simultaneously elevating formulation transparency as a competitive differentiator.
High-pressure processing (HPP) for ambient-stable proteins is decentralizing production economics previously dominated by centralized retort facilities. Japanese and Australian ingredient suppliers are licensing HPP systems to mid-scale Thai and Vietnamese co-manufacturers. The technology is decentralizing geographic concentration of premium ready-meal supply away from Japan toward lower-cost ASEAN production bases.
China's SAMR enforcement of GB 28050 nutritional labeling disclosure is forcing reformulation of sodium and fat content in pre-packaged meals. Domestic brands must now declare per-serving percentages of daily reference values, compressing permissible seasoning loads in Sichuan and Cantonese flavor profiles. Instant noodle and frozen dumpling segments are responding with reduced-sodium line extensions targeting health-conscious Shanghai and Beijing consumers.
Single-person household formation is rotating demand toward portion-flexible packaging formats. South Korea's one-person household ratio exceeds forty percent, driving convenience store chains to expand chilled bento and kimbap SKUs in hundred-gram increments. Traditional family-size frozen meal formats are losing shelf space to individually portioned ambient rice bowls in Seoul and Busan retail channels.
Asia-Pacific Ready-To-Eat Food Market Segmentation
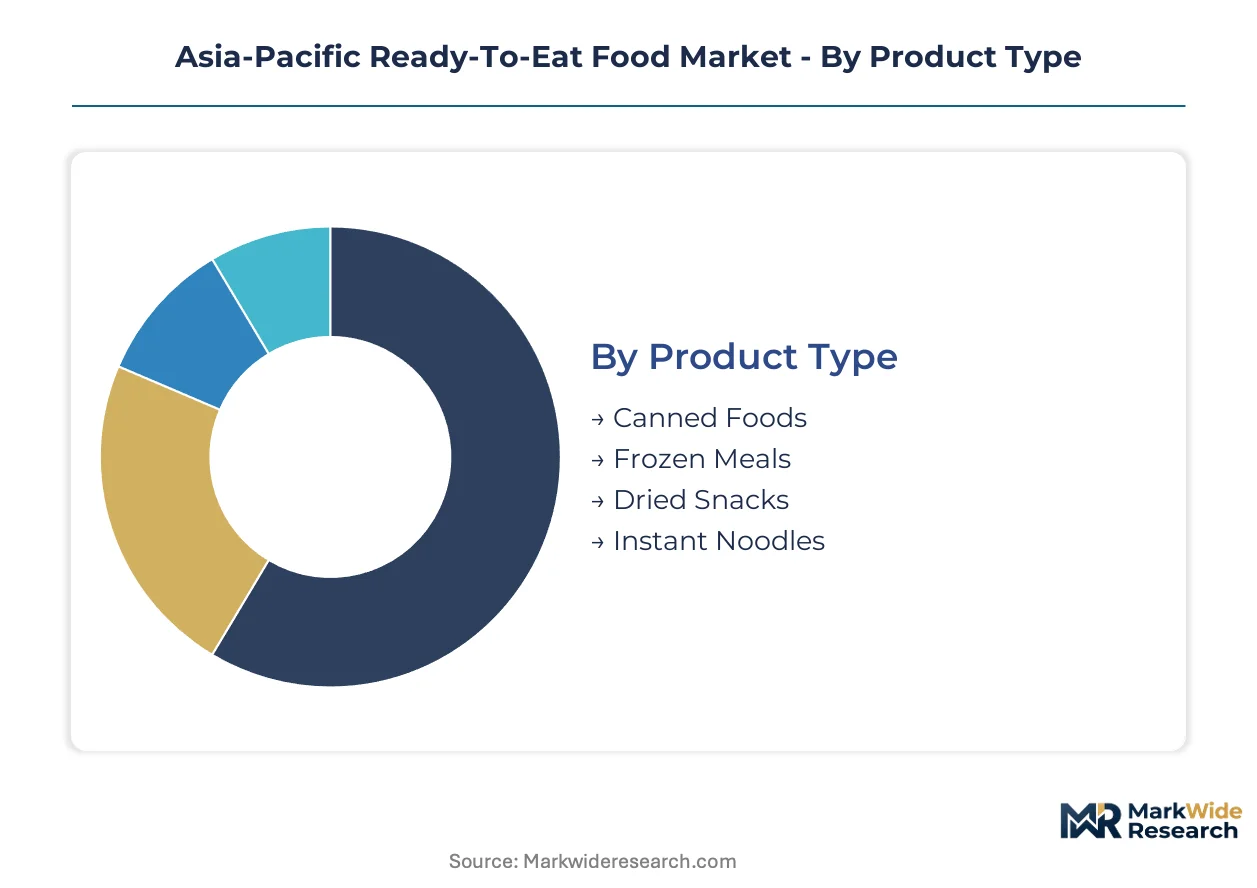
Segmentation in the Asia-Pacific Ready-To-Eat Food Market reveals how processing technology, consumption occasion, and logistics infrastructure create distinct competitive arenas. Each dimension exposes different margin structures and regulatory exposure for manufacturers operating across India, China, and Southeast Asian corridors.
Product Type:
Customization versus standardization tension runs deepest here — frozen meals demand capital-intensive cold chain coordination while ambient formats prioritize formulation flexibility for diverse national palates.
- Frozen Meals:IQF-processed proteins and vegetable components preserved at minus forty degrees Celsius retain sensory quality closest to fresh preparation. Demand concentrates in Japan's urban corridors and South Korea's dense apartment districts where refrigerated logistics penetration reaches ninety-five percent coverage, though cold chain gaps in Vietnamese and Indonesian secondary cities constrain addressable market expansion.
- Instant Noodles:Dehydrated wheat flour strands combined with palm oil-based seasoning sachets achieve mass-market unit economics through centralized retort and flash-frying production. Indonesia, Vietnam, and the Philippines absorb the highest regional volumes where single-serve packs dominate neighborhood provision shops and roadside stalls.
- Canned Foods:Thermally sterilized proteins and vegetables in metal or composite containers deliver eighteen-to-twenty-four month ambient stability for emergency stockpiling and rural distribution.
- Dried Snacks:Moisture-reduced fruits, meats, and seafood products targeting gifting occasions and travel consumption across Chinese tier-one cities and Thai tourism corridors.
Most installed capacity flows through Instant Noodles. Expansion is steepest in Frozen Meals.
End User:
Procurement authority concentrates differently across this dimension — household purchasers prioritize sensory familiarity while institutional buyers emphasize portion consistency and invoice consolidation.
- Households:Time-constrained urban couples and single-person dwellings in Bangkok, Jakarta, and Ho Chi Minh City drive weekly replenishment of ambient dinner solutions through convenience store and e-commerce channels.
- Food Service:Quick-service restaurants, office canteens, and airline catering operations in Japan and South Korea specify frozen meal components for labor cost reduction and menu standardization.
- Institutions:Hospital, school, and military feeding programs across India and China require Halal or FSSAI-certified bulk formats with extended shelf stability for inventory management.
- Retailers:Supermarket and convenience store chains in Seoul, Shanghai, and Mumbai control shelf placement and promotional pricing for branded ready-to-eat portfolios.
Volume concentrates in Households. Margin expansion is climbing the fastest in Food Service.
Packaging Type:
Material science investment intensity varies sharply — barrier film multilayers absorb disproportionate R&D spend while rigid formats compete on molded structural efficiency.
- Flexible Packaging:Multi-layer polymer pouches with oxygen scavenger integration extend ambient shelf life to eighteen months without refrigeration, unlocking distribution into Philippine archipelago regions lacking reliable cold storage infrastructure.
- Rigid Packaging:Polypropylene and polyethylene terephthalate trays with lidded sealing dominate frozen meal presentation in Japanese and South Korean retail channels where visual product inspection influences purchase decisions.
- Vacuum Sealed:Air evacuation protocols for cured meats and fermented preparations target premium positioning in Chinese tier-one city specialty retailers.
- Tray Sealed:Modified atmosphere configurations for chilled prepared meals serve South Korean convenience store chains expanding single-serve bento and kimbap SKUs.
Production gravity centers on Flexible Packaging. Technology licensing is expanding most quickly in Rigid Packaging.
Distribution Channel:
Channel control determines working capital intensity — offline retail demands slotting fee negotiation and inventory placement while direct digital routes compress margin leakage.
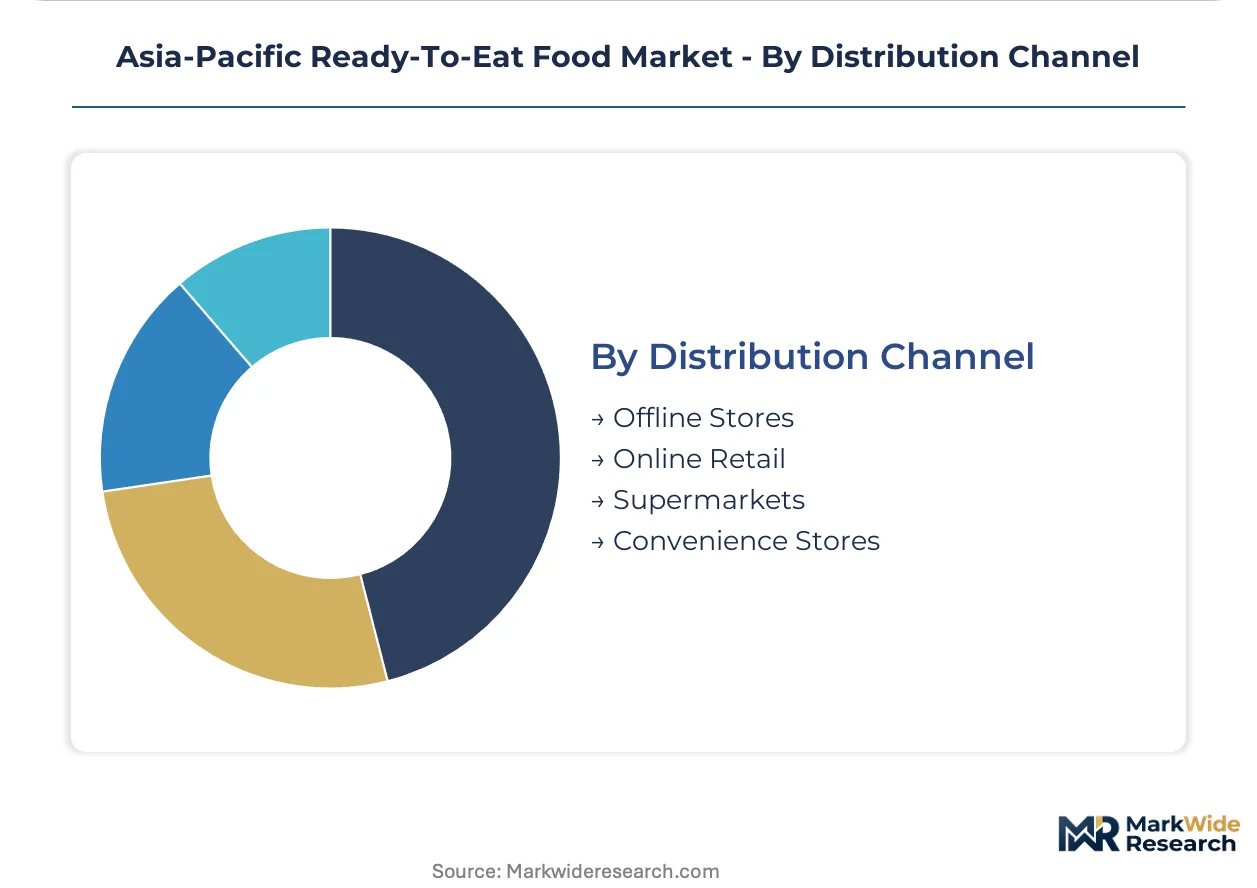
- Supermarkets:Modern trade chains in Mumbai, Delhi NCR, and Bangalore consolidate category management authority, demanding promotional support and exclusive SKU development from Nestlé, Ajinomoto, and CJ CheilJedang.
- Convenience Stores:7-Eleven, FamilyMart, and Lawson networks across Japan, Thailand, and Taiwan rotate chilled and ambient ready-to-eat assortments multiple times daily to match commuter traffic patterns.
- Offline Stores:Traditional provision shops and neighborhood grocers in Indonesian and Vietnamese secondary cities maintain instant noodle and canned food dominance through credit extension and local language service.
- Online Retail:Platform logistics integration in China and South Korea enables recurring delivery of ambient meal kits bypassing traditional retail slotting fees and capturing subscription economics.
Transaction volume concentrates in Supermarkets. Share gain is steepest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities absorb premium frozen meal volumes while India's metropolitan corridors drive mass-market instant noodle adoption through distinct regulatory and infrastructure conditions.
China
SAMR enforcement of GB 28050 nutritional labeling compels sodium reduction in Sichuan and Cantonese flavor profiles. Shanghai and Beijing consumers shift toward reduced-sodium line extensions as disclosure requirements compress permissible seasoning loads. Yangtze River Delta manufacturing clusters accommodate separate production runs for domestic and export formulations.
India
FSSAI additive transparency mandates from 2021 force preservative portfolio reformulation across Mumbai and Delhi NCR manufacturing bases. Working couples in Bangalore and Hyderabad represent the core weekly purchaser demographic for shelf-stable dinner solutions. Kolkata, Pune, and Ahmedabad exhibit underpenetrated modern trade coverage relative to saturated primary metros.
Japan
METI shelf-life extension grants promote modified atmosphere packaging research for convenience store distribution. Tokyo and Osaka apartment districts sustain refrigerated logistics penetration at ninety-five percent coverage for IQF meal formats. Single-person household ratios exceeding forty percent rotate demand toward hundred-gram portion increments in Seoul-mimicking consumption patterns.
South Korea
Platform logistics integration enables recurring direct-to-pantry delivery of ambient meal kits bypassing traditional retail slotting fees. Seoul Capital Area convenience store chains expand chilled bento and kimbap SKU rotations multiple times daily. Busan-Ulsan corridor cold chain density supports premium frozen meal distribution with established institutional kitchen supply contracts.
Indonesia
MUI halal certification requirements intersect with JAKIM and MUIS standards to force redundant facility audits for pan-ASEAN distribution ambitions. Jakarta and Surabaya drive mass-market instant noodle volumes through neighborhood provision shops and roadside stalls. Secondary city cold chain gaps create protected niches for retort-pouched alternatives lacking reliable frozen storage infrastructure.
Asia-Pacific Ready-To-Eat Food Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology and channel vectors. The market structure fragments across four to six dominant multinational anchors and numerous regional formulators serving national palates. Three strategic archetypes emerge: multinational packaged food conglomerates with frozen meal expertise, Asian family-controlled chaebols dominating instant noodle and fermented food segments, and regional specialists leveraging umami-based formulation IP. Competitive moves concentrate on portfolio diversification into clean-label extensions and strategic partnerships with platform logistics providers for direct-to-consumer subscription economics.
Within the multinational tier, Nestlé S.A. and PepsiCo Inc. occupy positions anchored by frozen and snack-meal expertise transferable across institutional and retail channels. Ajinomoto Co. Inc. exemplifies the umami-specialist archetype, while CJ CheilJedang Corp. represents the Korea-based chaebol structure with captive distribution networks. These three entities collectively illustrate how geographic origin and corporate heritage dictate competitive positioning across regulatory environments spanning FSSAI, SAMR, and METI jurisdictions.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Nestlé S.A. |
| Unilever PLC |
| Kellanov |
| General Mills Inc. |
| McCain Foods Ltd. |
| Ajinomoto Co. Inc. |
| CJ CheilJedang Corp. |
| Kraft Heinz Company |
| Others |
Value Chain & Pricing Dynamics
Palm oil futures originating from Malaysian and Indonesian commodity exchanges transmit volatility through instant noodle seasoning sachet costs into mass-market price floors across Jakarta, Manila, and Ho Chi Minh City. This input-cost channel separates premium retort-pouched meals commanding shelf-life technology premiums from economy dehydrated formats absorbing commodity squeezes.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for flexible-packaged ambient meals. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier-film technology grade and halal certification tier. Cost compression in the economy tier is intensifying because palm oil input volatility erodes margin buffers for mass-market producers. Household purchasers in Indonesian secondary cities exhibit highest price sensitivity, while Japanese convenience store chains demonstrate lowest sensitivity due to portion-flexibility premiums.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and South Korean food service buyers mandate multi-supplier qualification for retort pouch films and IQF protein components. Manufacturing gravity centers on China, Thailand, and Vietnam for flexible packaging conversion and ambient meal assembly. Raw material dependencies include Malaysian palm oil, Australian wheat flour, and Japanese modified atmosphere packaging films. Single-source vulnerability concentrates in halal certification audit capacity across JAKIM, MUI, and MUIS jurisdictions. Distribution runs through captive networks of CJ CheilJedang and platform logistics integration in Seoul and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Ready-To-Eat Food Market functions as a stable compounder where urban household formation in Southeast Asian megacities generates recurring replenishment demand for shelf-stable formats.
For Market Incumbents: Acquire retort process optimization expertise concentrated in Japanese and South Korean technical institutes to offset food technologist talent scarcity constraining Vietnamese and Indonesian plant expansion. Nestlé and Ajinomoto should deepen backward integration into modified atmosphere packaging film production to capture METI grant-funded technology transfers and defend margin position against emerging ASEAN contract manufacturers.
For New Entrants and Emerging Players: E-commerce direct-to-pantry subscription routes in South Korea and China offer the most penetrable channel architecture, bypassing supermarket slotting fees that consolidate category management authority with diversified conglomerates. Target India's tier-two cities—Kolkata, Pune, and Ahmedabad—where modern trade coverage remains underpenetrated relative to saturated Mumbai corridors. Launch with clean-label ambient rice bowls tailored to FSSAI additive transparency mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional formulators serving national palates lack scale to absorb clean-label R&D investment and dual-sourcing qualification costs. The market supports long-term viability for mid-cap specialists with captive halal certification and retort pouch barrier technology IP. Watch cold chain infrastructure buildout in Vietnamese and Indonesian secondary cities as the inflection signal for frozen segment addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | FSSAI and SAMR disclosure mandates force preservative portfolio overhaul across Mumbai and Yangtze River Delta clusters. |
| Retort Pouch Barrier Technology Licensing | METI-funded modified atmosphere packaging research transfers to ASEAN contract manufacturers decentralizing supply. |
| Direct-to-Consumer Subscription Launch | Platform logistics integration in Seoul and Shanghai captures recurring revenue bypassing retail slotting fees. |
| Halal Certification Consolidation | Harmonized JAKIM-MUI-MUIS audit protocols reduce redundant facility costs for pan-ASEAN distribution. |
| Cold Chain Infrastructure Partnership | Refrigerated logistics density gaps in Vietnamese and Indonesian secondary cities cap IQF meal penetration. |
Study Parameters
Multiple input streams—primary interviews with food technologists and retail category buyers, secondary validation through FSSAI filing databases and SAMR GB standard registrations, and trade flow analysis—were reconciled to construct segment-level demand estimates. Conversations with plant managers at Thai and Vietnamese co-manufacturers, procurement leads at Japanese convenience store chains, and regulatory affairs specialists navigating halal certification complexity informed operational constraints. Secondary sources included customs records for palm oil and wheat flour imports, METI research grant disclosures, and Nielsen retail audit data across Mumbai, Bangkok, and Jakarta. Bottom-up capacity assessments and top-down household penetration models were triangulated against macroeconomic indicators.
Data-stream reconciliation across product type, packaging technology, and distribution channel dimensions anchored the analytical framework over the projection horizon. Segmentation modeling captured frozen versus ambient format splits, flexible versus rigid packaging material science investments, and household versus food service procurement patterns. CAGRs were derived from installed capacity expansion timelines, urban household formation projections, and regulatory compliance cost trajectories. Forecast inputs incorporated cold chain infrastructure buildout assumptions and e-commerce platform logistics penetration rates.
Commodity price volatility in Malaysian palm oil markets, divergence between FSSAI and SAMR additive standards, and cold chain infrastructure deployment delays are the dominant revision risks that could compress or extend addressable market expansion. Forecasts reflect documented assumptions regarding household time-budget compression and dual-income penetration trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Australia Food Cans Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
North America Pasta Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Canned Legumes Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Ready Meals Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
UAE Breakfast Cereals Market