
 Pre-Packaged Sandwich Market | 2026-2036
Pre-Packaged Sandwich Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Packaged Sandwich Market Analysis
A capital-intensity divergence between automated production lines and artisan-scale assembly is rotating competitive dynamics across the pre-packaged sandwich sector. Greencore Group plc leverages centralized manufacturing hubs to supply major British retailers with uniform daily volumes. Tyson Foods, Inc. anchors its position through captive protein supply chains that reduce raw material cost volatility. Marks & Spencer Group plc differentiates via premium ingredient sourcing and in-house recipe development for chilled ready-to-eat formats.
Pre-packaged sandwiches consist of bread-based fillings assembled under controlled conditions, typically employing modified atmosphere packaging with gas mixtures of nitrogen and carbon dioxide to achieve shelf lives of three to seven days without artificial preservatives, serving commercial food retail and immediate consumption occasions. Vegetarian and gourmet segments capture expanding margin pools as health-conscious consumers trade up from standard meat-based offerings. The online retail channel sustains above-average velocity as subscription meal services and corporate catering platforms aggregate recurring orders. Gluten-free formulations occupy a premium niche where ingredient costs run higher but price elasticity remains favorable among diagnosed celiac and lifestyle-adopter populations.
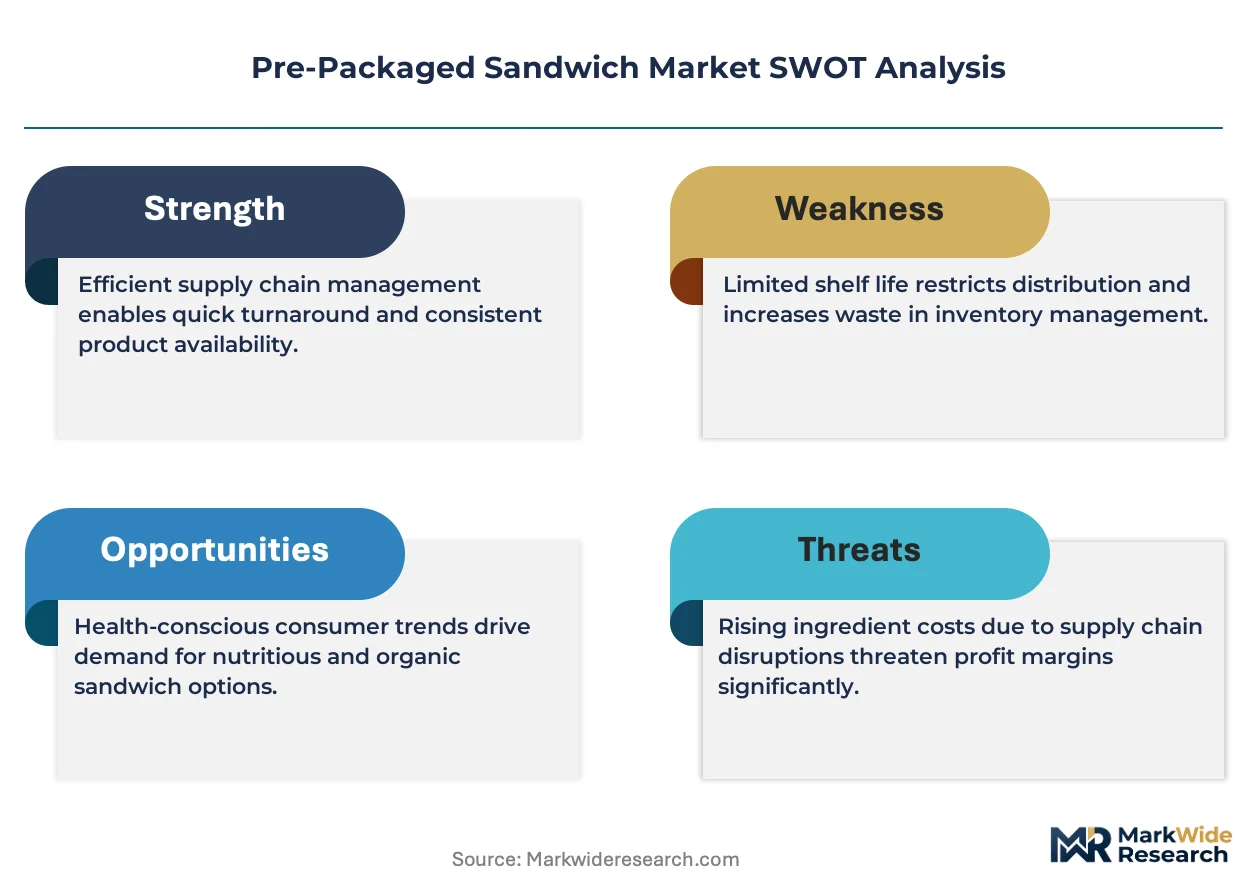
The FDA governs refrigerated food safety through Hazard Analysis Critical Control Point mandates while the USDA inspects meat-containing sandwiches under FSIS jurisdiction, creating dual compliance pathways that shape plant certification requirements and interstate distribution eligibility. The EU Green Deal packaging waste directives and national plastic reduction statutes in France and Germany are forcing material transitions toward fiber-based trays and compostable films. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to front-load capital into recyclable packaging infrastructure or absorb incremental compliance costs through supplier pass-through structures.
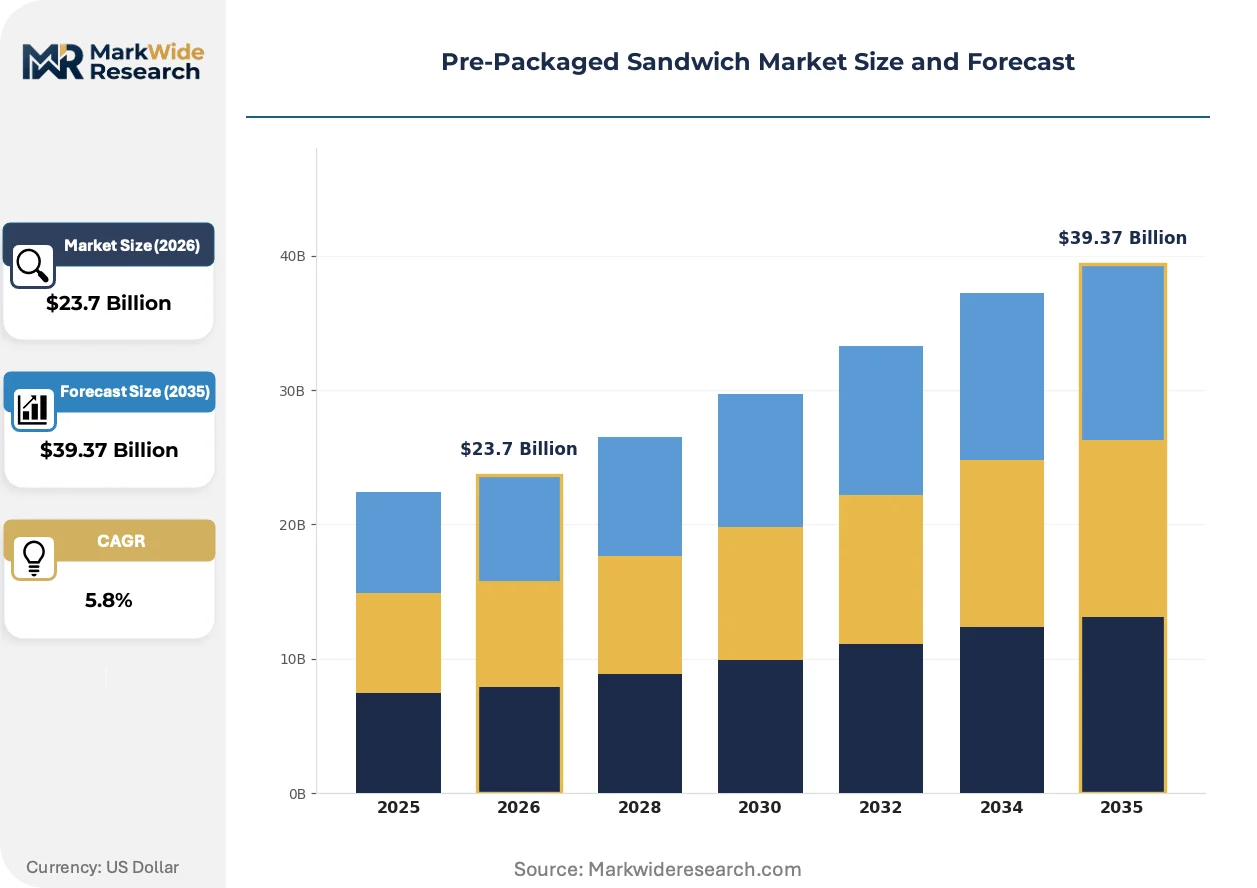
Market Dynamics
Modified atmosphere packaging technology is compressing shelf-life limitations while EU packaging waste directives force simultaneous capital redeployment into fiber-based tray systems, creating dual-track investment pressures across manufacturing footprints.
Growth Catalysts
- Urban Office Density:Corporate campus catering contracts and central business district foot traffic generate predictable daily volume commitments for chilled ready-to-eat formats.
- FSIS Modernization:Streamlined USDA inspection protocols for meat-containing sandwiches reduce plant certification timelines and expand interstate distribution eligibility for qualified facilities.
- MAP Technology Maturation:Nitrogen-carbon dioxide gas mixture systems now achieve seven-day preservative-free shelf life, unlocking convenience retail placement previously reserved for frozen alternatives.
Market Restraints
- Wheat Price Volatility:Bread input costs fluctuate with Black Sea grain export disruptions and North American drought cycles, compressing margin buffers on standard-tier products.
- Single-Site Dependency:Centralized manufacturing hub models concentrate production risk; flooding or labor action at key UK facilities disrupts national retailer supply.
- Refrigerated Last-Mile Costs:Cold chain maintenance requirements exclude pre-packaged sandwiches from ambient e-commerce logistics, limiting pure-play online penetration.
Strategic Opportunities
- German Plastic Reduction Statutes:Compostable film mandates create first-mover advantage for suppliers with certified fiber-tray capacity ahead of 2025 implementation deadlines.
- Subscription Meal Platforms:Corporate catering aggregators and direct-to-consumer breakfast box services represent recurring revenue channels with lower customer acquisition costs than retail slotting.
- Gluten-Free Premium Niche:Diagnosed celiac populations and lifestyle adopters accept ingredient cost premiums, supporting dedicated production lines with favorable price elasticity.
Industry Challenges
- Dual Jurisdiction Compliance:FDA HACCP and USDA FSIS inspection requirements create parallel certification pathways that extend facility commissioning timelines and raise audit costs.
- Recipe-to-Shelf Coordination:Short shelf lives demand precise demand forecasting; misalignment between in-house development cycles and retailer promotional calendars generates spoilage losses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Packaged Sandwich Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Meat, Gourmet, Gluten-Free Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice End User: Office Workers, Students, Travelers, Health-Conscious Consumers Packaging Type: Tray, Bag, Box, Clamshell |
| Companies Covered | Greencore Group plc, Marks & Spencer Group plc, Tyson Foods, Inc., Norac Food, Raynor Foods Limited, Landshire, Inc., AdvancePierre Foods, ABP Food Group, Around Noon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Packaged Sandwich Market Emerging Trajectories
Competitive positioning is splitting between automated high-volume production and artisan-scale assembly, with packaging material transitions and channel-specific format development accelerating simultaneously.
Modified atmosphere packaging is bifurcating the competitive landscape. Gas-flush systems with real-time leak detection now dominate premium chilled segments. Major British retailers demand MAP certification as a listing prerequisite. This technology is compressing the viable shelf-life gap between centralized production and store-level assembly, forcing mid-scale operators to choose between capital-intensive automation or niche positioning.
EU Green Deal packaging waste directives are mandating material transitions. Extended producer responsibility frameworks in France and Germany now assign end-of-life costs to original manufacturers. Chilled ready-to-eat formats face the steepest compliance curves due to multi-layer film requirements; suppliers are front-loading capital into fiber tray and compostable film lines or accepting supplier pass-through structures that erode unit economics.
Corporate procurement departments are consolidating foodservice contracts under single-source agreements. Subscription meal services and campus catering platforms aggregate fragmented demand into predictable weekly volumes. This concentration is most visible in London and Manchester financial districts, where facilities management firms negotiate exclusive supply relationships covering breakfast, lunch, and meeting catering.
Pre-Packaged Sandwich Market Segmentation
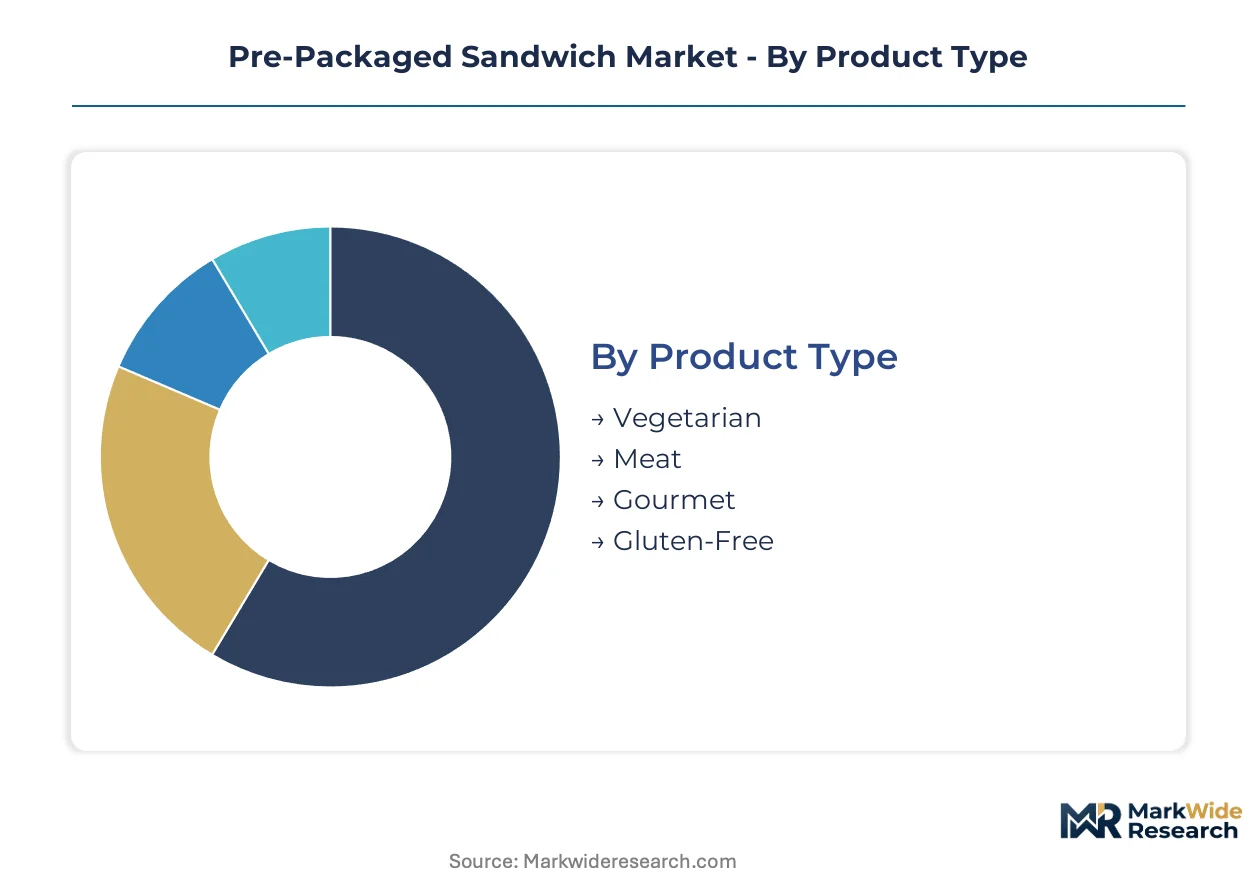
Pre-packaged sandwich segmentation reveals divergent margin profiles across product formats and channel structures. Channel-specific packaging requirements and end-user occasion patterns create distinct investment thresholds for manufacturers targeting volume versus premium positioning.
Product Type:
Substitution pressure from foodservice assembly and in-house corporate catering most threatens standard meat-based formats, while premium and restricted-diet segments defend share through ingredient differentiation.
- Meat:Standard deli fillings dominate unit economics through protein supplier scale and automated slicing lines. Demand concentrates in United Kingdom convenience retail where grab-and-go breakfast and lunch occasions sustain predictable daily velocity against fresh foodservice alternatives.
- Gourmet:Premium ingredient combinations command shelf space through in-house recipe development and shorter production runs with artisan assembly. Marks & Spencer and Waitrose list these as destination categories for affluent urban consumers trading up from standard tiers.
- Vegetarian:Plant-based fillings expand placement as health-conscious office workers reduce meat consumption.
- Gluten-Free:Dedicated production lines serve diagnosed celiac and lifestyle-adopter populations at ingredient cost premiums.
Meat retains volume leadership; gourmet holds the steepest expansion curve.
Distribution Channel:
Cost tier separation between high-frequency retail and relationship-driven foodservice contracts shapes capital allocation across manufacturing footprints.
- Supermarkets:Chilled ready-to-eat fixtures in Tesco, Sainsbury's, and Asda generate weekly promotional cycles demanding precise demand forecasting and MAP-certified supply continuity. Greencore's centralized hub model matches this channel's volume concentration and listing compliance requirements.
- Online Retail:Subscription meal platforms and corporate catering aggregators aggregate fragmented demand into recurring weekly volumes with lower customer acquisition costs than retail slotting. Cold chain maintenance requirements exclude this channel from ambient e-commerce logistics.
- Convenience Stores:Extended hours and travel-hub placement capture impulse occasions outside standard grocery trips.
- Foodservice:Direct supply to corporate campuses and business districts operates on contract terms distinct from retail.
Supermarkets retain volume leadership; online retail gains share fastest through subscription velocity.
End User:
Application-specific consumption patterns separate daily habit-driven demand from occasional and restricted-diet purchasing.
- Office Workers:Central business district foot traffic and corporate campus catering contracts generate predictable daily commitments for chilled formats. London and Manchester financial districts concentrate facilities management negotiations covering breakfast, lunch, and meeting occasions.
- Health-Conscious Consumers:Ingredient transparency and nutritional labeling drive trade-up from standard tiers toward vegetarian, reduced-sodium, and clean-label formulations. This segment accepts price premiums for perceived wellness benefits.
- Students:Budget-constrained purchasing favors value-tier placement in university-adjacent convenience retail.
- Travelers:Transport-hub convenience stores and service station forecourts capture time-pressured occasions.
Office workers retain volume leadership; health-conscious consumers show the steepest expansion trajectory.
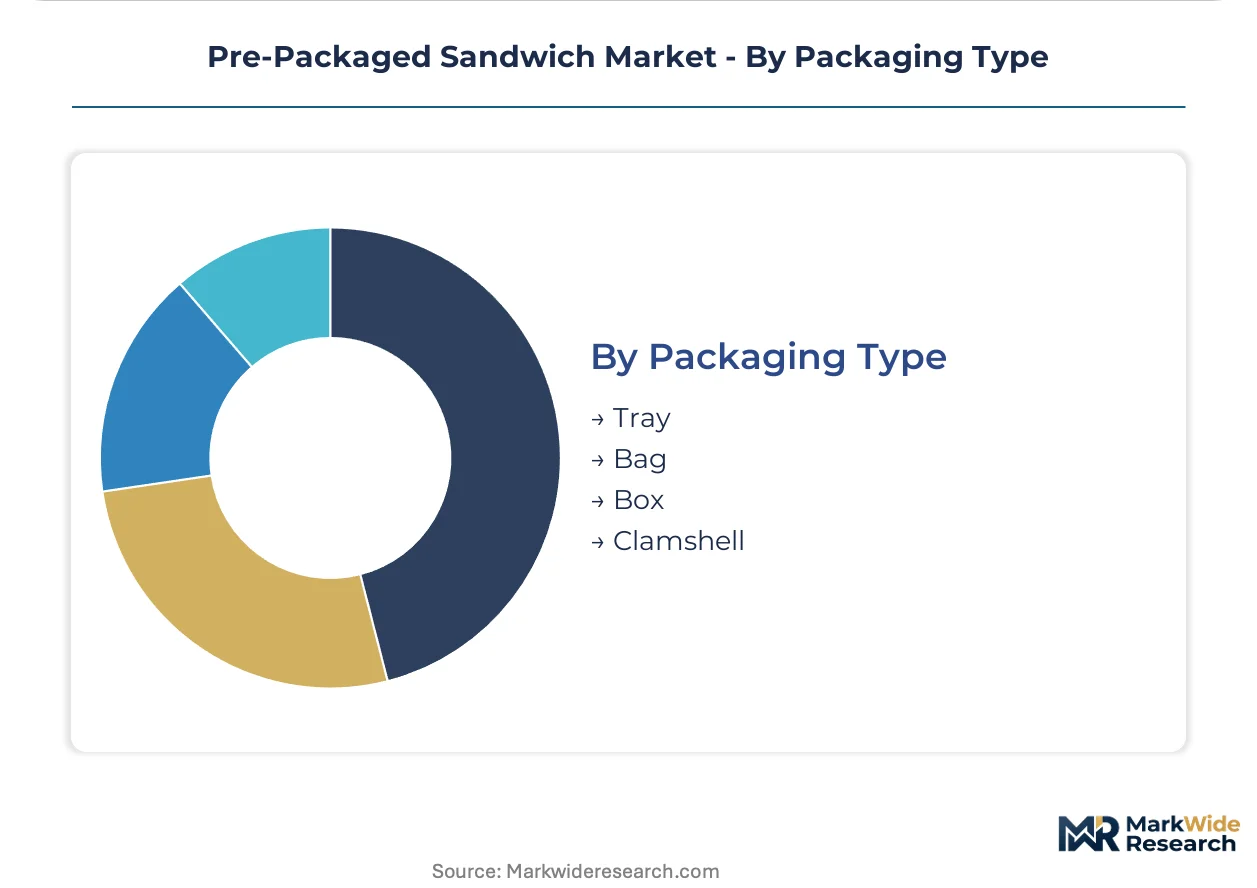
Packaging Type:
Margin structure varies with material compliance costs and shelf-life performance requirements across format specifications.
- Tray:Fiber-based rigid formats face the steepest EU Green Deal compliance curves as France and Germany mandate plastic reduction transitions. Extended producer responsibility frameworks assign end-of-life costs to original manufacturers, forcing capital front-loading into compostable lines.
- Clamshell:Hinged rigid structures dominate premium chilled visibility with superior product protection and stacking efficiency. Marks & Spencer specifies clamshell formats for its premium sandwich tier to differentiate shelf presentation.
- Bag:Flexible film structures serve ambient-stable formats with lower unit costs.
- Box:Paperboard formats support meal-kit and subscription channel requirements.
Tray formats retain volume leadership; clamshell commands the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom runs a structural trade surplus in pre-packaged sandwiches, exporting chilled ready-to-eat formats to Ireland and continental Europe while importing minimal volumes. This export orientation concentrates manufacturing investment around British distribution hubs serving cross-channel retail contracts.
United Kingdom
Corporate campus catering contracts in London and Manchester financial districts sustain daily volume commitments for chilled formats. The Food Standards Agency enforces Hazard Analysis Critical Control Point protocols across meat-containing and vegetarian production lines. Birmingham and the East Midlands host centralized manufacturing hubs supplying Tesco, Sainsbury's, and Asda with MAP-certified daily volumes.
Germany
Office worker demand in Frankfurt and Munich central business districts drives grab-and-go breakfast and lunch occasions. The EU Green Deal packaging waste directives mandate fiber-based tray transitions by 2025, assigning extended producer responsibility costs to original manufacturers. Bavaria's food processing clusters near Nuremberg are retooling compostable film lines ahead of statutory deadlines.
France
Parisian transport-hub convenience stores and La Défense corporate towers generate impulse and contract-driven demand. ANSM and DGCCRF coordinate enforcement of chilled food safety standards alongside national plastic reduction statutes. The Île-de-France region concentrates artisan-scale assembly operations supplying premium retailer tiers with shorter production runs.
United States
Urban office density in New York, Chicago, and San Francisco corporate campuses supports subscription meal platform growth. FDA HACCP and USDA FSIS maintain dual jurisdiction over meat-containing sandwiches, creating parallel certification pathways. The Midwest corridor between Illinois and Ohio anchors automated production lines serving national retail and foodservice contracts.
Ireland
Dublin's technology sector campuses and financial services hubs import British-manufactured sandwiches through cross-channel supply chains. The Food Safety Authority of Ireland aligns with EU chilled food directives while monitoring import compliance. Cork and Limerick distribution centers handle secondary consolidation for regional convenience retail placement.
Pre-Packaged Sandwich Market Vendor Landscape
Concentration sits with diversified food manufacturers and captive retail supply chains. The vendor base splits between centralized production specialists and premium-tier in-house developers. Three archetypes dominate: automated high-volume suppliers, protein-integrated conglomerates, and retailer-captive premium developers. Competitive moves center on MAP technology licensing and fiber-based packaging capacity front-loading ahead of EU compliance deadlines.
Among British-Irish food manufacturers, Greencore Group plc and Marks & Spencer Group plc exemplify divergent scale-positioning strategies, while Tyson Foods, Inc. represents the protein-integrated conglomerate archetype with upstream supply control. These three anchors illustrate how competitive positioning splits between volume-driven automation, premium recipe development, and backward integration into raw material sourcing.
| Leading Market Players |
|---|
| Greencore Group plc |
| Marks & Spencer Group plc |
| Tyson Foods, Inc. |
| Norac Food |
| Raynor Foods Limited |
| Landshire, Inc. |
| AdvancePierre Foods |
| ABP Food Group |
| Around Noon |
| Others |
Supply Flow & Price Mechanics
FDA HACCP and USDA FSIS dual certification requirements gate both supplier qualification and price-tier separation in the pre-packaged sandwich sector, compressing margin structures for uncertified operators while rewarding compliant facilities with premium channel access. This regulatory threshold concentrates pricing power among manufacturers with parallel inspection pathways, forcing non-compliant players toward commodity convenience tiers or regional foodservice contracts.
Pricing Analysis
Corporate procurement departments anchor contract-based pricing structures across subscription meal platforms and campus catering aggregators. Three-tier pricing stratifies across gourmet, standard meat-based, and value vegetarian levels, with MAP certification and fiber-tray compliance serving as the primary differentiation drivers. Pricing pressure stems from wheat input cost volatility and extended producer responsibility packaging mandates, compressing margins on standard-tier products. Students and budget-constrained travelers exhibit highest price sensitivity, while health-conscious office workers and diagnosed celiac populations accept ingredient premiums for restricted-diet formulations.
Supply Chain Analysis
Just-in-time inventory models dominate chilled ready-to-eat formats where three-to-seven-day shelf lives preclude strategic stockpiling. Manufacturing concentrates in the United Kingdom, Germany, and the United States, with Birmingham and the East Midlands anchoring European volume. Raw material dependencies center on Black Sea wheat flows, captive protein supply chains, and compostable film transitions. Single-site hub concentration creates vulnerability to flooding or labor disruption. Distribution runs through centralized retailer supply chains and corporate catering platforms, with cold chain requirements excluding ambient e-commerce logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-packaged sandwich competitive fragmentation creates niche opportunities as health-conscious consumers and subscription meal platforms fragment demand away from supermarket concentration. This demand-side shift rewards specialized players with certification agility and channel-specific format development.
For Market Incumbents: Shield market position by front-loading capital into fiber-tray and compostable film capacity ahead of EU Green Deal implementation deadlines. Secure backward integration into captive protein supply chains to reduce raw material cost volatility exposure. Greencore's centralized hub model demonstrates how MAP-certified volume concentration defends retailer listing continuity against artisan-scale challengers.
For New Entrants and Emerging Players: Corporate catering platform under-service in secondary UK cities and German financial districts outside Frankfurt and Munich represents immediate white-space opportunity. Target gluten-free and gourmet vegetarian segments where ingredient premiums support favorable price elasticity and dedicated production line economics. Pursue direct-to-subscription-platform go-to-market routes that bypass retail slotting fee barriers.
For Investors and Strategic Acquirers: EU packaging waste directive implementation reshapes the acquisition landscape toward fiber-tray capacity holders and MAP technology licensees. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than brand equity alone. Target acquisition archetypes include mid-scale operators with certified compostable lines and established corporate catering relationships. Watch for tariff exposure on Black Sea wheat flows as the critical inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| MAP Technology Licensing | Seven-day preservative-free shelf life unlocks convenience retail placement previously reserved for frozen alternatives. |
| Fiber-Tray Capacity Expansion | EU Green Deal compliance mandates in France and Germany assign extended producer responsibility costs to original manufacturers. |
| Corporate Catering Platform Partnership | Subscription meal services aggregate fragmented demand into predictable weekly volumes with lower customer acquisition costs. |
| Gluten-Free Production Line Investment | Diagnosed celiac and lifestyle-adopter populations accept ingredient cost premiums supporting favorable price elasticity. |
| Captive Protein Supply Integration | Tyson Foods demonstrates how upstream control reduces raw material cost volatility exposure across meat-containing formats. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with retail category buyers, corporate catering procurement managers, food manufacturing plant directors, and chilled distribution logistics coordinators. Secondary validation drew from FDA FSIS inspection records, EU packaging directive filings, Food Standards Agency enforcement data, and customs trade flows for wheat and protein inputs. Bottom-up volume modeling triangulated against top-down market sizing across product type, distribution channel, and end-user segmentation dimensions.
Across the analysis window, forecasts employed a structured analytical framework modeling meat, gourmet, vegetarian, and gluten-free product trajectories alongside supermarket, online retail, convenience store, and foodservice channel dynamics. CAGRs derived from segment-level growth rate calibration against macroeconomic consumption indicators and regulatory implementation timelines. Forecast inputs incorporated MAP technology adoption curves, EU Green Deal compliance cost pass-through assumptions, and wheat price volatility scenarios.
Material uncertainties — Black Sea grain export disruption, labor action at centralized UK manufacturing hubs, and accelerated EU plastic reduction statute enforcement — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding shelf-life extension technology maturation and retailer private-label expansion rates. Revision becomes warranted when wheat input cost volatility or packaging compliance cost pass-through crosses thresholds that compress standard-tier product margins below viable production economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Dried Honey Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
North America Breakfast Cereals Market