
 Carbon Labeled Packaged Meal Market | 2026-2036
Carbon Labeled Packaged Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Labeled Packaged Meal Market Insights
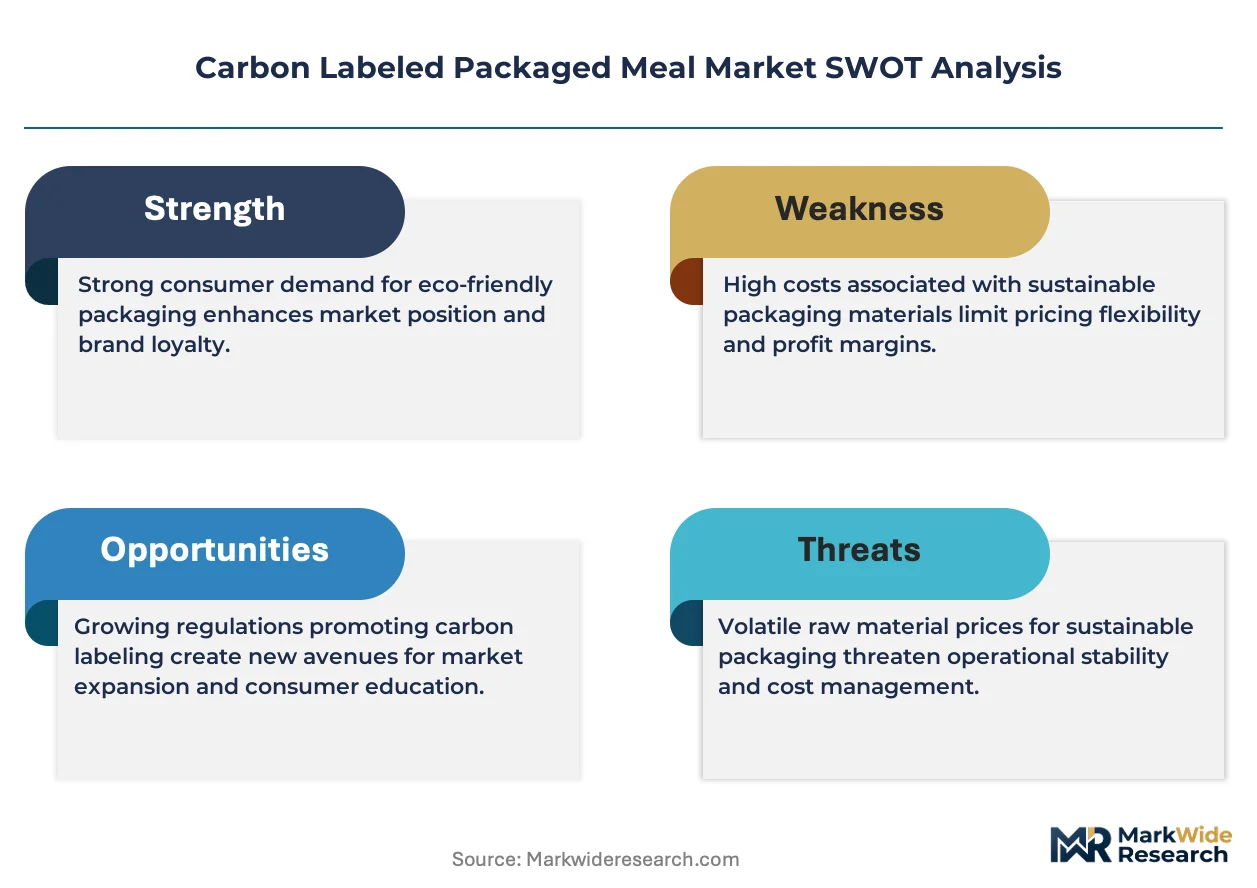
Project finance for climate-tech infrastructure is fragmenting capital access across the Carbon Labeled Packaged Meal landscape. Nestlé leverages its captive supply chain to secure lower-carbon ingredient streams at scale. Unilever anchors its competitive position through intensive R&D spending on lifecycle assessment tooling. HelloFresh competes by controlling last-mile logistics networks that trim transport emissions per delivery.
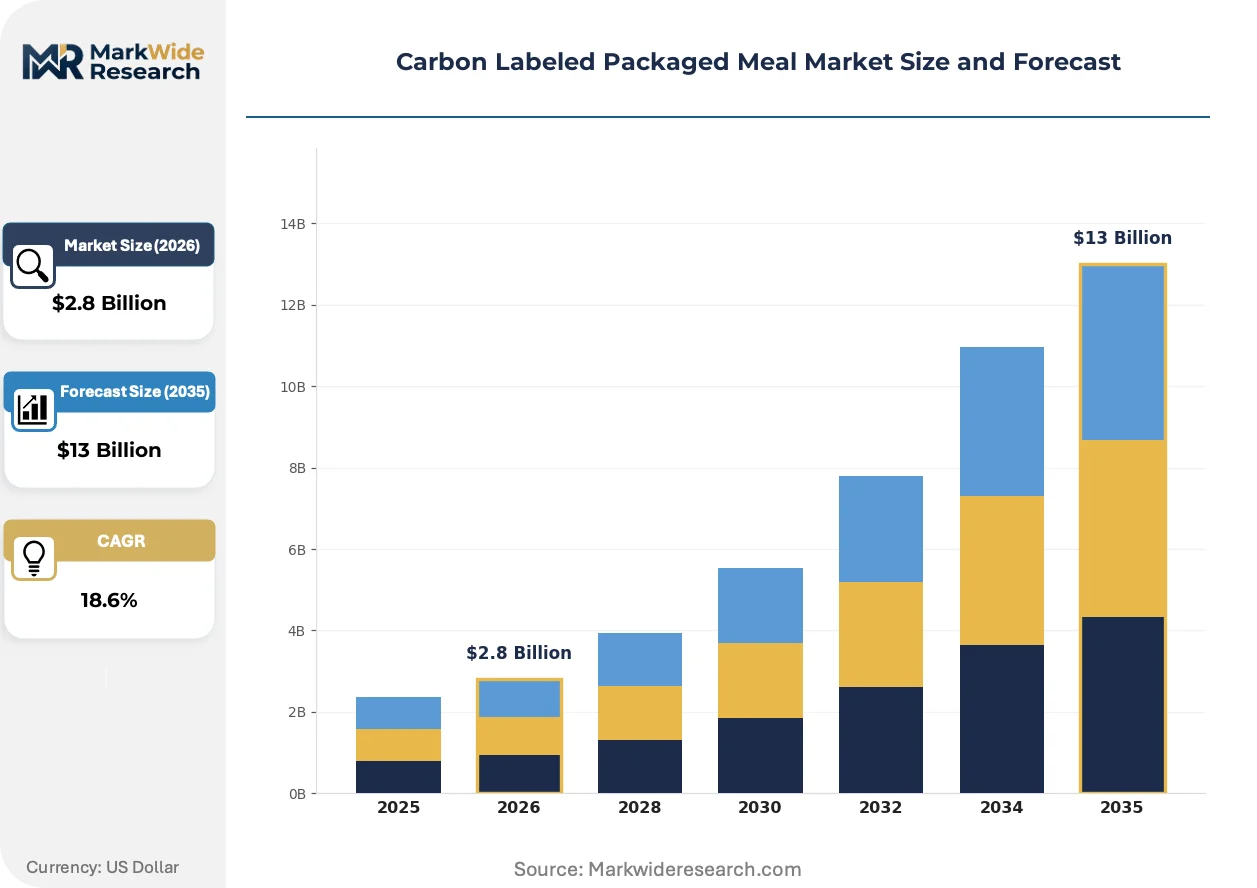
Carbon labeled packaged meals are pre-portioned food products carrying verified greenhouse gas emissions data, typically measured in CO2-equivalent kilograms per serving and audited through ISO-compliant lifecycle assessment protocols. Ready-to-eat meals command the dominant share of current revenue as shelf-stable formats simplify carbon accounting across complex supply chains. Frozen entrees represent the fastest-growing product category, driven by cold-chain innovations that reduce refrigeration energy intensity. Paperboard boxes capture widening margin pools as brand owners absorb premium packaging costs to signal environmental credibility.
The EU Green Deal and its Farm to Fork Strategy mandate standardized carbon disclosure for food products sold within member states. EFSA guidelines on environmental claims constrain how manufacturers communicate carbon reductions on pack labels. Stakeholders must monitor whether emerging national carbon labeling schemes achieve mutual recognition or fragment into competing compliance architectures.
Market Dynamics
Corporate procurement teams are rewriting supplier scorecards to include verified carbon footprints, forcing packaged meal manufacturers to reengineer sourcing relationships and audit protocols. This contractual pressure is compressing margins for laggards while rewarding early adopters with preferred vendor status.
Growth Catalysts
- EU Green Deal carbon border adjustments:Exporters into member states must now document embedded emissions, creating compliant supply chain demand for verified low-carbon meals.
- Blockchain-enabled supply chain tracing:Distributed ledger systems allow real-time carbon attribution from farm to fork, reducing audit costs and accelerating label certification.
- Germany:Retailer-led carbon scoring systems have achieved consumer recognition levels that drive measurable purchase preference shifts toward labeled products.
Market Restraints
- Lifecycle assessment tooling costs:ISO-compliant carbon accounting requires specialized software and third-party verification, creating fixed cost barriers for smaller manufacturers.
- Ingredient supply concentration:Low-carbon protein alternatives remain concentrated among a limited set of North American and European suppliers, creating input bottlenecks.
- EFSA environmental claim constraints:Strict guidelines on how carbon reductions can be communicated on-pack limit marketing differentiation and consumer education effectiveness.
Strategic Opportunities
- Frozen entree category expansion:Cold-chain energy intensity innovations are opening margin space in the fastest-growing product format for carbon-labeled meals.
- Direct-to-institutional channels:Corporate cafeterias and university foodservice operations are consolidating procurement around carbon-transparent suppliers.
- Farm to Fork Strategy harmonization:Pending mutual recognition agreements between national carbon labeling schemes could reduce multi-jurisdiction compliance duplication costs.
Industry Challenges
- Lifecycle assessment specialist shortage:Qualified carbon accountants and ISO 14044 auditors command premium compensation, constraining certification throughput.
- Legacy ERP integration friction:Existing enterprise systems lack native carbon data fields, requiring expensive middleware development for supply chain emissions tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Labeled Packaged Meal Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat Meals, Frozen Entrees, Snack Packs, Beverage Combos Packaging Type: Plastic Containers, Paperboard Boxes, Biodegradable Films, Glass Jars Application: Weight Management, Diabetic Care, Sports Nutrition, Elderly Nutrition Customer Type: Health Enthusiasts, Busy Professionals, Students, Outdoor Enthusiasts |
| Companies Covered | Nestlé, Unilever, Danone, PepsiCo, Mondelez International, The Kraft Heinz Company, General Mills, HelloFresh, Quorn Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Labeled Packaged Meal Market Trends and Innovations
Digital verification infrastructure and cold-chain engineering are converging to transform how carbon accountability gets embedded into packaged food production. These developments are compressing certification timelines while expanding the addressable market for climate-transparent meals.
Blockchain-based supply chain tracing is rendering obsolete paper-based audit trails and static annual carbon disclosures. Mid-sized meal manufacturers in the Benelux region are piloting these systems at scale, attracted by real-time emissions dashboards that satisfy both procurement teams and regulators. The structural consequence is a collapse in third-party verification costs that previously locked smaller players out of carbon labeling.
CSRD disclosure mandates are extending carbon reporting obligations deep into food sector value chains. Large EU-domiciled food retailers must now scope 3 emissions from suppliers, creating downstream pressure for standardized product-level carbon data. Frozen entree suppliers face the steepest compliance ramps given their complex multi-ingredient supply chains and energy-intensive processing requirements.
Corporate foodservice buyers are consolidating supplier rosters around vendors with third-party carbon certification. This procurement concentration is displacing fragmented spot-buying of unlabeled meal alternatives in institutional channels. German and French corporate campus contracts now specify maximum CO2-equivalent thresholds per serving, with penalties for non-compliance.
Carbon Labeled Packaged Meal Market Segmentation
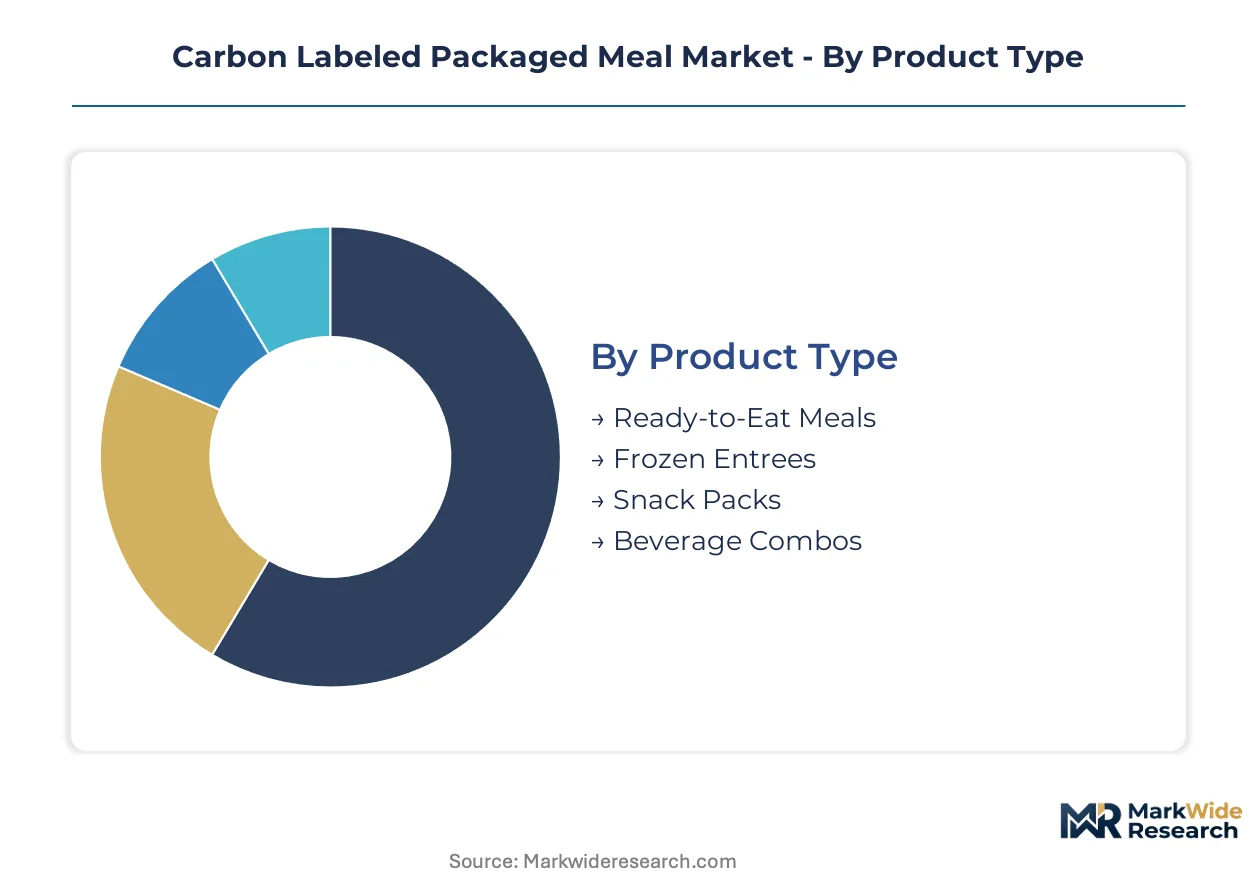
Carbon labeling requirements vary sharply across product formats and use cases, forcing manufacturers to prioritize segments where certification costs can be recovered through measurable price premiums. Procurement teams in institutional channels now specify carbon transparency thresholds by segment, reshaping production allocation decisions.
Product Type:
Ready-to-eat formats span shelf-stable to refrigerated applications, each presenting distinct lifecycle assessment complexity and cold-chain energy trade-offs.
- Ready-to-Eat Meals:Shelf-stable formats with retort processing simplify carbon accounting through reduced refrigeration dependency. German retailers prioritize these for carbon scoring pilot programs due to supply chain traceability advantages.
- Frozen Entrees:Cold-chain innovations reduce refrigeration energy intensity per unit, opening margin expansion despite higher processing emissions. French corporate campus contracts specify maximum CO2 thresholds that favor these formats for bulk procurement.
- Snack Packs:Portion-controlled configurations with simplified ingredient matrices enable faster ISO 14044 certification cycles.
- Beverage Combos:Liquid-plus-solid pairings introduce packaging complexity that complicates per-serving carbon attribution.
Established volume favors Ready-to-Eat Meals; emerging adoption favors Frozen Entrees.
Packaging Type:
Material selection directly governs Scope 3 emissions attribution and EFSA-compliant on-pack claim permissibility.
- Plastic Containers:Virgin polymer formats face carbon border adjustment exposure under EU Green Deal mechanisms. Dutch meal manufacturers are pivoting toward recycled-content specifications to maintain export eligibility.
- Paperboard Boxes:Fiber-based formats with FSC chain-of-custody documentation command procurement preference from sustainability-led buyers. Swedish retailer-led carbon scoring systems assign favorable ratings to these configurations.
- Biodegradable Films:Industrial-compostable specifications require separate waste stream infrastructure that fragments regional addressability.
- Glass Jars:Reusable-loop systems in Danish foodservice channels offset higher transport emissions through return logistics.
Procurement weighting favors Paperboard Boxes; regulatory pressure is accelerating Biodegradable Films.
Application:
Clinical and performance nutrition segments impose distinct carbon transparency standards tied to reimbursement and sponsorship frameworks.
- Weight Management:Portion-calibrated meals with protein-forward macronutrient profiles attract carbon labeling from wellness-focused retailers. UK pharmacy chains now stock certified options alongside conventional dietetic products.
- Diabetic Care:Glycemic-controlled formulations with complex carbohydrate sourcing require granular ingredient-level carbon tracking. Italian hospital foodservice tenders increasingly specify ISO-compliant lifecycle data.
- Sports Nutrition:High-protein density drives ingredient sourcing concentration that amplifies Scope 3 exposure.
- Elderly Nutrition:Texture-modified formats with specialized processing energy requirements complicate per-serving emission calculations.
Retail shelf space favors Weight Management; institutional contract growth favors Diabetic Care.
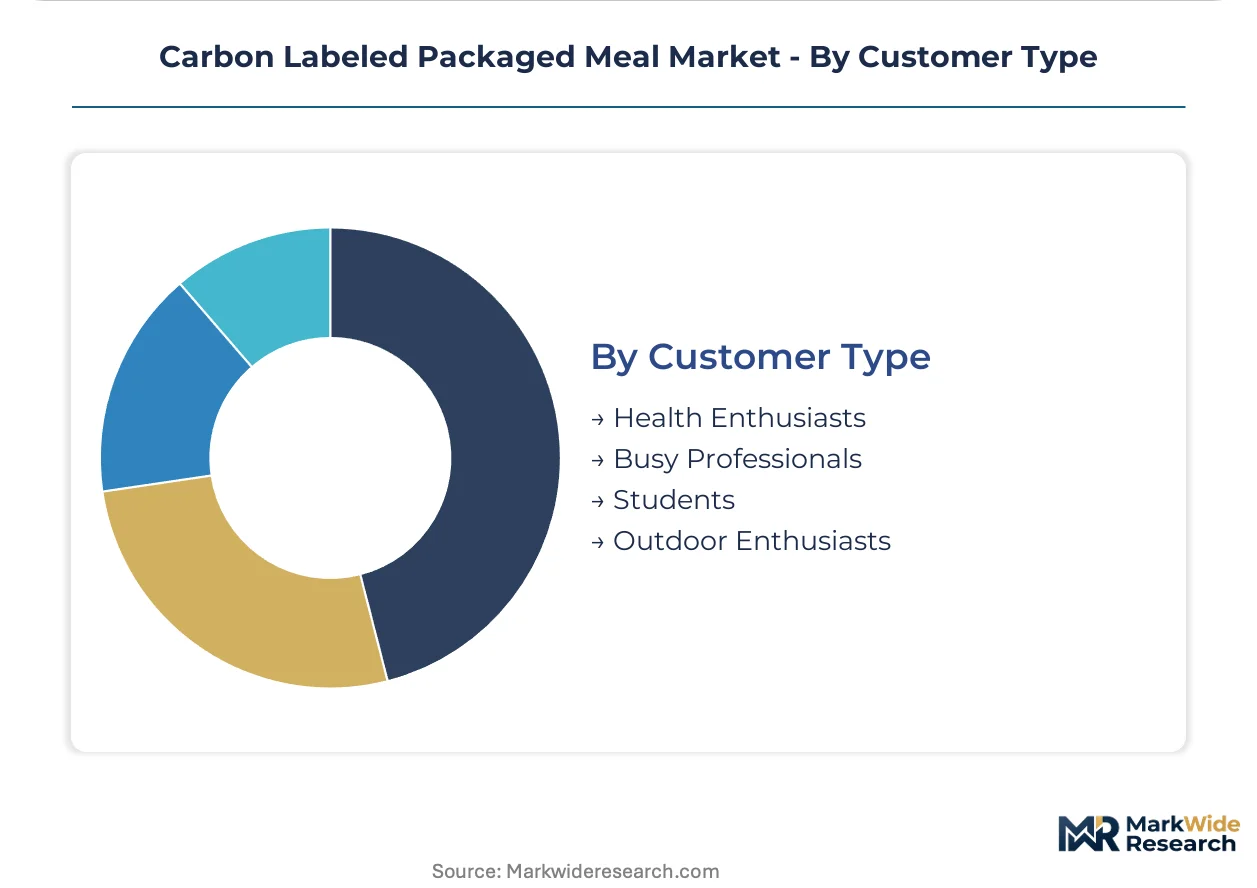
Customer Type:
Time-constrained and mobility-driven segments exhibit divergent willingness-to-pay for verified carbon transparency.
- Health Enthusiasts:Nutrition-literate buyers with established supplement purchasing patterns cross-adopt carbon-labeled meals readily. Austrian organic retail channels report strongest repeat purchase rates from this cohort.
- Busy Professionals:Subscription-oriented purchasing with delivery consolidation reduces per-meal transport emissions and supports premium pricing. Finnish corporate benefit programs now subsidize verified low-carbon meal plans.
- Students:Price-sensitive demand with limited brand loyalty constrains carbon label penetration without institutional subsidy.
- Outdoor Enthusiasts:Shelf-stable requirements align with lightweight packaging formats that complicate recycling claims.
Subscription revenue concentrates among Busy Professionals; trial conversion peaks with Health Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows between major food manufacturing hubs and EU member states are accelerating carbon labeling infrastructure investments. Germany's retailer-led scoring systems now serve as the de facto reference standard for cross-border compliance. Cold-chain logistics networks in France and the Netherlands are adapting to handle verified low-carbon frozen entrees at scale.
Germany
Retailers Rewe and Edeka have embedded carbon scores into shelf-edge labeling systems, creating consumer-facing transparency that drives measurable purchase shifts. The EU Green Deal's Farm to Fork Strategy mandates standardized disclosure that German regulators enforce through the Federal Office for Agriculture and Food. Berlin-Brandenburg hosts the densest cluster of ISO 14044 audit firms serving Central European food manufacturers.
France
Corporate campus foodservice contracts in Île-de-France now specify maximum CO2-equivalent thresholds per meal serving, with penalty clauses for non-compliance. ANSM and DGCCRF coordinate enforcement of EFSA guidelines on environmental claims across packaged food labeling. The Lyon-Grenoble corridor concentrates cold-chain engineering specialists developing energy-efficient frozen entree logistics.
Netherlands
Dutch meal manufacturers face carbon border adjustment exposure that accelerates recycled-content packaging pivots and supply chain reengineering. The Netherlands Food and Consumer Product Safety Authority integrates EU Green Deal compliance into routine food business inspections. Rotterdam's port infrastructure now offers bonded cold storage with embedded emissions tracking for re-export to German and Belgian buyers.
United Kingdom
UK pharmacy chains in London and the Southeast have begun stocking certified carbon-labeled weight management meals alongside conventional dietetic products. The Competition and Markets Authority enforces emerging greenwashing standards that constrain how manufacturers communicate carbon reductions. Cambridge-Oxford corridor startups specialize in blockchain-enabled farm-to-fork traceability systems for mid-sized meal producers.
Sweden
Swedish retailer-led carbon scoring systems assign favorable ratings to paperboard packaging configurations, influencing procurement specifications across Nordic markets. The Swedish Food Agency aligns national labeling requirements with EFSA guidelines while permitting additional climate claim flexibility. Stockholm-Uppsala clusters host lifecycle assessment software developers serving Scandinavian food manufacturers.
Carbon Labeled Packaged Meal Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with concentrated expertise in protein alternatives and packaging materials. The vendor base organizes around three functional tiers: diversified multinationals with captive supply chains, subscription-platform operators controlling last-mile logistics, and specialized protein-alternative manufacturers. Two dominant competitive moves define current positioning: backward integration into low-carbon ingredient sourcing and strategic partnerships with blockchain verification providers.
Within the diversified multinational tier, Nestlé, Unilever, and HelloFresh occupy distinct positioning archetypes. Nestlé exemplifies scale-driven supply chain control through in-house production of ingredient streams. Unilever anchors the intensive R&D expenditure model for lifecycle assessment tooling development. HelloFresh represents platform-native logistics optimization, with subscription density enabling per-delivery emission reductions that support premium positioning. Each structure reflects a different path to carbon label credibility.
| Leading Market Players |
|---|
| Nestlé |
| Unilever |
| Danone |
| PepsiCo |
| Mondelez International |
| The Kraft Heinz Company |
| General Mills |
| HelloFresh |
| Quorn Foods |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Benelux contract manufacturing facilities is compressing per-unit processing costs while simultaneously eroding supplier bargaining power against consolidated retail procurement teams. German retailer-led carbon scoring systems now dictate pricing premiums, forcing manufacturers to absorb ISO 14044 certification costs or surrender shelf space to certified competitors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium certified, standard compliant, and economy unlabeled tiers. Price differentiation rests on ISO 14044 verification grade and volume scale commitments, with subscription-based corporate foodservice contracts commanding favorable unit economics. Pricing pressure stems from EFSA environmental claim constraints that limit marketing-driven premium extraction. Students and price-sensitive retail channels exhibit highest price elasticity, while institutional procurement teams demonstrate lowest sensitivity due to mandated carbon transparency thresholds.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized cold-chain processors in the Netherlands, France, and Germany, where Rotterdam and Lyon-Grenoble corridors host energy-efficient frozen entree facilities. Raw material dependencies draw from concentrated North American and European low-carbon protein suppliers, FSC-certified fiber packaging streams, and specialized cold-chain refrigerants. Single-source vulnerability in ISO 14044 auditor availability creates certification bottlenecks. Distribution runs through retailer-controlled logistics networks and direct-to-institutional channels with embedded emissions tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate procurement team consolidation, with German and French foodservice operations consolidating supplier rosters around carbon-certified vendors and displacing fragmented spot-buying.
For Market Incumbents: Insulate market position through captive supply chain control over low-carbon ingredient streams and accelerated blockchain verification partnerships that lock in preferred vendor status. Threats from specialized protein-alternative manufacturers with superior carbon profiles require defensive certification investments in ISO 14044 lifecycle tooling. Capacity addition in Benelux cold-chain facilities preserves margin structure against transport emission penalties. For New Entrants and Emerging Players: Build out white-space presence in diabetic care institutional tenders and Swedish paperboard-packaged snack formats where certification barriers remain surmountable. The penetrable segment sits with mid-sized Dutch meal manufacturers piloting blockchain traceability at scale. A direct-to-institutional go-to-market angle bypasses retailer margin extraction and leverages corporate campus carbon threshold mandates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-platform operators with dense last-mile logistics networks and corporate benefit program integrations. Long-term viability across the analysis window favors acquisition targets with proprietary lifecycle assessment software and established auditor relationships. The signal to watch is mutual recognition progress between national carbon labeling schemes as inflection indicator for compliance cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Verification Partnership | Real-time carbon attribution collapses audit costs and accelerates ISO 14044 certification timelines for mid-tier manufacturers. |
| Cold-Chain Energy Efficiency Investment | Frozen entree margin expansion depends on Lyon-Grenoble corridor engineering innovations reducing refrigeration intensity. |
| Direct-to-Institutional Channel Development | Corporate campus procurement consolidation in Île-de-France and Berlin-Brandenburg creates preferred vendor access. |
| Backward Integration into Low-Carbon Proteins | North American and European supplier concentration risks input bottlenecks that captive sourcing mitigates. |
| Lifecycle Assessment Software Development | Specialist auditor shortages constrain certification throughput, creating first-mover advantage for automated tooling. |
Research Methodology
Initial hypotheses were tested against primary input from sustainability procurement leads at German retailers, ISO 14044 audit firm partners, corporate foodservice directors, and cold-chain logistics operators, then refined through secondary validation. Bottom-up triangulation combined Nielsen retail audit data, EU Green Deal regulatory filings, EFSA guideline documentation, and customs records tracking low-carbon ingredient trade flows. Top-down cross-checks anchored against CSRD disclosure mandates and Farm to Fork Strategy implementation timelines.
Demand-supply balance modeling across the projection horizon segmented by product format, packaging material, application use case, and customer archetype, with regional regulatory cluster overlays for EU member states. CAGRs derived from volume trajectory analysis incorporating carbon border adjustment implementation pace and blockchain verification adoption curves. Industry-specific inputs included corporate procurement team scorecard evolution and cold-chain energy efficiency improvement rates.
Stress conditions across auditor availability constraints, mutual recognition agreement delays, and low-carbon protein supply concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EFSA guideline enforcement intensity and retailer carbon scoring system expansion. Quarterly review of corporate procurement mandate adoption rates and national labeling scheme harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Morning Goods Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
Canned Mushroom Market