
 Dried Soup Market | 2026-2036
Dried Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Soup Market Intelligence
Freeze-drying technology is reshaping how dried soup products retain nutritional density and flavor integrity through sublimation-based moisture removal. Nestlé S.A. leverages its global R&D network to dominate proprietary freeze-dried formulations across European and North American retail channels. Campbell Soup Company anchors its competitive position through backward integration into vegetable dehydration facilities in California and New Jersey. Ajinomoto Co., Ltd. specializes in umami-enhanced powdered soup bases that command premium placement in Asian convenience retail.
Dried soup consists of moisture-reduced vegetable, protein, and starch components reconstituted with hot water, typically containing sodium levels between 1,500 and 2,400 milligrams per serving depending on formulation. The product serves commercial food service operations and retail consumers seeking shelf-stable meal solutions with preparation times under five minutes. Instant soup leads volume distribution through supermarkets and convenience stores where single-serve packaging drives impulse purchases. Powdered soup occupies the fastest-growing margin pool as health food stores stock reduced-sodium and organic variants targeting wellness-oriented shoppers. Freeze-dried soup remains a premium niche with concentrated demand in online retail channels where longer shelf life justifies higher unit pricing.
The FDA enforces nutrition labeling requirements and sodium reduction targets for processed foods sold in interstate commerce, directly influencing reformulation investments by domestic manufacturers. The USDA administers school meal programs that specify sodium limits and whole-grain content for food service providers supplying colleges and institutional kitchens. Stakeholders must monitor evolving clean-label certification standards and traceability requirements that will determine market access for imported ingredient suppliers and private-label entrants.
Market Dynamics
Freeze-drying technology is compressing traditional dehydration economics while FDA sodium mandates force simultaneous reformulation across legacy powdered soup portfolios.
Growth Catalysts
- USDA School Meal Standards:College cafeteria procurement now favors reduced-sodium dried soup formats that meet federal sodium limits for institutional food service contracts.
- Freeze-drying equipment advances:Sub-zero vacuum sublimation systems preserve volatile flavor compounds that hot-air dehydration destroys, enabling clean-label positioning in premium retail.
- Direct-to-consumer channel expansion:Subscription meal-kit platforms in the United States stock extended-shelf-life soup components for home assembly kits.
Market Restraints
- Vegetable input cost volatility:California drought cycles and New Jersey processing seasonality create margin pressure for captive dehydration facilities.
- Single-serve packaging waste regulations:Extended producer responsibility frameworks in multiple jurisdictions impose compliance costs on multi-layer sachet formats.
- Fresh prepared soup substitution:Refrigerated grab-and-go alternatives in convenience retail capture time-pressured consumers seeking minimal preparation.
Strategic Opportunities
- Clean-label certification tailwinds:USDA Organic and Non-GMO Project verification unlock shelf placement in health food store channels at 40-60% price premiums over conventional.
- Umami base technology convergence:Yeast extract and fermented soy peptide combinations replace monosodium glutamate in formulations targeting sodium-reduction mandates.
- Campus food service digitization:Mobile ordering platforms at US colleges integrate dried soup into automated pantry replenishment systems for residence halls.
Industry Challenges
- Reformulation R&D timelines:Salt reduction without flavor degradation requires 18-24 month sensory testing cycles that delay product launches.
- Traceability system integration:Blockchain-enabled ingredient tracking demands IT infrastructure upgrades at mid-sized dehydration processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Soup Market |
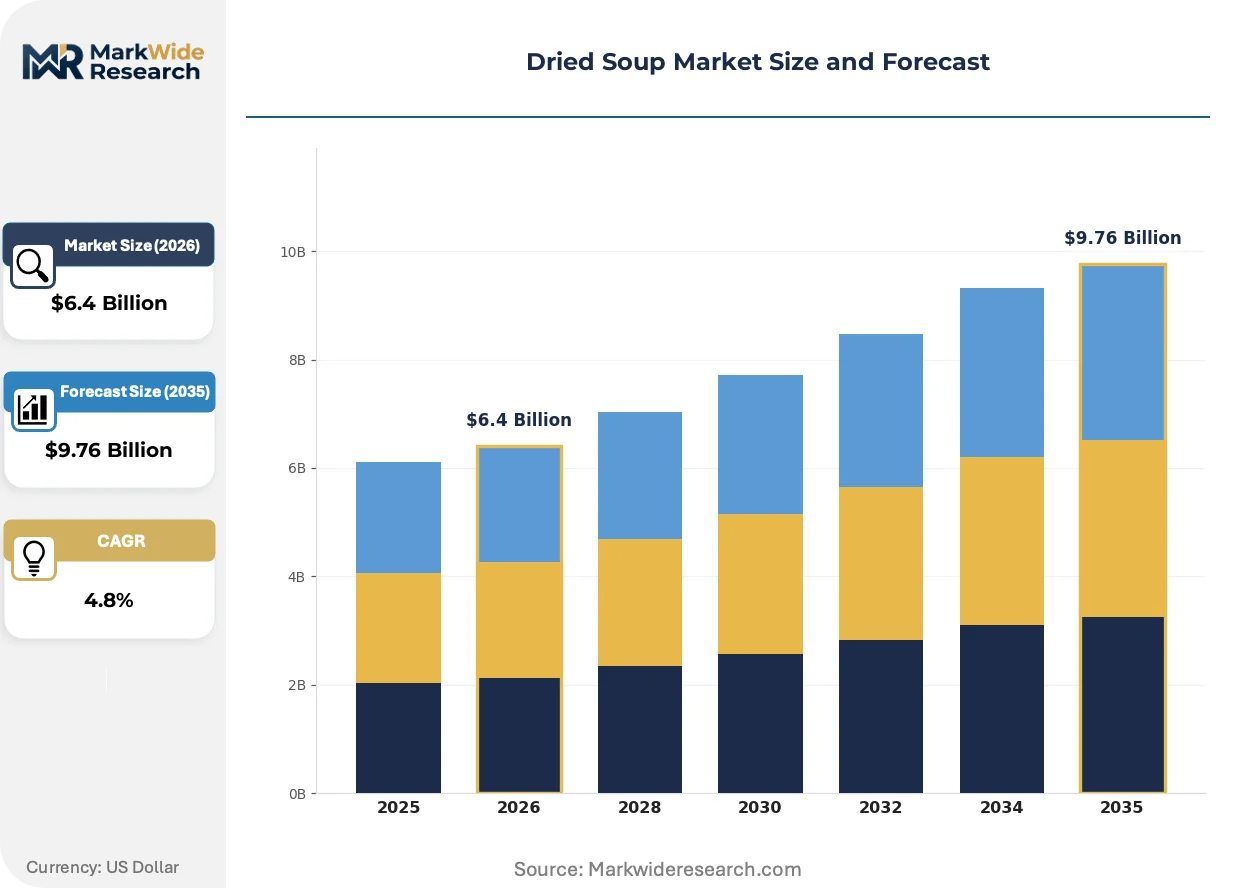
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Soup, Dehydrated Soup, Powdered Soup, Freeze-Dried Soup Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores End User: Individual Consumers, Restaurants, Food Service Providers, Colleges Flavor Profile: Vegetable, Chicken, Beef, Spicy, Others |
| Companies Covered | Campbell Soup Company, General Mills, Nestlé S.A., Baxters Food Group Limited, Ajinomoto Co., Ltd., The Kraft Heinz Company, Nissin Foods, Conagra Brands, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Soup Market Strategic Shifts & Innovations
Reformulation priorities are splitting the competitive field between legacy sodium-heavy portfolios and emerging clean-label architectures, with technology adoption rates diverging sharply by price tier.
Spray-drying technology for dairy and protein hydrolysates is migrating from infant formula applications into savory soup base production. Specialty ingredient suppliers in the United States are retrofitting existing towers for vegetable and yeast extract processing. This equipment repurposing is compressing capital barriers for mid-tier manufacturers seeking freeze-dried quality at powdered soup cost structures.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration system retrofits at European freeze-drying facilities. Industrial operators must replace hydrofluorocarbon-based cooling units with ammonia or CO2 alternatives by mandated deadlines. German and French processing plants face the steepest compliance curves, driving consolidation toward facilities with completed infrastructure upgrades.
Pantry-loading behavior among remote workers has shifted volume toward bulk canister formats and away from single-serve sachets. Club store channels in the United States are expanding private-label soup SKUs in 12-24 serving containers. This format rotation is compressing impulse-driven convenience store placements while rewarding shelf-stable stockpiling in suburban household segments.
Dried Soup Market Segmentation
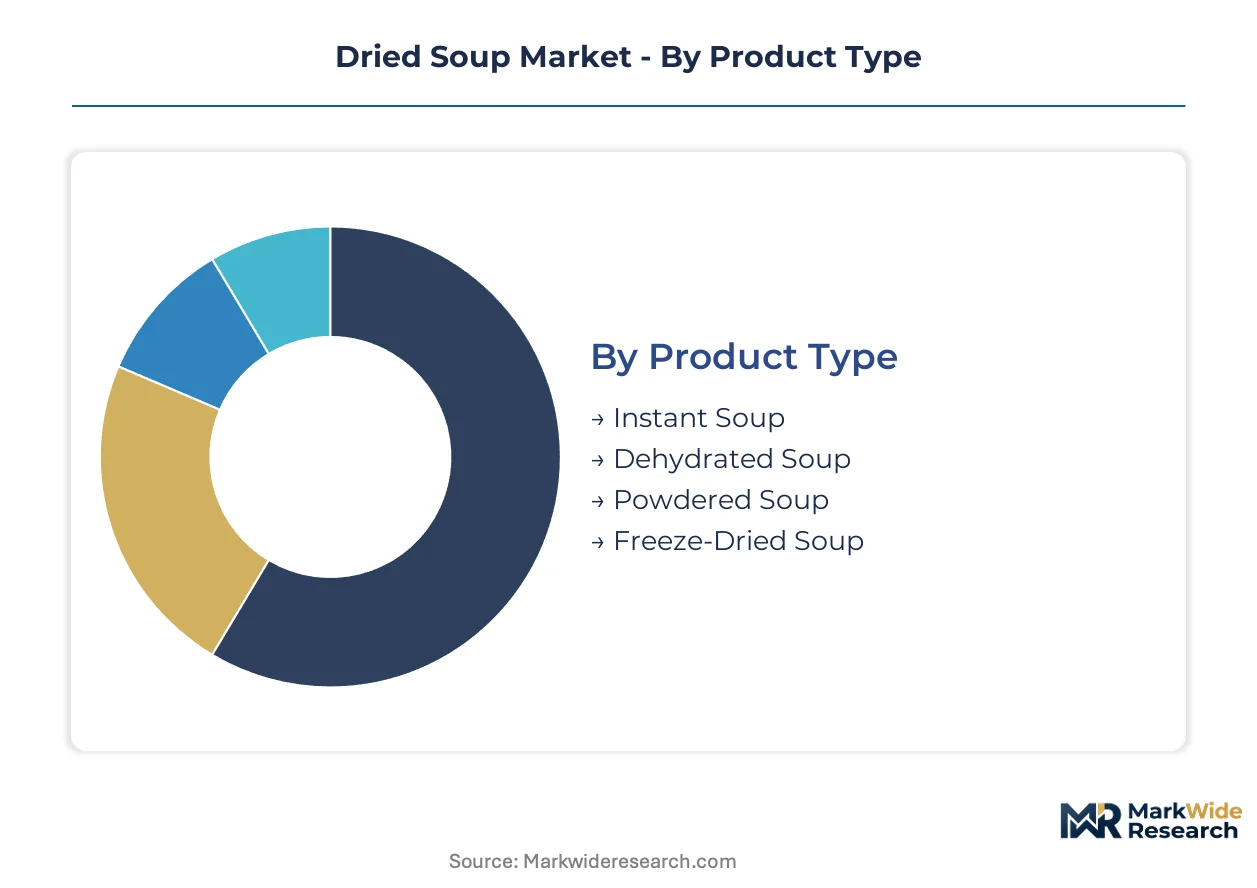
Dried soup segmentation reveals divergent margin architectures across preparation formats and channel strategies. Product type distinctions separate commodity powdered portfolios from premium freeze-dried lines, while distribution channel choices determine whether brands capture impulse volume or subscription loyalty.
Product Type:
Preparation technology spans from hot-air dehydration to sublimation-based freeze-drying, each locking in distinct flavor retention profiles and shelf-life economics.
- Instant Soup:Pre-cooked and dehydrated noodles or grains with seasoning sachets requiring boiling water activation. US college cafeterias and convenience stores concentrate procurement here, driven by sub-five-minute preparation mandates for time-pressured food service operations.
- Dehydrated Soup:Hot-air dried vegetable and protein components reconstituting in hot water with moderate sodium loads between 1,500 and 2,400 milligrams per serving. Club store channels in the United States are rotating volume toward bulk canister formats as pantry-loading behavior shifts among remote workers.
- Powdered Soup:Finely milled starch and hydrolyzed protein bases delivering the lowest unit cost per serving across all formats. Health food stores stock reduced-sodium and organic variants targeting wellness-oriented shoppers.
- Freeze-Dried Soup:Vacuum sublimation preserves volatile flavor compounds and nutritional density at premium price points justified by extended shelf life. Online retail channels concentrate demand where longer storage duration offsets higher unit pricing for disaster preparedness and outdoor recreation segments.
The dominant share belongs to Instant Soup, while Freeze-Dried Soup is closing the gap fastest.
Distribution Channel:
Channel selection determines packaging format requirements and margin capture potential, with digital infrastructure investments separating growth trajectories.
- Supermarkets:Mass-market retail commanding the highest absolute volume through multi-SKU shelf sets and promotional discounting cycles. Impulse placement at aisle end-caps drives trial conversion for new flavor launches.
- Online Retail:Subscription meal-kit platforms and direct-to-consumer brands leverage extended shelf-life claims for home assembly kit components. Mobile ordering integration at US colleges is embedding dried soup into automated pantry replenishment systems.
- Convenience Stores:Single-serve sachet formats dominate grab-and-go positioning where time-pressured consumers seek immediate consumption solutions. Extended producer responsibility frameworks in multiple jurisdictions are imposing compliance costs on multi-layer packaging waste.
- Health Food Stores:Clean-label certification requirements including USDA Organic and Non-GMO Project verification unlock shelf placement at 40-60% price premiums over conventional alternatives. Wellness-oriented shoppers drive repeat purchase of reduced-sodium formulations.
Supermarkets maintain volume leadership, though Online Retail is expanding most quickly through subscription model penetration.
End User:
Customer type segmentation separates household consumption from institutional procurement with divergent specification requirements and contract structures.
- Individual Consumers:Household purchasers selecting formats based on preparation time constraints and storage space limitations. Pantry-loading behavior has shifted volume toward bulk canister formats and away from single-serve sachets.
- Restaurants:Commercial kitchens utilizing dried soup bases for sauce preparation and batch cooking efficiency. Backward integration into vegetable dehydration facilities supports supply security for high-volume operators.
- Food Service Providers:Institutional contractors managing college cafeterias and corporate dining facilities with federal sodium compliance mandates. USDA school meal standards specify sodium limits and whole-grain content for contract eligibility.
- Colleges:Campus food service programs representing a growing institutional buyer segment with mobile ordering platform integration. Federal procurement guidelines favor reduced-sodium dried soup formats meeting institutional nutrition requirements.
Individual Consumers command the largest addressable base, while Colleges are gaining share fastest through digitized procurement expansion.
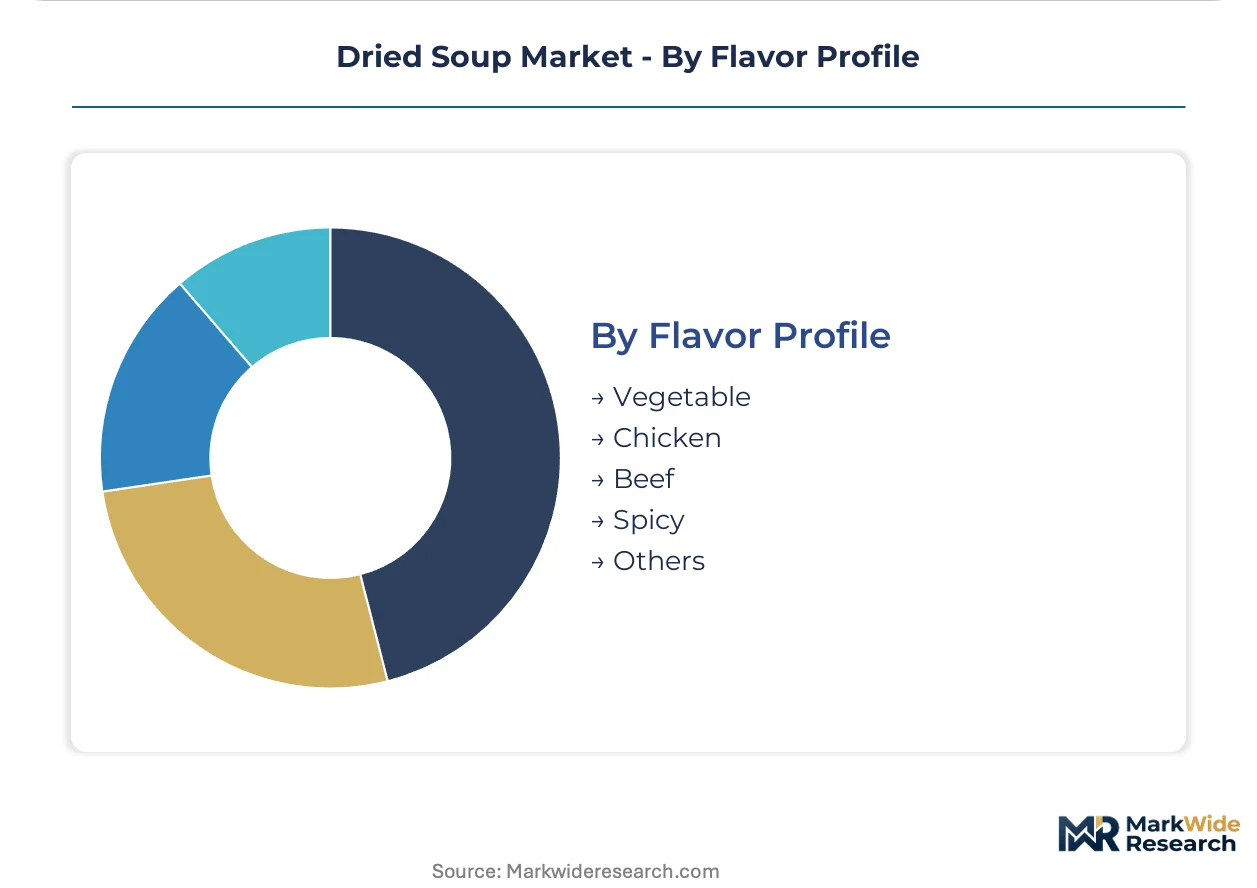
Flavor Profile:
Taste segmentation reflects protein source economics and regional preference variation, with umami enhancement technologies enabling sodium reduction without flavor degradation.
- Vegetable:Dehydrated tomato, mushroom, and legume bases appealing to plant-forward dietary trends. California and New Jersey processing seasonality creates input cost volatility for captive dehydration facilities.
- Chicken:Poultry-derived protein hydrolysates and fat encapsulation for mouthfeel replication. Spray-drying technology migration from infant formula applications is compressing capital barriers for mid-tier manufacturers.
- Beef:Red meat flavor systems utilizing yeast extract and fermented soy peptide combinations to replace monosodium glutamate in sodium-reduction formulations. Yeast extract suppliers command premium placement in reformulation pipelines.
- Spicy:Capsicum and pepper extract formulations targeting younger demographic trial and ethnic cuisine authenticity claims. Asian convenience retail channels concentrate demand for heat-forward positioning.
- Others:Seafood, curry, and regional specialty profiles occupying niche placement in ethnic grocery and international food service segments. Traceability requirements for imported ingredient suppliers determine market access.
Vegetable formulations hold the leading position, though Spicy variants are climbing the fastest on younger consumer preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
College cafeterias and campus food service programs concentrate procurement power in the United States, while private-label expansion and direct-to-consumer channels reshape retail dynamics across developed markets.
United States
US college cafeterias and institutional food service programs drive demand for reduced-sodium dried soup formats meeting USDA sodium limits. The FDA enforces updated nutrition labeling requirements and sodium reduction targets for processed foods sold in interstate commerce. California and New Jersey host captive vegetable dehydration facilities serving backward-integrated manufacturers.
Germany
German freeze-drying facilities face steep EU F-Gas Regulation compliance curves requiring hydrofluorocarbon cooling unit replacement with ammonia or CO2 alternatives. The EU Green Deal accelerates refrigeration system retrofits at processing plants. Bavarian and North Rhine-Westphalian facilities consolidate toward operators with completed infrastructure upgrades.
Japan
Japanese convenience retail channels concentrate demand for umami-enhanced powdered soup bases commanding premium placement. METI oversees industrial energy efficiency standards affecting dehydration equipment investments. Tokyo-Osaka corridor processors specialize in yeast extract and fermented soy peptide formulations replacing monosodium glutamate.
United Kingdom
UK health food stores stock clean-label certified variants at 40-60% price premiums over conventional alternatives, driven by wellness-oriented shopper demand. The Food Standards Agency monitors sodium content claims and labeling compliance. London and Southeast England clusters host subscription meal-kit platforms integrating extended-shelf-life soup components.
France
French freeze-drying plants confront EU F-Gas phase-down deadlines driving consolidation toward upgraded facilities. EFSA guidelines influence clean-label certification requirements for organic and non-GMO positioning. Auvergne-Rhône-Alpes processing centers leverage sublimation technology for premium flavor retention in savory applications.
Dried Soup Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The structure fragments between mass-market retail dominators and niche premium operators, with mid-tier manufacturers consolidating through equipment repurposing. Three archetypes prevail: multinational CPG conglomerates with captive dehydration networks, umami-technology specialists leveraging Asian fermentation expertise, and private-label suppliers riding club-store expansion. Competitive moves center on backward integration into vegetable processing and freeze-drying equipment upgrades for clean-label positioning.
Within the multinational tier, Nestlé S.A. and Campbell Soup Company anchor distinct strategic positions, while Ajinomoto Co., Ltd. exemplifies the umami-specialist archetype. Nestlé leverages global R&D infrastructure across European and North American retail channels. Campbell anchors competitive position through captive dehydration facilities in California and New Jersey. Ajinomoto occupies the premium convenience retail channel with fermented flavor systems. These three represent the dominant competitive vectors: scale-driven global distribution, backward-integrated supply security, and technology-led premium positioning.
| Leading Market Players |
|---|
| Campbell Soup Company |
| General Mills |
| Nestlé S.A. |
| Baxters Food Group Limited |
| Ajinomoto Co., Ltd. |
| The Kraft Heinz Company |
| Nissin Foods |
| Conagra Brands |
| Unilever |
| Others |
Cost & Logistics Intelligence
California drought cycles tethered to New Jersey processing seasonality compress margin buffers for captive dehydration facilities while simultaneously forcing three-tier pricing stratification across premium freeze-dried, standard powdered, and economy instant formats. This input volatility determines both the spread between contract and spot procurement and the geographic clustering of backward-integrated manufacturers seeking supply security.
Pricing Analysis
Cost-plus contracts with vegetable commodity indexation dominate institutional procurement agreements serving USDA-compliant college cafeterias and campus food service programs. Price differentiation hinges on clean-label certification tier and volume scale, with USDA Organic and Non-GMO Project verification commanding 40-60% premiums over conventional alternatives. Cost compression in the economy instant tier is intensifying because private-label expansion at club stores erodes branded shelf space. Individual consumers in health food channels exhibit lowest price sensitivity, while mass-market supermarket shoppers and institutional food service contractors face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and imported yeast extract suppliers dominates supply chain risk matrices for umami-base reformulation pipelines. Geographic concentration centers on California and New Jersey for vegetable dehydration, Japan for fermented soy peptide and yeast extract technology, and Germany for freeze-drying equipment manufacturing. Raw material dependencies draw from drought-vulnerable vegetable inputs, hydrolyzed protein bases, and specialized fermentation cultures. Single-source vulnerability runs through Asian umami ingredient suppliers as FDA sodium mandates accelerate reformulation demand. Distribution runs through supermarket multi-SKU shelf sets, subscription meal-kit platforms, and digitized campus pantry replenishment systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying equipment mastery and clean-label certification infrastructure represent the scarcest capabilities in a market splitting between legacy sodium-heavy portfolios and reformulation-ready architectures. Manufacturers without captive sublimation technology or USDA Organic verification access face structural exclusion from the fastest-growing margin pools.
For Market Incumbents: Insulate market position by accelerating backward integration into California and New Jersey vegetable dehydration facilities to secure input supply against drought-driven volatility. Prioritize freeze-drying equipment upgrades at European plants ahead of EU F-Gas Regulation phase-down deadlines. Defend against private-label encroachment by locking exclusive clean-label certification partnerships with health food store channels. For New Entrants and Emerging Players: Mid-tier powdered soup manufacturers in the United States represent the most penetrable entry point for equipment repurposing strategies that deliver freeze-dried quality at conventional cost structures. Campus food service digitization contracts with mobile ordering integration offer a second white-space target with lower competitive density than supermarket channels. A go-to-market angle anchored to umami-base technology convergence—yeast extract and fermented soy peptide combinations—sidesteps entrenched MSG-dependent incumbents while meeting FDA sodium reduction mandates. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors acquisition targets with completed freeze-drying infrastructure upgrades and established clean-label certification pipelines. Long-term viability over the next decade hinges on reformulation-ready manufacturing footprints rather than legacy sodium-heavy asset bases. The signal to watch is EU F-Gas Regulation compliance completion rates among European processing facilities, which will determine which assets command premium valuations versus stranded-equipment discounts.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Equipment Upgrade | EU F-Gas Regulation deadlines force ammonia or CO2 cooling retrofits at German and French facilities. |
| Backward Integration into Vegetable Dehydration | Captive California and New Jersey processing secures supply against drought-driven input cost spikes. |
| Clean-Label Certification Investment | USDA Organic and Non-GMO Project verification unlocks health food store placement at premium pricing. |
| Umami-Base Technology Convergence | Yeast extract and fermented soy peptide combinations replace MSG while meeting FDA sodium mandates. |
| Campus Food Service Digitization | Mobile ordering platform integration embeds dried soup into automated college pantry replenishment systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA sodium reduction guidance documents, USDA school meal program procurement specifications, and trade data on vegetable dehydration equipment imports. Primary interviews engaged R&D directors at multinational CPG conglomerates, procurement managers at US college food service contractors, and technical sales leads at freeze-drying equipment manufacturers. Secondary validation drew from SEC filings of publicly traded soup manufacturers, EU F-Gas Regulation implementation tracking databases, and health food store channel audit data. Bottom-up volume modeling triangulated against top-down category spend analysis.
Forecast inputs span product type segmentation across instant, dehydrated, powdered, and freeze-dried formats; distribution channel dynamics covering supermarkets, online retail, convenience stores, and health food stores; and end-user categories including individual consumers, restaurants, food service providers, and colleges. CAGRs were derived from trend extrapolation of historical volume patterns adjusted for regulatory mandate timelines and technology adoption curves. Industry-specific forecast inputs incorporate FDA sodium reduction compliance deadlines and EU F-Gas Regulation phase-down schedules across the analysis window.
Practitioners should monitor California drought severity indices, EU refrigeration retrofit completion rates, and private-label expansion velocity at club store channels for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
North America Pasta Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Freekeh Market
Packaged Foods
Dried Honey Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Packaged Food Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Fruit Filling Market
Packaged Foods
North America Breakfast Cereals Market