
 Canned Fruits Market | 2026-2036
Canned Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Fruits Market Analysis
Buyer concentration among large-format retail and food service procurement groups is hardening across North America and Western Europe. Del Monte Foods leverages its integrated plantation-to-can supply chain to secure long-term contracts with major grocery banners. Bonduelle sustains its competitive edge through specialized organic and conventional product lines tailored to European retail specifications. Seneca Foods anchors its position by controlling substantial domestic fruit sourcing volumes and maintaining cost discipline across its Midwest processing footprint.
Canned fruits comprise thermally processed whole, sliced, or chunked fruit preserved in hermetically sealed metal, glass, or flexible containers with syrup, juice, or water, achieving commercial sterility through retort processing at temperatures exceeding 100°C to eliminate spoilage microorganisms and enzymes. The primary purpose is to deliver shelf-stable, year-round fruit availability independent of harvest cycles and refrigerated distribution infrastructure. Pineapple and mixed fruit segments dominate volume flows due to their versatility across retail baking and food service dessert applications, while pouch and Tetra Pack formats are gaining fastest among convenience-oriented urban consumers seeking lighter, recyclable packaging. Grade A and organic categories command concentrated margin pools as premium private-label and branded lines expand in affluent metro markets.
The FDA enforces low-acid canned food regulations under 21 CFR Parts 108, 113, and 114, mandating thermal process filing, scheduled process controls, and container closure inspections that shape manufacturing investment and product safety liability for US market access. The EU Green Deal and F-Gas Regulation are accelerating processor migration from energy-intensive frozen chains toward ambient-stable canned formats, while REACH and CE marking requirements govern material contact substances and packaging machinery compliance across European trade. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return schemes that will reshape packaging cost structures and format selection across major demand centers.
Market Dynamics
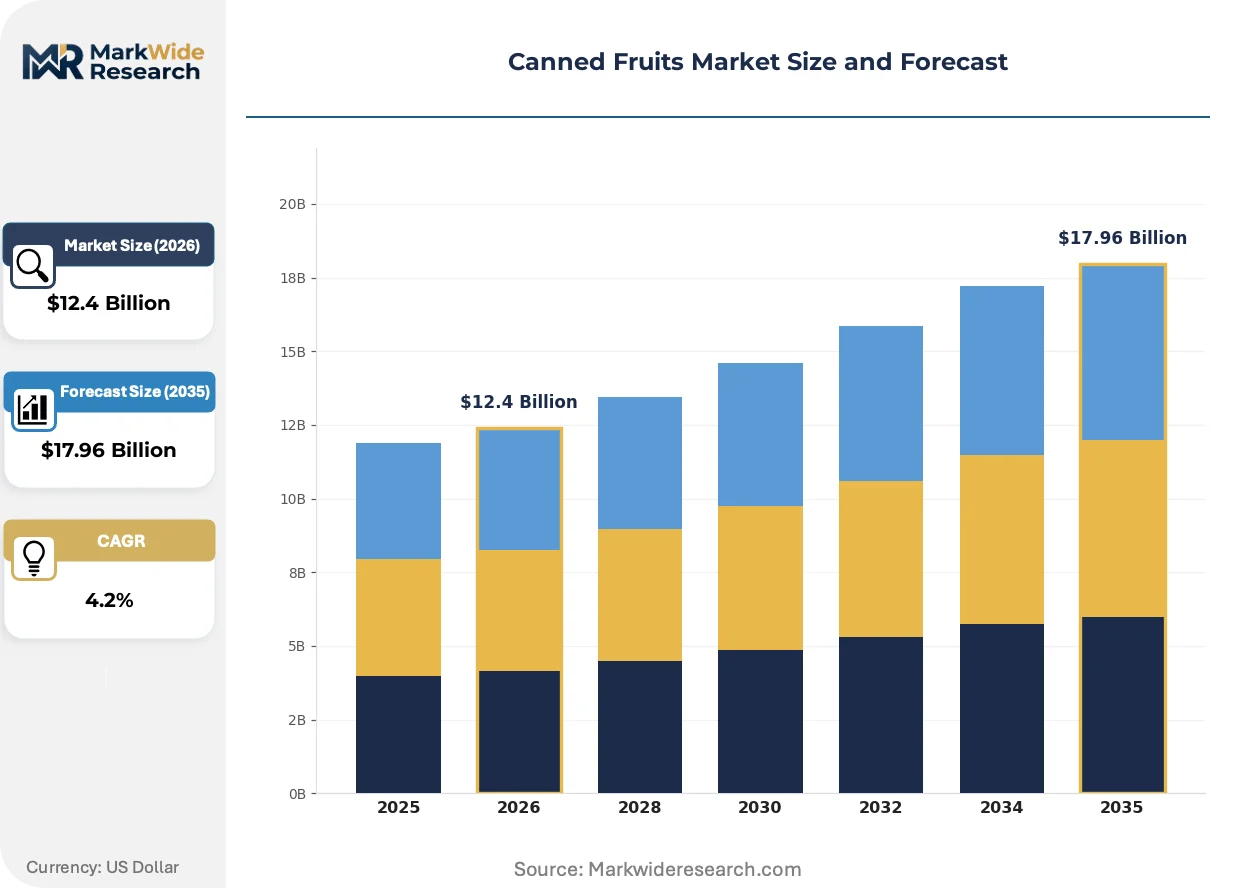
Supermarket procurement consolidation and the EU F-Gas Regulation are compressing processor margins while accelerating format migration toward shelf-stable ambient products that bypass refrigerated distribution entirely.
Growth Catalysts
- EU Green Deal cold-chain restrictions:The EU F-Gas Regulation is forcing frozen fruit processors toward retort-sterilized canned formats to eliminate hydrofluorocarbon-dependent refrigeration.
- Southeast Asian urbanization:Metro consumers in Indonesia, Vietnam, and the Philippines are substituting fresh fruit with packaged convenience formats as refrigerated retail infrastructure remains limited.
- Retort pouch technology:Flexible laminate pouches with modified atmosphere capabilities are displacing rigid metal cans in food service portion-control applications.
Market Restraints
- Tinplate volatility:Steel input costs and coating material supply uncertainty from Chinese mills are destabilizing metal can economics.
- Thailand pineapple concentration:Over 60% of global canned pineapple raw material flows through Thai processing clusters, creating weather and labor disruption exposure.
- Frozen fruit substitution:Quick-freeze technology improvements and cold-chain expansion in developed markets are eroding canned fruit's price advantage in institutional baking.
Strategic Opportunities
- Organic certification expansion:EU organic label requirements and USDA National Organic Program standards are opening premium shelf-space allocations in German and US natural retail banners.
- Aseptic carton formats:Tetra Pak ambient technology is penetrating Southeast Asian convenience stores where refrigeration is unreliable and lightweight transport matters.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz and France's AGEC law are mandating recyclable packaging, favoring aluminum and glass over multi-layer laminates.
Industry Challenges
- Thermal process validation:FDA 21 CFR Part 113 filing requirements and scheduled process documentation are extending new product launch timelines by 8-14 months.
- Retort operator skill scarcity:Qualified thermal processing technicians capable of managing continuous rotary sterilizer systems are concentrated in aging Midwest and Mediterranean workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Fruits Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $17.96 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pineapple, Peaches, Pears, Mixed Fruits Packaging Type: Cans, Jars, Pouches, Tetra Packs End User: Retail, Food Service, Exporters, Manufacturers Quality Grade: Grade A, Grade B, Organic, Conventional |
| Companies Covered | Seneca Foods, Bonduelle, Del Monte Foods, Fresh Del Monte Produce, B&G Foods, Dole Food Company, Conagra Brands, Princes Foods, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Fruits Market Emerging Trajectories
Format lightweighting and regulatory pressure on cold-chain emissions are converging to reshape material selection and processing investment priorities across the value chain.
Pouch packaging with high-barrier metallized films is overtaking traditional three-piece steel cans in single-serve and food service applications. Urban convenience retailers in Tokyo, Seoul, and Singapore are expanding ambient pouch facings by 40% annually. This shift is compressing metal can demand in portions below 200 grams while opening new export logistics configurations for Southeast Asian processors.
REACH substance restrictions on bisphenol-A epoxy coatings are forcing European can makers toward polyester and acrylic liner alternatives. ECHA authorization timelines are extending material qualification cycles to 18-24 months. Fruit processors serving German and French retail banners are accelerating non-BPA line certifications to maintain shelf access.
Direct-store-delivery bypass of traditional wholesale distributors is concentrating procurement leverage with large-format retail banners. Walmart and Carrefour are consolidating canned fruit category management through centralized private-label development. This pattern is most visible in North American and Western European markets where banner consolidation has reduced viable sales channels by half since 2018.
Canned Fruits Market Segmentation
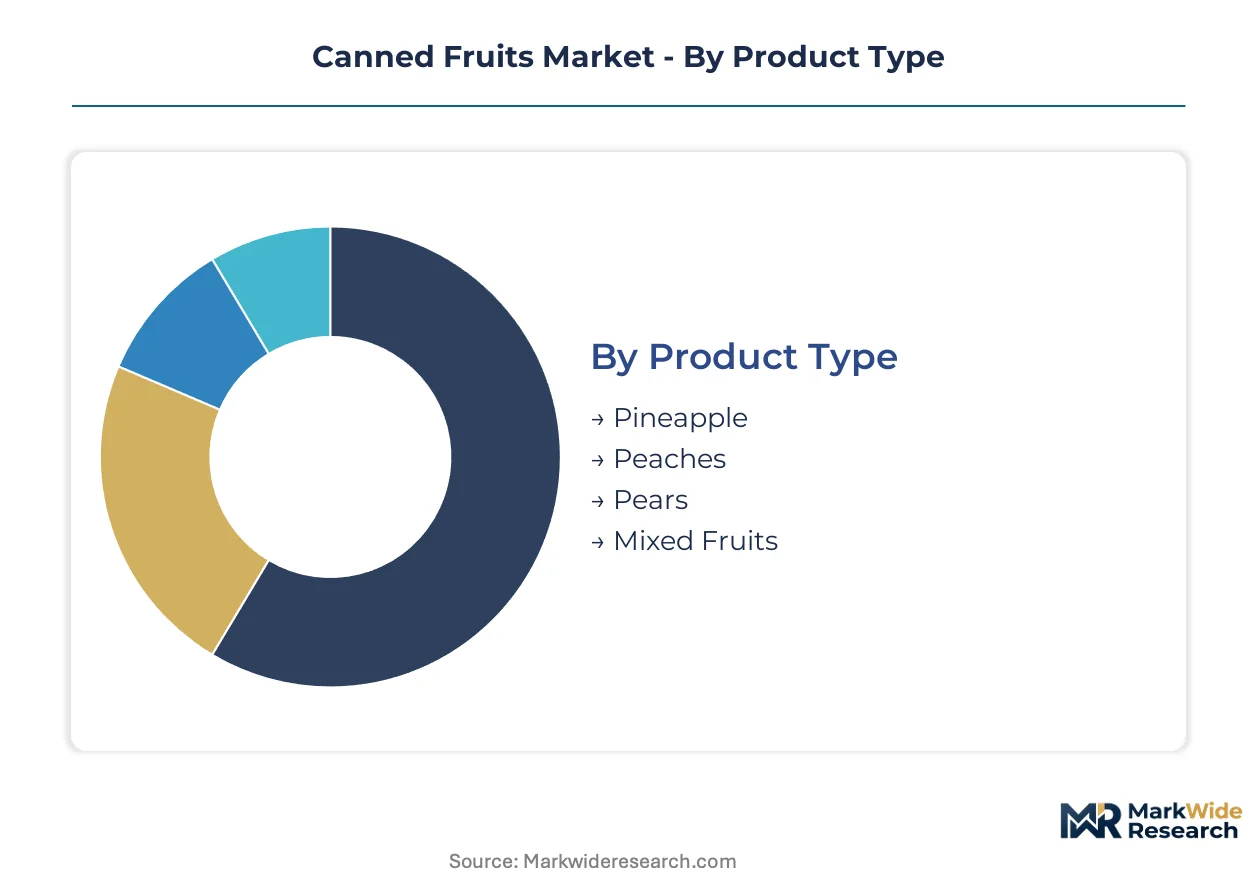
Segmentation in canned fruits reveals how processing economics and distribution constraints allocate margin pools across format and quality tiers. Understanding these divisions exposes where procurement leverage concentrates and which specifications command premium shelf positioning.
Product Type:
Standalone fruit varieties serve distinct end-use applications with embedded mixed formats penetrating multi-purpose channels.
- Pineapple:Tropical acid fruit processed in rings, chunks, and crushed forms for retail baking and food service dessert applications. Thai and Indonesian canneries dominate raw material flows, with Metro Manila and Ho Chi Minh City retail banners expanding facings for ambient dessert ingredients.
- Mixed Fruits:Blended combinations of peaches, pears, grapes, and cherries packed in syrup or juice media. German and French retail private-label programs are concentrating procurement around standardized fruit cocktail specifications for institutional catering contracts.
- Peaches:Clingstone and freestone varieties processed halves and slices. California and Greek canneries anchor supply for US and EU retail channels respectively.
- Pears:Bartlett and d'Anjou cultivars packed in light syrup or water. Pacific Northwest processors control domestic US sourcing volumes.
Volume placements concentrate in Pineapple; the faster expansion belongs to Mixed Fruits.
Packaging Type:
Format selection maps directly to cold-chain availability and retail infrastructure density across target markets.
- Cans:Three-piece steel and two-piece drawn containers with epoxy or polyester linings achieving commercial sterility through retort processing. Tinplate cost volatility from Chinese mill supply uncertainty is compressing margin structures for standard-format retail SKUs.
- Pouches:High-barrier metallized laminate retort pouches with spout or tear-notch features. Tokyo, Seoul, and Singapore convenience retailers are expanding ambient pouch facings by substantial annual increments for single-serve urban consumption.
- Jars:Wide-mouth glass containers with vacuum-sealed metal closures. German Verpackungsgesetz recyclability mandates are favoring glass return schemes over multi-layer alternatives.
- Tetra Packs:Aseptic carton technology with aluminum foil barrier layers. Indonesian and Vietnamese distributors are adopting lightweight carton formats where refrigerated logistics remain unreliable.
Metal can volumes dominate current throughput; pouch formats are climbing the fastest.
End User:
Channel concentration determines specification stringency and contract structure across the value chain.
- Retail:Supermarket and hypermarket banners with centralized category management and private-label development programs. Walmart and Carrefour procurement consolidation has halved viable sales channels since 2018.
- Food Service:Institutional bakeries, dessert manufacturers, and hospitality procurement groups. Portion-control pouch specifications are displacing institutional-size cans in commercial kitchen applications.
- Exporters:Cross-border traders serving developing markets with limited cold-chain infrastructure. Southeast Asian re-export hubs are consolidating regional distribution leverage.
- Manufacturers:Industrial users incorporating canned fruit into yogurt, ice cream, and pastry formulations. Grade A specifications with defined Brix and texture standards command dedicated supply contracts.
Procurement leverage pools in Retail; Food Service specifications are expanding most quickly.
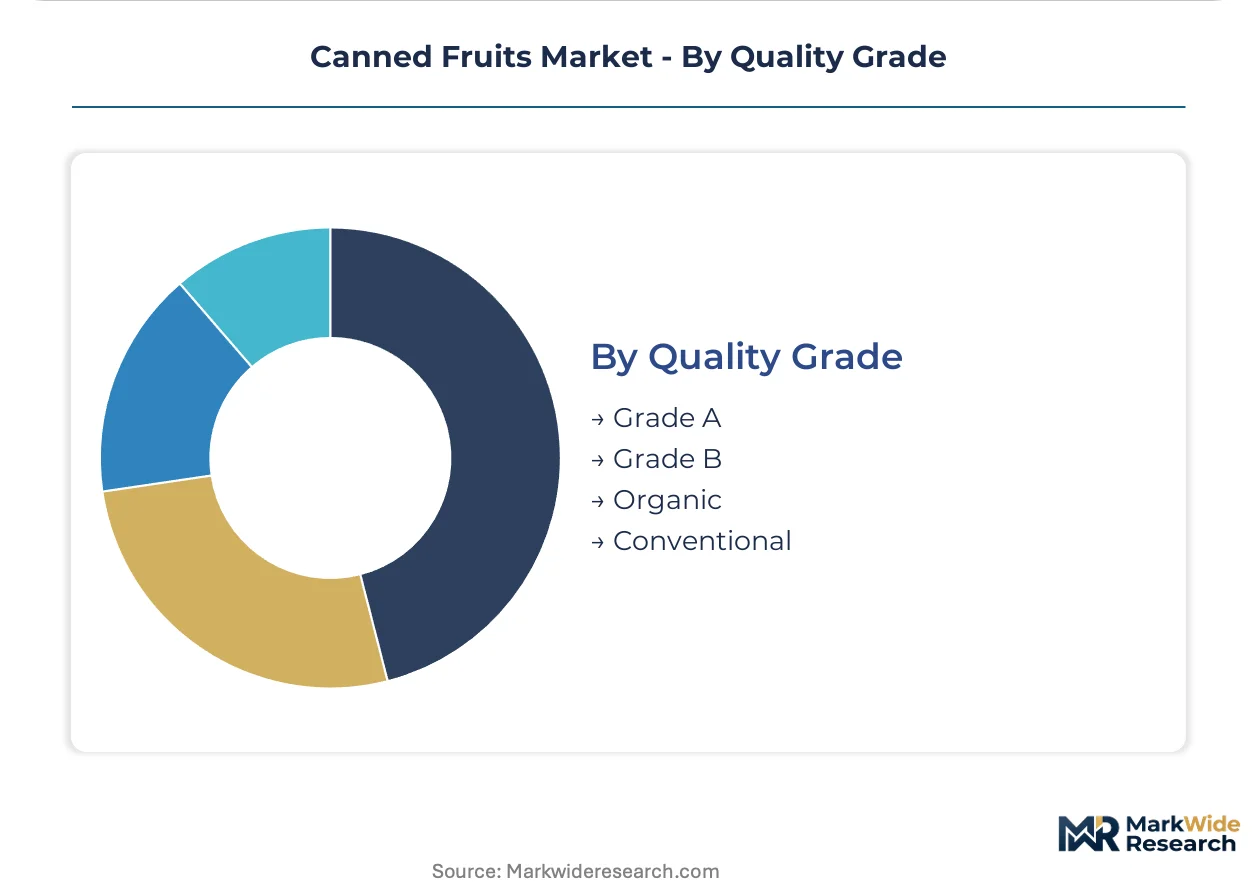
Quality Grade:
Certification tiers separate commodity volume from premium margin capture across regulatory jurisdictions.
- Grade A:Uniform size, color, and defect specifications meeting USDA or EU commercial standards. German and US natural retail banners are allocating expanded shelf space to premium-grade private-label lines.
- Organic:Cultivation and processing certified under USDA National Organic Program or EU organic label requirements. EU regulation 2018/848 implementation is tightening conversion period and input restrictions for imported organic fruit.
- Grade B:Processed fruit with size variation and minor blemish tolerance. Industrial manufacturers and institutional food service channels absorb this tier for cost-sensitive applications.
- Conventional:Standard cultivation with synthetic input protocols and conventional thermal processing. Volume concentration in Southeast Asian retail channels where price positioning dominates purchase decisions.
Grade A specifications anchor current revenue; organic certification is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai pineapple plantations anchor the raw-material base for global canned fruit flows, with processing clusters concentrated in Prachuap Khiri Khan and Rayong provinces. Metro Manila, Ho Chi Minh City, and Jakarta retail banners are expanding ambient fruit facings as refrigerated infrastructure remains patchy.
United States
California clingstone peach orchards and Pacific Northwest pear growers supply domestic canneries with Grade A raw material. FDA 21 CFR Part 113 thermal process filings govern retort operations across Midwest processing plants. Seneca Foods controls substantial sourcing volumes from its Geneva, New York headquarters while maintaining cost discipline across Illinois and Minnesota facilities.
Germany
Verpackungsgesetz recyclability mandates are shifting retail procurement toward glass jars and aluminum formats over multi-layer laminates. ECHA REACH restrictions on bisphenol-A epoxy coatings are extending material qualification cycles for can makers serving Rewe and Edeka banners. Bavarian fruit processors are accelerating non-BPA line certifications to maintain shelf access in Frankfurt and Munich metro markets.
Thailand
Prachuap Khiri Khan and Rayong province canneries process over sixty percent of global canned pineapple raw material flows. Thai labor regulations and seasonal weather patterns create periodic disruption exposure for export-dependent processors. Bangkok-based distributors are consolidating regional leverage across Indonesian and Vietnamese re-export channels.
Indonesia
Jakarta and Surabaya urban consumers are substituting fresh fruit with packaged convenience formats as modern retail penetration accelerates. Tetra Pak aseptic carton technology is penetrating convenience stores where refrigerated logistics remain unreliable. Local processors are adopting lightweight ambient formats for inter-island distribution across the archipelago.
France
AGEC anti-waste law provisions are mandating recyclable packaging transitions for retail-facing fruit products. Bonduelle maintains specialized organic and conventional lines tailored to Carrefour and Intermarché specifications. Lyon and Marseille food service distributors are consolidating procurement around standardized fruit cocktail grades for institutional catering contracts.
Canned Fruits Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pouch-format convenience positioning and organic certification premiums. The vendor base stratifies across integrated plantation-to-can operators, regional private-label specialists, and multinational branded portfolios. Three archetypes dominate: backward-integrated agricultural processors, retail-banner captive suppliers, and technology-focused format innovators. Competitive moves concentrate on M&A consolidation of regional sourcing assets and strategic partnerships for aseptic packaging technology licensing.
Among North American integrated processors, Seneca Foods exemplifies the agricultural-processor archetype through its captive sourcing footprint. Del Monte Foods represents the multinational branded portfolio model with plantation-to-can supply chain control. Bonduelle occupies a position within the European specialist tier, anchoring organic and conventional line differentiation for premium retail channels.
| Leading Market Players |
|---|
| Seneca Foods |
| Bonduelle |
| Del Monte Foods |
| Fresh Del Monte Produce |
| B&G Foods |
| Dole Food Company |
| Conagra Brands |
| Princes Foods |
| The Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps across Mediterranean and Southeast Asian processing clusters maintain pricing discipline through captive plantation sourcing, insulating contract negotiations with European retail banners from spot-market tinplate volatility. This ownership structure concentrates supply-side bargaining power while forcing private-label specialists toward thinner margin tiers.
Pricing Analysis
Volume placements concentrate in Grade A conventional fruit cocktail specifications while organic and pouch-format SKUs capture expanding margin pools. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic lines from EU-label conventional grades from institutional Grade B bulk supply. Cost compression in standard metal-can formats is intensifying because Chinese tinplate supply uncertainty feeds raw material volatility. Food service procurement groups exhibit highest price sensitivity; German natural retail banners show lowest.
Supply Chain Analysis
Regional distribution centers in Bangkok, Jakarta, and Ho Chi Minh City consolidate re-export flows across Southeast Asian archipelago markets. Raw material supply draws from Thai pineapple plantations, California clingstone peach orchards, and Pacific Northwest pear growers. Single-source vulnerability concentrates in Thai processing clusters where over sixty percent of global canned pineapple flows through Prachuap Khiri Khan and Rayong facilities. Distribution runs through banner-controlled direct-store-delivery networks that bypass traditional wholesale channels in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
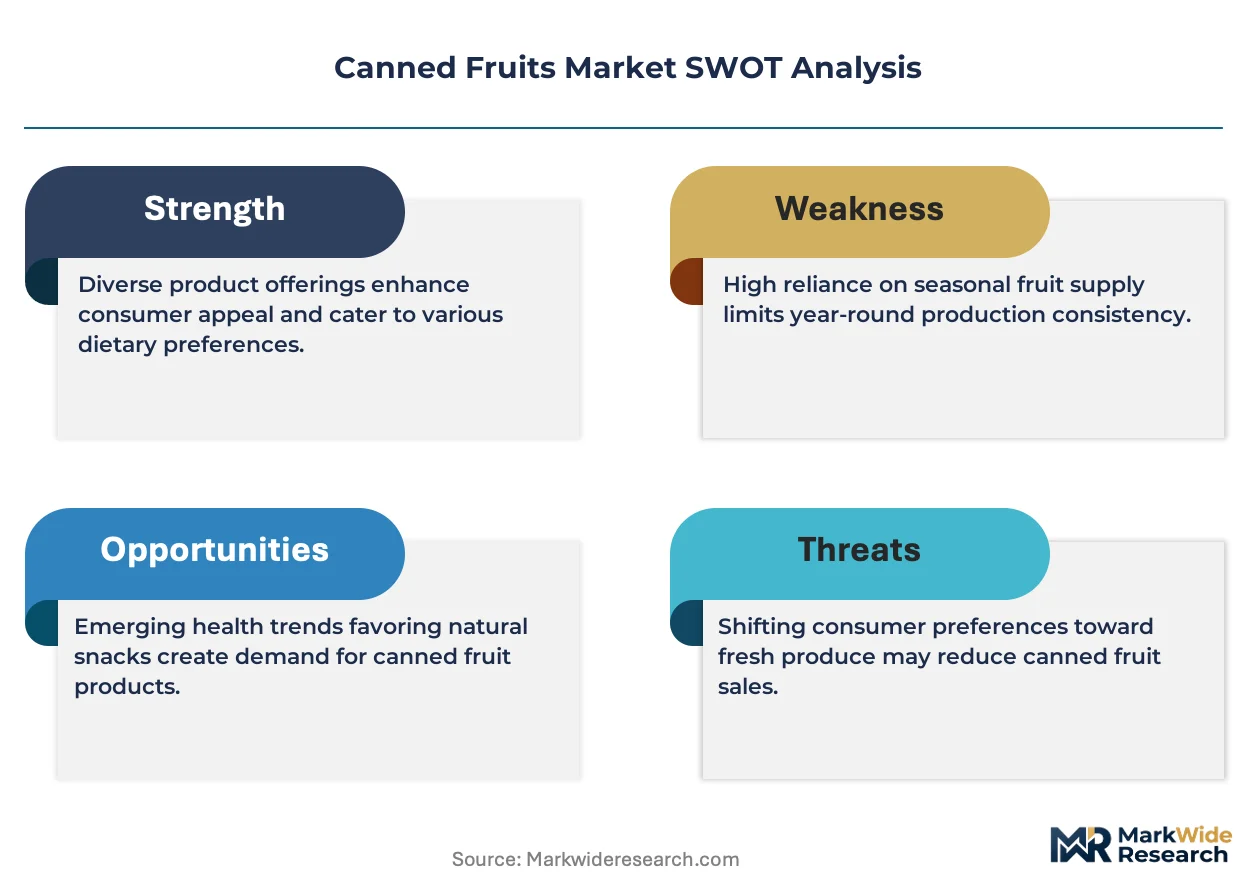
The canned fruits sector is becoming a vertical-integration race as processors pursue captive plantation sourcing to secure raw material tenure against climate and labor disruption exposure.
For Market Incumbents: Acquire Southeast Asian pineapple plantation assets to lock in raw material tenure against Thai labor regulation shifts and seasonal weather patterns. Expand retort pouch capacity in Indonesian and Vietnamese facilities to capture urban convenience-format demand. Defend shelf access in German and French retail banners by accelerating non-BPA line certifications ahead of ECHA REACH enforcement timelines. For New Entrants and Emerging Players: Aseptic carton technology licensing offers entry into Indonesian and Vietnamese convenience store channels where refrigerated logistics remain unreliable. Target Tetra Pak format penetration in Jakarta and Surabaya metro markets where ambient shelf-stable demand outpaces cold-chain infrastructure development. Pursue organic certification under EU regulation 2018/848 to access premium shelf-space allocations in Rewe and Edeka banner specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional private-label specialists with established Southeast Asian re-export relationships and underutilized retort capacity. Long-term viability hinges on format diversification away from metal-can dependence toward pouch and carton ambient technologies. Monitor ECHA authorization timelines for polyester and acrylic liner alternatives as inflection indicator for European can-maker consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Thai and Indonesian land tenure secures raw material supply against climate disruption exposure. |
| Retort Pouch Capacity Expansion | Tokyo and Seoul convenience retailer facings are climbing fastest for single-serve formats. |
| Non-BPA Line Certification | ECHA REACH restrictions on epoxy coatings mandate polyester liner qualification for EU shelf access. |
| Aseptic Carton Technology Licensing | Tetra Pak penetration in Indonesian archipelago distribution bypasses unreliable refrigerated logistics. |
| Organic Certification Investment | EU regulation 2018/848 implementation tightens conversion requirements for imported fruit supply. |
Methodological Framework
Independent corroboration across fruit processor operations executives, retail category buyers at Walmart and Carrefour banners, food service procurement directors, and thermal processing equipment specialists underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 113 filing records, EU F-Gas Regulation implementation guidance, ECHA REACH substance restriction timelines, and Thai Board of Investment processing cluster reports. Bottom-up volume modeling triangulates against top-down category expenditure estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, packaging format, quality grade, and end-user channel dimensions. CAGRs derive from segmented trend extrapolation anchored in historical trade flow patterns and regulatory implementation schedules. Forecast inputs incorporate EU Green Deal cold-chain restriction timelines and Southeast Asian urban retail infrastructure development trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Thai labor regulation shifts and tinplate supply disruption scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Zhug Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Freekeh Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Peanut Butter Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Alginate Casings Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Hummus Market