
 Europe Free from Food Market | 2026-2036
Europe Free from Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Free from Food Market Foresight
Subscription-based replenishment services for allergen-free pantry staples is consolidating how European households manage chronic dietary restrictions. Danone S.A. leverages its specialized medical nutrition infrastructure to serve celiac and lactose-intolerant consumers across France and Benelux. Nestlé S.A. anchors its free-from portfolio through dedicated R&D facilities in Switzerland that reformulate classic brands without priority allergens. Dr. Schär AG / SPA dominates the gluten-free bakery channel through deep distribution partnerships with European pharmacy and supermarket networks.
Europe free from food comprises formulated products excluding specific allergenic proteins, additives, or intolerant compounds, manufactured through segregated production lines with validated cleaning protocols and allergen threshold testing below detectable limits. These products serve clinical dietary management, lifestyle wellness, and preventive health objectives across retail and foodservice channels. Gluten-free and dairy-free categories lead volume due to diagnosed celiac disease prevalence and flexitarian milk substitution trends, while nut-free formulations capture premium shelf space in school and institutional procurement channels. Online retailers and health food stores together command the fastest-growing distribution share as direct-to-consumer platforms bypass traditional grocery slotting constraints.
EFSA allergen labeling requirements, EU Green Deal farm-to-fork targets, and national health authority nutritional guidelines collectively mandate cleaner ingredient declarations and sustainable sourcing credentials across member states. REACH chemical safety standards further restrict processing aids and packaging migrants in free-from formulations. Stakeholders must monitor evolving EN standard harmonization for gluten-free threshold definitions and prepare for tightened carbon footprint disclosure rules affecting plant-based dairy alternatives.
Market Dynamics
EFSA allergen threshold harmonization and REACH chemical safety protocols are compressing formulation timelines while forcing segregated production investments across European manufacturing networks.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Sustainability disclosure requirements for plant-based dairy alternatives are accelerating clean-label ingredient sourcing from Nordic and Baltic suppliers.
- Celiac disease diagnostic expansion:National health authority screening programs in Italy and Spain are enlarging the addressable patient population for certified gluten-free formulations.
- Enzymatic protein hydrolysis:Novel processing technologies are reducing allergen cross-contamination risks in shared bakery equipment across Benelux contract manufacturers.
Market Restraints
- Oat and rice protein input volatility:Climate-driven harvest fluctuations in Northern European growing regions are destabilizing plant-based dairy alternative cost structures.
- Segregated line capital intensity:Dedicated allergen-free production infrastructure requires 40-60% higher equipment investment than conventional flexible lines.
- EN standard threshold uncertainty:Pending gluten-free ppm definition revisions are freezing new product development budgets at mid-size German and Austrian millers.
Strategic Opportunities
- Eastern European retail penetration:Polish and Romanian supermarket chains are expanding free-from shelf space faster than Western European mature markets.
- Pharmacy channel consolidation:Reimbursement-eligible medical nutrition positioning for celiac patients is opening prescription-accessible distribution in France and Belgium.
- AI-driven allergen detection:Machine vision systems combined with rapid ELISA testing are enabling real-time production line verification for nut-free confectionery.
Industry Challenges
- Validated cleaning protocol expertise:Shortages of food safety engineers capable of designing segregated line sanitation procedures are extending facility commissioning timelines.
- Multi-certification compliance burden:Simultaneous pursuit of organic, gluten-free, and carbon-neutral labels creates documentation conflicts across French and Italian auditors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Free from Food Market |
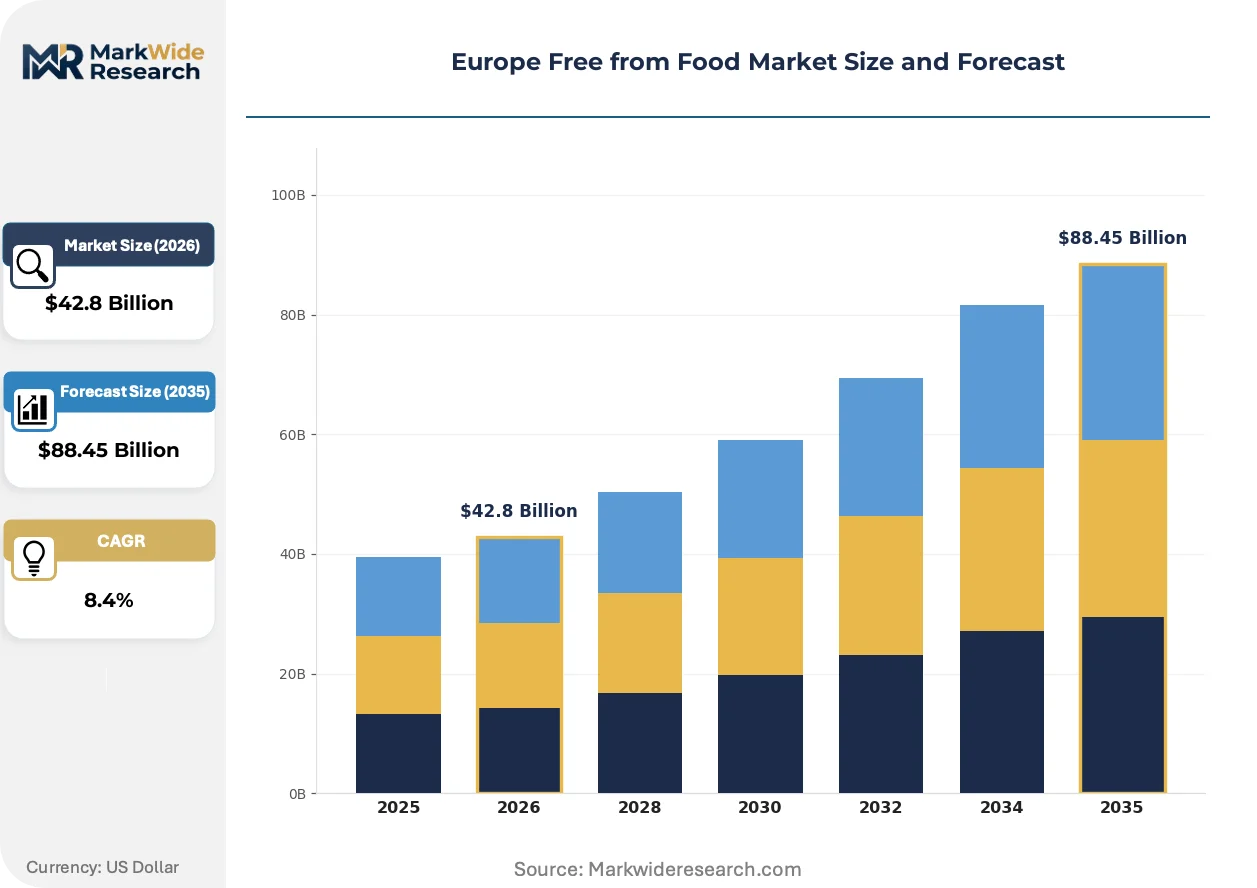
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Soy-Free End User: Retail Consumers, Food Service Providers, Health Conscious Individuals, Allergy Sufferers Form: Snacks, Beverages, Baking Ingredients, Meal Replacements Distribution Channel: Online Retailers, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Danone S.A., Nestlé S.A., General Mills Inc., Oatly Group AB, Arla Foods amba, The Hain Celestial Group, Inc., Dr. Schär AG / SPA, Premier Foods PLC, Kellogg Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Free from Food Market Shifts & Advancements
High-pressure processing and precision fermentation are converging to reshape protein ingredient sourcing, while regulatory disclosure mandates and direct-to-consumer channel expansion are rewriting how European households discover and replenish allergen-free staples.
Novel precision fermentation platforms for whey and casein analogs are electrifying the dairy-free category by delivering functional properties previously unattainable with conventional plant proteins. German and Dutch ingredient startups are scaling these platforms to serve reformulation demands from legacy bakery and confectionery brands. The technology is electrifying competitive positioning by collapsing the performance gap between allergen-free and conventional dairy in applications requiring emulsification and browning.
REACH restrictions on processing aids and packaging migrants are forcing reformulation of leavening agents and emulsifiers used in gluten-free bread production. ECHA substance evaluation timelines are compressing supplier qualification windows for Spanish and Italian industrial bakeries. Free-from manufacturers in Portugal and Greece are responding by accelerating natural fermentation and clean-label stabilizer adoption ahead of enforcement deadlines.
Subscription-based replenishment for chronic dietary conditions is displacing intermittent supermarket purchasing among French and German millennial households with celiac or lactose intolerance diagnoses. Direct-to-consumer platforms are capturing pantry staple volume that previously flowed through conventional grocery slotting. This behavioral pivot is most visible in Benelux urban corridors where delivery density supports profitable last-mile economics for specialized allergen-free assortments.
Europe Free from Food Market Segmentation
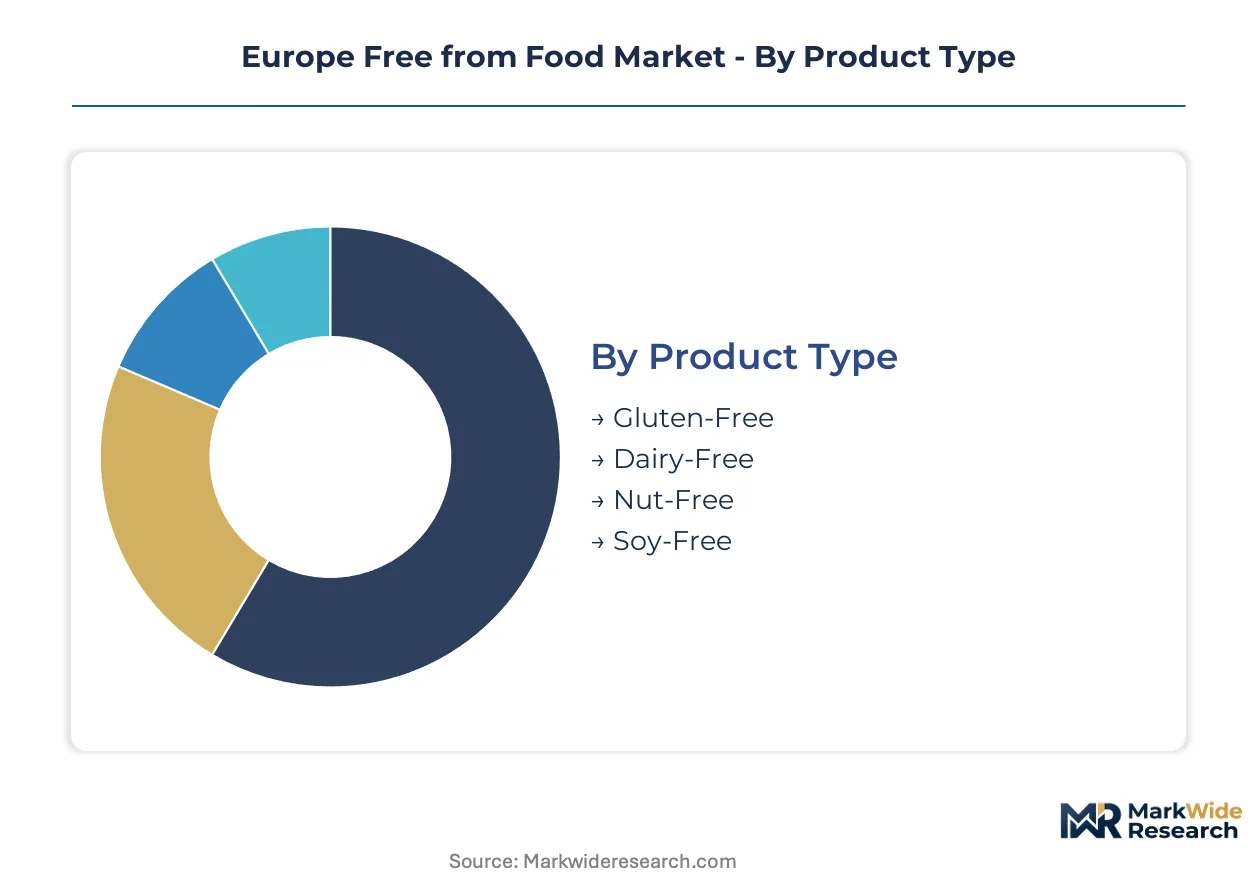
Europe free from food market segmentation reveals distinct formulation and channel strategies across allergen categories. Product specifications, end-user clinical needs, and distribution economics create divergent margin profiles that manufacturers must navigate simultaneously.
Product Type:
Formulation technology separates allergen removal approaches from protein substitution strategies, with enzymatic hydrolysis and precision fermentation commanding distinct capital intensity profiles.
- Gluten-Free:Formulations rely on rice, corn, and pseudocereal starches with hydrocolloid binders to replicate wheat viscoelasticity. Italian and Spanish diagnostic expansion is enlarging the certified patient population served by pharmacy-reimbursed medical nutrition positioning.
- Dairy-Free:Precision fermentation platforms for whey and casein analogs are collapsing the functional performance gap with conventional dairy in emulsification and browning applications. German and Dutch ingredient startups are scaling these bioreactor systems to serve legacy bakery reformulation demands.
- Nut-Free:Seed-based protein concentrates from sunflower and pumpkin sources substitute for tree nut functionality in European confectionery. School procurement channels in France and Belgium mandate validated allergen threshold testing below detectable limits.
- Soy-Free:Pea and fava bean isolates replace soy protein in meat analog formulations targeting estrogen-sensitive consumer segments. Nordic clean-label sourcing requirements are accelerating adoption of domestic pulse protein supplies.
Mature deployment sits with gluten-free formulations across pharmacy and supermarket networks. Newer deployment is concentrated in dairy-free precision fermentation platforms scaling toward industrial volumes.
End User:
Customer archetypes span chronic clinical management, discretionary wellness positioning, and institutional procurement with divergent price elasticity and certification requirements.
- Retail Consumers:Subscription-based replenishment services capture pantry staple volume from millennial households managing celiac or lactose intolerance diagnoses through direct-to-consumer platforms bypassing conventional grocery slotting constraints.
- Food Service Providers:Kitchen segregation protocols and supplier certification documentation dominate procurement criteria for contract caterers serving schools and healthcare facilities across Benelux urban corridors.
- Health Conscious Individuals:Flexitarian milk substitution trends drive discretionary purchasing of dairy-free alternatives without clinical diagnosis requirements.
- Allergy Sufferers:EFSA threshold harmonization mandates validated cleaning protocols and segregated production lines serving the most price-inelastic demand segment with medical nutrition reimbursement eligibility in France and Belgium.
Volume concentration rests with retail consumers. Margin expansion is climbing fastest among allergy sufferers accessing prescription-channel distribution.
Form:
Processing intensity and shelf stability requirements differentiate manufacturing asset configurations across the four form categories.
- Snacks:Extruded and puffed formulations using alternative starches dominate gluten-free cracker and chip production with lower water activity constraints than fresh bakery.
- Beverages:Plant-based dairy alternatives face EU Green Deal farm-to-fork carbon disclosure mandates accelerating Nordic and Baltic clean-label ingredient sourcing.
- Baking Ingredients:Pre-mixed flour blends with hydrocolloid and enzyme systems simplify home preparation for celiac consumers while reducing cross-contamination risk in shared kitchen environments.
- Meal Replacements:Complete nutritional formulations target diagnosed patients requiring macro- and micronutrient assurance beyond simple allergen exclusion.
Manufacturing scale advantages accumulate in snacks and beverages. Product development investment is concentrating in meal replacements with medical nutrition positioning.
Distribution Channel:
Channel economics determine certification burden, slotting fee exposure, and direct consumer relationship depth across the four pathways.
- Online Retailers:Direct-to-consumer platforms capture replenishment subscription volume with delivery density supporting profitable last-mile economics in German and French urban corridors.
- Supermarkets:Polish and Romanian chains are expanding free-from shelf space faster than Western European mature markets with lower slotting fee barriers for emerging brands.
- Health Food Stores:Staff expertise and consumer trust position these outlets for premium-priced specialty formulations with complex ingredient storytelling requirements.
- Specialty Stores:Pharmacy channel consolidation in France and Belgium opens prescription-accessible distribution for reimbursement-eligible celiac and lactose-intolerant patients.
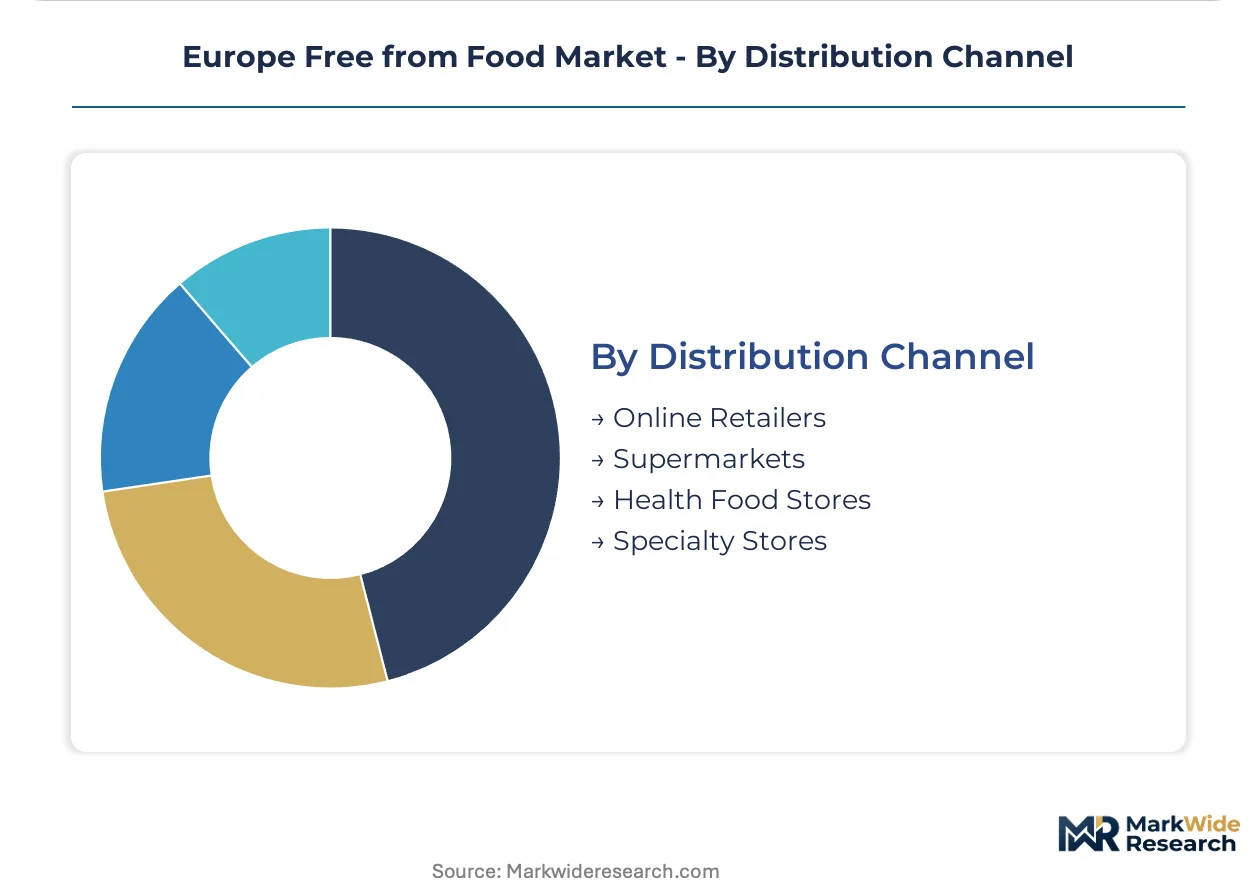
Established volume flows through supermarkets. Channel expansion is gaining share fastest among online retailers capturing subscription replenishment behavioral shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for allergen-free formulations concentrates in Western European manufacturing belts, while consumption growth accelerates faster in Eastern European retail channels where free-from shelf space expansion outpaces mature markets.
Germany
Millennial households in Berlin and Hamburg drive subscription-based replenishment demand for gluten-free and dairy-free pantry staples. EFSA allergen labeling protocols mandate validated cleaning procedures across Bavarian contract manufacturing facilities. The Rhine-Ruhr industrial corridor hosts segregated production lines serving reformulation demands from legacy bakery brands.
France
Pharmacy channel consolidation opens prescription-accessible distribution for reimbursement-eligible celiac patients in Paris and Lyon. ANSM nutritional guidelines reinforce medical nutrition positioning for certified gluten-free formulations. The Auvergne-Rhône-Alpes region anchors precision fermentation R&D platforms scaling whey analog production.
Italy
National health authority screening programs enlarge the diagnosed celiac population seeking certified formulations in Milan and Rome. EU Green Deal farm-to-fork mandates accelerate clean-label ingredient sourcing from domestic pulse protein suppliers. Emilia-Romagna industrial bakeries pioneer enzymatic hydrolysis systems reducing cross-contamination risks.
Poland
Supermarket chains in Warsaw and Kraków expand free-from shelf space faster than Western European mature markets with lower slotting fee barriers. REACH chemical safety standards compress supplier qualification windows for local contract manufacturers. The Łódź manufacturing belt attracts segregated line investments serving export demand to Benelux.
Spain
Diagnostic expansion programs in Madrid and Barcelona enlarge the addressable patient population for pharmacy-distributed medical nutrition. ECHA substance evaluation timelines force reformulation of leavening agents in Catalan industrial bakeries. The Valencia region concentrates nut-free confectionery production serving school procurement channels.
Europe Free from Food Market Competitive Landscape
Top-tier vendors anchor the medical nutrition and mass-market branded segments, while mid-tier specialists occupy private-label and regional distribution niches. The competitive structure stratifies across pharmaceutical-channel incumbents, dairy majors diversifying into plant-based alternatives, and dedicated gluten-free bakery specialists. Three archetypes dominate: legacy food conglomerates leveraging R&D infrastructure, allergen-focused specialists with pharmacy network depth, and ingredient technology startups commercializing precision fermentation platforms. M&A activity targets pharmacy channel access and precision fermentation capacity, while portfolio diversification moves concentrate on dairy-free extension and Eastern European distribution buildout.
Among Swiss and French food conglomerates, Nestlé S.A. and Danone S.A. exemplify the R&D-led diversification archetype, with the former anchoring reformulation capabilities through dedicated facilities and the latter leveraging medical nutrition infrastructure across France and Benelux. Dr. Schär AG / SPA occupies a distinct position as an allergen-focused specialist with deep pharmacy and supermarket network penetration. These three entities represent the tiered competitive structure: multinational scale players, regional medical nutrition leaders, and dedicated free-from specialists each commanding different margin profiles and channel access levels.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| General Mills Inc. |
| Oatly Group AB |
| Arla Foods amba |
| The Hain Celestial Group, Inc. |
| Dr. Schär AG / SPA |
| Premier Foods PLC |
| Kellogg Company |
| Others |
Supply & Pricing Matrix
Oat and rice protein futures volatility cascades through European plant-based dairy supply chains into three-tier pricing structures across premium, standard, and economy levels. EFSA allergen threshold harmonization and REACH chemical safety protocols compound input cost uncertainty while segregated production investments compress margin flexibility across Benelux and German contract manufacturers.
Pricing Analysis
Margin tightening in mid-tier formulations reflects oat protein input volatility and segregated line capital intensity. Premium-mid-economy pricing differentiation separates pharmacy-reimbursed medical nutrition from supermarket private-label alternatives. Cost-down pressure on economy tiers accelerates because Polish and Romanian supermarket chains negotiate slotting fees below Western European benchmarks. Allergy sufferers accessing prescription channels exhibit lowest price sensitivity while flexitarian retail consumers drive volume at highest elasticity.
Supply Chain Analysis
EFSA certification and EN standard compliance gating restricts qualified supplier pools to German, Dutch, and Italian facilities with validated cleaning protocols. Raw material flows draw from Nordic oat cultivation, Baltic pea protein processing, and domestic pseudocereal milling. Single-source vulnerability concentrates in precision fermentation capacity scaling from Auvergne-Rhône-Alpes bioreactor platforms. Distribution runs through pharmacy networks in France and Belgium alongside direct-to-consumer subscription platforms in German urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA allergen threshold uncertainty and REACH chemical safety enforcement are consolidating mid-tier manufacturers without segregated production infrastructure. Weaker players lacking pharmacy channel access or precision fermentation partnerships face accelerated exit pressure.
For Market Incumbents: Anticipate EN standard threshold revisions by accelerating gluten-free certification investments ahead of pending ppm definition changes. Defensive consolidation moves should prioritize backward integration into Nordic oat protein supplies and captive precision fermentation capacity in the Netherlands. Pharmacy channel control in France and Belgium remains the priority lever against supermarket private-label erosion. For New Entrants and Emerging Players: Capture Eastern European retail penetration opportunities in Polish and Romanian supermarket chains where slotting fee barriers remain below Western European levels. White-space targets include AI-driven allergen detection systems for real-time production line verification and subscription-based replenishment platforms serving millennial celiac households in Berlin and Hamburg. Go-to-market positioning should emphasize direct-to-consumer delivery density over conventional grocery slotting. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale German and Austrian millers with frozen NPD budgets but intact pharmacy network relationships. Long-term viability over the next decade hinges on precision fermentation platform access and EN standard compliance infrastructure. The signal to watch is EFSA gluten-free ppm definition finalization triggering acquisition premiums for certified facility capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | German and Dutch bioreactor platforms collapse functional performance gaps in dairy-free reformulation. |
| Pharmacy Channel Expansion | Reimbursement-eligible positioning in France and Belgium opens prescription-accessible distribution for celiac patients. |
| Segregated Line Investment | Validated cleaning protocols and dedicated allergen-free infrastructure satisfy EFSA threshold harmonization mandates. |
| Direct-to-Consumer Platform Launch | Subscription replenishment captures pantry staple volume from millennial households bypassing grocery slotting constraints. |
| Eastern European Distribution Buildout | Polish and Romanian supermarket chains expand free-from shelf space faster than mature Western European markets. |
Research Methodology
Independent corroboration across EFSA regulatory filings, EU Green Deal farm-to-fork implementation documents, and REACH chemical safety substance evaluations underwrites the qualitative findings. Primary interviews with food safety engineers, pharmacy procurement managers at French and Belgian hospital systems, and category buyers at German supermarket chains combined with secondary validation from customs trade data, Nielsen retail audit records, and EN standard harmonization notices. Bottom-up facility capacity assessments and top-down consumption modeling triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price mix effects across product type, end user, form, and distribution channel dimensions. CAGRs derive from segmented growth trajectory modeling incorporating celiac disease diagnostic expansion rates, precision fermentation capacity buildout timelines, and subscription platform penetration curves. Industry-specific forecast inputs include EFSA allergen threshold revision schedules and EU Green Deal carbon disclosure implementation phases.
The model holds under stable regulatory interpretation of EN gluten-free thresholds and REACH chemical safety enforcement timelines; deviation in EFSA ppm definition finalization or ECHA substance evaluation acceleration would shift capacity investment and pricing assumptions. A model refresh is warranted upon material change in precision fermentation platform commercialization rates or pharmacy reimbursement policy adjustments in France and Belgium.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Tortilla Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Burritos Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Canned Goods Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Hummus Market
Packaged Foods
Packaged Vegan Foods Market