
 Packaged Sprouts Market | 2026-2036
Packaged Sprouts Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Sprouts Market Analysis
North American sprout growers is rebalancing capacity toward controlled-environment agriculture after recurring contamination incidents in field-grown operations. Fuji Natural Foods leverages its integrated seed-to-package traceability system to sustain retail shelf presence across Japanese convenience chains. Van der Plas Sprouts anchors European supply through its Netherlands-based hydroponic facilities, while Pulmuone competes in Korean and North American channels with refrigerated logistics expertise.
Packaged sprouts are germinated seeds or legumes harvested at the cotyledon stage, typically containing 4-6 day-old plant tissue with moisture content between 80-90%, requiring continuous refrigeration below 5°C to suppress pathogen proliferation; their primary commercial purpose is delivering ready-to-eat plant protein and micronutrients to food service and retail consumers without home preparation. Broccoli sprout varieties command premium positioning due to sulforaphane content claims, while mung bean formats occupy mainstream volume through Asian cuisine integration. Supermarkets dominate distribution channel value capture, though online retail segments attract subscription-based household buyers seeking direct delivery of vacuum-packed formats.
The FDA enforces pathogen testing mandates under the Produce Safety Rule, while EU regulators apply MDR-adjacent traceability requirements and EFSA hygiene benchmarks for ready-to-eat sprouted seeds; these frameworks elevate compliance costs but simultaneously filter low-capability entrants from commercial channels. Japan's Food Sanitation Act and positive list system for agricultural chemicals create additional certification layers for imported sprout products. Stakeholders must monitor evolving microbiological standards and packaging material restrictions as regulatory divergence between major jurisdictions intensifies sourcing complexity.
Market Dynamics
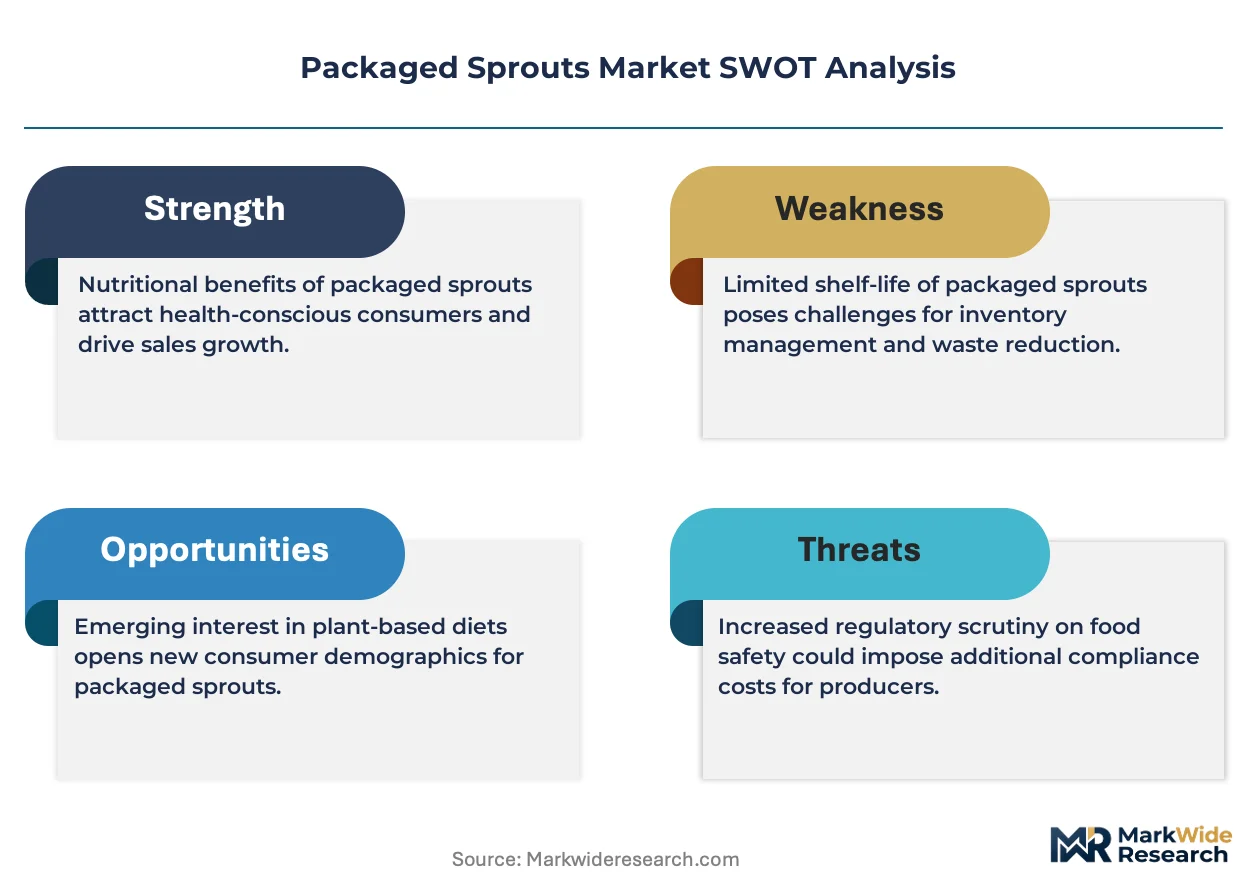
Controlled-environment agriculture is displacing field-grown sprout operations as contamination incidents drive capital toward hydroponic and vertical farming infrastructure with sealed climate control.
Growth Catalysts
- Produce Safety Rule enforcement:FDA pathogen testing mandates accelerate consolidation toward large-scale processors capable of laboratory verification, filtering smaller field operators from commercial channels.
- Plant-based protein demand:Food service chains and meal-kit providers specify pre-washed sprout formats to reduce kitchen labor and cross-contamination risk in high-volume settings.
- Sulforaphane research:Broccoli sprout varieties gain shelf space as functional food positioning around glucoraphanin content attracts health-conscious retail buyers.
Market Restraints
- Seed supply concentration:Certified organic sprouting seed production clusters in limited geographic zones, creating input vulnerability for processors scaling non-GMO product lines.
- Cold chain cost structure:Continuous sub-5°C refrigeration requirements from harvest through retail elevate logistics expenditure versus ambient produce categories.
- Substitution by microgreens:Soil-grown microgreen formats offer similar visual appeal with reduced microbiological risk, capturing overlapping use cases in garnish and salad applications.
Strategic Opportunities
- Subscription direct-to-consumer:Vacuum-packed sprout formats bypass traditional supermarket slotting fees through recurring delivery models targeting urban households.
- EU Green Deal alignment:Controlled-environment facilities qualify for sustainability-linked financing as water-recirculating hydroponic systems demonstrate resource efficiency metrics.
- Asian cuisine export:Mung bean sprout processors expand into Southeast Asian markets where quick-service noodle chains standardize ingredient specifications.
Industry Challenges
- HACCP specialist scarcity:Sprout-specific hazard analysis expertise concentrates among legacy processors, constraining new facility commissioning timelines.
- Packaging material compliance:Evolving EU restrictions on single-use plastics force simultaneous reformulation of breathable film specifications and shelf-life validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Sprouts Market |
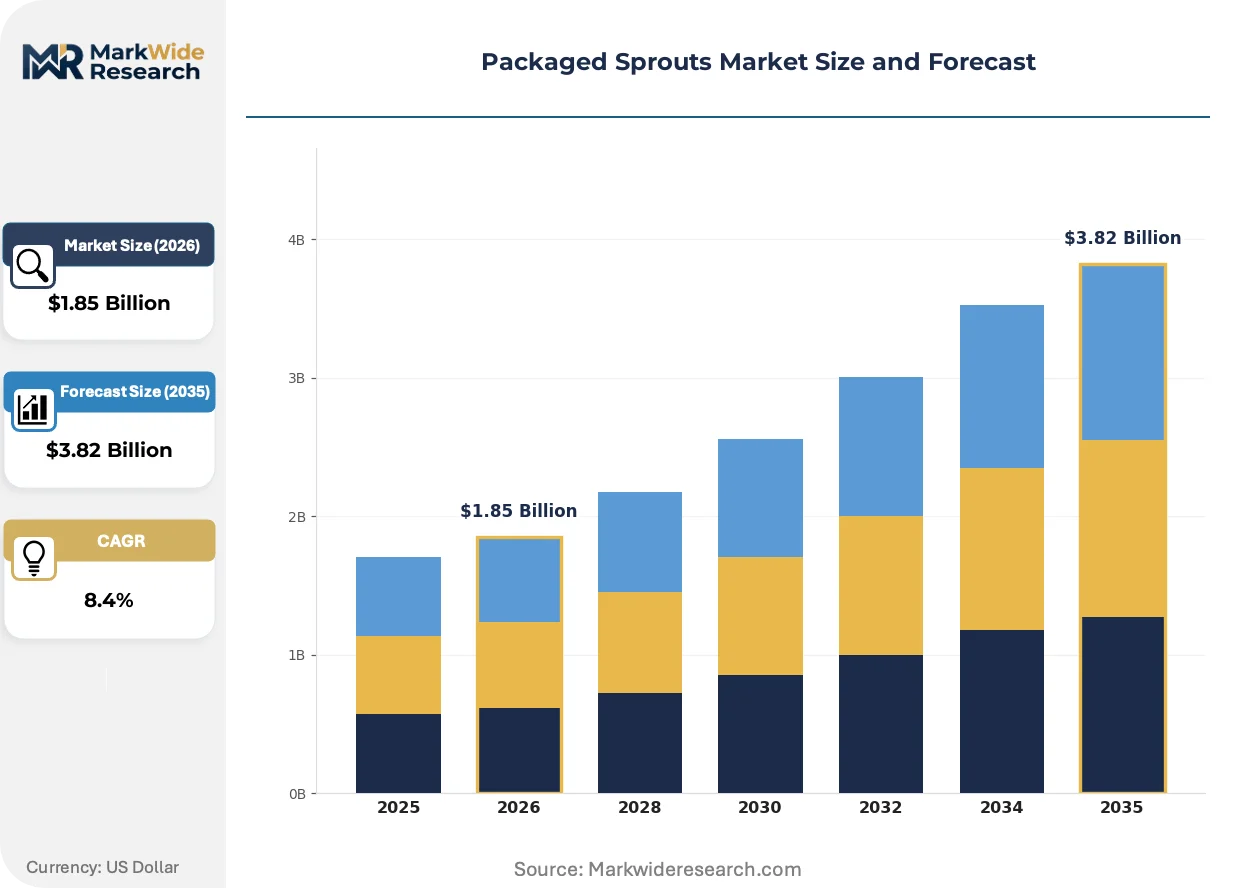
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alfalfa, Broccoli, Mung Bean, Sunflower Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Wholesale End User: Restaurants, Households, Food Processors, Catering Services Packaging Type: Plastic Bags, Glass Containers, Vacuum Packs, Eco-Friendly Packaging |
| Companies Covered | Fuji Natural Foods, Van der Plas Sprouts, Jonathan Sprouts, Narita Foods, Ocean Mist Farms, Pulmuone, International Specialty Supply, Misionero Vegetables, BrightFresh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Sprouts Market Emerging Trajectories
Automation of seed handling and environmental monitoring is compressing labor dependency while regulatory data-logging requirements reshape facility design standards.
Hyperspectral imaging systems are automating early-stage contamination detection in sprout washing lines. Large-scale processors in the United States and Germany deploy these sensors to replace manual spot-checking with continuous spectral analysis. This compression of quality assurance labor is automating throughput scaling without proportional headcount expansion.
EFSA hygiene benchmark revisions for ready-to-eat sprouted seeds tighten microbiological surveillance protocols across European processing facilities. The industrial consequence is mandatory environmental monitoring program expansion with third-party laboratory verification. Small-to-mid processors in Spain and Italy face disproportionate compliance cost absorption relative to integrated Dutch competitors.
Restaurant procurement teams now specify lot-level traceability as a contract prerequisite, displacing anonymous wholesale sourcing. Distributors respond by integrating blockchain-anchored documentation into their value proposition. This verification-driven preference shift is most visible in Japanese convenience chain supply agreements where seed-to-package records determine vendor qualification.
Packaged Sprouts Market Segmentation
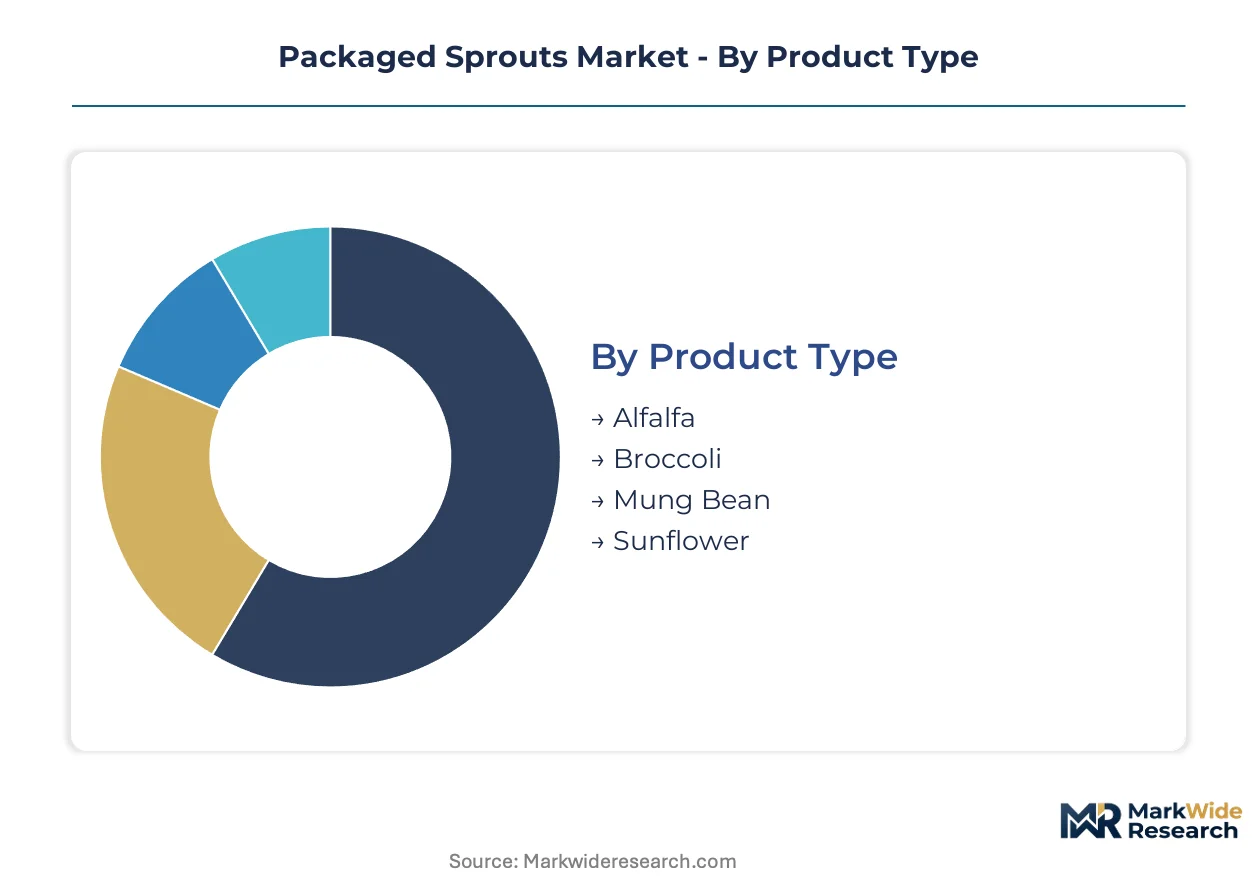
Segmentation in packaged sprouts reveals distinct operational requirements across product biology, channel cold-chain capabilities, and end-user preparation protocols. Each dimension shapes facility investment, packaging specification, and regulatory compliance burden differently.
Product Type:
Integration depth varies sharply: alfalfa and mung bean formats embed directly into prepared food manufacturing, while broccoli and sunflower varieties command standalone functional positioning.
- Broccoli:Sulforaphane-rich cotyledon tissue harvested at 3-4 days delivers standardized glucoraphanin content for supplement and functional food channels. Premium positioning in Japanese convenience retail and US natural products stores depends on verified active compound testing.
- Mung Bean:White hypocotyls with minimal chlorophyll development serve as the workhorse input for Asian quick-service noodle chains and stir-fry manufacturing. Volume concentration in Korean and Southeast Asian food processing reflects cuisine-standardized ingredient specifications.
- Alfalfa:Fine-stemmed microgreen format with 5-7 day harvest cycles fills sandwich and salad garnish applications through US supermarket deli channels.
- Sunflower:Large cotyledon structure with nutty flavor profile targets premium salad kit inclusion and direct-to-consumer subscription boxes.
Mung bean leads volumes today; broccoli is gaining share fastest.
Distribution Channel:
Cost tier stratification separates capital-intensive refrigerated infrastructure from asset-light digital intermediation.
- Supermarkets:Temperature-controlled distribution centers with dedicated produce sections absorb slotting fees and category management costs. German and US chains dominate value capture through private label sprout programs.
- Online Retail:Vacuum-packed formats bypass retail intermediation via subscription models targeting urban households with recurring delivery schedules. Cold-chain last-mile execution remains the critical capability differentiator.
- Health Food Stores:Organic-certified SKUs with transparent seed sourcing command price premiums in specialty retail environments.
- Wholesale:Food service distributors aggregate restaurant and catering demand through consolidated procurement contracts with lot-level traceability requirements.
Supermarket channels anchor current revenue; online retail is expanding most quickly.
End User:
Application maturity separates industrial-scale processing from fragmented household consumption patterns.
- Restaurants:Pre-washed, ready-to-use formats reduce kitchen labor and cross-contamination risk in high-volume settings. Japanese and Korean quick-service chains specify standardized sprout dimensions for menu consistency.
- Food Processors:Ingredient-scale procurement with HACCP documentation requirements drives consolidation toward large-scale certified suppliers.
- Households:Retail package sizes of 100-200 grams serve direct consumption through supermarket and online channels.
- Catering Services:Event-scale volume with variable demand patterns requires flexible supply agreements and extended shelf-life packaging.
Restaurant procurement dominates transaction value; food processor demand is climbing the fastest.
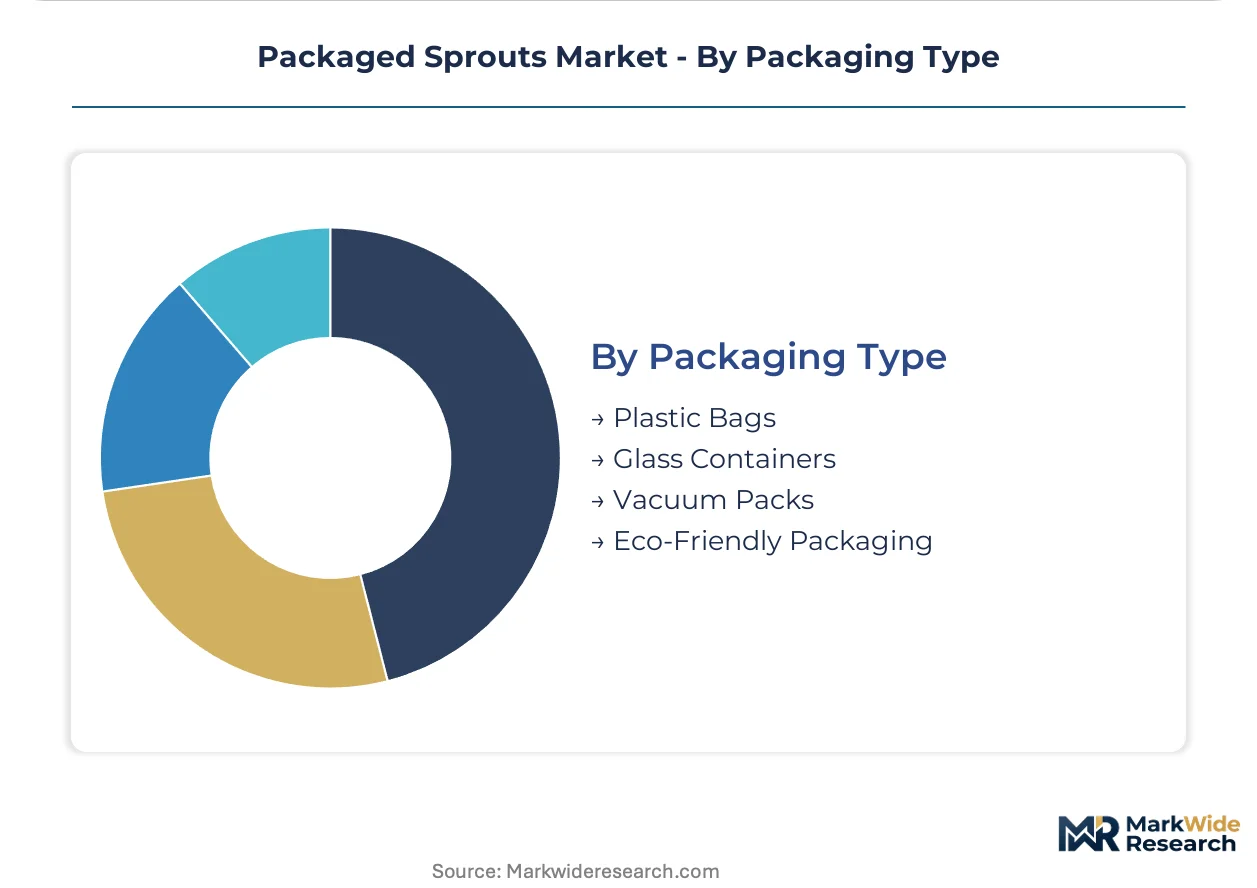
Packaging Type:
Margin structure separates commodity film formats from premium sustainable alternatives with regulatory compliance premiums.
- Vacuum Packs:Modified atmosphere packaging extends shelf life to 14-21 days through oxygen reduction, enabling direct-to-consumer subscription models and export logistics.
- Plastic Bags:Perforated polyethylene dominates mainstream retail with lowest unit cost and established recycling infrastructure.
- Eco-Friendly Packaging:Compostable films and molded fiber trays respond to EU single-use plastic restrictions and retailer sustainability mandates.
- Glass Containers:Reusable and recyclable format targets premium health food retail with visual quality signaling.
Plastic bags lead unit volumes today; eco-friendly alternatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping packaged sprout production geography as processors migrate toward jurisdictions with established controlled-environment agriculture infrastructure and streamlined pathogen-testing protocols. Compliance cost differentials between field-grown and hydroponic operations drive capital allocation toward Germany, Japan, and the Netherlands.
United States
Restaurant chains and meal-kit providers specify pre-washed sprout formats to reduce kitchen labor costs. The FDA's Produce Safety Rule mandates pathogen testing that accelerates consolidation toward large-scale processors with laboratory verification capabilities. California's Salinas Valley and Central Coast regions anchor domestic production through integrated seed-to-package operations serving West Coast retail channels.
Germany
Supermarket private-label programs and organic-certified retail formats sustain processor margins through premium positioning. EFSA hygiene benchmarks for ready-to-eat sprouted seeds tighten microbiological surveillance protocols with mandatory third-party laboratory verification. The Netherlands-bordering North Rhine-Westphalia region concentrates hydroponic facility investment from Dutch-controlled operations seeking EU market access.
Japan
Convenience chain supply agreements demand lot-level traceability as a contract prerequisite for vendor qualification. The Food Sanitation Act and positive list system for agricultural chemicals create additional certification layers for imported products. Tokyo-Osaka corridor processors deploy blockchain-anchored documentation to satisfy procurement team verification requirements.
South Korea
Quick-service noodle chains standardize mung bean sprout ingredient specifications across franchise networks. MFDS microbiological standards for ready-to-eat sprouted seeds align with export-market access requirements. Seoul-Incheon logistics clusters support refrigerated distribution into Southeast Asian markets where Korean cuisine penetration drives ingredient demand.
Netherlands
Water-recirculating hydroponic systems qualify for EU Green Deal sustainability-linked financing based on resource efficiency metrics. REACH-adjacent traceability requirements and packaging material restrictions elevate compliance costs that filter low-capability entrants. The Westland greenhouse cluster hosts vertically integrated sprout operations supplying German and Belgian retail channels.
Packaged Sprouts Market Vendor Landscape
Japanese producers anchor one tier through integrated seed-to-package traceability systems; Dutch and Korean specialists hold positions in controlled-environment agriculture and refrigerated logistics respectively. Market structure reflects moderate consolidation around legacy processors with HACCP expertise and laboratory verification capabilities. Three archetypes dominate: vertically integrated seed-to-retail operators, hydroponic facility specialists, and refrigerated logistics-anchored exporters. Capacity expansion and strategic partnerships constitute the dominant competitive moves as processors secure raw material access and cold-chain infrastructure.
Within the integrated traceability tier, Fuji Natural Foods exemplifies seed-to-package documentation systems that determine vendor qualification for Japanese convenience chains. Van der Plas Sprouts occupies a position among Netherlands-based hydroponic facility operators leveraging EU Green Deal financing eligibility. Pulmuone represents the refrigerated logistics-anchored archetype competing across Korean and North American channels through cold-chain execution capabilities.
| Leading Market Players |
|---|
| Fuji Natural Foods |
| Van der Plas Sprouts |
| Jonathan Sprouts |
| Narita Foods |
| Ocean Mist Farms |
| Pulmuone |
| International Specialty Supply |
| Misionero Vegetables |
| BrightFresh |
| Others |
Supply Flow & Price Mechanics
HACCP-certified facility managers in the Netherlands command wage premiums that compress operating margins for mid-tier processors, widening the spread between economy-grade plastic-bagged sprouts and vacuum-packed premium formats. Cold-chain labor differentials between Dutch hydroponic clusters and Spanish field operations translate directly into three-tier pricing stratification across European retail channels.
Pricing Analysis
Distributor margin layers absorb 15-25 percent of final shelf price before retailer markup applies. Pricing stratifies across premium, standard, and economy tiers based on certification grade and packaging format. Cost compression in the standard tier intensifies as supermarket private-label programs consolidate procurement volumes. Food service buyers exhibit lowest price sensitivity due to labor-cost savings from pre-washed formats, while household direct-to-consumer subscribers negotiate aggressively on recurring delivery rates.
Supply Chain Analysis
Dual-sourcing requirements from Japanese convenience chains mandate processors qualify backup facilities in both domestic and Korean supply bases. Certified organic seed production draws from the United States, Italy, and New Zealand, with germination infrastructure concentrated in the Netherlands, Japan, and California. Single-source vulnerability in specialized HACCP expertise constrains new facility commissioning. Distribution runs through temperature-controlled consolidation centers before last-mile refrigerated delivery to retail and food service endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment agriculture yields margin expansion as water-recirculating hydroponic systems reduce input costs while premium functional positioning around sulforaphane content commands price premiums.
For Market Incumbents: To counter substitution by soil-grown microgreens, anchor shelf space through backward integration into seed breeding programs and accelerate certification investment for EU Green Deal-aligned sustainability credentials. Capacity addition in the Netherlands-bordering German regions secures proximity to Dutch technical expertise while satisfying EFSA laboratory verification requirements. For New Entrants and Emerging Players: Launch via subscription direct-to-consumer models targeting urban households in underserved Southeast Asian markets where Korean cuisine penetration drives ingredient demand. White-space concentration in vacuum-packed broccoli sprout formats for Japanese supplement channels offers the most penetrable entry point, with blockchain-anchored traceability documentation as the qualifying go-to-market angle. For Investors and Strategic Acquirers: Food service distributors with refrigerated logistics networks are the most active acquirer in this space, consolidating regional sprout processors to secure HACCP-compliant supply bases. Acquisition target archetypes include mid-scale Dutch hydroponic operators with EU Green Deal financing eligibility and established seed-to-package documentation systems. Watch microbiological standard revisions from EFSA and FDA as the signal indicating regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Breeding | Captures margin from certified organic seed supply concentrated in Italy and New Zealand. |
| HACCP Certification Investment | Filters smaller competitors as FDA Produce Safety Rule enforcement tightens laboratory verification requirements. |
| Subscription Direct-to-Consumer Launch | Bypasses supermarket slotting fees through recurring vacuum-packed delivery models targeting urban households. |
| EU Green Deal Alignment | Unlocks sustainability-linked financing for water-recirculating hydroponic facilities in the Netherlands and Germany. |
| Blockchain-Anchored Traceability Deployment | Satisfies Japanese convenience chain procurement mandates for lot-level seed-to-package documentation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sprout processing facility managers, food service procurement directors, supermarket category buyers, and cold-chain logistics operators with secondary validation from FDA Produce Safety Rule guidance documents, EFSA hygiene benchmark publications, EU customs trade data, and Japanese Food Sanitation Act regulatory filings. Bottom-up facility capacity assessments and top-down retail channel value capture estimates were triangulated to anchor market size calculations.
Segment-weighting applied product type, distribution channel, and end-user dimensions across the analysis window, with broccoli and mung bean varieties modeled separately due to divergent functional positioning and cuisine integration patterns. CAGRs were derived from historical growth trajectory analysis adjusted for regulatory enforcement intensity and controlled-environment agriculture capital deployment trends. Forecast inputs incorporated seed supply concentration metrics and cold-chain infrastructure expansion pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under simultaneous EFSA microbiological standard revision and EU single-use plastic packaging restriction acceleration. Deviation in HACCP specialist labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Brio Bowls Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Instant Rice Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Burritos Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Instant Noodles Market