
 Sausage Casing Market | 2026-2036
Sausage Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Sausage Casing Market Outlook
European collagen casing producers is repositioning capacity toward higher-yield extrusion formats. Viscofan sustains vertical integration from hide sourcing to finished spool distribution across Iberian and Latin American plants. Devro specializes in slow-release collagen films for dry-cured applications, occupying a defensible niche in premium charcuterie supply chains. Shenguan Holdings leverages cost-optimized regenerated cellulose output to compete on volume in Asian processed-meat segments.
Sausage casing refers to the tubular membrane—composed of cleaned animal intestines, regenerated collagen fibers, extruded cellulose, or food-grade polymers—that encloses ground meat mixtures during forming, cooking, smoking, or drying operations. Natural casings deliver traditional snap and permeability for artisanal dry sausages, though supply fluctuates with slaughter volumes and labor-intensive cleaning requirements. Collagen casings dominate industrial fresh and smoked sausage production where diameter consistency and automated stuffing speeds matter most. Cellulose casings peel away after thermal processing to yield skinless frankfurters, a format preferred by North American food manufacturers and quick-service restaurant suppliers.
FDA food-contact substance notifications and USDA FSIS ingredient standards govern collagen and cellulose casing approvals in the United States, while EFSA evaluates novel extraction processes and migration limits for European market access. China's SAMR enforces GB standards for regenerated cellulose food packaging, creating compliance friction for imported casing reels. Stakeholders must monitor evolving biopolymer regulations and slaughter byproduct traceability mandates, as these will determine which material platforms retain cost-competitive market access across major protein-processing jurisdictions.
Market Dynamics
EU plastic packaging reduction mandates under the Packaging and Packaging Waste Regulation are redirecting procurement toward edible and biodegradable casing alternatives, compressing conventional polymer adoption timelines across European meat processing clusters.
Growth Catalysts
- Clean-label portfolio expansion:Meat processors across Germany and Spain are reformulating sausage lines to eliminate synthetic additives, driving collagen casing volumes in premium retail segments.
- REACH-compliant biopolymer pathways:ECHA-registered cellulose regeneration processes are unlocking industrial-scale edible casing production with reduced migration risk profiles.
- Automated stuffing line upgrades:High-speed extrusion-compatible collagen formats are displacing natural casings in North American fresh sausage operations where throughput consistency determines supplier selection.
Market Restraints
- Hide supply concentration:Bovine collagen feedstock availability fluctuates with slaughter cycles in Brazil and Argentina, exposing processors to raw material volatility.
- Cellulose peeling limitations:Regenerated cellulose casings require post-cook mechanical removal, adding labor cost and limiting adoption in cook-in-bag applications.
- SAMR compliance friction:China's GB standards for food-contact cellulose create extended approval timelines for imported casing reels, constraining market entry.
Strategic Opportunities
- Plant-based protein convergence:Pea and mycoprotein sausage formats in the Netherlands and UK are testing alginate-collagen hybrid casings for texture replication.
- Direct-to-processor distribution:Spool-to-stuffer supply contracts are bypassing traditional distributor markups for mid-tier US meat processors.
- Carbon accounting integration:EU Green Deal-aligned casing suppliers are embedding Scope 3 emissions data into procurement platforms, capturing sustainability-premium contracts.
Industry Challenges
- Collagen extrusion technician scarcity:Specialized knowledge of viscoelastic flow control in high-yield spinning lines remains concentrated among veteran operators in Spain and Germany.
- Multi-jurisdiction traceability:Slaughter byproduct documentation must satisfy USDA FSIS, EFSA, and SAMR simultaneously, extending compliance timelines for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sausage Casing Market |
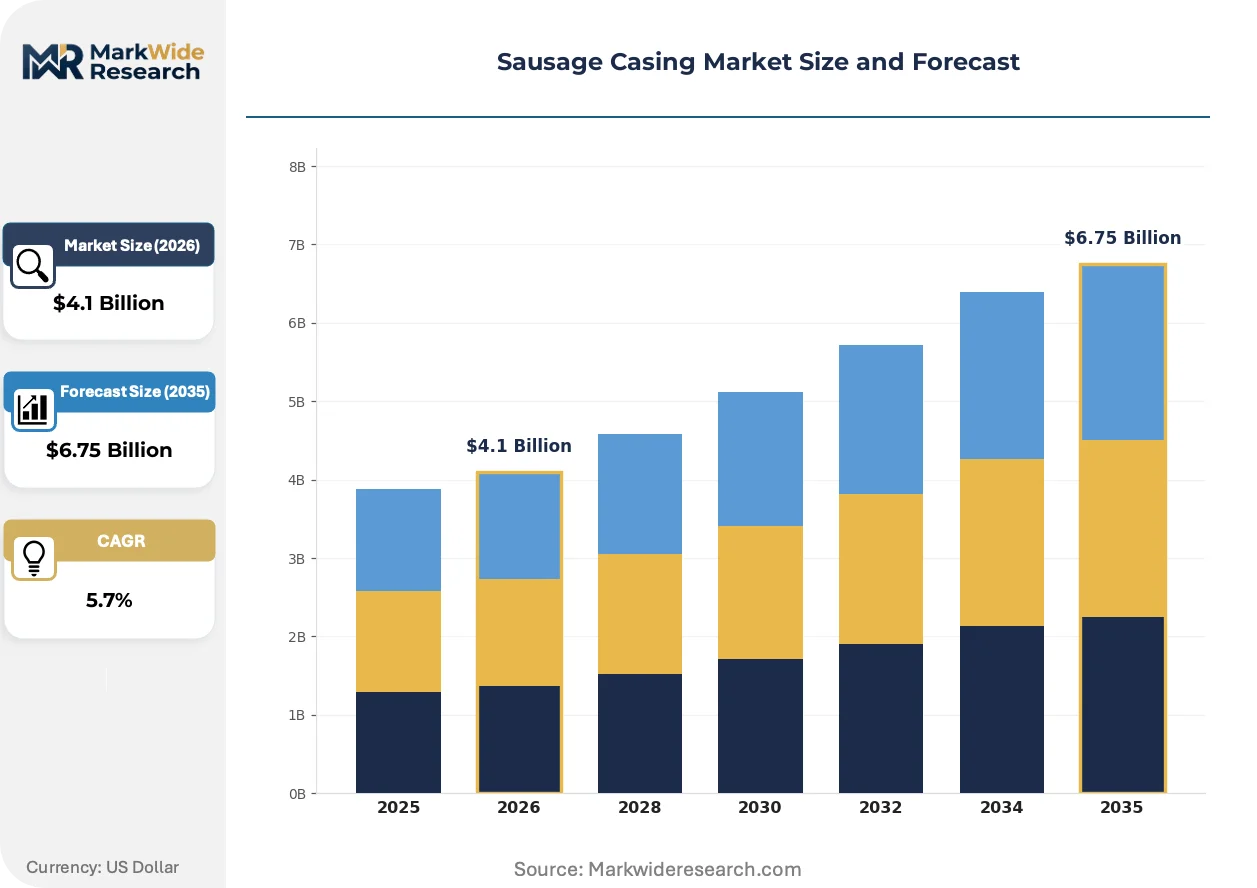
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.75 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Casings, Collagen Casings, Cellulose Casings, Plastic Casings End User: Meat Processors, Restaurants, Retailers, Food Manufacturers Application: Fresh Sausages, Smoked Sausages, Dry Sausages, Cooked Sausages Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Shenguan Holdings (Group), DAT-Schaub Group, Viscofan, ViskoTeepak, Kalle, Viskase Companies, Nitta Casings, Atlantis-Pak, Devro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sausage Casing Market Strategic Shifts
Collagen extraction and extrusion technologies are compressing cost differentials between natural and artificial casings, while regulatory pressure on single-use plastics accelerates material substitution across European protein processing.
Continuous collagen extrusion with controlled fiber alignment is overtaking batch-processed natural casing cleaning in high-volume fresh sausage operations. North American quick-service restaurant suppliers are adopting these formats for diameter uniformity and automated line compatibility. The technology is compressing labor-intensive natural casing procurement in commodity sausage segments.
EFSA's evolving migration limits for regenerated cellulose food-contact substances are tightening purity specifications for imported casing reels. European processors must now demonstrate compliance with updated extraction solvent residue thresholds. German and Polish meat cooperatives are responding by qualifying domestic collagen suppliers to reduce regulatory exposure.
Long-term spool supply contracts with embedded volume commitments are displacing spot-market casing purchases among large-scale processors. This shift locks in supplier relationships and reduces working capital volatility for industrial sausage manufacturers. The pattern is most visible in US Midwest pork processing clusters where processor consolidation has concentrated buying power.
Sausage Casing Market Segmentation
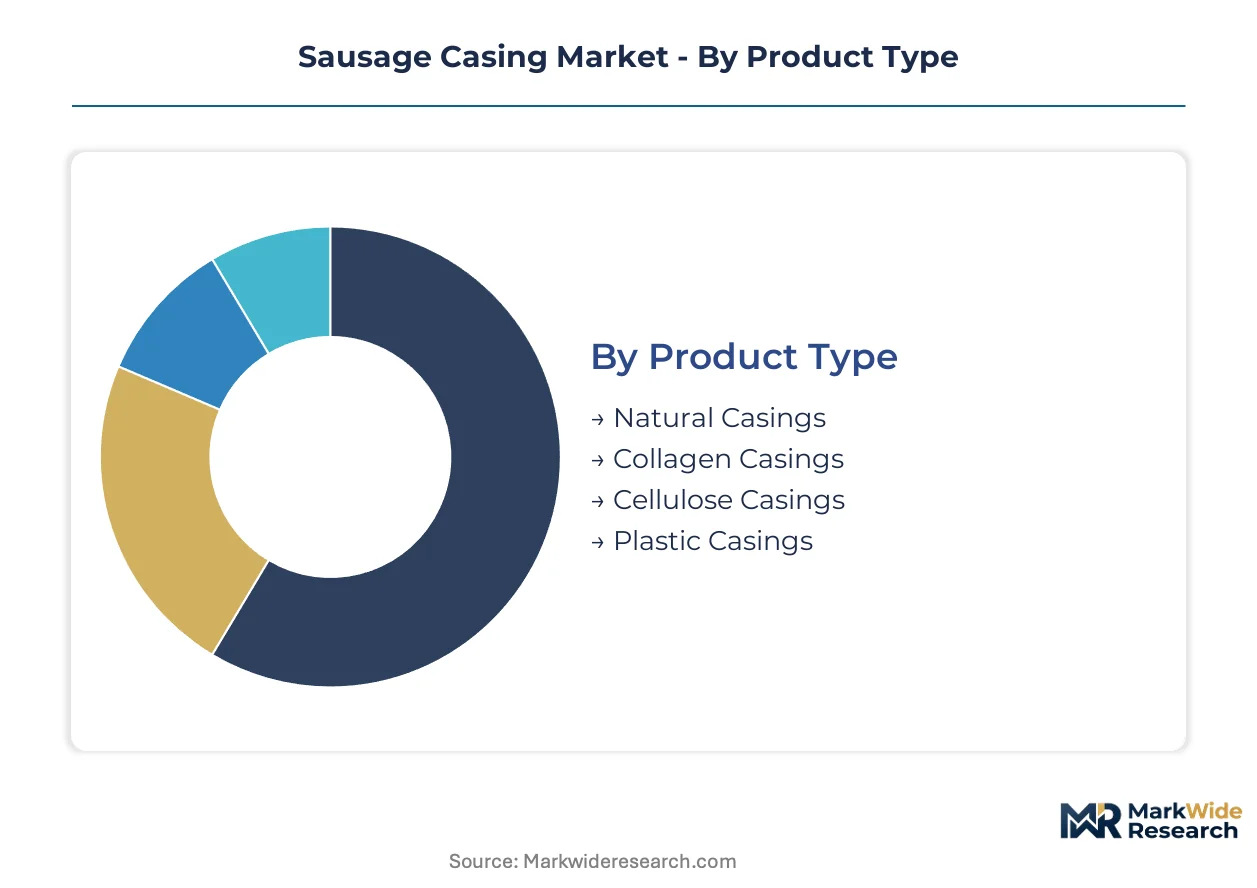
Sausage casing procurement patterns diverge sharply between artisanal processors seeking traditional snap and industrial operators prioritizing automated line speeds. Material selection cascades through diameter consistency requirements, thermal processing protocols, and end-product positioning across retail and foodservice channels.
Product Type:
Equipment upgrade cycles in high-volume fresh sausage operations are accelerating displacement of labor-intensive formats by extrusion-compatible alternatives.
- Collagen Casings:Extruded from bovine hide collagen fibers with controlled fiber alignment, these casings deliver precise diameter uniformity for automated stuffing lines. Demand concentrates in North American pork processing clusters where throughput consistency determines supplier contracts and labor cost reduction drives procurement decisions.
- Natural Casings:Composed of cleaned sheep, hog, or beef intestines, these deliver traditional bite resistance and permeability for dry-cured applications. German and Spanish artisanal sausage traditions sustain premium consumption despite supply fluctuations tied to slaughter volumes and manual cleaning requirements.
- Cellulose Casings:Regenerated cellulose films peel away post-cooking to yield skinless frankfurters. North American quick-service restaurant suppliers favor this format for its compatibility with high-speed thermal processing and mechanical peeling systems.
- Plastic Casings:Food-grade polymer films serve cook-in-bag and barrier-intensive applications where moisture retention and extended shelf life outweigh edibility requirements. EU Packaging and Packaging Waste Regulation mandates are compressing adoption timelines across European meat processing clusters.
Volume placements concentrate in collagen formats; the faster expansion belongs to cellulose alternatives displacing plastic in skinless applications.
End User:
Customer procurement scale determines supply contract structures, with large processors extracting volume commitments while smaller operators rely on distributor intermediaries.
- Meat Processors:Industrial sausage manufacturers operate high-speed extrusion and stuffing lines requiring spool-fed casing formats with diameter tolerances under one millimeter. US Midwest pork processors and German cooperatives dominate procurement volumes through direct-to-manufacturer supply contracts.
- Food Manufacturers:Branded retail sausage producers specify casing performance for specific cooking methods and label claims. Clean-label portfolio expansion across European markets is redirecting procurement toward edible collagen and away from synthetic barrier films.
- Restaurants:Foodservice operators sourcing artisanal and premium sausage formats prioritize natural casing snap for grilled and charcuterie applications. Independent butcher shops and regional restaurant groups in Italy and France sustain niche demand.
- Retailers:Private-label sausage programs at supermarket chains specify casing formats balancing visual appeal with cost control. Centralized procurement teams at German and UK retail banners are consolidating supplier bases to reduce compliance complexity.
Procurement volume aggregates with meat processors; margin capture is climbing fastest among food manufacturers reformulating for clean-label positioning.
Application:
Thermal processing intensity and moisture loss tolerance dictate material selection, with permeable formats serving dry-cured segments and barrier films protecting high-moisture cooked products.
- Fresh Sausages:Uncooked ground meat mixtures requiring breathable casings for refrigerated distribution. Collagen formats dominate North American breakfast sausage and bratwurst production where automated line speeds exceed 500 links per minute.
- Smoked Sausages:Thermal processing with controlled smoke penetration demands casings with calibrated permeability. Polish and Czech meat cooperatives specify natural casings for traditional kielbasa varieties while industrial producers adopt collagen alternatives.
- Dry Sausages:Extended aging with moisture loss requires highly permeable natural casings for salami and pepperoni varieties. Italian and Spanish charcuterie traditions sustain premium natural casing consumption despite higher labor intensity.
- Cooked Sausages:Fully thermal-processed products favor peelable cellulose or barrier plastic casings protecting against post-cook contamination. North American hot dog manufacturers and institutional foodservice suppliers drive standardization in this segment.
Production volume clusters in fresh sausage formats; dry sausage applications command the steepest premium pricing and slowest material substitution.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to casing manufacturing or converting operations.
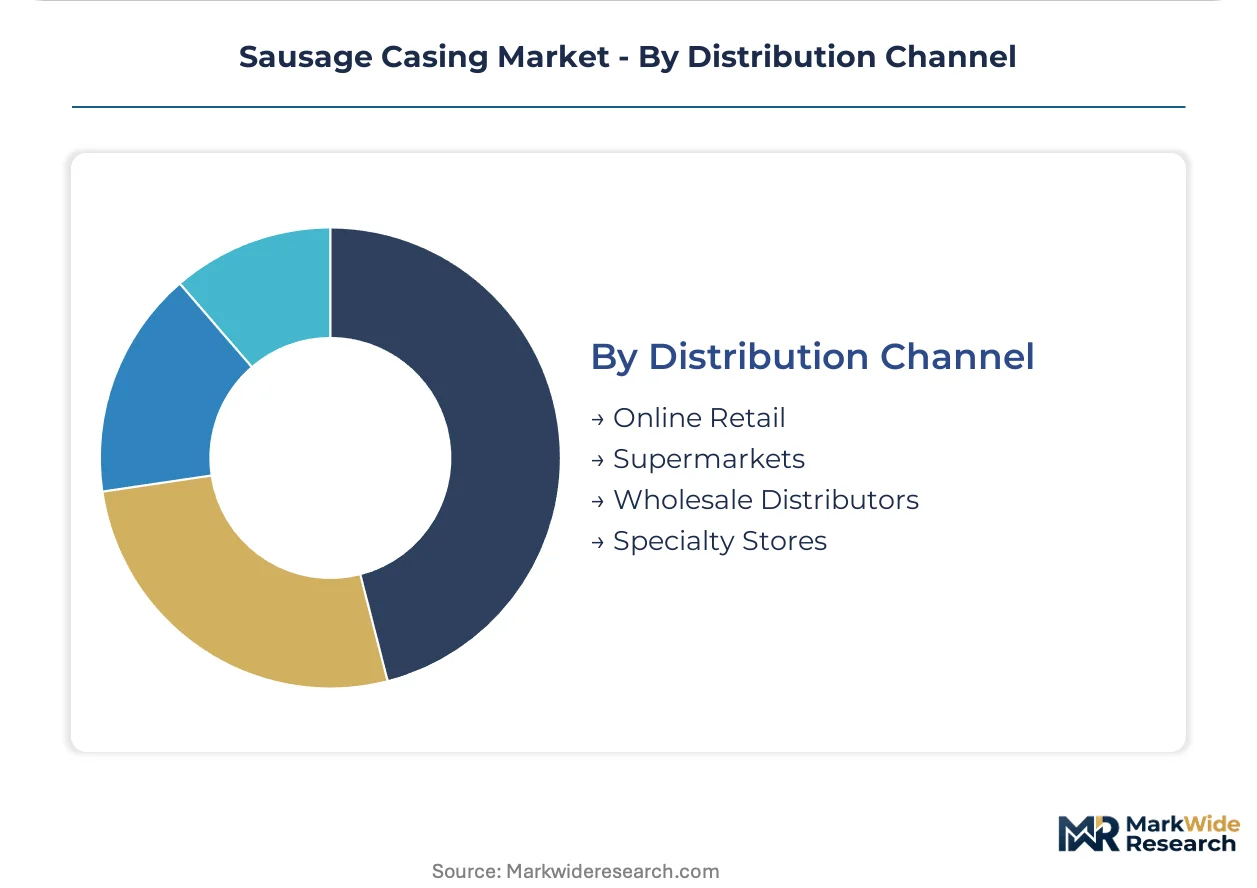
- Wholesale Distributors:Regional intermediaries inventory multiple casing formats for mid-tier processors lacking direct manufacturer relationships. US and German distribution networks maintain technical field service teams for stuffing line troubleshooting.
- Supermarkets:Retail banners with private-label sausage programs procure casings through nominated suppliers integrated with their co-manufacturing networks. UK and French retail consolidation is reducing distributor count per banner.
- Online Retail:E-commerce platforms serve small-scale processors and artisanal producers with low-volume, high-SKU casing requirements. Specialty natural casing varieties for home charcuterie practitioners represent a growing sub-segment.
- Specialty Stores:Butcher supply shops and restaurant equipment dealers stock premium natural casings and collagen varieties for craft processors. Italian and Spanish regional networks sustain this channel for traditional sausage-making communities.
Transaction volume flows through wholesale distributors; channel expansion is accelerating most quickly in direct online procurement serving small-batch producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian and Argentine hide supply corridors anchor collagen feedstock availability for casing manufacturers serving North American and European meat processing clusters. Slaughter cycle volatility in these regions ripples through extrusion capacity planning worldwide.
Germany
Artisanal sausage traditions sustain premium natural casing consumption across Bavarian and Thuringian charcuterie producers. The EU Packaging and Packaging Waste Regulation accelerates procurement shifts toward edible collagen alternatives in industrial processing. Frankfurt and Nuremberg meat cooperatives dominate high-volume fresh sausage output while maintaining heritage dry-cured lines.
United States
Midwest pork processing clusters demand extrusion-compatible collagen formats for automated lines exceeding 500 links per minute. USDA FSIS ingredient standards govern casing approvals alongside FDA food-contact substance notifications. Chicago and Des Moines processors consolidate supplier bases through long-term spool supply contracts with embedded volume commitments.
China
Regenerated cellulose output from cost-optimized plants serves domestic processed-meat segments and export markets. SAMR enforces GB standards for food-contact cellulose, creating compliance friction for imported casing reels. Shandong and Jiangsu provinces concentrate manufacturing capacity for regenerated cellulose food packaging.
Spain
Iberian charcuterie traditions sustain defensible niche demand for slow-release collagen films in dry-cured applications. EFSA evaluates novel extraction processes and migration limits for European market access. Catalonian and Aragonese plants maintain vertical integration from hide sourcing through finished spool distribution.
Netherlands
Pea and mycoprotein sausage formats test alginate-collagen hybrid casings for plant-based protein texture replication. REACH-compliant biopolymer pathways unlock industrial-scale edible casing production with reduced migration risk profiles. Wageningen food technology clusters drive material innovation for alternative protein convergence.
Sausage Casing Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty collagen formats and regional market penetration. The supplier base consolidates around three to five vertically integrated specialists controlling hide-to-spool value chains. Strategic archetypes include hide-integrated extrusion specialists, cellulose regeneration scale players, and natural casing heritage operators. Capacity expansion and backward integration into raw material sourcing represent the dominant competitive moves across major producing regions.
Among European specialists, Viscofan and Devro exemplify contrasting strategic positions within collagen casing supply. Viscofan anchors Iberian and Latin American manufacturing footprints through integrated operations. Devro occupies a position emphasizing slow-release film technologies for premium charcuterie segments. Shenguan Holdings represents cost-optimized regenerated cellulose production targeting volume-competitive Asian markets. These three entities collectively illustrate the geographic and technological segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Shenguan Holdings (Group) |
| DAT-Schaub Group |
| Viscofan |
| ViskoTeepak |
| Kalle |
| Viskase Companies |
| Nitta Casings |
| Atlantis-Pak |
| Devro |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon accounting requirements gate qualified supplier status and premium-tier pricing access for casing manufacturers serving European meat processing clusters. Processors embedding Scope 3 emissions data into procurement platforms capture sustainability-premium contracts while excluding non-compliant competitors from qualified supplier lists.
Pricing Analysis
Technical service bundling separates full-service contracts from unbundled commodity reel sales across the casing market. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Pricing pressure stems from hide supply volatility in Brazil and Argentina compressing margin buffers in collagen extrusion tiers. Mid-tier meat processors exhibit highest price sensitivity due to distributor markup exposure, while consolidated US Midwest pork processors leverage direct spool contracts for cost stability.
Supply Chain Analysis
Bovine hide supply rests on Brazilian and Argentine slaughter corridors anchoring global collagen feedstock availability for extrusion plants. Regenerated cellulose production draws from wood pulp suppliers in China and Southeast Asia, while natural casing cleaning operations concentrate in Germany and Spain. Single-source vulnerability in South American hide supply exposes processors to slaughter cycle fluctuations. Distribution runs through wholesale intermediaries for mid-tier processors, with direct spool-to-stuffer contracts displacing traditional channels among large-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sausage casing market functions as a vertical-integration race where hide-to-spool control determines cost position and supply security. Players pursuing captive raw material sourcing gain insulation from slaughter cycle volatility and regulatory traceability mandates.
For Market Incumbents: Anchor defensible positioning through backward integration into Brazilian and Argentine hide sourcing networks. Devro and Viscofan demonstrate how Iberian and Latin American plant networks reduce feedstock exposure. Incumbents must also lock in long-term spool supply contracts with embedded volume commitments to freeze out emerging cellulose competitors from US Midwest pork processing clusters.
For New Entrants and Emerging Players: Alginate-collagen hybrid casing technology offers a technology-first wedge into plant-based protein convergence segments in the Netherlands and UK. White-space targets include pea and mycoprotein sausage formats seeking texture replication without animal-derived inputs. New entrants should pursue direct-to-processor distribution bypassing traditional distributor markups for mid-tier US meat processors lacking manufacturer relationships.
For Investors and Strategic Acquirers: EFSA migration limit tightening for regenerated cellulose is the leading indicator that domestic European collagen suppliers will capture procurement share from imported reel competitors. Long-term viability favors vertically integrated specialists controlling hide sourcing through finished spool distribution. Investors should monitor SAMR approval timeline extensions for imported cellulose casings as a signal of Chinese market access friction creating acquisition opportunities for domestic producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Sourcing | Brazilian and Argentine slaughter corridor control reduces raw material volatility exposure. |
| Long-term Spool Supply Contracts | Embedded volume commitments with US Midwest pork processors freeze working capital volatility. |
| Alginate-Collagen Hybrid Development | Wageningen food technology clusters drive plant-based protein texture replication for alternative sausage formats. |
| Scope 3 Emissions Data Integration | EU Green Deal alignment captures sustainability-premium procurement contracts from German retail banners. |
| Domestic Collagen Supplier Qualification | EFSA migration limit compliance reduces regulatory exposure for European meat cooperatives. |
Study Parameters
Trade databases, EFSA guidance documents, and USDA FSIS ingredient standards formed the secondary backbone for this analysis. Primary interviews with sausage casing procurement managers at German meat cooperatives, collagen extrusion technicians in Spanish and German plants, and regulatory affairs specialists navigating SAMR compliance supplemented secondary validation. Plant managers at Brazilian hide processing facilities and distribution channel partners in US Midwest pork processing clusters provided operational perspective. Bottom-up casing volume estimates triangulated against top-down meat processing capacity assessments.
Bottom-up modeling anchored forecasts across product type, application, and end-user segmentation dimensions. The projection horizon spans fresh sausage, smoked sausage, dry sausage, and cooked sausage applications with material-specific substitution dynamics. CAGRs derived from extrusion capacity expansion timelines and regulatory substitution mandates. Hide supply concentration in South America and EU Packaging and Packaging Waste Regulation compliance timelines served as key forecast inputs.
Several conditions sit outside the modeled scope, including abrupt slaughter cycle disruptions in Argentina, unilateral SAMR standard revisions, and breakthrough synthetic biology alternatives displacing collagen and cellulose formats. Forecasts reflect documented assumptions about regulatory implementation pacing and protein processor capital expenditure continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Tortilla Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Instant Rice Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Cook-In-Bags Market
Packaged Foods
Freekeh Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
US Packaged Food Market