
 France Motor Insurance Market | 2026-2036
France Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
France Motor Insurance Market Foresight
Fleet operator purchasing is rebalancing toward bundled corporate policies with embedded telematics, pulling premium volume away from fragmented individual driver accounts. Covea leverages its mutualist structure to sustain pricing discipline across regional broker networks. Axa France Iard anchors commercial motor lines through direct corporate partnerships with logistics chains. Macif competes aggressively for young driver segments via digital-first onboarding platforms.
France motor insurance constitutes a risk-transfer contract indemnifying policyholders against financial loss from vehicle damage, theft, bodily injury, or third-party liability, with premiums calibrated via actuarial models incorporating driver history, vehicle type, and geographic risk density. The primary commercial purpose centers on restoring economic position post-loss while satisfying France's mandatory coverage requirements for all registered vehicles. Third-party liability policies dominate premium volume due to legal minimums, yet comprehensive coverage generates superior margins through add-on modules like roadside assistance and legal expenses. Distribution through bancassurance channels captures affluent household segments, while online platforms attract price-sensitive renewals.
France's Autorité de Contrôle Prudentiel et de Résolution enforces solvency ratios and consumer protection standards, while Loi Hamon-mandated portability provisions compress retention cycles and intensify switching behavior. EU Green Deal vehicle-emission targets redirect underwriting focus toward electric motor pools and battery-risk assessments. Stakeholders must monitor regulatory calibration of connected-vehicle data usage for premium personalization.
Market Dynamics
Loi Hamon-mandated portability provisions compress retention cycles and intensify switching behavior across France's motor insurance sector. This regulatory pressure forces insurers to front-load customer acquisition investments while eroding traditional renewal economics.
Growth Catalysts
- Fleet telematics integration:Commercial vehicle operators deploy embedded sensors to capture real-time driving behavior. Insurers leverage this data stream to refine risk segmentation and reduce loss ratios.
- Loi Hamon portability:Mandatory 12-month contract portability empowers consumers to switch providers without penalty. This regulatory framework accelerates competitive pressure on pricing transparency.
- Île-de-France density:Greater Paris concentrates registered vehicles and premium volume. Geographic clustering enables insurers to optimize claims infrastructure and achieve operational scale.
Market Restraints
- Input cost volatility:Vehicle repair costs fluctuate with semiconductor availability and body shop labor rates. Insurers face margin compression when technical inflation outpaces premium adjustments.
- Supply concentration risk:Telematics hardware depends on a limited base of sensor manufacturers. Component bottlenecks delay policy deployment and inflate device procurement costs.
- Technical limitation:Battery degradation assessment for electric vehicles lacks standardized actuarial models. Underwriters struggle to price long-term exposure on emerging powertrain technologies.
Strategic Opportunities
- Underpenetrated Occitania:Rural southern France exhibits lower insurance density per vehicle. Digital distribution platforms reduce cost-to-serve in dispersed populations.
- EU Green Deal alignment:Vehicle-emission targets redirect underwriting focus toward electric motor pools. Battery-risk assessment capabilities differentiate specialist carriers.
- Connected-vehicle data convergence:OEM telematics systems merge with insurer analytics platforms. Real-time risk scoring enables dynamic premium adjustment at policy inception.
Industry Challenges
- Actuarial talent scarcity:Demand for data scientists with automotive risk expertise exceeds supply. Insurers compete with fintech and technology sectors for quantitative modeling skills.
- Legacy system integration:Core policy administration platforms require costly modernization to support API-driven telematics ingestion. Migration timelines extend 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Motor Insurance Market |
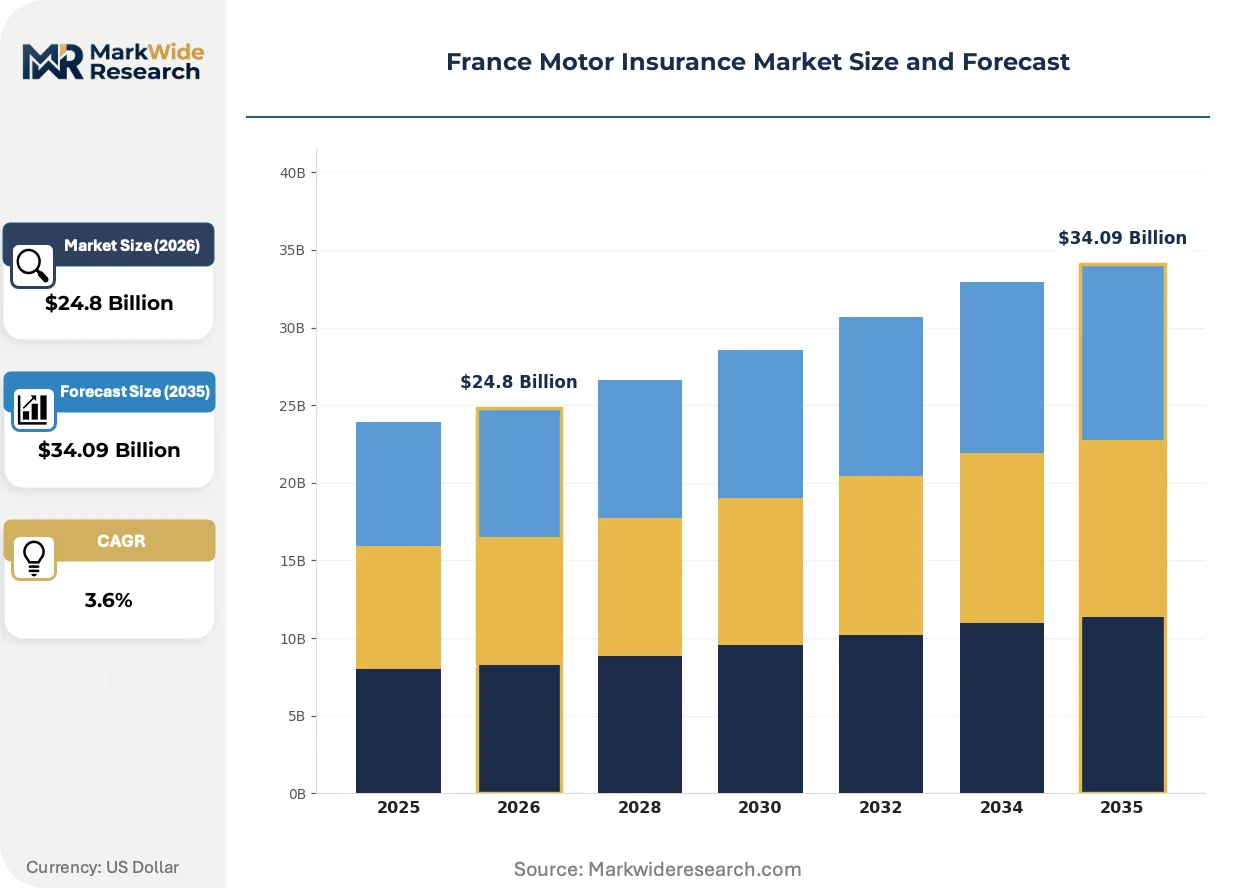
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $34.09 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third-Party Liability, Third-Party Fire & Theft, Personal Accident, Legal Expenses Coverage Type: Collision, Theft, Natural Disasters, Vandalism, Medical Payments, Roadside Assistance Customer Type: Individual Drivers, Fleet Operators, Car Rentals, Corporate Clients, Ride-Sharing Providers Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Bancassurance, Agent Networks |
| Companies Covered | Covea, Axa France Iard, Macif, Allianz Vie, Generali Iard, Predica Prevoyance Dialogue du Credit Agricole S.A., Groupama, Groupe Matmut, Gmf Assurances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Motor Insurance Market Shifts & Advancements
Telematics-enabled usage-based insurance is restructuring how French carriers acquire, price, and retain policyholders. Three interconnected developments are accelerating this transformation.
Usage-based insurance platforms are decentralizing risk assessment from annual policy reviews to continuous monitoring. Young driver segments adopt smartphone-enabled mileage tracking fastest. Real-time feedback loops compress the traditional actuarial cycle into dynamic premium adjustments.
Autorité de Contrôle Prudentiel et de Résolution guidelines on connected-vehicle data governance impose strict consent and retention protocols. Insurers must rearchitect data pipelines to comply with consumer protection mandates. Commercial motor lines face the steepest compliance costs due to fleet-scale data volumes.
French households increasingly unbundle insurance from vehicle purchase decisions. Digital comparison platforms capture price-sensitive renewals that bancassurance channels previously dominated. This channel rotation concentrates in urban centers where smartphone penetration and digital literacy peak.
France Motor Insurance Market Segmentation
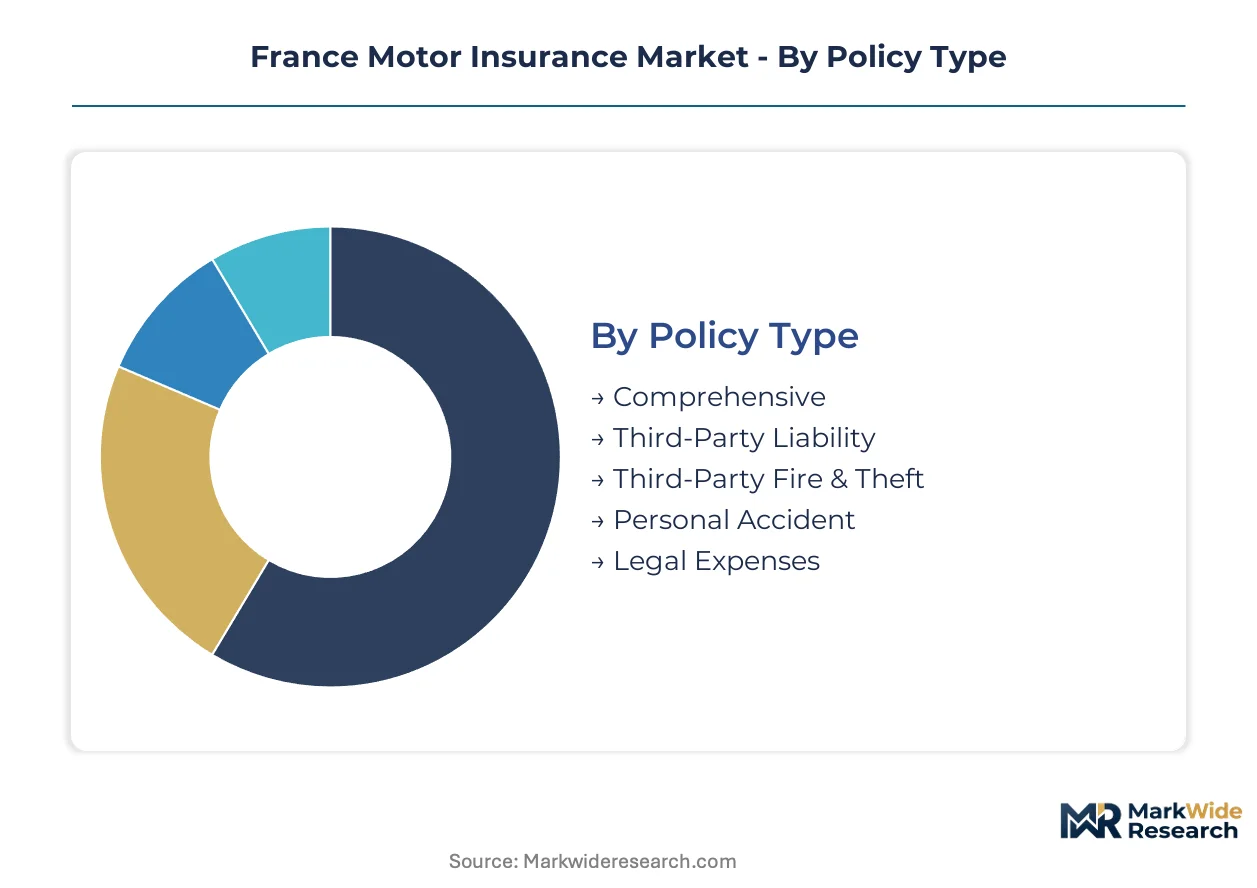
Segmentation in France motor insurance determines pricing precision, distribution economics, and regulatory compliance obligations. Each dimension—policy structure, risk coverage, customer profile, and channel—creates distinct operational requirements for carriers underwriting risks across metropolitan and rural territories.
Policy Type:
Standalone policies dominate personal lines, while embedded corporate contracts absorb fleet risks through master agreements.
- Comprehensive:Bundles third-party liability with own-damage coverage for collision, theft, and natural perils. Demand clusters among new vehicle purchasers in Île-de-France, where higher asset values justify premium outlays for full protection.
- Third-Party Liability:Mandatory minimum coverage satisfying France's Code des Assurances requirements. Volume concentrates in used-vehicle segments and budget-conscious households in peripheral regions where premium sensitivity peaks.
- Third-Party Fire & Theft:Intermediate tier covering liability plus fire and theft losses while excluding collision damage. Appeals to vehicle owners in Occitania seeking balanced protection without comprehensive pricing.
- Personal Accident:Rider policy extending medical and disability benefits to drivers and passengers. Corporate clients embed this coverage within fleet master contracts to satisfy workplace safety obligations.
- Legal Expenses:Accessory coverage funding litigation costs for traffic disputes and liability claims. Ride-sharing providers mandate this add-on to shield drivers from contractual disputes with platforms.
Volume placements concentrate in Third-Party Liability; the faster expansion belongs to Comprehensive.
Coverage Type:
Cost-tier stratification separates essential protections from premium add-ons that carriers use to lift margins.
- Collision:Own-damage protection for at-fault accidents and single-vehicle incidents. Fleet operators in logistics corridors around Lyon and Marseille negotiate fleet-scale collision deductibles to control premium leakage.
- Theft:Indemnity for vehicle theft and attempted theft damage. Urban policyholders in Greater Paris exhibit elevated take-up rates reflecting higher theft incidence in dense parking environments.
- Natural Disasters:Coverage for flood, storm, and hail damage under France's Cat Nat regime. Southern coastal regions drive demand where Mediterranean weather patterns intensify property risk.
- Vandalism:Protection against malicious damage excluding theft. Young driver segments in university cities show disproportionate claim frequency on this coverage.
- Medical Payments:Reimbursement of healthcare costs for accident-related injuries. Integration with France's Sécurité Sociale system limits standalone demand outside corporate benefit structures.
- Roadside Assistance:Breakdown recovery and emergency services. Electric vehicle owners prioritize this coverage given immature charging infrastructure and battery-related immobilization risks.
Collision and Theft absorb the premium mass; Roadside Assistance is climbing the fastest as electrification spreads.
Customer Type:
Customer maturity separates price-sensitive individual purchasers from sophisticated corporate buyers with risk management departments.
- Individual Drivers:Personal vehicle owners purchasing single-policy coverage through broker or direct channels. Digital comparison platforms capture switching behavior among this segment following Loi Hamon portability activation.
- Fleet Operators:Commercial vehicle owners managing 10+ units under master policies. Telematics integration enables these buyers to negotiate experience-rated premiums based on aggregated driving data.
- Car Rentals:Short-term vehicle lessors requiring blanket coverage for rotating vehicle pools. Loss ratio volatility plagues this segment due to renter unfamiliarity with vehicle handling.
- Corporate Clients:Non-transportation businesses maintaining company vehicle fleets for executive and sales mobility. These buyers demand seamless integration with existing property and liability programs.
- Ride-Sharing Providers:Platform-mediated drivers requiring hybrid personal-commercial coverage. Regulatory ambiguity around driver employment status complicates policy structuring for this emerging segment.
Individual Drivers retain volume dominance; Ride-Sharing Providers show the steepest expansion trajectory despite underwriting complexity.
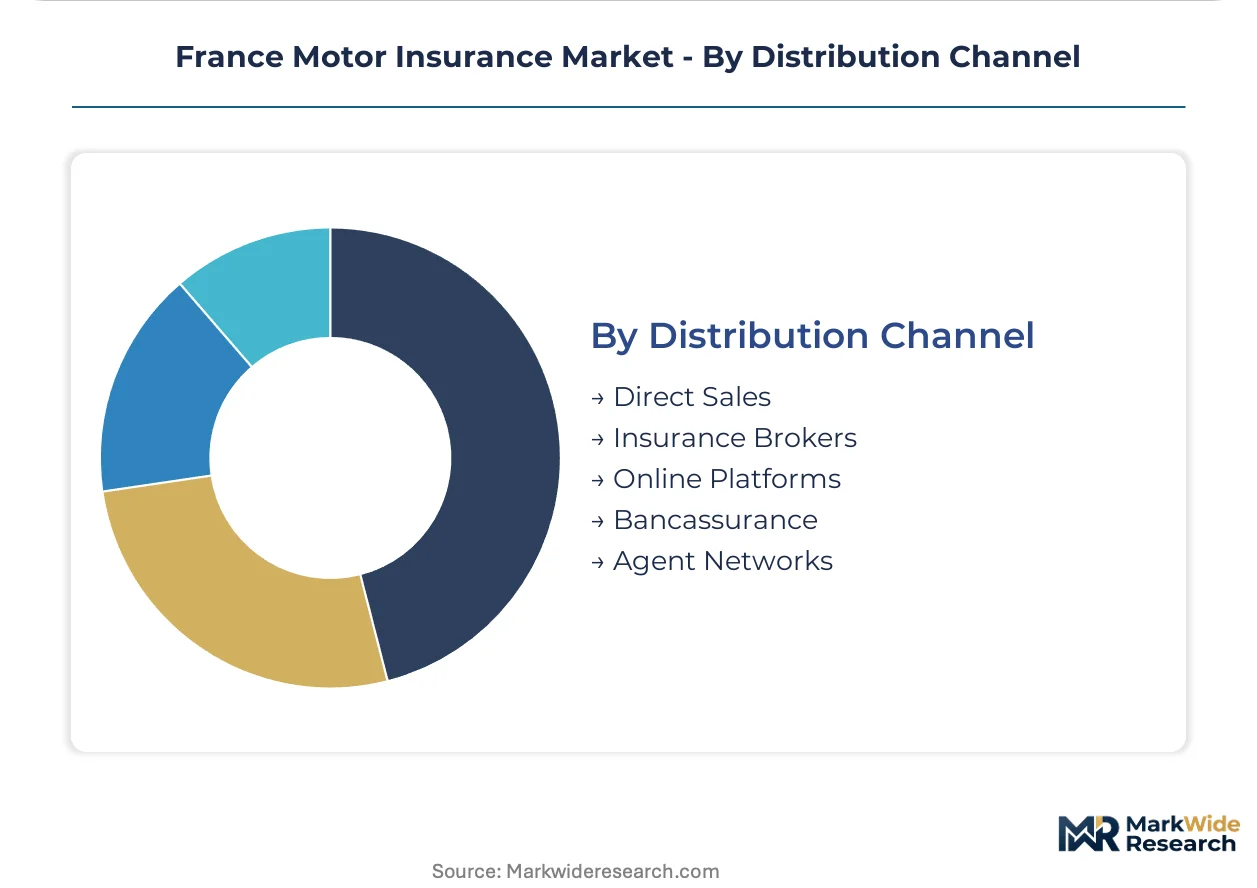
Distribution Channel:
Channel economics determine acquisition cost and customer lifetime value through differential servicing intensity.
- Direct Sales:Carrier-owned channels including call centers and proprietary websites. Axa France Iard and Covéa deploy direct infrastructure to capture renewal economics without broker commission load.
- Insurance Brokers:Independent intermediaries advising on coverage selection and claims advocacy. Regional broker networks in Brittany and Normandy maintain durable relationships with agricultural and small commercial clients.
- Online Platforms:Digital aggregators enabling price comparison and instant policy binding. Urban millennials in Paris, Lyon, and Bordeaux drive adoption where smartphone penetration enables seamless digital journeys.
- Bancassurance:Insurance distribution through banking networks leveraging customer deposit relationships. Affluent households with mortgage and investment products exhibit elevated cross-sell receptivity in this channel.
- Agent Networks:Tied representatives exclusive to single carriers. Macif's mutualist agent structure sustains member loyalty through local presence in mid-sized cities.
Insurance Brokers and Bancassurance split the incumbent volume; Online Platforms are gaining share fastest as digital literacy diffuses beyond metropolitan cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan France's motor insurance density concentrates where vehicle registration volumes and premium purchasing power align most tightly.
Île-de-France
Greater Paris anchors national premium volume through concentrated vehicle ownership and elevated asset values. The Autorité de Contrôle Prudentiel et de Résolution maintains strict solvency oversight for carriers operating in this high-exposure zone. La Défense and inner-ring suburbs host broker networks serving corporate fleet accounts with embedded telematics requirements.
Auvergne-Rhône-Alpes
Lyon and Grenoble drive commercial motor demand through logistics corridors connecting Alpine freight routes to Mediterranean ports. Regional prefectures enforce EU Green Deal vehicle-emission standards that redirect underwriting toward electric commercial pools. Saint-Étienne's manufacturing heritage sustains mid-sized fleet operators negotiating experience-rated premiums.
Provence-Alpes-Côte d'Azur
Marseille and Nice exhibit elevated theft claim frequency that compresses margins on comprehensive coverage. Mediterranean weather patterns intensify natural disaster exposure under France's Cat Nat regime. Aix-en-Provence clusters affluent households purchasing bundled motor-property coverage through bancassurance channels.
Hauts-de-France
Lille and the Belgian border corridor concentrate cross-border commercial vehicle traffic requiring harmonized liability coverage. Regional economic development agencies incentivize fleet modernization through telematics adoption grants. Dunkirk's port infrastructure anchors heavy goods vehicle insurance pools with specialized cargo-liability riders.
Occitanie
Toulouse and Montpellier present underpenetrated rural markets where digital distribution reduces cost-to-serve. The Loi Hamon portability mandate accelerates price-sensitive switching among dispersed agricultural vehicle owners. Perpignan's proximity to Spanish border traffic creates niche demand for international motor coverage extensions.
France Motor Insurance Market Competitive Landscape
Established mutualist insurers occupy the standard tier; emerging digital-first entrants pursue direct-to-consumer distribution and telematics-enabled pricing. The market structure reflects moderate consolidation around heritage mutual networks balanced against accelerating online platform competition. Three archetypes dominate: mutualist cooperatives with regional broker ties, integrated bancassurance operators, and direct-writing specialists leveraging proprietary data assets. Competitive moves concentrate on telematics partnership formation and legacy system modernization to support real-time premium adjustment.
Within the mutualist tier, Covea and Macif exemplify cooperative structures sustaining member loyalty through local agent presence. Axa France Iard anchors the integrated carrier segment with direct corporate capabilities. These three names represent distinct strategic positions without implying specific operational metrics or market share claims.
| Leading Market Players |
|---|
| Covea |
| Axa France Iard |
| Macif |
| Allianz Vie |
| Generali Iard |
| Predica Prevoyance Dialogue du Credit Agricole S.A. |
| Groupama |
| Groupe Matmut |
| Gmf Assurances |
| Others |
Supply & Pricing Matrix
Mutualist cooperatives with century-old regional broker networks anchor supply-side discipline in France motor insurance, translating localized risk knowledge into tiered premium structures that resist price erosion. Their member-owned capital structure limits aggressive pricing wars, while Loi Hamon-mandated portability forces simultaneous investment in retention technology and acquisition infrastructure.
Pricing Analysis
Volume concentrates in mandatory third-party liability policies where thin margins compress carrier economics, while comprehensive coverage with embedded telematics modules generates superior profitability. Price differentiation rests on driving history granularity and geographic risk density, with Île-de-France policyholders absorbing elevated premiums reflecting theft frequency and collision incidence. Cost compression in the standard tier intensifies because repair labor inflation outpaces technical rate filings. Price-sensitive individual drivers in Occitania and peripheral regions drive switching behavior through digital comparison platforms, whereas fleet operators with telematics-negotiated experience rates exhibit lower elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese telematics hardware manufacturers supplying embedded sensors for usage-based insurance deployment. The ecosystem draws from Taiwanese semiconductor foundries for device processing units, French cloud infrastructure for data analytics pipelines, and domestic body shop networks for claims fulfillment. Tariff exposure on connected-vehicle components threatens margin stability as EU-China trade frictions escalate. Distribution runs through regional broker networks in Brittany and Normandy, direct carrier platforms in metropolitan cores, and bancassurance channels capturing affluent cross-sell opportunities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France motor insurance constitutes a consolidation play where Loi Hamon portability and telematics capital requirements squeeze subscale mutualists into defensive mergers or runoff. Weaker players lacking real-time data infrastructure face irreversible policyholder attrition.
For Market Incumbents: Lock in fleet operator relationships through exclusive telematics partnerships before digital entrants capture commercial lines. Covea and Axa France Iard should accelerate API integration with OEM connected-vehicle platforms to preempt standalone sensor procurement. Defensive consolidation of regional broker networks in Occitania and Hauts-de-France preserves distribution control against online platform erosion. For New Entrants and Emerging Players: Digital-native aggregators represent the most penetrable channel partner type for white-space expansion. Target underpenetrated rural Occitania with smartphone-enabled mileage tracking for agricultural vehicle owners. Pursue ride-sharing platform partnerships to structure hybrid personal-commercial coverage before regulatory clarity solidifies incumbent advantage. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized mutualists with intact regional broker networks in southern France. Long-term viability hinges on telematics data assets and Loi Hamon compliance infrastructure rather than legacy policy reserves. Monitor Autorité de Contrôle Prudentiel et de Résolution solvency intervention filings as the inflection signal for forced consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | OEM data partnerships with Stellantis and Renault enable real-time risk scoring at policy inception. |
| Regional Broker Network Consolidation | Acquiring independent intermediaries in Occitania reduces cost-to-serve in dispersed populations. |
| Electric Vehicle Battery Risk Assessment | Specialized underwriting capabilities differentiate carriers as EU Green Deal accelerates fleet electrification. |
| Direct Digital Channel Expansion | Proprietary platforms capture Loi Hamon switching behavior without commission load to intermediaries. |
| Legacy System Modernization | API-driven policy administration supports telematics ingestion and dynamic premium adjustment cycles. |
Research Methodology
Independent corroboration across primary interviews with motor insurance actuaries, fleet risk managers, and regional broker principals underwrites the qualitative findings. Secondary validation incorporated Autorité de Contrôle Prudentiel et de Résolution solvency filings, EU Green Deal regulatory texts, and French vehicle registration databases. Bottom-up segmentation modeling triangulated against top-down premium volume estimates from bancassurance and direct channel disclosures.
Comparable-period anchoring established baseline retention and loss ratio patterns before projecting across the analysis window. The quantitative framework modeled policy type, customer maturity, distribution channel, and regional risk density as core segmentation dimensions. CAGRs derived from actuarial trend extrapolation incorporating telematics adoption curves and Loi Hamon switching elasticity estimates.
Caveats apply where semiconductor supply disruptions, battery degradation model uncertainty, or regulatory recalibration of connected-vehicle data governance could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market