
 New Energy Car Insurance Market | 2026-2036
New Energy Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Car Insurance Market Insights
Multi-source data partnerships between automakers and underwriters is restructuring how actuarial risk gets priced into new energy vehicle policies. Allianz SE leverages its European motor-fleet expertise to anchor specialized battery-degradation coverage products. Ping An Group sustains dominance in Chinese new energy insurance through integrated telematics and claims automation. Progressive Corporation differentiates via usage-based pricing models calibrated to real-time battery health monitoring.
New energy car insurance constitutes specialized underwriting coverage for battery-electric, plug-in hybrid, and fuel-cell vehicles, incorporating actuarial models that weight battery state-of-health, thermal management system integrity, and high-voltage component failure rates against traditional mechanical risk pools. Its primary commercial purpose centers on transferring financial liability for catastrophic battery failure, charging infrastructure damage, and technology-specific depreciation curves from vehicle owners to risk-pooling institutions. Comprehensive coverage leads policy value generation due to bundled battery-replacement riders, while fleet-oriented policyholder categories represent the fastest-growing risk pool as commercial electrification accelerates. Distribution through embedded insurance at point-of-sale and mobile app platforms is capturing margin from disintermediated broker channels.
China's SAMR oversees mandatory new energy vehicle insurance filing requirements, while the NMPA enforces battery safety testing protocols that directly inform underwriting standards. The EU AI Act and GDPR constrain telematics data deployment in European pricing models, creating compliance cost layers for cross-border carriers. Stakeholders must monitor how regulator-mandated battery traceability requirements in multiple jurisdictions reshape claims verification workflows and reserve calculations.
Market Dynamics
Battery thermal runaway risk quantification is forcing actuarial recalculation across underwriting portfolios as NMPA certification mandates tighten testing protocols for lithium-ion cell integrity.
Growth Catalysts
- Fleet electrification mandates:Logistics operators in Germany and California face binding zero-emission vehicle procurement rules that expand commercial policy volumes.
- GB standards evolution:China's updated new energy vehicle safety frameworks create compliance-driven demand for certified coverage riders.
- Telematics integration:Real-time battery health monitoring systems enable usage-based premium calibration that attracts price-sensitive private buyers.
Market Restraints
- Lithium price volatility:Cathode material cost swings compress repair-cost predictability and inflate loss-ratio uncertainty for underwriters.
- Cell manufacturer concentration:Supply bottlenecks at dominant Chinese battery producers delay claims settlement timelines and parts availability.
- GDPR data friction:EU restrictions on telematics deployment limit granular risk segmentation and cross-border policy portability.
Strategic Opportunities
- Second-life battery coverage:Stationary energy storage applications create aftermarket liability products for degraded automotive packs.
- Embedded insurance channels:Point-of-sale distribution through OEM financing arms captures margin from traditional broker networks.
- India's FAME subsidy extension:Central government electric vehicle incentives expand addressable vehicle stock for specialized underwriting.
Industry Challenges
- Actuarial data scarcity:Limited historical loss experience for solid-state chemistries complicates reserve adequacy calculations.
- High-voltage technician certification:Repair network capacity constraints extend claim cycle times and inflate loss-adjustment expenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Car Insurance Market |
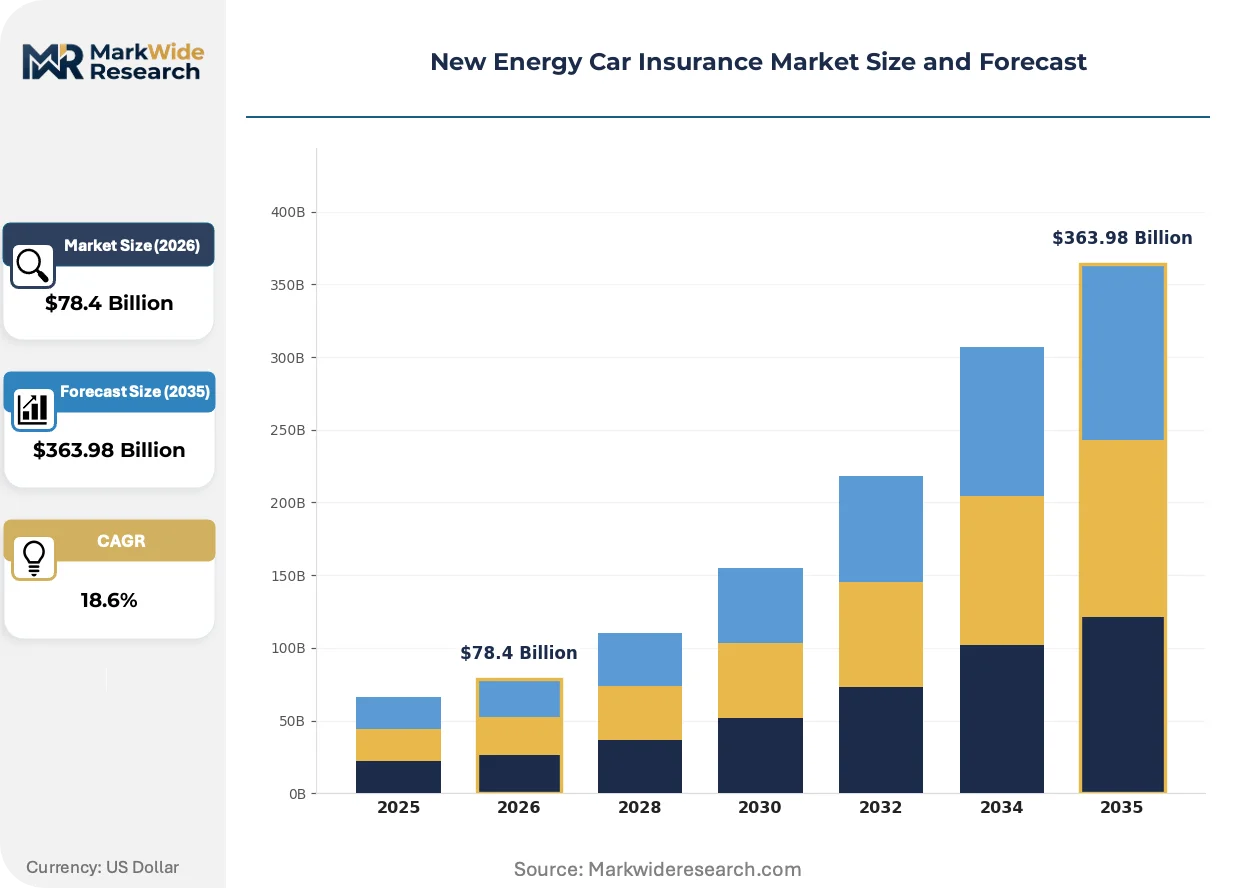
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $363.98 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Third-Party Liability, Comprehensive Coverage, Collision Coverage, Personal Injury Protection, Uninsured Motorist Policyholder Category: Private Vehicle Owners, Fleet Operators, Corporate Clients, Ride-Hailing Drivers, Leasing Companies Coverage Scope: Battery Damage, Theft Protection, Fire and Explosion, Natural Disasters, Mechanical Breakdown Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Mobile Apps, Bancassurance |
| Companies Covered | AXA, Liberty Mutual Group, Allianz SE, State Farm Mutual Automobile Insurance Company, Ping An Group, Progressive Corporation, Zurich Insurance Group, The Allstate Corporation, Tokio Marine Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Car Insurance Market Trends and Innovations
Digital risk assessment infrastructure is consolidating around multi-source data architectures that merge vehicle telemetry, battery diagnostics, and charging behavior into unified underwriting engines.
AI-powered predictive maintenance platforms are consolidating fragmented battery health data streams into single risk scores that underwriters embed directly into dynamic premium algorithms. Fleet managers at ride-hailing operators adopt these tools fastest, compressing traditional annual policy cycles into monthly adjustments. The technology is consolidating actuarial functions previously handled by separate mechanical and electrical risk teams.
China's SAMR filing requirements for new energy vehicle insurance products mandate standardized battery degradation disclosure that reshapes product design timelines. Domestic carriers must submit thermal runaway scenario modeling before policy approval, extending development cycles. Commercial fleet underwriters absorb these compliance costs most heavily, passing portions through to logistics policyholders.
Buyers increasingly demand unbundled coverage components that separate battery replacement riders from traditional collision protection. Direct-to-consumer mobile platforms capture this preference shift, disintermediating agent-driven distribution in urban Chinese markets. Shanghai and Shenzhen policyholders lead this behavioral pivot, accelerating channel restructuring among domestic insurers.
New Energy Car Insurance Market Segmentation
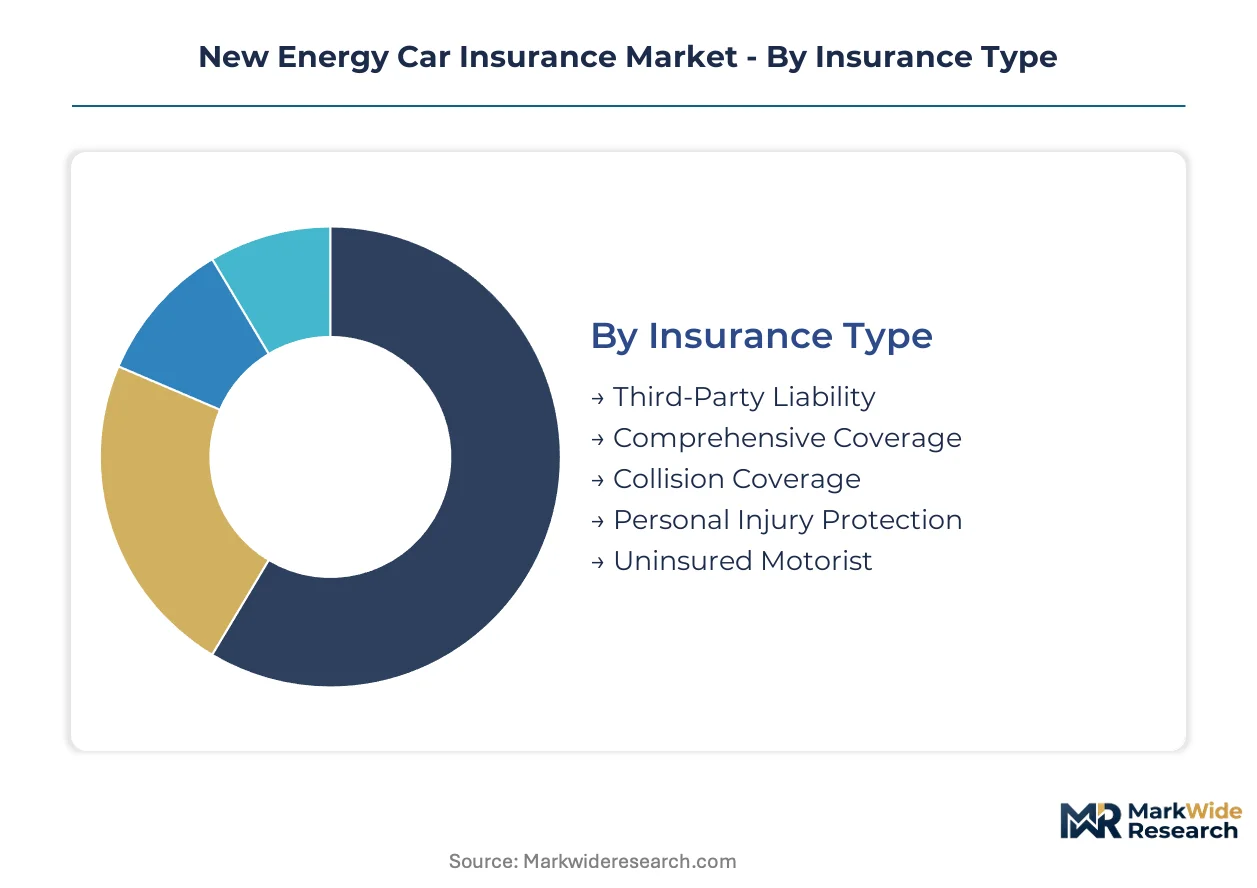
Segmentation in new energy car insurance determines how actuarial risk pools align with technology-specific liabilities. Battery thermal runaway and degradation curves demand coverage structures that diverge sharply from internal-combustion vehicle policies.
Insurance Type:
Standalone products dominate high-liability exposures, while bundled riders integrate with base automotive coverage.
- Third-Party Liability:Mandatory coverage addressing bodily injury and property damage to external parties. Fleet operators in Germany absorb rising premiums as KBA mandates tighten zero-emission vehicle certification requirements.
- Comprehensive Coverage:Bundles collision, theft, and battery-specific riders into unified policies. Private owners in Shenzhen and Shanghai favor this structure for integrated battery-replacement protection.
- Collision Coverage:Damage to policyholder vehicles from accidents regardless of fault.
- Personal Injury Protection:Medical expenses and lost wages for occupants.
- Uninsured Motorist:Protection when at-fault parties lack adequate coverage.
Volume placements concentrate in Comprehensive Coverage; the faster expansion belongs to Third-Party Liability as fleet mandates proliferate.
Policyholder Category:
Cost-tier segmentation separates high-volume standardized underwriting from bespoke commercial risk engineering.
- Fleet Operators:Logistics and ride-hailing fleets require scheduled vehicle coverage with centralized claims management. California's binding zero-emission procurement rules expand commercial policy volumes fastest.
- Private Vehicle Owners:Individual buyers seeking personal-use coverage with telematics-linked pricing. Chinese first-time NEV buyers in lower-tier cities drive mobile-app distribution adoption.
- Corporate Clients:Multi-vehicle entities with centralized procurement and risk management functions.
- Ride-Hailing Drivers:Gig-economy operators needing flexible, short-term coverage structures.
- Leasing Companies:Asset holders requiring residual value protection and damage waiver products.
Margin concentration sits with Fleet Operators; steepest expansion trajectory belongs to Ride-Hailing Drivers as platform-mediated coverage proliferates.
Coverage Scope:
Application-specific modules address where electrified powertrains introduce novel loss categories absent from conventional automotive risk.
- Battery Damage:Core coverage for cell degradation, thermal runaway, and replacement costs. SAMR filing requirements in China mandate standardized degradation disclosure, extending product development timelines.
- Fire and Explosion:Catastrophic failure protection addressing lithium-ion thermal propagation. NMPA certification protocols for cell integrity directly inform underwriting standards and reserve calculations.
- Theft Protection:Vehicle and component theft including high-voltage system targeting.
- Natural Disasters:Flood, earthquake, and weather-related damage to electrified systems.
- Mechanical Breakdown:Non-collision failures of electric drivetrain components.
Pricing power clusters in Battery Damage; gaining share fastest is Fire and Explosion as thermal runaway modeling matures.
Distribution Channel:
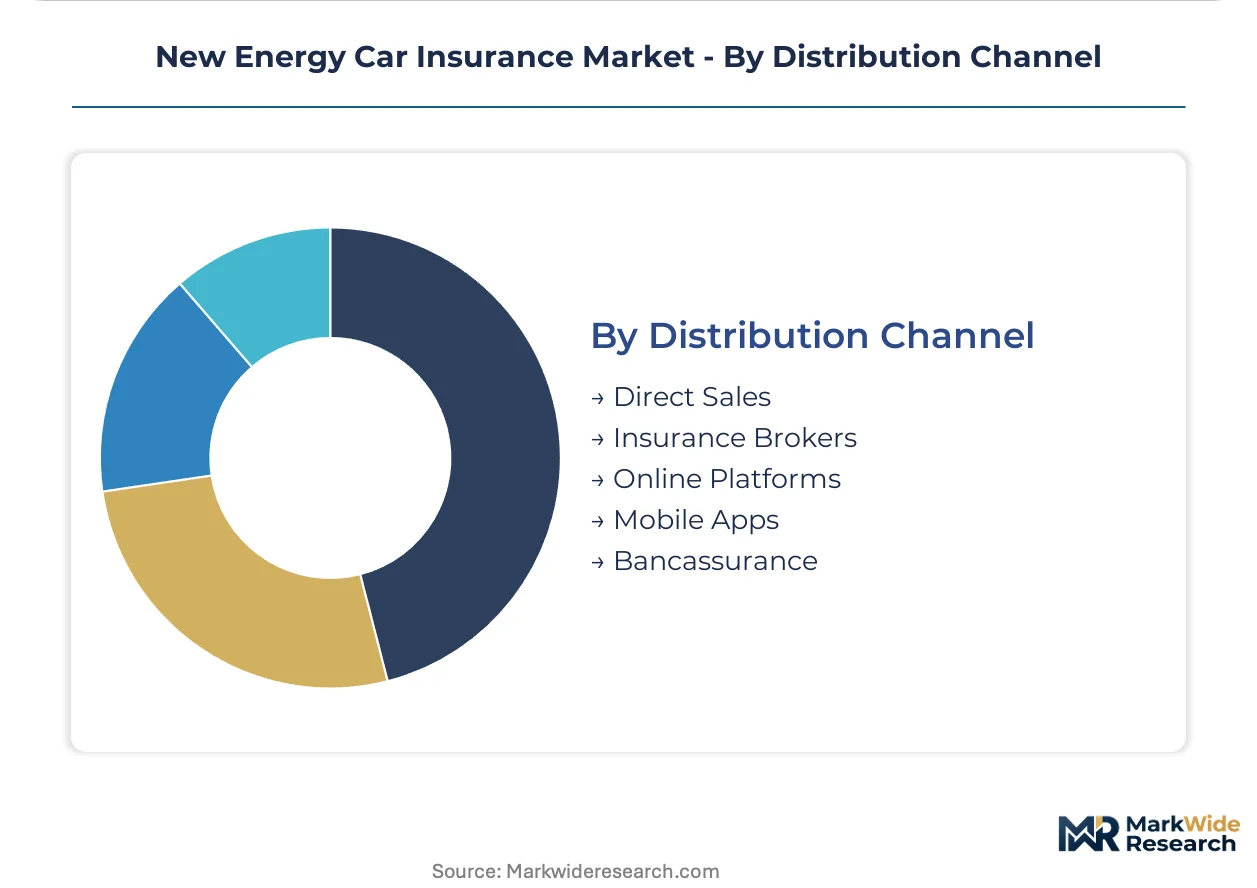
Customer-type segmentation tracks how embedded point-of-sale capture displaces traditional intermediary relationships.
- Online Platforms:Direct-to-consumer digital marketplaces enabling unbundled coverage selection. Urban Chinese buyers in Guangzhou and Beijing pivot fastest to self-directed policy configuration.
- Mobile Apps:Telematics-integrated distribution with real-time premium adjustment. Ping An and domestic carriers leverage usage-based pricing to attract price-sensitive segments.
- Direct Sales:Insurer-controlled channels bypassing intermediaries.
- Insurance Brokers:Independent advisors serving complex commercial placements.
- Bancassurance:Financial institution partnerships embedding coverage with auto financing.
Commission compression hits Insurance Brokers hardest; channel expansion concentrates in Mobile Apps as OEM-integrated distribution scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over half of global new energy vehicle insurance demand, with domestic carriers and joint ventures building dedicated actuarial frameworks for battery degradation and thermal runaway liabilities. European markets follow with specialized coverage for fleet electrification mandates, while North American insurers calibrate usage-based models to real-time battery health monitoring.
China
Fleet operators across logistics and ride-hailing sectors are expanding coverage procurement as electrified vehicle fleets scale. SAMR filing requirements mandate standardized battery degradation disclosure, extending product development timelines for domestic carriers. Shanghai and Shenzhen policyholders lead adoption of unbundled coverage components, accelerating channel restructuring toward mobile-app distribution.
Germany
Logistics operators face binding zero-emission vehicle procurement rules that expand commercial policy volumes fastest in Europe. KBA mandates tighten certification requirements for zero-emission vehicle fleets, reshaping underwriting standards. Munich and Stuttgart anchor the concentration of specialized battery-degradation coverage products from European motor-fleet experts.
United States
California's binding zero-emission procurement rules drive commercial policy expansion, while usage-based pricing models attract price-sensitive private buyers. NHTSA safety protocols inform underwriting standards for high-voltage system integrity. Silicon Valley telematics providers and Detroit legacy carriers compete to embed real-time battery health monitoring into premium calibration.
Japan
Corporate fleet clients demand residual value protection and damage waiver products for electrified commercial vehicles. METI standards for battery traceability reshape claims verification workflows and reserve calculations. Tokyo and Osaka metropolitan areas concentrate underwriting innovation for solid-state battery chemistries with limited historical loss experience.
India
Central government electric vehicle incentives under FAME subsidy extension expand addressable vehicle stock for specialized underwriting. The country's national automotive regulator enforces evolving safety frameworks that create compliance-driven demand for certified coverage riders. Maharashtra and Karnataka lead sub-regional concentration of mobile-app distribution adoption among first-time NEV buyers.
New Energy Car Insurance Market Competitive Landscape
Strategic partnerships dominate the current landscape as carriers merge telematics capabilities with battery diagnostics expertise. The vendor base clusters around three tiers: global multi-line insurers with dedicated NEV divisions, domestic Chinese carriers leveraging integrated data ecosystems, and technology-forward specialists in usage-based pricing. Two strategic archetypes define competitive positioning: telematics-integrated platforms capturing margin from disintermediated broker channels, and fleet-focused underwriters anchoring commercial electrification mandates. M&A activity concentrates on data analytics acquisitions, while geographic expansion through joint ventures targets high-growth Asian markets.
Within the telematics-integrated tier, Ping An Group and Progressive Corporation exemplify carriers embedding real-time battery health monitoring into dynamic premium algorithms. Allianz SE represents the European motor-fleet expertise archetype, anchoring specialized coverage products for battery degradation. These three occupy positions across distinct geographic and technological vectors, with Ping An sustaining dominance in Chinese new energy insurance, Progressive differentiating via usage-based models, and Allianz leveraging continental fleet expertise.
| Leading Market Players |
|---|
| AXA |
| Liberty Mutual Group |
| Allianz SE |
| State Farm Mutual Automobile Insurance Company |
| Ping An Group |
| Progressive Corporation |
| Zurich Insurance Group |
| The Allstate Corporation |
| Tokio Marine Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified battery supply and premium-tier pricing access for new energy car insurance carriers, as NMPA-certified thermal runaway testing becomes a mandatory filter for underwriting authority. Fleet operators absorbing compliance-driven product development costs pass portions through to policyholders, while uncertified competitors face margin compression in standard coverage tiers.
Pricing Analysis
Volume placements concentrate in standard comprehensive coverage, while margin capture belongs to premium battery-degradation riders with certified thermal management backing. Price differentiation hinges on NMPA certification tier and telematics integration depth, with uncertified carriers facing pricing pressure from SAMR-mandated disclosure requirements. Fleet operators show lowest price sensitivity due to binding zero-emission procurement rules, while private owners in lower-tier Chinese cities drive mobile-app price competition.
Supply Chain Analysis
Direct-to-OEM embedded insurance channels handle hyperscale fleet demand, bypassing traditional broker networks. Cell supply concentrates in China, South Korea, and Japan, with lithium carbonate and cathode active materials as critical input dependencies. Single-source vulnerability at dominant Chinese battery producers creates claims settlement bottlenecks. Distribution runs through OEM financing arms, mobile-app platforms, and bancassurance partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage technician scarcity props pricing power for carriers with in-house repair networks, constraining supply expansion faster than fleet electrification mandates expand addressable risk pools.
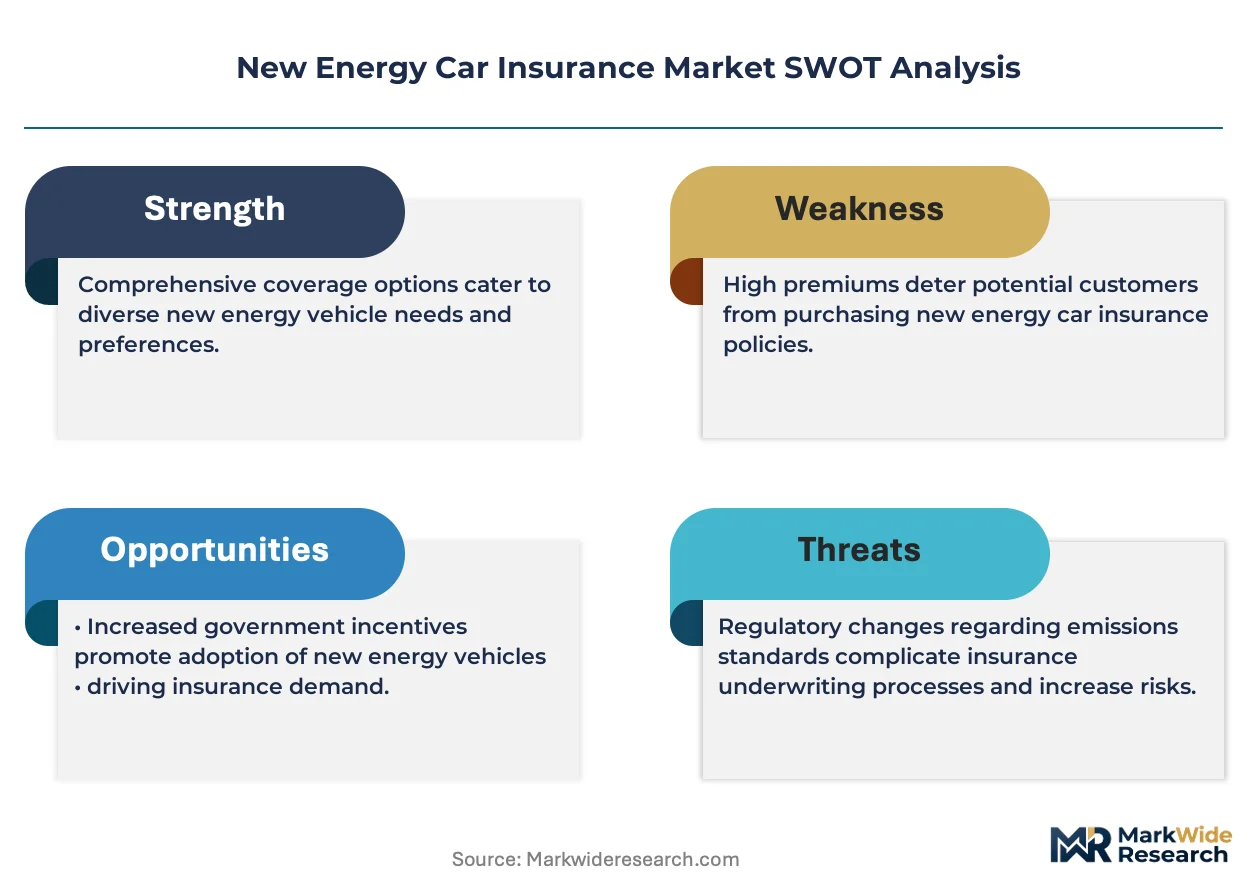
For Market Incumbents: Cement telematics-data exclusivity through OEM partnership lock-ins before battery-health monitoring commoditizes. Acquire specialized high-voltage technician training capacity to compress claim cycle times. Vertical integration into repair networks defends margin against independent service channel encroachment. For New Entrants and Emerging Players: Second-life battery coverage for stationary energy storage represents an underserved buyer archetype with limited incumbent presence. Target India's FAME-subsidized first-time NEV buyers through mobile-native distribution. Embedded point-of-sale partnerships with regional financing arms offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: SAMR filing requirement expansion is the leading indicator that compliance infrastructure will separate viable carriers from distressed exits. Long-term viability favors acquirers of telematics-integrated platforms with battery-diagnostic data moats. Watch for NMPA certification backlogs as the signal that technical underwriting capacity is tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time battery health monitoring enables dynamic premium calibration for usage-based products. |
| High-Voltage Technician Certification Program | In-house repair capacity compresses claim cycle times and reduces loss-adjustment expenses. |
| OEM Embedded Insurance Partnership | Point-of-sale distribution captures margin from disintermediated traditional broker channels. |
| Second-Life Battery Coverage Launch | Stationary storage applications create aftermarket liability products for degraded automotive packs. |
| Regulatory Compliance Infrastructure Investment | SAMR filing and NMPA certification capabilities extend product development timelines for competitors. |
Research Methodology
Document review covered regulatory filings from SAMR and NMPA, complemented by interviews with chief underwriting officers at domestic Chinese carriers, fleet risk managers at logistics operators, telematics platform engineers, and claims adjustment specialists. Secondary sources included vehicle production databases, insurance regulatory disclosures, and battery safety testing protocols. Bottom-up policy volume estimates triangulated against top-down fleet electrification mandate projections.
Historical claims experience cross-referenced against expert panel input on solid-state chemistry loss patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included insurance type, policyholder category, coverage scope, and distribution channel complexity. CAGRs derived from actuarial reserve growth trajectories and fleet procurement schedule acceleration, with battery degradation curves and thermal runaway frequency as industry-specific inputs.
Revisions become necessary when NMPA certification protocols tighten, lithium price volatility disrupts repair cost predictability, or GDPR enforcement shifts constrain telematics deployment in European markets. Forecasts reflect assumptions about regulatory stability and cell manufacturer capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market