
 United Arab Emirates Motor Insurance Market | 2026-2036
United Arab Emirates Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Motor Insurance Market Analytics
UAE Insurance Authority capital adequacy rules is pivoting the cost-of-entry calculus for new market participants. Abu Dhabi National Insurance Company leverages its bancassurance partnerships to sustain premium flow across the northern emirates. Emirates Insurance Company anchors its position through direct corporate fleet relationships with logistics operators. Sukoon Insurance differentiates via takaful-compliant product structures that appeal to sharia-conscious vehicle owners.
United Arab Emirates motor insurance constitutes risk-transfer contracts indemnifying policyholders against financial loss from vehicle damage, theft, or third-party liability, with premiums calibrated via actuarial models incorporating vehicle age, driver history, and territorial risk coefficients. Its primary commercial purpose is to satisfy mandatory coverage requirements while offering optional asset protection for individual and commercial vehicle owners. Comprehensive policies command the deepest premium pools due to broader peril coverage and higher attachment points. Fleet operator segments generate recurring volume with lower acquisition costs than individual channels. Online platforms represent the fastest-growing distribution vector as digital onboarding reduces policy issuance friction.
UAE Central Bank prudential regulations and MOHAP health coverage coordination standards shape product design, mandating minimum bodily injury limits and claims settlement timelines. ISO 9001 quality management and UAE-specific takaful governance frameworks further constrain operating models for conventional and Islamic insurers alike. Stakeholders must monitor telematics data ownership disputes and evolving autonomous vehicle liability frameworks as these will determine next-generation product architectures and pricing granularity.
Market Dynamics
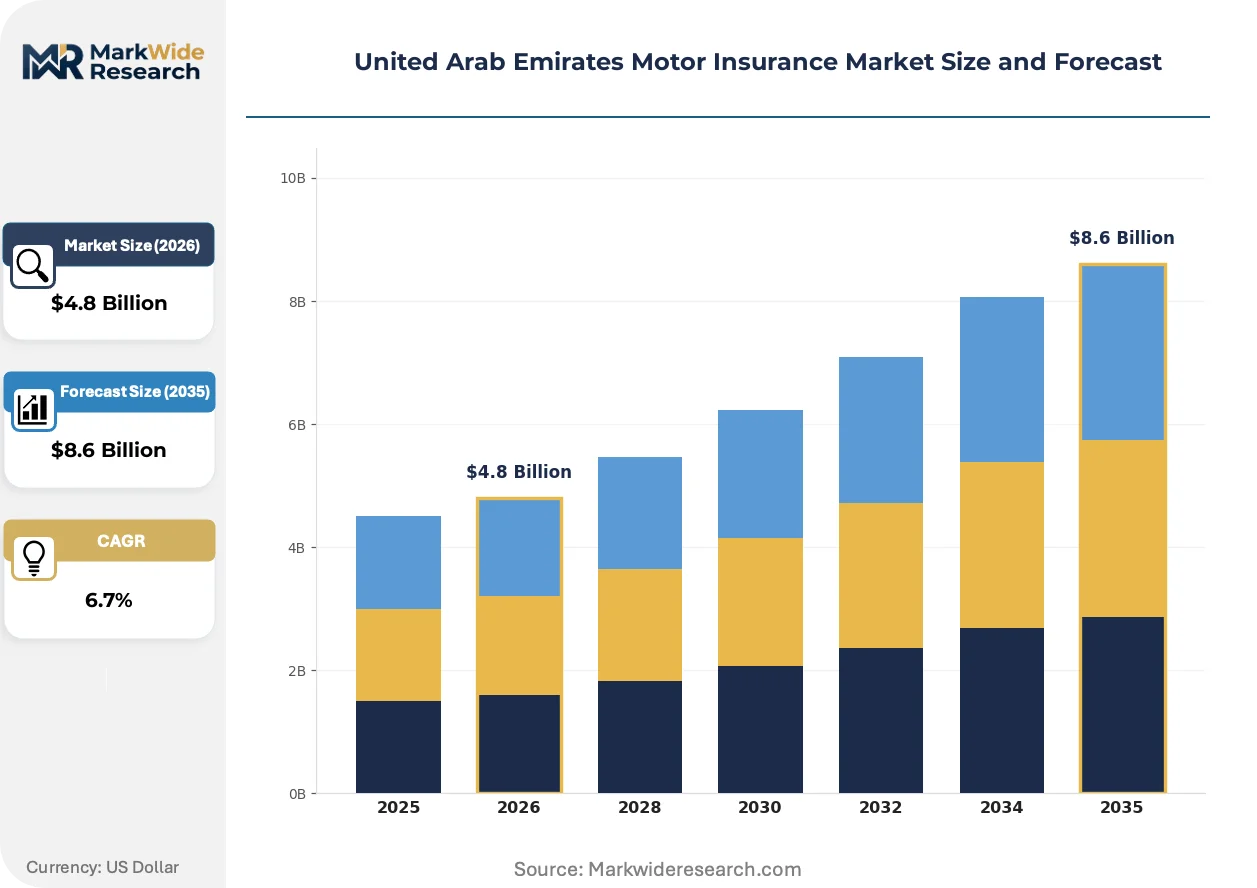
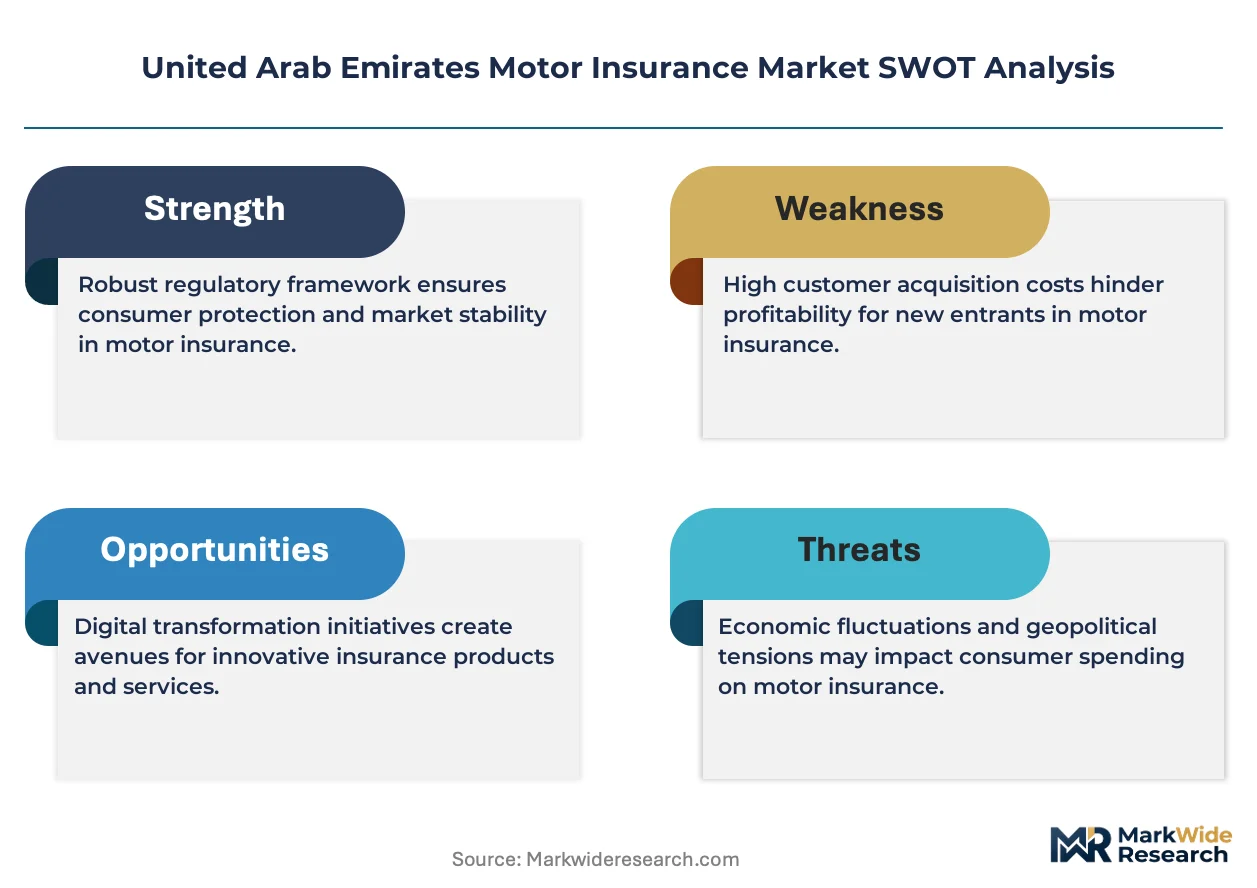
UAE Central Bank's 2023 insurance capital adequacy framework is compressing underwriting capacity for smaller insurers while accelerating consolidation among established players with stronger balance sheets.
Growth Catalysts
- Fleet expansion mandates:Logistics operators in Dubai and Abu Dhabi are extending coverage requirements to contractor vehicles, broadening the addressable policy base beyond owned fleets.
- ISO 9001 quality certification:Mandatory quality management standards for claims processing are reducing settlement friction and improving policyholder retention rates.
- Telematics penetration:Usage-based insurance platforms are enabling dynamic premium calibration that rewards low-risk driving behavior with immediate cost reductions.
Market Restraints
- Actuarial data scarcity:Limited historical claims databases for electric vehicles and autonomous systems inflate uncertainty margins in premium pricing models.
- Reinsurance capacity concentration:Regional catastrophe bond markets remain underdeveloped, forcing UAE underwriters to rely on London and Singapore markets for peak risk transfer.
- Third-party liability caps:MOHAP-mandated bodily injury minimums create asymmetric exposure where medical cost inflation outpaces premium adjustment mechanisms.
Strategic Opportunities
- Northern emirates penetration:Ras Al Khaimah and Fujairah exhibit lower insurance density per registered vehicle, offering first-mover advantages for digital-native distributors.
- Takaful product innovation:Sharia-compliant structures are capturing premium flow from religiously observant vehicle owners underserved by conventional product architectures.
- Embedded insurance integration:Automotive dealerships and ride-hailing platforms represent captive distribution channels with conversion rates exceeding traditional broker networks.
Industry Challenges
- Telematics data ownership disputes:Insurers, vehicle manufacturers, and platform operators contest control over driving behavior datasets essential for risk segmentation.
- Legacy core system integration:Incumbent underwriters face technical debt burdens when connecting traditional policy administration platforms to real-time data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Motor Insurance Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third-Party Liability, Collision, Additionally Insured Customer Type: Individual Owners, Fleet Operators, Corporate Clients, Leasing Companies Coverage Type: Bodily Injury, Property Damage, Personal Injury Protection, Uninsured Motorist Distribution Channel: Direct Sales, Brokers, Online Platforms, Banks |
| Companies Covered | Assicurazioni Generali S.P.A., Emirates Insurance Company, Sukoon Insurance, Watania Takaful, GIG Gulf, Orient Insurance PJSC, National General Insurance Co. (P.S.C), Islamic Arab Insurance Company, Abu Dhabi National Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Motor Insurance Market Evolving Landscape
Digital distribution infrastructure is compressing policy issuance cycles from days to minutes, while regulatory pressure on capital reserves is forcing product architecture innovation across the underwriting value chain.
Usage-based insurance platforms leveraging onboard diagnostics and smartphone telemetry are modularizing risk assessment workflows. Fleet operators in Abu Dhabi are adopting these systems fastest, with logistics companies leading deployment. Real-time data ingestion is modularizing traditional annual premium cycles into adjustable monthly or per-kilometer structures that align cost exposure with actual vehicle utilization.
UAE Central Bank's updated solvency requirements are tightening capital reserve ratios for motor liability exposures. Smaller underwriters face portfolio restructuring pressure to maintain compliance without sacrificing market presence. Takaful operators report particular adaptation challenges as profit-sharing mechanisms complicate reserve calculation methodologies under the new prudential standards.
Direct digital onboarding is displacing traditional broker intermediation for individual policyholders. Price comparison platforms and insurer-owned mobile applications now capture the majority of new policy issuance in Dubai and Sharjah. Younger vehicle owners demonstrate strongest channel preference shifts, with after-sales service bundling emerging as a retention mechanism for digitally acquired customers.
United Arab Emirates Motor Insurance Market Segmentation
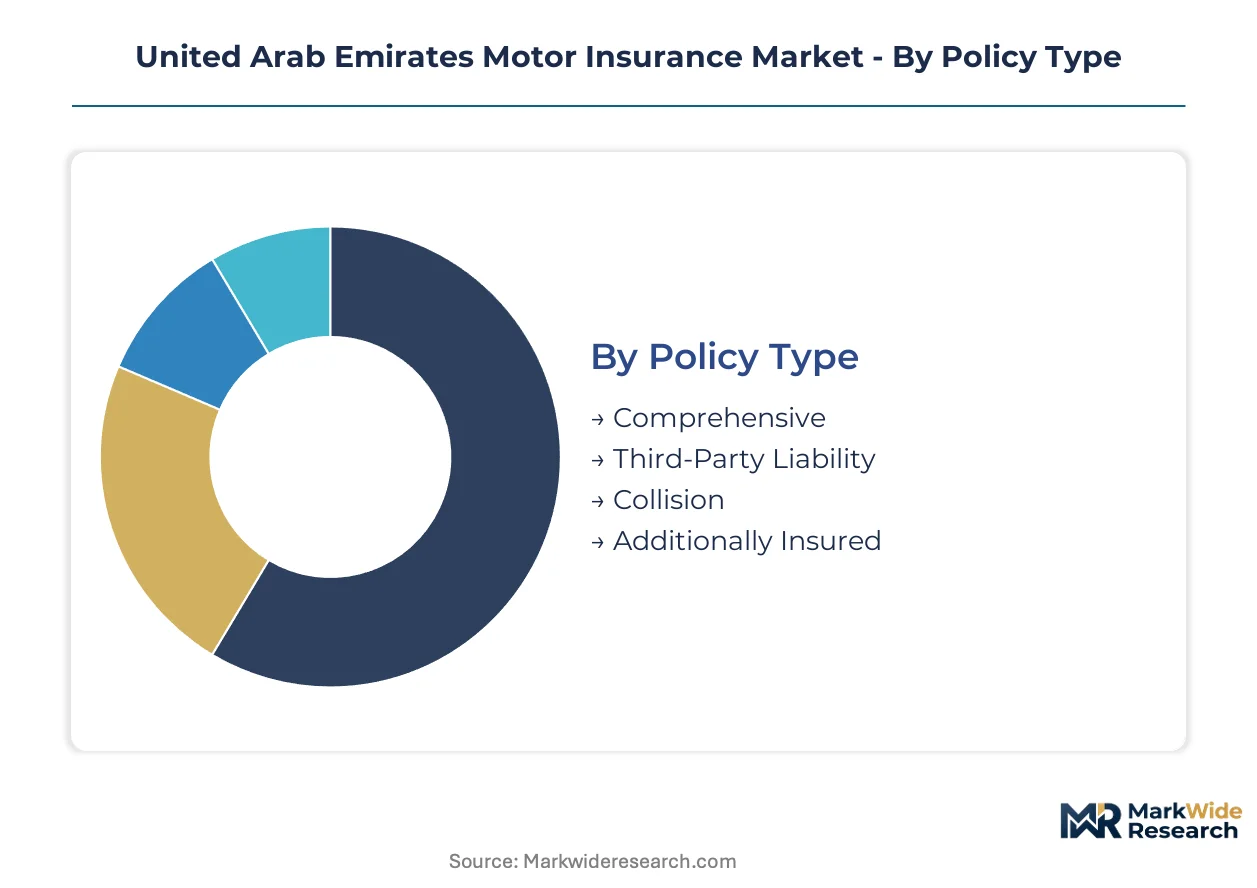
Motor insurance segmentation in the UAE reflects divergent risk profiles between mandatory liability coverage and asset protection products. Premium concentration varies sharply across customer types, with fleet operators generating recurring volume at lower acquisition costs than individual channels.
Policy Type:
Comprehensive policies command premium multiples of third-party coverage, while liability-only products dominate policy count.
- Comprehensive:Full-spectrum coverage indemnifying against own-vehicle damage, theft, fire, and third-party liability through single-contract structures. Dubai and Abu Dhabi corporate fleets concentrate demand here, driven by asset protection requirements for high-value commercial vehicles and mandatory coverage escalation clauses in logistics contracts.
- Third-Party Liability:Minimum legal coverage satisfying UAE Central Bank mandates for bodily injury and property damage to third parties. Individual vehicle owners in Sharjah and northern emirates drive volume, constrained by premium sensitivity and regulatory minimum thresholds that compress insurer margins.
- Collision:Named-peril coverage limited to vehicle-to-vehicle impact damage, excluding theft, weather, or vandalism losses. Leasing companies favor this tiered structure to reduce premium outlay while satisfying contractual asset protection minimums.
- Additionally Insured:Extension endorsements adding named drivers, territorial expansion, or specialized equipment coverage to base policies. Rental car operators and cross-border logistics fleets generate demand for UAE-Oman-Saudi territorial extensions.
Mature deployment sits with Third-Party Liability. Newer deployment is concentrated in Comprehensive.
Customer Type:
Commercial accounts deliver superior retention economics despite higher per-policy servicing complexity.
- Fleet Operators:Multi-vehicle accounts with centralized policy administration, claims coordination, and loss control programs. Abu Dhabi logistics corridors anchor demand, with telematics integration accelerating as fuel subsidy reforms tighten operating cost management.
- Individual Owners:Single-vehicle policyholders purchasing through digital channels or broker intermediation. Dubai's young professional demographic exhibits strongest price elasticity, with comparison platform usage displacing traditional agency relationships.
- Corporate Clients:Non-fleet commercial entities insuring executive vehicles, service vans, and employee transportation assets. Healthcare and construction sectors in Al Ain and Ras Al Khaimah generate consistent renewal flow through bundled risk management contracts.
- Leasing Companies:Captive finance subsidiaries and independent lessors requiring blanket coverage across residual-value vehicle portfolios. Sharjah's automotive finance cluster concentrates this segment, with Islamic leasing structures demanding takaful-compliant product adaptations.
Profitability concentrates with Fleet Operators. Volume expansion is fastest among Individual Owners.
Coverage Type:
Medical cost inflation is reshaping bodily injury limit adequacy across all policy architectures.
- Bodily Injury:Liability coverage for medical expenses, disability, and death benefits arising from at-fault accidents. MOHAP-mandated minimums in Dubai and Abu Dhabi now require higher attachment points as hospital cost inflation outpaces statutory adjustment mechanisms.
- Property Damage:Third-party vehicle and infrastructure repair or replacement indemnification. Luxury vehicle density on Sheikh Zayed Road corridors elevates severity exposure, compressing loss ratios for underwriters with inadequate reinsurance structures.
- Personal Injury Protection:First-party medical coverage regardless of fault determination, including passenger and pedestrian extensions. Corporate wellness programs in Dubai International Financial Centre are driving adoption as employee benefit differentiators.
- Uninsured Motorist:Protection against losses caused by non-compliant or unidentified vehicles, critical given enforcement gaps in northern emirates. Ras Al Khaimah and Fujairah policyholders exhibit highest take-up rates due to cross-border traffic patterns and documentation variability.
Regulatory pressure is intensifying around Bodily Injury. Product innovation is concentrating in Personal Injury Protection.
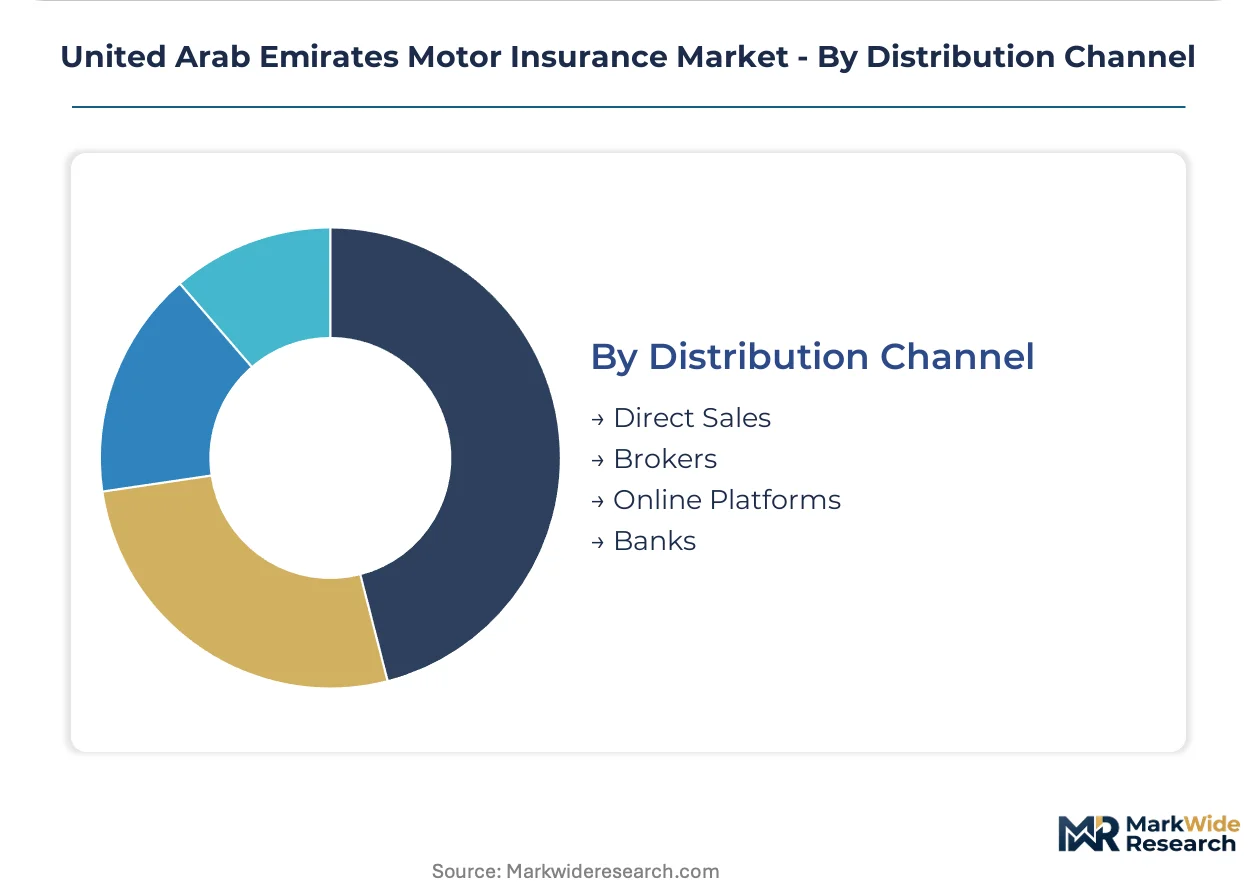
Distribution Channel:
Digital onboarding is compressing policy issuance cycles while eroding traditional broker economics.
- Online Platforms:Direct-to-consumer websites and mobile applications with real-time quotation, document upload, and payment integration. Dubai and Sharjah urban demographics exhibit complete channel preference shifts, with price transparency engines driving commoditization pressure.
- Brokers:Independent intermediaries providing coverage comparison, claims advocacy, and risk advisory services. Complex commercial accounts in Abu Dhabi sustain broker relevance despite margin compression in personal lines.
- Direct Sales:Insurer-employed agents and branch networks serving relationship-driven corporate accounts. Emirates Insurance Company and Abu Dhabi National Insurance Company maintain captive sales forces for flagship fleet relationships.
- Banks:Bancassurance partnerships embedding motor coverage within auto loan origination and credit card benefit programs. UAE Central Bank capital rules are constraining non-core insurance activities, reshaping commission structures and exclusivity arrangements.
Established infrastructure dominates through Banks. Channel migration is steepest toward Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Financial Centre and Abu Dhabi Global Market anchor motor insurance underwriting concentration through tax-advantaged licensing frameworks that attract regional headquarters of multinational carriers.
Dubai
Logistics operators along Sheikh Zayed Road corridors drive comprehensive policy demand for high-value commercial fleets. UAE Central Bank capital adequacy rules compress underwriting capacity for smaller insurers while accelerating consolidation among established players with stronger balance sheets. Dubai's young professional demographic exhibits strongest price elasticity, with comparison platform usage displacing traditional agency relationships.
Abu Dhabi
Corporate fleet relationships with logistics operators generate recurring premium volume at lower acquisition costs than individual channels. MOHAP-mandated bodily injury minimums now require higher attachment points as hospital cost inflation outpaces statutory adjustment mechanisms. Khalifa Industrial Zone Abu Dhabi concentrates telematics-integrated fleet deployments as fuel subsidy reforms tighten operating cost management.
Sharjah
Islamic leasing structures in the automotive finance cluster demand takaful-compliant product adaptations from underwriters. Individual vehicle owners drive third-party liability volume, constrained by premium sensitivity and regulatory minimum thresholds that compress insurer margins. Price comparison platforms and insurer-owned mobile applications now capture the majority of new policy issuance.
Northern Emirates
Ras Al Khaimah and Fujairah exhibit lower insurance density per registered vehicle, offering first-mover advantages for digital-native distributors. Cross-border traffic patterns and documentation variability elevate uninsured motorist coverage take-up rates. Enforcement gaps in these emirates create asymmetric exposure where medical cost inflation outpaces premium adjustment mechanisms.
United Arab Emirates Motor Insurance Market Competitive Landscape
Abu Dhabi-based underwriters anchor one tier through bancassurance partnerships and direct corporate fleet relationships; Dubai-dominant specialists hold another via digital distribution infrastructure and takaful-compliant architectures. The market structure reflects moderate consolidation among established domestic players with stronger balance sheets, while smaller insurers face portfolio restructuring pressure. Three strategic archetypes prevail: capital-reserve-heavy incumbents with captive sales forces, digital-native distributors leveraging real-time onboarding, and sharia-compliant operators capturing religiously observant segments. Competitive moves concentrate on embedded insurance integration with automotive dealerships and telematics platform partnerships.
Within the takaful-specialist tier, Sukoon Insurance and Watania Takaful occupy positions exemplifying sharia-compliant product structures that appeal to underserved vehicle owners. Among conventional underwriters with geographic naming conventions, Abu Dhabi National Insurance Company and Emirates Insurance Company represent archetypes of capital-adequate incumbents sustaining premium flow through relationship-driven corporate accounts. These named entities illustrate how regulatory pressure on solvency requirements favors established balance sheets over new market entry.
| Leading Market Players |
|---|
| Assicurazioni Generali S.P.A. |
| Emirates Insurance Company |
| Sukoon Insurance |
| Watania Takaful |
| GIG Gulf |
| Orient Insurance PJSC |
| National General Insurance Co. (P.S.C) |
| Islamic Arab Insurance Company |
| Abu Dhabi National Insurance Company |
| Others |
Value Network & Pricing Analysis
Fleet operators in Abu Dhabi and Dubai anchor demand concentration for comprehensive motor coverage, driving contract-based pricing structures that reward multi-year commitments and telematics integration with preferential rate adjustments. This buyer archetype's procurement leverage compresses margins for underwriters serving fragmented individual channels while elevating pricing power for insurers with captive corporate relationships.
Pricing Analysis
Short lead-time policy issuance commands premium pricing in the UAE motor insurance market, with digital-native platforms extracting margin advantages through instant quotation-to-binding workflows that traditional broker channels cannot match. Three-tier pricing structure across premium, standard, and economy levels segments the market, with ISO 9001 certification status and telematics data transparency serving as primary price differentiation drivers. Cost compression in the third-party liability tier is intensifying because regulatory minimum thresholds prevent premium escalation despite medical cost inflation. Individual vehicle owners in Sharjah and northern emirates exhibit highest price sensitivity, while Abu Dhabi corporate fleets demonstrate lowest elasticity due to contractual coverage mandates.
Supply Chain Analysis
Freight and logistics costs concentrate in the UAE's motor insurance supply chain through reinsurance capacity sourcing from London and Singapore markets, creating currency exposure and settlement friction for peak risk transfer. Underwriting capacity draws from domestic balance sheets, regional takaful pools, and international reinsurance treaties, with actuarial talent and claims processing technology serving as critical input dependencies. Single-source vulnerability sits with London market reinsurance for catastrophe layers, exposing UAE underwriters to capacity withdrawal during hard market cycles. Distribution runs through bancassurance partnerships, digital direct-to-consumer platforms, and embedded automotive dealership channels, with broker intermediation eroding fastest in personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE motor insurance market functions as a cost-of-compliance arena where UAE Central Bank capital adequacy rules erect formidable barriers to entry, privileging established underwriters with stronger balance sheets and regulatory relationships.
For Market Incumbents: Deploy telematics platform partnerships to deepen data moats and lock in fleet operator relationships before digital-native distributors achieve scale. Consolidate underwriting capacity through selective portfolio acquisitions of smaller insurers facing solvency pressure under updated capital reserve requirements. Reinforce bancassurance channel control against UAE Central Bank constraints on non-core insurance activities by restructuring commission frameworks and exclusivity arrangements. For New Entrants and Emerging Players: Usage-based insurance infrastructure offers the most penetrable wedge for technology-first entrants, with real-time premium calibration capabilities that incumbent legacy systems cannot replicate. Target northern emirates digital distribution gaps in Ras Al Khaimah and Fujairah, where insurance density per registered vehicle remains lowest and first-mover advantages persist. Pursue embedded insurance integration with ride-hailing platforms and automotive dealerships as the primary go-to-market angle, bypassing saturated broker and direct sales channels. For Investors and Strategic Acquirers: The window for entry favors takaful-compliant operators with established sharia governance frameworks, as religiously observant vehicle owner segments remain underserved by conventional architectures. Acquisition targets should display balance sheet strength sufficient to absorb UAE Central Bank solvency requirements without portfolio restructuring. Monitor telematics data ownership dispute resolutions as the critical inflection signal determining which underwriting models achieve next-generation pricing granularity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Partnership | Enables dynamic premium calibration that rewards low-risk driving behavior with immediate cost reductions. |
| Takaful Product Line Expansion | Captures premium flow from sharia-conscious vehicle owners underserved by conventional insurance architectures. |
| Embedded Insurance Integration | Automotive dealerships and ride-hailing platforms deliver conversion rates exceeding traditional broker networks. |
| Digital Direct-to-Consumer Launch | Mobile applications and price comparison engines compress policy issuance cycles from days to minutes. |
| Reinsurance Treaty Restructuring | Diversifies peak risk transfer beyond London and Singapore markets to reduce capacity concentration exposure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with insurance authority executives, motor underwriters, fleet procurement managers, and claims processing directors. UAE Central Bank prudential returns, Insurance Authority market statistics, and vehicle registration databases from Dubai and Abu Dhabi transport departments provided foundational quantitative anchors. Bottom-up policy issuance modeling and top-down premium pool estimation were reconciled through iterative triangulation across data streams.
Data-stream reconciliation ensured consistency between vehicle registration growth trajectories, premium rate filings, and insurer-reported portfolio compositions across the analysis window. Segmentation modeling incorporated policy type, customer archetype, coverage tier, and distribution channel dimensions alongside emirate-specific regulatory variation. CAGRs were derived from fitted trend analysis against historical premium pools and forward-projected vehicle fleet expansion. Forecast inputs included fuel subsidy reform impacts on fleet telematics adoption and MOHAP-mandated bodily injury limit escalations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under autonomous vehicle liability framework delays or telematics data ownership regulatory interventions. Stakeholders should weight assumptions against their own operating context, particularly regarding capital reserve adequacy and reinsurance capacity access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
China Motor Insurance Market