
 India Car Insurance Market | 2026-2036
India Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Car Insurance Market Insights
Digital distribution is fragmenting across aggregator platforms, insurer-direct portals, and embedded auto-finance partnerships. ACKO General Insurance Ltd. leverages fully digital underwriting to compete on acquisition cost. HDFC ERGO General Insurance Co. Ltd. anchors its position through bancassurance ties with HDFC Bank's auto loan book. ICICI Lombard General Insurance Co. Ltd. extends its reach via telematics-linked usage-based products for commercial fleets.
India car insurance constitutes risk-transfer contracts indemnifying vehicle owners against collision, theft, liability, and natural peril losses, with policies priced through actuarial modeling of insured declared value, engine cubic capacity, and geographic zone risk ratings. Third-party coverage dominates policy volumes due to statutory mandates under the Motor Vehicles Act, while comprehensive plans capture superior margins through bundled add-on covers including engine protection and roadside assistance. Online portals represent the fastest-growing distribution vector, displacing traditional agent networks among individual owners in tier-1 cities.
The Insurance Regulatory and Development Authority of India governs solvency margins and premium rate filings, while the Motor Vehicles Act enforces compulsory third-party coverage and penalizes uninsured operation. The Insurance Information Bureau of India maintains centralized claim history databases that enable risk-based pricing refinements. Stakeholders must monitor how IRDAI's sandbox approvals for on-demand and pay-as-you-drive products reshape customer acquisition economics and retention strategies.
Market Dynamics
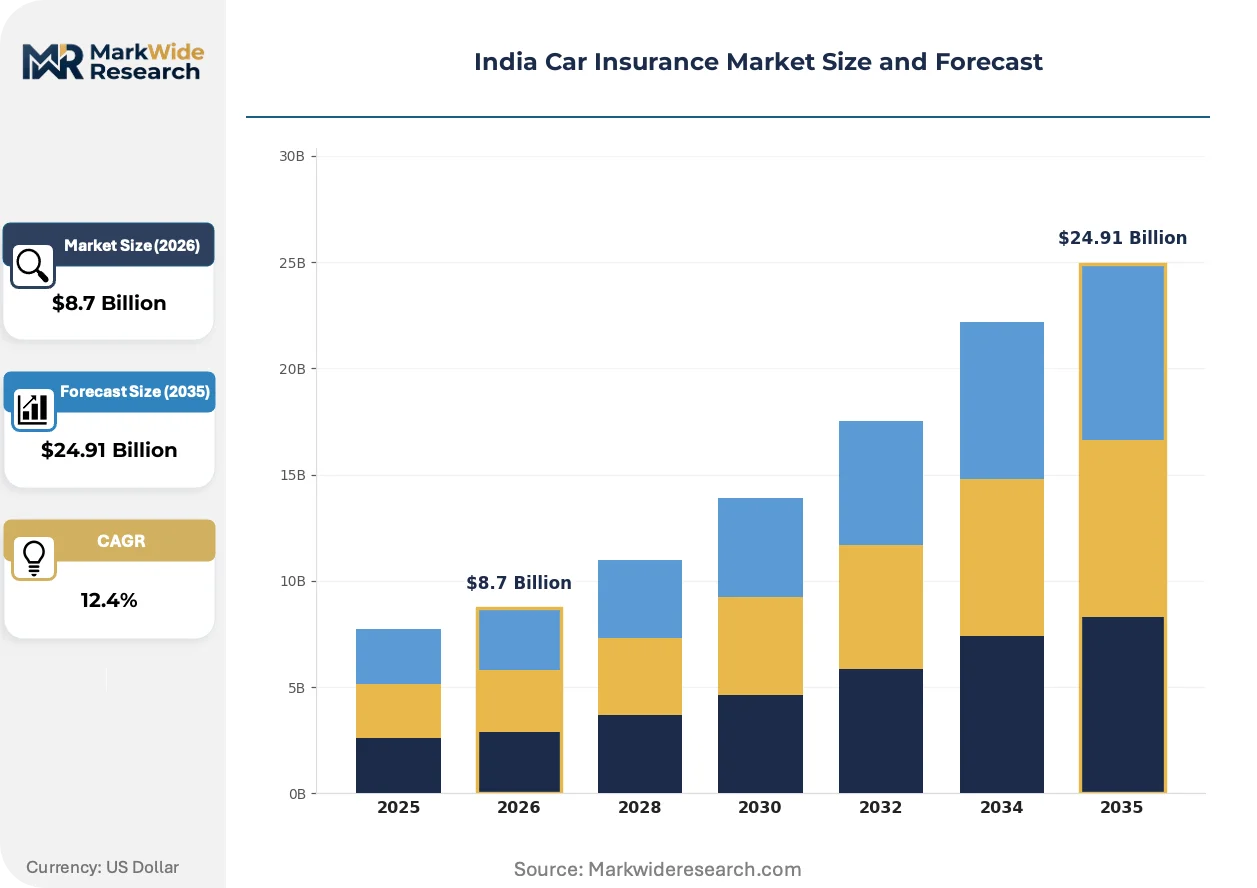
Digital underwriting platforms are compressing acquisition costs and fragmenting distribution across aggregator portals, insurer-direct channels, and embedded auto-finance partnerships in India's car insurance sector.
Growth Catalysts
- Motor Vehicles Act mandates:Statutory third-party liability requirements create guaranteed policy volumes across all vehicle registrations.
- Telematics integration:Commercial fleet operators adopt usage-based products linked to real-time driving behavior data.
- Maharashtra and Gujarat corridors:Urban vehicle density and highway freight concentration elevate premium volumes in these states.
Market Restraints
- Actuarial data asymmetry:Limited historical loss data for electric vehicle battery damage impedes accurate pricing models.
- Agent network dependency:Tier-2 and tier-3 cities remain locked into traditional commission-based distribution with higher cost ratios.
- Fraudulent claims clustering:Staged accidents and inflated repair bills concentrate in high-traffic urban zones.
Strategic Opportunities
- IRDAI sandbox approvals:On-demand and pay-as-you-drive product frameworks enable new customer acquisition economics.
- Karnataka and Tamil Nadu expansion:Underpenetrated southern states with rising vehicle ownership offer premium growth headroom.
- Embedded finance partnerships:Direct integration with OEMs and NBFCs at point of sale captures first-mover policy relationships.
Industry Challenges
- Legacy core system integration:Incumbent insurers face friction connecting telematics data streams to decades-old policy administration platforms.
- Actuarial talent scarcity:Shortage of professionals skilled in machine learning-based pricing models limits product innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Car Insurance Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third-Party, Own Damage, Total Loss Coverage Features: Personal Accident, Roadside Assistance, Engine Protection, No Claim Bonus Distribution Channel: Direct Sales, Agents, Brokers, Online Portals Customer Type: Individual Owners, Fleet Owners, Corporate Clients, Leaseholders |
| Companies Covered | ICICI Lombard General Insurance Co. Ltd., HDFC ERGO General Insurance Co. Ltd., Bajaj Allianz General Insurance Co. Ltd., Tata AIG General Insurance Co. Ltd., New India Assurance Co. Ltd., SBI General Insurance Co. Ltd., Reliance General Insurance Co. Ltd., ACKO General Insurance Ltd., IFFCO TOKIO General Insurance Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Car Insurance Market Trends and Innovations
Artificial intelligence and connected vehicle data streams are restructuring how risk is assessed, priced, and monitored across the policy lifecycle.
Telematics devices capturing real-time driving behavior, braking patterns, and mileage are rendering obsolete traditional zone-based and engine-capacity pricing models. Commercial fleet managers and ride-hailing operators adopt these systems fastest, demanding granular risk segmentation. Actuarial departments compress premium leakage through dynamic pricing adjustments tied to actual usage patterns.
IRDAI's sandbox framework permits controlled experimentation with on-demand coverage and usage-based products outside standard filing requirements. Insurers pilot micro-duration policies for occasional drivers and pay-per-kilometer structures for low-mileage vehicles. Digital-native carriers leverage these approvals to test customer acquisition models before full-scale rollout.
Aggregator platforms now capture significant share of individual policy searches, displacing traditional agent relationships in tier-1 cities. Younger vehicle owners compare quotes across multiple insurers instantly, compressing decision cycles from days to minutes. Mumbai and Delhi exhibit the sharpest channel shift, with embedded partnerships at auto dealerships gaining parallel traction.
India Car Insurance Market Segmentation
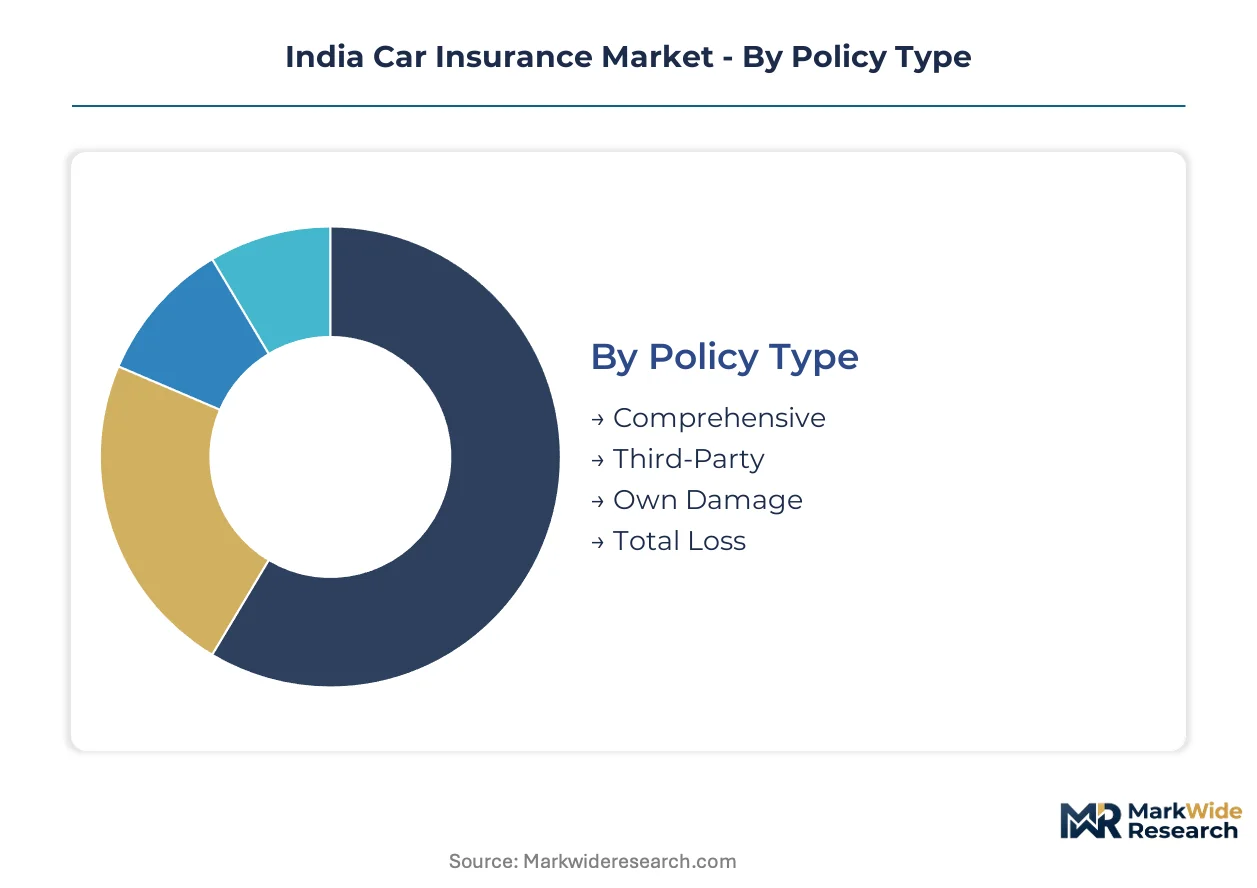
Segmentation in India's car insurance market determines pricing precision, distribution channel selection, and claim servicing intensity. After-sales service requirements vary dramatically across policy types and customer categories, shaping insurer operating models and capital allocation priorities.
Policy Type:
After-sales service intensity peaks with comprehensive products requiring multi-peril claims handling and add-on administration, while statutory mandates create volume anchors with minimal servicing overhead.
- Comprehensive:Bundled coverage combining own damage, third-party liability, and optional add-ons including engine protection and consumables. Demand concentrates among individual owners in Maharashtra and Gujarat seeking full asset protection against collision and natural peril losses, with urban vehicle density elevating claim frequencies and service center utilization rates.
- Third-Party:Statutory minimum coverage mandated under the Motor Vehicles Act indemnifying against injury or property damage to third parties. Fleet operators across highway freight corridors in Gujarat purchase these policies in bulk to satisfy compliance requirements, with IRDAI-mandated premium floors compressing margins but guaranteeing policy volumes.
- Own Damage:Standalone coverage for vehicle theft, collision, and specified perils excluding third-party liability. Individual owners with older vehicles in tier-2 cities select this tier to reduce premium outlays while retaining asset protection.
- Total Loss:Specialized coverage triggering full insured declared value payout upon constructive or actual total loss declaration. Commercial leaseholders and ride-hailing operators in Mumbai and Delhi adopt this structure to accelerate fleet replacement cycles.
Third-Party holds the largest share; momentum sits with Comprehensive as bundled add-on penetration deepens.
Coverage Features:
Cost tier differentiation separates basic statutory offerings from premium-loaded protection bundles that command superior margins and retention rates.
- Personal Accident:Mandatory driver and passenger death or disability coverage with statutory minimum sums insured. Individual owners in tier-1 cities frequently upgrade beyond minimums, with Maharashtra recording highest voluntary limit selections.
- Roadside Assistance:24-hour emergency services including towing, battery jump-start, and fuel delivery. Fleet operators across Gujarat's highway corridors bundle this feature to minimize cargo delay costs, with telematics integration enabling automated dispatch.
- Engine Protection:Add-on coverage for hydrostatic lock and consequential engine damage excluded from standard policies. Monsoon-exposed geographies in Mumbai and coastal Maharashtra drive attachment rates.
- No Claim Bonus:Premium discount mechanism rewarding claim-free policy periods with progressive rate reductions. Digital-native insurers leverage NCB portability to poach renewal business from incumbent carriers.
No Claim Bonus holds the largest share; momentum sits with Roadside Assistance as fleet operators prioritize uptime guarantees.
Distribution Channel:
Customer type and geography dictate channel selection, with digital adoption fragmenting traditional agent dominance in metropolitan clusters.
- Direct Sales:Insurer-employed representatives targeting corporate fleet accounts and large leaseholders. Direct channels capture highest policy values per contract in Mumbai and Delhi commercial vehicle segments.
- Agents:Commission-based individual intermediaries retaining stronghold in tier-2 and tier-3 cities where digital literacy gaps persist. Agent networks in Uttar Pradesh and Rajasthan maintain premium collection advantages through relationship-based renewal servicing.
- Brokers:Licensed intermediaries comparing multiple insurer offerings for commercial clients. Corporate fleet managers in Gujarat leverage brokers to structure multi-vehicle master policies with centralized claims administration.
- Online Portals:Aggregator platforms and insurer-direct websites enabling instant quote comparison and policy issuance. Younger vehicle owners in Bangalore and Hyderabad exhibit sharpest channel migration, with decision cycles compressing from days to minutes.
Agents hold the largest share; momentum sits with Online Portals as smartphone penetration deepens in tier-1 cities.
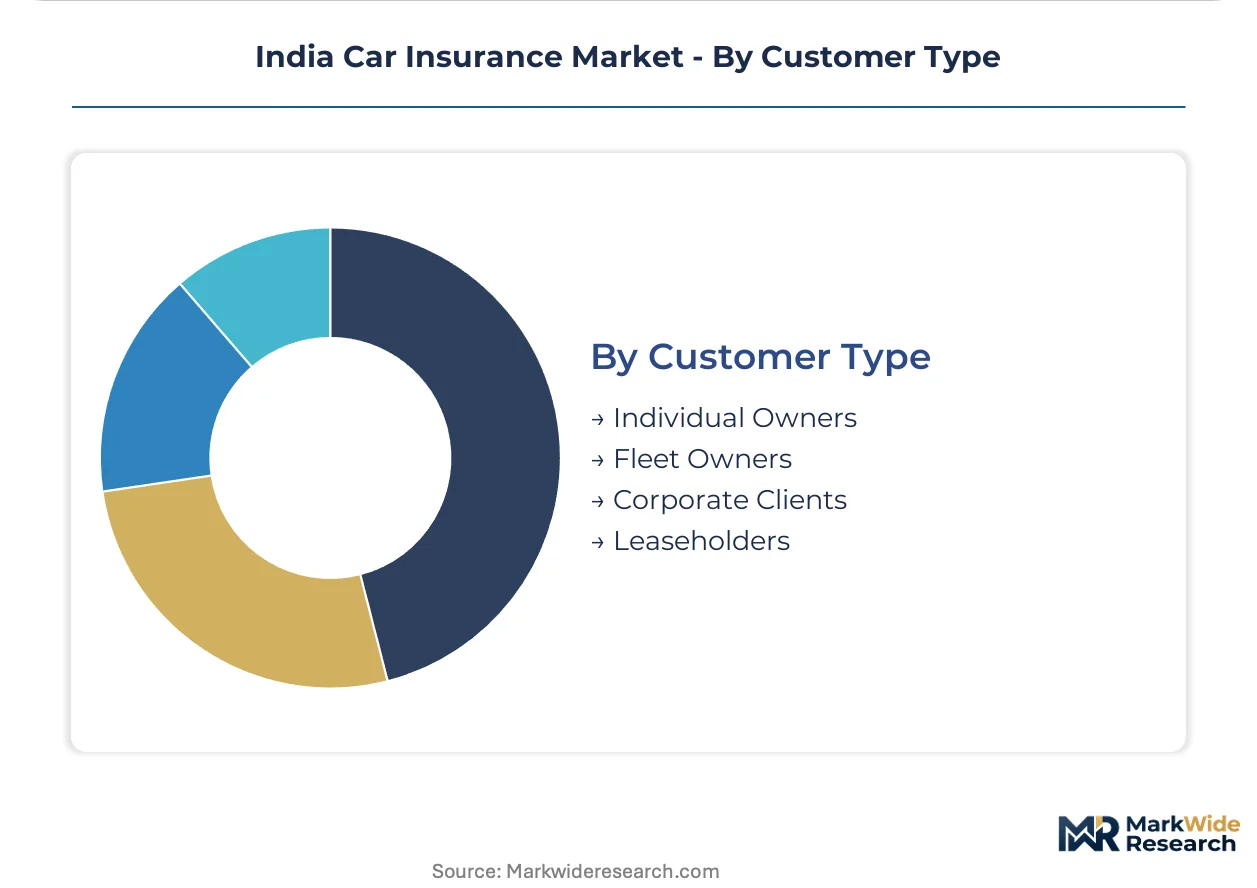
Customer Type:
Volume concentration and margin profiles diverge sharply between fragmented individual ownership and concentrated fleet accounts with specialized servicing requirements.
- Individual Owners:Private vehicle purchasers seeking personal use coverage with flexible add-on selection. Urban centers in Maharashtra and Gujarat generate highest policy densities per capita.
- Fleet Owners:Commercial vehicle pool operators managing five or more units under centralized insurance programs. Highway freight corridors in Gujarat and Rajasthan anchor fleet premium volumes, with telematics-linked usage-based products gaining traction.
- Corporate Clients:Employer-sponsored vehicle programs covering executive cars and commercial delivery fleets. IT and logistics sector employers in Bangalore and Hyderabad drive group policy structuring.
- Leaseholders:Vehicle finance customers with lender-mandated comprehensive coverage requirements. NBFC-embedded partnerships at point of sale capture first-mover policy relationships in Mumbai and Delhi auto finance markets.
Individual Owners hold the largest share; momentum sits with Fleet Owners as commercial vehicle registrations accelerate and telematics adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor freight rail network underwrites Gujarat's dominance in commercial vehicle insurance volumes, while the Western Dedicated Freight Corridor accelerates policy density across Maharashtra's highway nodes.
Maharashtra
Mumbai's dense urban vehicle population and Pune's automotive manufacturing cluster generate India's highest comprehensive policy attachment rates. The Motor Vehicles Act enforcement by the Maharashtra Regional Transport Office mandates third-party coverage at registration, with Mumbai recording elevated claim frequencies from monsoon flooding and collision incidents.
Gujarat
The Mundra and Kandla port complexes anchor India's largest commercial fleet concentrations, with Ahmedabad-Surat highway freight corridors driving bulk third-party policy purchases. The state's Industrial Extension Bureau promotes fleet modernization subsidies that expand insurable asset bases across logistics operators.
Karnataka
Bangalore's technology sector employers sponsor executive vehicle programs with bundled comprehensive coverage, while emerging vehicle ownership in Mysore and Hubli-Dharwad creates underpenetrated premium headroom. The Karnataka Transport Department's digitized registration system accelerates policy issuance velocity.
Tamil Nadu
Chennai's automotive OEM supply chain generates corporate fleet insurance demand, with Coimbatore's SME manufacturing base expanding individual owner policy volumes. The Tamil Nadu Industrial Development Corporation's vehicle financing schemes embed lender-mandated comprehensive coverage at point of sale.
Delhi-NCR
The National Capital Region's odd-even vehicle rationing policies and pollution control regulations compress replacement cycles, accelerating new policy issuance. The Delhi Transport Department's compulsory pollution-under-control certificate linkage with insurance renewal tightens compliance enforcement.
India Car Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower risk-transfer offerings. The market structures around three player tiers: public sector incumbents with legacy bancassurance networks, private sector diversified insurers with multi-channel distribution, and digital-native carriers with zero-commission acquisition models. Strategic moves concentrate on telematics partnership formations and embedded finance integrations at auto dealership point-of-sale.
Among private sector diversified insurers, ICICI Lombard General Insurance Co. Ltd. and HDFC ERGO General Insurance Co. Ltd. occupy positions anchored to banking parent distribution networks, while ACKO General Insurance Ltd. exemplifies the digital-native archetype with fully online underwriting infrastructure. These three represent the competitive spectrum from legacy integration to platform-native acquisition economics.
| Leading Market Players |
|---|
| ICICI Lombard General Insurance Co. Ltd. |
| HDFC ERGO General Insurance Co. Ltd. |
| Bajaj Allianz General Insurance Co. Ltd. |
| Tata AIG General Insurance Co. Ltd. |
| New India Assurance Co. Ltd. |
| SBI General Insurance Co. Ltd. |
| Reliance General Insurance Co. Ltd. |
| ACKO General Insurance Ltd. |
| IFFCO TOKIO General Insurance Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
IRDAI's premium rate filing controls concentrate pricing authority in Mumbai's regulatory hub, channeling margin pools toward insurers with direct distribution infrastructure and compressing acquisition-cost advantages for agent-dependent carriers. This upstream concentration of rate-setting power shapes downstream competitive economics across tier-1 and tier-2 city penetration strategies.
Pricing Analysis
Volume-discount tiering structures dominate fleet account negotiations, with commercial operators commanding 15-30% premium reductions against individual owner rates based on telematics-verified loss ratios and centralized claims administration. Price differentiation hinges on geographic zone risk ratings and engine cubic capacity brackets, with Mumbai and Delhi commanding highest base rates due to elevated claim frequencies. Pricing pressure stems from digital-native carriers zero-commission models forcing margin compression across traditional agent networks. Fleet operators exhibit lowest price sensitivity due to uptime guarantees and bundled roadside assistance, while individual owners in tier-3 cities remain most price-sensitive and coverage-minimal.
Supply Chain Analysis
Export-control regimes on telematics hardware and connected-vehicle data platforms limit technology flows into Indian underwriting infrastructure, constraining real-time risk assessment capabilities for domestic carriers. Supply concentrates in Taiwan for semiconductor components, China for telematics device assembly, and domestic India for policy administration software development. Raw material dependencies include GPS modules, cellular connectivity chipsets, and cloud computing infrastructure. Single-source vulnerability runs through Taiwan's semiconductor foundries for telematics processing units. Distribution runs through insurer-direct portals, aggregator platforms, and embedded auto-finance partnerships at point of sale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital distribution fragmentation creates multiple entry niches as telematics-enabled products and on-demand coverage formats displace one-size-fits-all policy structures.
For Market Incumbents: Build data moats through telematics partnership exclusivity with commercial fleet operators and ride-hailing platforms. Integrate legacy core systems with real-time driving behavior data streams to prevent customer poaching by digital-native carriers. Expand bancassurance tie depth with HDFC Bank and ICICI Bank auto loan books to lock in first-mover policy relationships at vehicle financing origination. For New Entrants and Emerging Players: Karnataka and Tamil Nadu's underpenetrated southern markets with rising vehicle ownership represent the most penetrable entry point for digital-first acquisition models. Target tier-2 city individual owners through smartphone-native quote comparison tools that compress decision cycles below traditional agent timelines. Pursue embedded finance partnerships with NBFCs and OEM dealerships to capture policy relationships at point of sale before incumbent renewal cycles begin. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telematics-linked usage-based products as cloud infrastructure costs per policy decline with scale. Long-term viability favors platforms with proprietary driving data repositories and direct distribution infrastructure over agent-dependent carriers facing commission cost compression. Monitor IRDAI sandbox approval velocity for on-demand and pay-as-you-drive products as the signal indicating regulatory openness to business model innovation.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Partnership Formation | Exclusive data sharing with commercial fleet operators enables dynamic pricing models that compress premium leakage. |
| Embedded Finance Integration | Direct policy issuance at HDFC Bank and ICICI Bank auto loan origination captures first-mover customer relationships. |
| Sandbox Product Pilot | IRDAI-approved on-demand coverage testing validates customer acquisition economics before full-scale rollout. |
| Legacy System Modernization | Core platform upgrades connect real-time driving data streams to decades-old policy administration infrastructure. |
| Geographic Expansion | Karnataka and Tamil Nadu penetration captures underexploited premium headroom in southern state vehicle markets. |
Research Methodology
The analysis maps comprehensive, third-party, own damage, and total loss policy segments, each validated through chief underwriting officers, actuarial department heads, distribution channel managers, and fleet operations directors. Primary interviews with these stakeholders combined with secondary validation from IRDAI regulatory filings, Insurance Information Bureau of India claim databases, Motor Vehicles Act compliance records, and regional transport office registration statistics. Bottom-up policy volume estimates triangulated against top-down premium value assessments across the analysis window.
Assumption sets held IRDAI regulatory frameworks and Motor Vehicles Act mandates fixed while varying telematics adoption rates, digital channel penetration curves, and electric vehicle registration trajectories. The analytical framework modeled policy type, coverage features, distribution channel, and customer type segmentation dimensions across the projection horizon. CAGRs derived from actuarial loss ratio trends, premium rate filing histories, and vehicle registration forecasts. Industry-specific inputs included commercial fleet telematics deployment schedules and sandbox product approval timelines.
Practitioners should monitor IRDAI regulatory shifts, electric vehicle battery damage claims emergence, and digital-native carrier market share trajectories for early signals of structural change. Forecasts reflect these documented assumptions and modeled conditions. Material shifts in statutory coverage mandates, telematics data privacy regulations, or electric vehicle adoption velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Automotive Insurance Market