
 Marine Freight Insurance Market | 2026-2036
Marine Freight Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Freight Insurance Market Analysis
Market Dynamics
Hull-and-machinery coverage with enhanced war-risk provisions is rotating toward the center of broker negotiations. Lloyd's of London leverages its syndicated capital structure to dominate high-value energy cargo placements. Allianz SE anchors continental European port risk through integrated marine and logistics underwriting. Chubb Limited specializes in fine-art and pharmaceutical cold-chain policies for trans-Pacific routes.
Segmentation Analysis
Marine freight insurance encompasses contractual indemnity against physical loss or damage to vessels, cargo, and third-party liabilities arising from maritime transit, with policies typically specifying per-voyage or annual attachment points, Institute Cargo Clauses coverage triggers, and general average contribution obligations. Cargo Insurance leads premium volume as containerized trade expands, while Liability Insurance captures widening margin pools from environmental and cyber-incident endorsements. Single Voyage policies retain dominance in spot-market commodity flows, though Annual coverage grows fastest among integrated logistics operators seeking rate stability.
Regulatory Environment
The International Maritime Organization mandates hull-safety inspections through SOLAS conventions, while the EU Green Deal's emissions disclosure rules reshape carrier liability profiles and underwriting data requirements. Lloyd's Market Association and the International Underwriting Association coordinate clause standardization across London, Bermuda, and Singapore placements. Stakeholders must monitor how evolving carbon-accounting mandates alter loss-adjustment protocols and premium allocation between charterers and beneficial cargo owners.
Market Dynamics
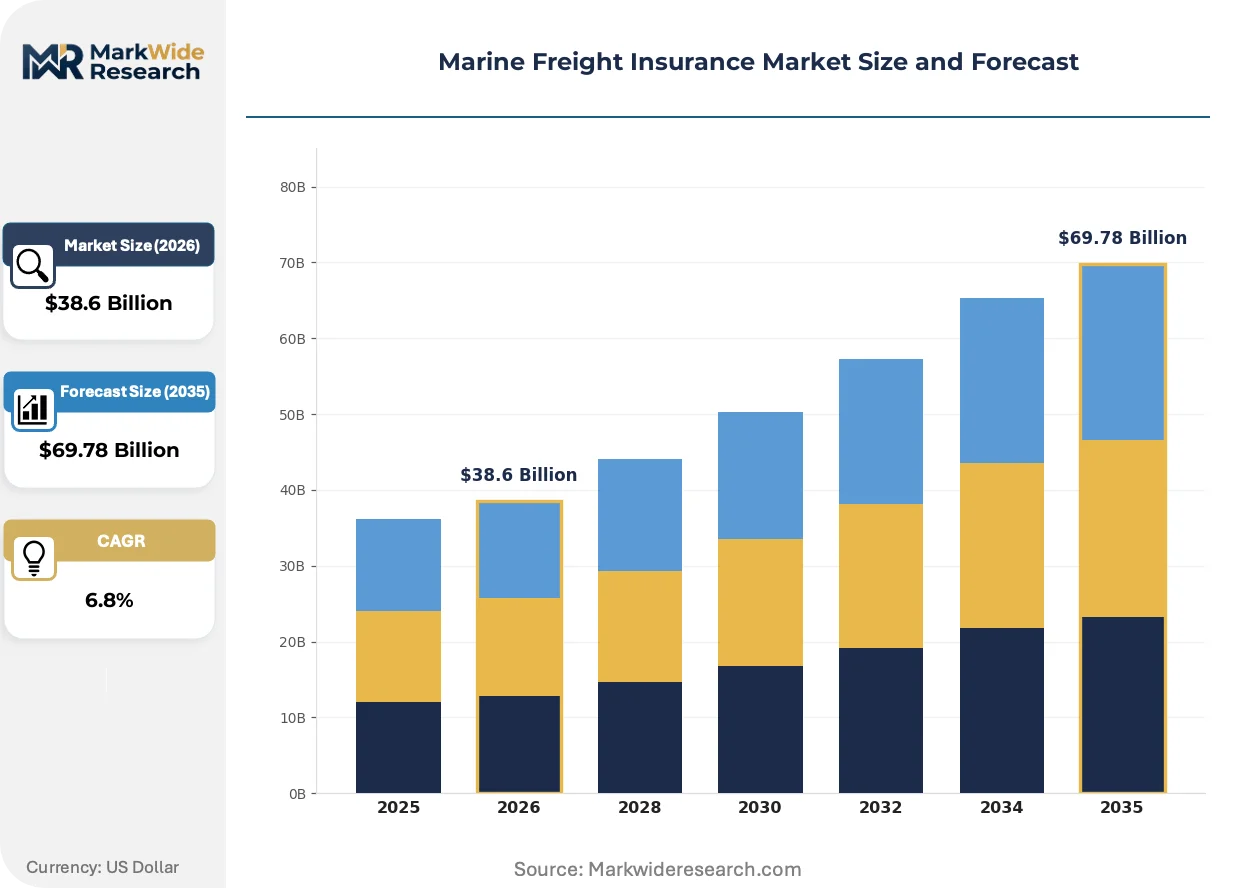
The International Maritime Organization's revised safety protocols are compressing underwriting cycles and elevating capital requirements across marine freight insurance, forcing carriers to reprice risk attachments and recalibrate general average contribution models.
Growth Catalysts
- Containerized trade expansion from Asian manufacturing hubs:Freight forwarders in Singapore, Shenzhen, and Busan are bundling annual open-cover policies with logistics contracts. Premium volumes concentrate along transpacific and Asia-Europe corridors.
- SOLAS convention mandates on verified gross mass:The International Maritime Organization's container-weighing rules have standardized cargo-declaration protocols. Underwriters now price policies with cleaner loss-history data.
- Cold-chain pharmaceutical logistics:Temperature-controlled biologics shipments from Indian and Irish manufacturing sites are driving demand for parametric trigger policies with real-time sensor verification.
Market Restraints
- War-risk premium volatility:Red Sea transit disruptions have compressed hull-and-machinery attachment pricing windows. Syndicates at Lloyd's of London are ceding capacity to reinsurance layers.
- Concentration of hull surveyor capacity:Classification societies in Hamburg, Rotterdam, and Singapore face inspection backlogs. Vessel condition assessments now lag policy renewal timelines by 30-60 days.
- Cyber-attack exposure on bridge systems:GPS spoofing and ECDIS manipulation present unmodeled accumulation risks. Traditional Institute Cyber Attack Exclusions leave cargo interests exposed to navigation-failure losses.
Strategic Opportunities
- Parametric insurance for port congestion:Demurrage cost protection using AIS vessel-tracking data is displacing traditional delay-damage adjusters. Indonesian and Vietnamese port operators are piloting index-triggered covers.
- EU Green Deal emissions disclosure alignment:The EU's carbon-accounting rules for maritime transport are creating demand for environmental-liability endorsements. Carriers are bundling ETS compliance costs into freight-all-kinds policies.
- Integration of IoT sensor telemetry:Reefer container monitoring systems from Mediterranean Shipping and Maersk Line are enabling real-time loss prevention. Underwriters are pricing annual policies against live temperature and humidity feeds.
Industry Challenges
- Actuarial talent scarcity in marine catastrophe modeling:Flood and storm-surge risk quantification for coastal port clusters requires specialized hydrodynamic expertise. Lloyd's and Bermuda markets are competing for the same quantitative analysts.
- Legacy policy administration system integration:London market syndicates using ECF (Electronic Claims Files) face friction connecting to insureds' ERP platforms. Data standardization across Institute Cargo Clauses versions remains incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Freight Insurance Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cargo Insurance, Hull Insurance, Liability Insurance, Freight Insurance Coverage Type: All Risk, Named Perils, Total Loss, Specific Cargo End User: Importers, Exporters, Freight Forwarders, Shipping Companies Policy Term: Annual, Single Voyage, Short-term, Long-term |
| Companies Covered | Lloyd's of London, Allianz SE, American International Group, Chubb Limited, Zurich Insurance Group, AXA XL, Munich Re, Tokio Marine Holdings, QBE Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Freight Insurance Market Emerging Trajectories
Blockchain-verified bills of lading and automated cargo-tracking systems are compressing the information asymmetry between underwriters and insureds, reshaping how marine risk is priced, bound, and adjusted.
Telematics-enabled parametric cargo insurance is displacing traditional loss-adjustment workflows for temperature-sensitive shipments. Pharmaceutical distributors and perishable-food importers are adopting policies with automatic payout triggers tied to reefer container sensor breaches. This technology is compressing claims settlement cycles from months to days while reducing forensic investigation costs.
The EU Green Deal's emissions disclosure rules are mandating granular fuel-consumption reporting for vessels calling at European ports. Ship operators must now submit verified carbon-intensity metrics to classification societies. Container lines serving Rotterdam and Hamburg are restructuring charter-party agreements to allocate ETS compliance liability between owners and charterers.
Freight forwarders are consolidating procurement of annual open-cover marine cargo policies under single broker relationships. Small and mid-sized logistics providers in Vietnam and Bangladesh are abandoning per-voyage placements. This concentration is visible most acutely among NVOCCs serving the intra-Asia trade lane, where rate stability outweighs spot-market flexibility.
Marine Freight Insurance Market Segmentation
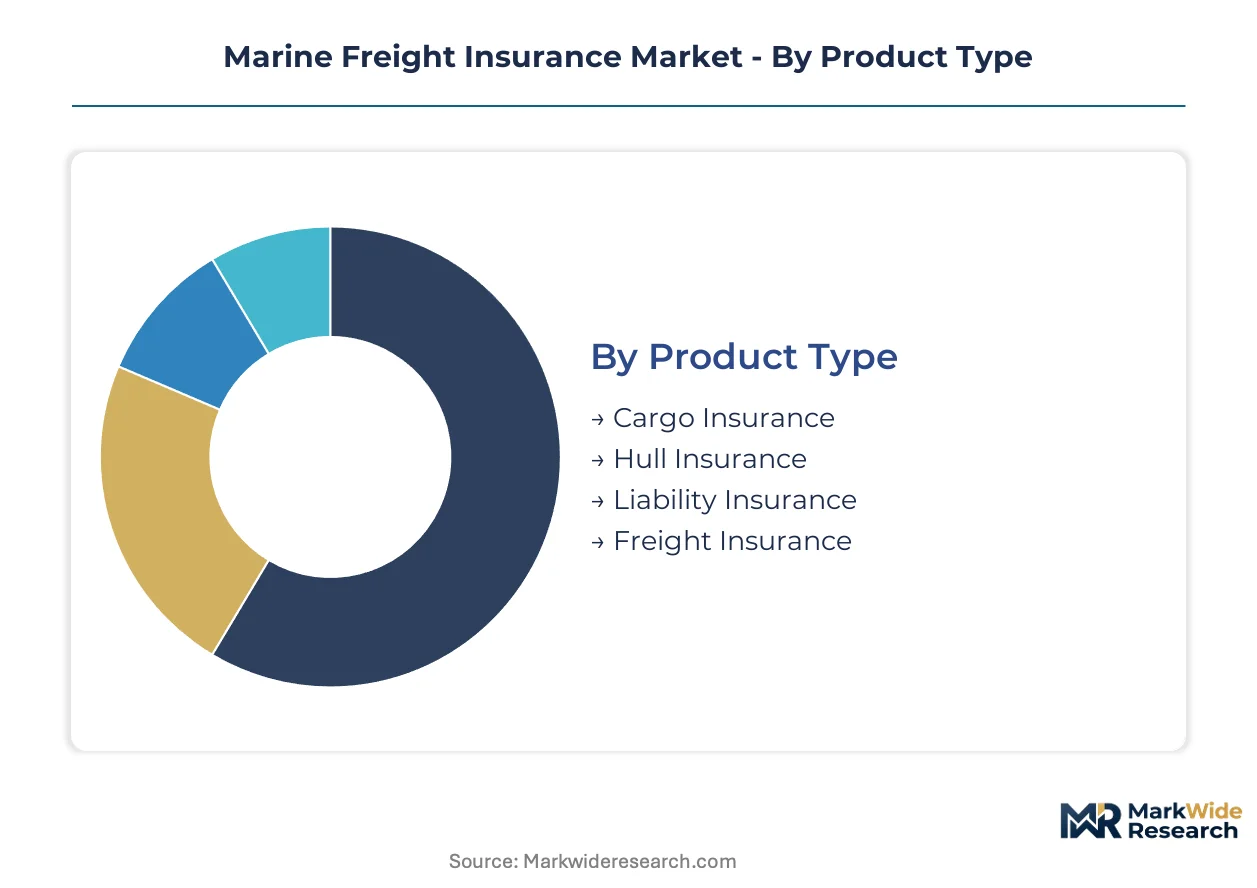
Marine freight insurance segmentation reflects divergent risk appetites across cargo interests, vessel operators, and intermediaries. Underwriting sophistication varies sharply by product type and coverage trigger, with regulatory mandates from the International Maritime Organization and EU Green Deal reshaping policy structures.
Product Type:
Regulatory differentiation between SOLAS-mandated hull inspections and voluntary cargo declarations splits capital allocation across product lines.
- Cargo Insurance:Institute Cargo Clauses A, B, and C define coverage breadth for containerized, bulk, and project cargo movements. Singapore and Rotterdam freight forwarders bundle open-cover cargo policies with logistics contracts to secure rate stability across transpacific lanes.
- Hull Insurance:Protection against physical damage to vessels and machinery, governed by classification society survey cycles. Hamburg and Singapore underwriters price hull-and-machinery coverage against verified gross mass data from SOLAS-compliant weighbridge protocols.
- Liability Insurance:Third-party protection for pollution, collision, and crew injury exposures.
- Freight Insurance:Indemnity for loss of anticipated freight earnings due to vessel disablement.
Established volume favors Cargo Insurance; emerging adoption favors Liability Insurance.
Coverage Type:
Cost tier differentiation separates premium-priced comprehensive protection from stripped-down perils lists favored by commodity traders.
- All Risk:Broadest Institute Cargo Clauses coverage encompassing external damage, theft, and non-delivery except enumerated exclusions. Pharmaceutical distributors transiting Indian cold-chain corridors demand All Risk policies with parametric temperature-breach triggers.
- Named Perils:Specified-risk coverage listing fire, sinking, and jettison as insured events. Dry bulk operators on intra-Asia routes select Named Perils to compress premium outlays against predictable loss histories.
- Total Loss:Coverage activating only on constructive or actual total vessel or cargo destruction.
- Specific Cargo:Tailored policies for project cargo, fine art, or hazardous materials with bespoke valuation clauses.
All Risk commands premium pricing; Named Perils expands most quickly among cost-sensitive commodity flows.
End User:
Application maturity separates integrated logistics operators from transactional cargo interests in policy sophistication.
- Freight Forwarders:NVOCCs and logistics integrators procuring annual open-cover policies across multiple carrier relationships. Vietnamese and Bangladeshi forwarders consolidate broker relationships to replace per-voyage placements with rate-stable annual structures.
- Shipping Companies:Vessel owners and operators managing hull, machinery, and protection and indemnity exposures through mutual clubs and commercial markets. Container lines serving Rotterdam and Hamburg restructure charter-party agreements to allocate EU ETS compliance liability.
- Importers:Beneficial cargo owners purchasing contingent coverage against seller-default or transit gaps.
- Exporters:Shipper-controlled policies ensuring coverage continuity through multimodal handoffs.
Freight Forwarders drive annual policy growth; Shipping Companies anchor hull premium pools.
Policy Term:
Customer type stratification matches spot-market commodity traders against integrated operators seeking multiyear rate certainty.
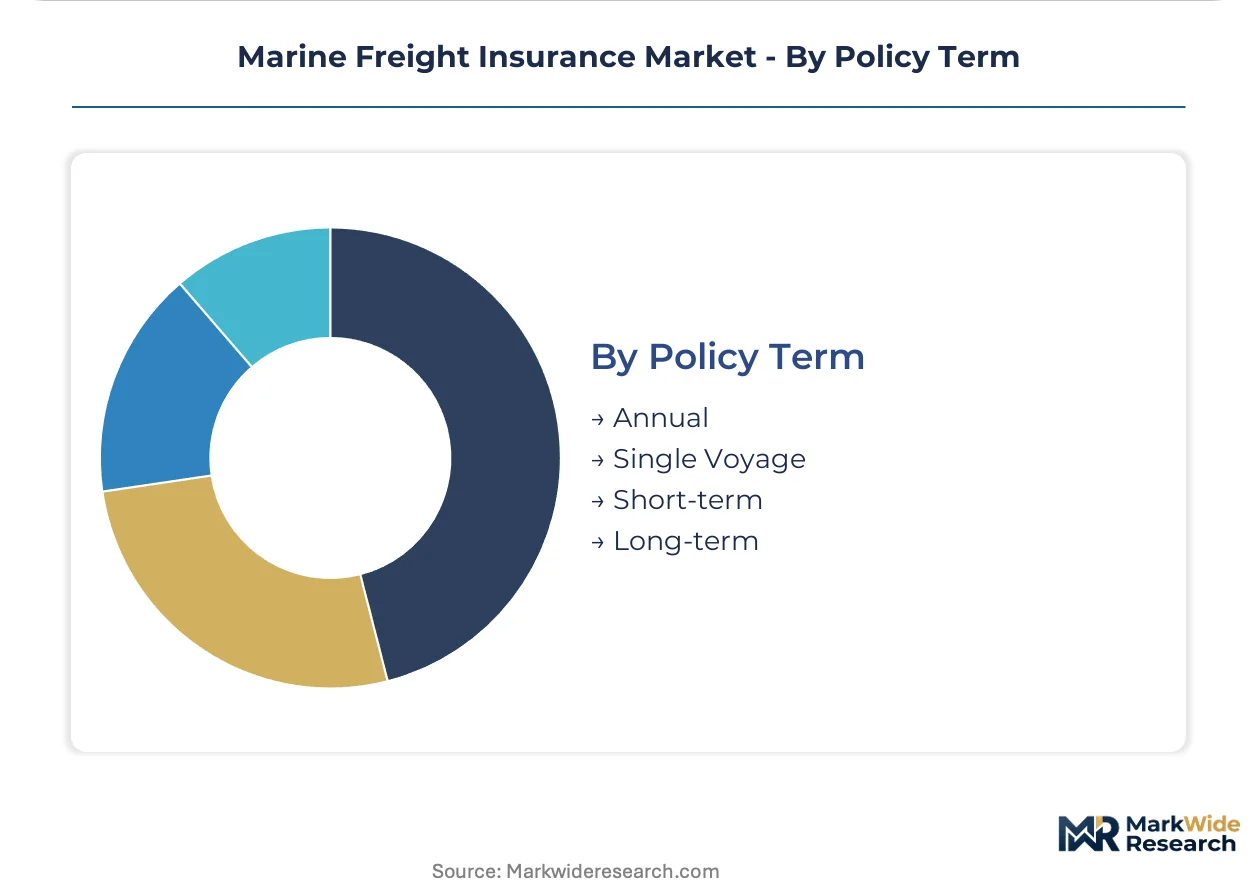
- Annual:Open-cover agreements with automatic renewal and adjustable limit structures. Integrated logistics operators across Shenzhen and Busan prefer Annual coverage to eliminate per-shipment administrative friction.
- Single Voyage:Transactional policies attaching to specific voyages with defined ports of loading and discharge. Spot-market coal and grain traders favor Single Voyage for cargo concentration flexibility.
- Short-term:Duration-specific coverage for project cargo or seasonal trade windows.
- Long-term:Multi-annual agreements with rate caps and loss-sensitive premium adjustments.
Single Voyage retains commodity flow dominance; Annual policies gain share fastest among logistics integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across major trading economies are redistributing marine freight insurance premium flows. Countries with containerized manufacturing surpluses generate cargo policy demand, while import-dependent markets concentrate hull and liability coverage placement.
Singapore
Freight forwarders bundling annual open-cover policies with logistics contracts drive premium growth. The Maritime and Port Authority of Singapore enforces strict vessel inspection protocols that elevate underwriting standards. The Port of Singapore anchors Asia-Europe cargo corridor placements, with Lloyd's syndicates dominating high-value energy cargo negotiations.
Germany
Hamburg's classification societies face hull surveyor backlogs extending policy renewal timelines. The EU Green Deal's emissions disclosure rules reshape carrier liability profiles and underwriting data requirements. The Port of Hamburg concentrates continental European port risk through integrated marine and logistics underwriting.
China
Shenzhen and Shanghai freight forwarders procure annual policies to eliminate per-shipment administrative friction. SOLAS convention mandates on verified gross mass standardize cargo-declaration protocols for cleaner loss-history data. The Pearl River Delta and Yangtze River Delta manufacturing hubs generate containerized trade expansion driving cargo insurance volume.
United States
Pharmaceutical cold-chain logistics from Indian and Irish manufacturing sites drive demand for parametric trigger policies. FDA regulations on temperature-controlled biologics shipments intersect with marine coverage requirements. The Port of Los Angeles and Port of Long Beach concentrate trans-Pacific fine-art and pharmaceutical policy placements.
United Kingdom
Lloyd's Market Association coordinates clause standardization across London, Bermuda, and Singapore placements. The Prudential Regulation Authority oversees solvency requirements for marine underwriters operating from London. The City of London retains dominance in high-value energy cargo and war-risk premium placements despite Red Sea transit disruptions.
Marine Freight Insurance Market Vendor Landscape
Concentration sits with syndicated capital structures and integrated multinational insurers. The market exhibits tiered competition between specialized marine underwriters, diversified global carriers, and mutual protection and indemnity clubs. Three archetypes dominate: London market syndicates leveraging delegated authority frameworks, continental European integrated insurers with port risk expertise, and Asia-Pacific carriers capturing intra-regional trade growth. Competitive moves center on parametric product development and broker relationship consolidation.
Within the syndicated capital tier, Lloyd's of London and Chubb Limited exemplify specialist marine underwriting archetypes. Among diversified European carriers, Allianz SE and Zurich Insurance Group occupy positions integrating marine coverage with broader logistics and commercial portfolios. These entities represent contrasting strategic postures—specialized depth versus balanced diversification—within a market where broker negotiations increasingly rotate around enhanced war-risk provisions and real-time sensor verification capabilities.
| Leading Market Players |
|---|
| Lloyd's of London |
| Allianz SE |
| American International Group |
| Chubb Limited |
| Zurich Insurance Group |
| AXA XL |
| Munich Re |
| Tokio Marine Holdings |
| QBE Insurance Group |
| Others |
Supply Flow & Price Mechanics
Thirty-to-sixty-day hull surveyor backlogs compress policy renewal windows and concentrate pricing leverage with classification societies in Hamburg, Rotterdam, and Singapore. This lead-time distortion elevates premiums for vessel operators while freight forwarders absorb rate volatility through annual open-cover structures.
Pricing Analysis
Industrial OEM buyers anchor premium stratification across Institute Cargo Clauses tiers, with All Risk coverage commanding substantial markups over Named Perils alternatives. Price differentiation rests on SOLAS certification compliance and real-time sensor verification capabilities for cold-chain cargo. Pricing pressure stems from war-risk volatility in Red Sea corridors, compressing attachment windows for hull-and-machinery coverage. Commodity traders on intra-Asia routes exhibit highest price sensitivity, while pharmaceutical distributors accept premium outlays for parametric temperature-breach protection.
Supply Chain Analysis
United Kingdom and Germany anchor specialist underwriting capacity through Lloyd's syndicates and Hamburg classification societies, while Singapore concentrates Asia-Pacific placement infrastructure. Raw material inputs draw from actuarial talent pools in London and Bermuda, hydrodynamic modeling expertise in coastal research institutes, and sensor telemetry systems from Mediterranean Shipping and Maersk Line. Single-source vulnerability sits with concentrated hull surveyor capacity creating inspection bottlenecks. Distribution runs through broker relationships consolidating annual open-cover procurement for integrated logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Claims settlement acceleration through parametric trigger policies expands faster than traditional loss-adjustment hardware, positioning marine freight insurance as a data-service attach opportunity rather than pure risk transfer.
For Market Incumbents: Fortify broker relationship concentration by embedding annual open-cover structures with integrated logistics operators across Shenzhen and Busan. Expand in-house hydrodynamic catastrophe modeling capability to reduce dependence on scarce external actuarial talent. Lloyd's syndicates face displacement risk from Asia-Pacific carriers capturing intra-regional trade growth through parametric product development. For New Entrants and Emerging Players: SOLAS certification fast-tracks for verified gross mass compliance create entry pathways for digital-native underwriters bypassing legacy ECF system friction. Target Vietnamese and Bangladeshi freight forwarders abandoning per-voyage placements for rate-stable annual structures. Lead with AIS vessel-tracking data products for port congestion demurrage protection, displacing traditional delay-damage adjusters. For Investors and Strategic Acquirers: Long-term, this sits as a data-asset play because real-time sensor telemetry and blockchain-verified bills of lading transform underwriting from retrospective risk transfer to predictive loss prevention. Acquisition targets include parametric insurance specialists with established IoT integrations and classification societies with hydrodynamic modeling capabilities. Monitor EU Green Deal emissions disclosure enforcement as inflection indicator for environmental-liability endorsement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Automatic payout triggers tied to reefer sensor breaches compress claims cycles from months to days. |
| IoT Telemetry Integration | Live temperature and humidity feeds from Maersk Line containers enable real-time loss prevention pricing. |
| Broker Relationship Consolidation | Single-broker annual open-cover structures eliminate per-shipment administrative friction for NVOCCs. |
| EU Green Deal Alignment | Environmental-liability endorsements bundle ETS compliance costs into freight-all-kinds policies for Rotterdam carriers. |
| Hydrodynamic Modeling Investment | In-house catastrophe quantification for coastal port clusters reduces reliance on scarce external actuarial talent. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across marine underwriters, freight forwarders, classification society surveyors, and broker intermediaries. Primary fieldwork combined with secondary validation from Lloyd's Market Association clause documentation, International Maritime Organization SOLAS convention filings, EU Green Deal regulatory texts, and port authority inspection protocols. Bottom-up premium volume estimates triangulated against top-down macro trade flow projections.
Across the analysis window, segmentation modeling captured product type, coverage trigger, end-user archetype, and policy term dimensions alongside regional regulatory cluster differentiation. CAGRs derived from trend extrapolation of containerized trade volumes, hull inspection backlogs, and parametric adoption curves. Forecast inputs incorporated verified gross mass compliance penetration and cold-chain pharmaceutical shipment growth trajectories.
Underlying assumptions cover sustained Red Sea transit disruption, EU ETS enforcement timelines, and sensor telemetry standardization, with deviation risk concentrated in war-risk premium volatility and cyber-attack accumulation modeling gaps. Recalibration cycles align with material shifts in International Maritime Organization safety protocol revisions and carbon-accounting mandate implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance Aggregators Market
Insurance
Singapore Business Income Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Aviation Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
China Group Health Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Business Insurance Market