
 Heavy Duty Clutches Market | 2026-2036
Heavy Duty Clutches Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Clutches Market Insights
Construction equipment is realigning demand toward higher-torque clutch systems as earthmoving fleets expand in mining and infrastructure corridors. ZF Friedrichshafen AG leverages integrated powertrain architectures to capture specification-influence at the OEM design stage. Eaton Corporation sustains aftermarket channel density through distributor partnerships across North American heavy truck corridors. Schaeffler AG differentiates via ceramic-composite friction technology that extends service intervals in high-cyclic loader applications.
Heavy duty clutches are torque-transfer devices engineered to engage and disengage power transmission between engine and drivetrain in commercial and industrial vehicles, typically rated above 1,000 Nm and constructed with friction-facing materials bonded to steel or aluminum carrier plates. Multi-plate configurations dominate the highest-torque segments where space constraints limit single-plate diameter, while hydraulic actuation commands premium positioning in automated manual transmission integrations. The aftermarket provider channel captures recurring revenue from rebuild programs, though OEM specifications increasingly lock in original friction material chemistry through warranty terms. Extra-large sizing for mining haulers and marine propulsion concentrates margin pools where heat dissipation engineering determines replacement frequency.
The EPA enforces particulate and NOx thresholds that cascade into clutch system thermal management requirements, while the EU Green Deal's embedded carbon rules pressure friction material supply chain provenance. China's MIIT mandates domestic content ratios for heavy vehicle subsystems that influence local sourcing decisions for clutch assembly plants. Stakeholders must monitor how copper-reduction mandates across EPA, REACH, and emerging GB standards reshape friction formulation R&D priorities and supplier qualification timelines.
Market Dynamics
Friction material chemistry is undergoing forced reformulation as copper-reduction mandates cascade from EPA, REACH, and China's emerging GB standards, compressing supplier qualification timelines and locking in OEM specification control through warranty terms.
Growth Catalysts
- Euro VI thermal management thresholds:European emissions rules are extending replacement cycles by forcing heat-dissipation engineering upgrades in mining hauler applications.
- China's MIIT domestic content mandates:Local sourcing requirements for heavy vehicle subsystems are sustaining assembly plant expansion in domestic mining and infrastructure corridors.
- Hydraulic actuation in AMT integrations:Automated manual transmission architectures are commanding premium positioning as fleet operators pursue fuel efficiency gains.
Market Restraints
- Copper and rare earth input volatility:Friction-facing material costs fluctuate with mining supply constraints and export quota policies.
- OEM specification lock-in:Warranty terms increasingly restrict aftermarket rebuild programs to original friction chemistry, constraining independent channel revenue.
- Single-plate diameter limitations:Space constraints in compact driveline architectures prevent scaling in highest-torque segments without multi-plate cost premiums.
Strategic Opportunities
- India's PLI scheme for heavy commercial vehicles:Production-linked incentives are creating localized clutch assembly capacity for domestic mining and construction fleets.
- Ceramic-composite friction convergence with predictive maintenance:Sensor-enabled clutch health monitoring is integrating with telematics platforms to enable condition-based replacement scheduling.
- EU Green Deal embedded carbon rules:Supply chain provenance requirements are opening qualification pathways for low-carbon friction material suppliers.
Industry Challenges
- Tribology and thermal engineering skill scarcity:Specialized heat-dissipation expertise for extra-large mining applications concentrates in aging workforce cohorts.
- Multi-standard certification complexity:Parallel EPA, REACH, and GB standard compliance extends product development timelines by 18-24 months.
- Legacy mechanical actuation integration:Hydraulic system retrofits face compatibility friction with existing fleet maintenance protocols and technician training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Clutches Market |
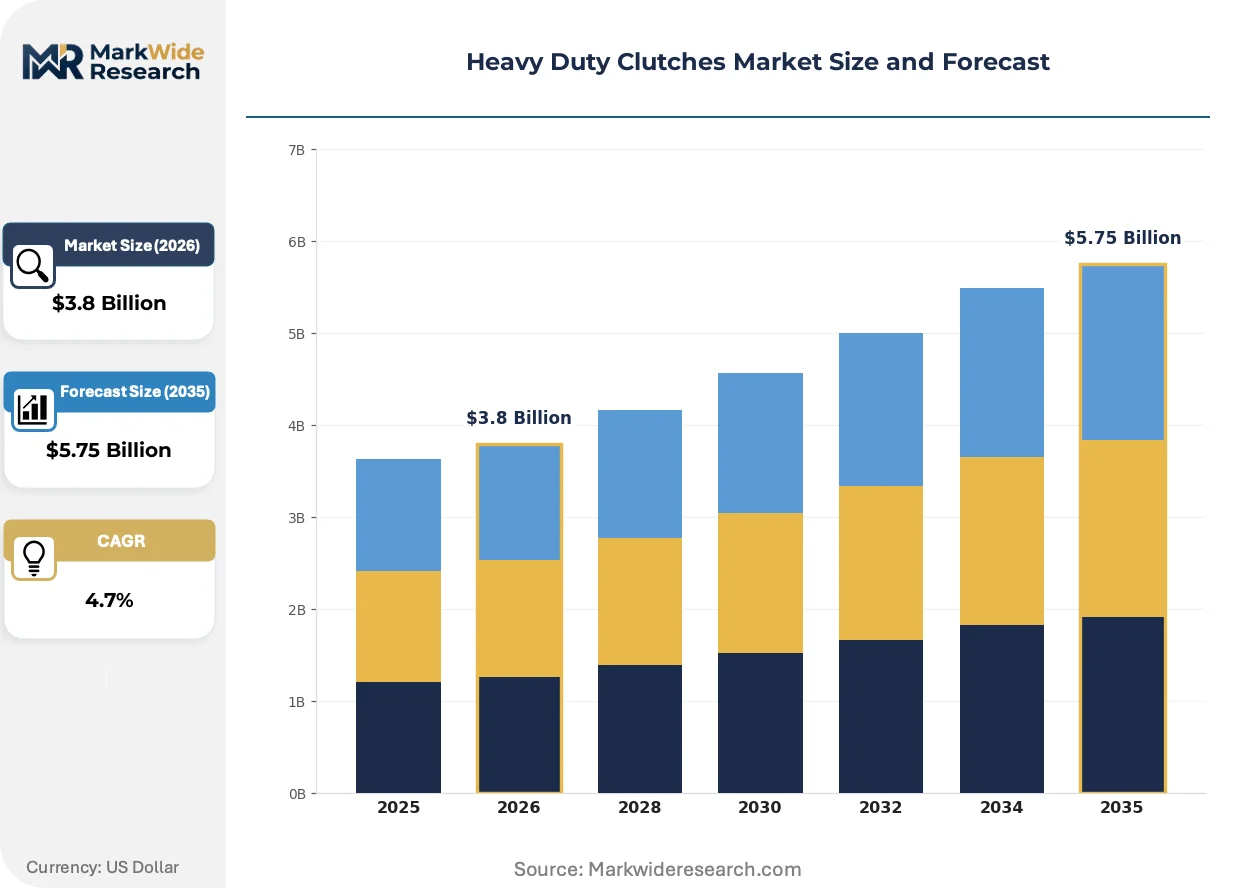
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Plate, Multi-Plate, Hydraulic, Pneumatic Application: Industrial Machinery, Construction Equipment, Marine Vessels, Agricultural Equipment Size: Small, Medium, Large, Extra Large End User: OEMs, Aftermarket Providers, Rental Services, Distributors |
| Companies Covered | ZF Friedrichshafen AG, Eaton Corporation, Valeo, BorgWarner, Schaeffler AG, Aisin Seiki, Exedy Corporation, F.C.C. Co., Ltd., Haldex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Clutches Market Trends and Innovations
Active thermal management and connected diagnostics are compressing traditional replacement economics, while regulatory chemistry mandates are reshaping supplier qualification hierarchies across three converging vectors.
Ceramic-composite friction materials are integrating sensor-enabled temperature monitoring to predict thermal degradation before catastrophic failure. Mining fleet operators in Australia's Pilbara region are adopting these systems fastest, driven by unplanned downtime costs exceeding $100,000 per hour. The technology is integrating clutch health data into centralized fleet management platforms, compressing the traditional aftermarket rebuild channel into OEM-controlled subscription models.
EPA copper-reduction mandates are forcing reformulation of bronze-bearing friction facings toward sintered iron-carbon alternatives with modified thermal coefficients. The industrial consequence is extended validation cycles for new material stacks as OEMs demand million-cycle durability testing. North American heavy truck specifications are responding fastest, with Eaton and ZF accelerating qualification of low-copper alternatives ahead of 2027 enforcement windows.
Fleet procurement departments are consolidating clutch specification authority away from regional maintenance managers toward centralized engineering functions with total cost-of-ownership modeling. Direct OEM supply agreements are displacing traditional distributor networks in North American Class 8 truck corridors. This concentration is most visible in US for-hire trucking, where megafleets exceeding 10,000 units now specify friction material chemistry at the corporate level, locking in decade-long supplier relationships.
Heavy Duty Clutches Market Segmentation
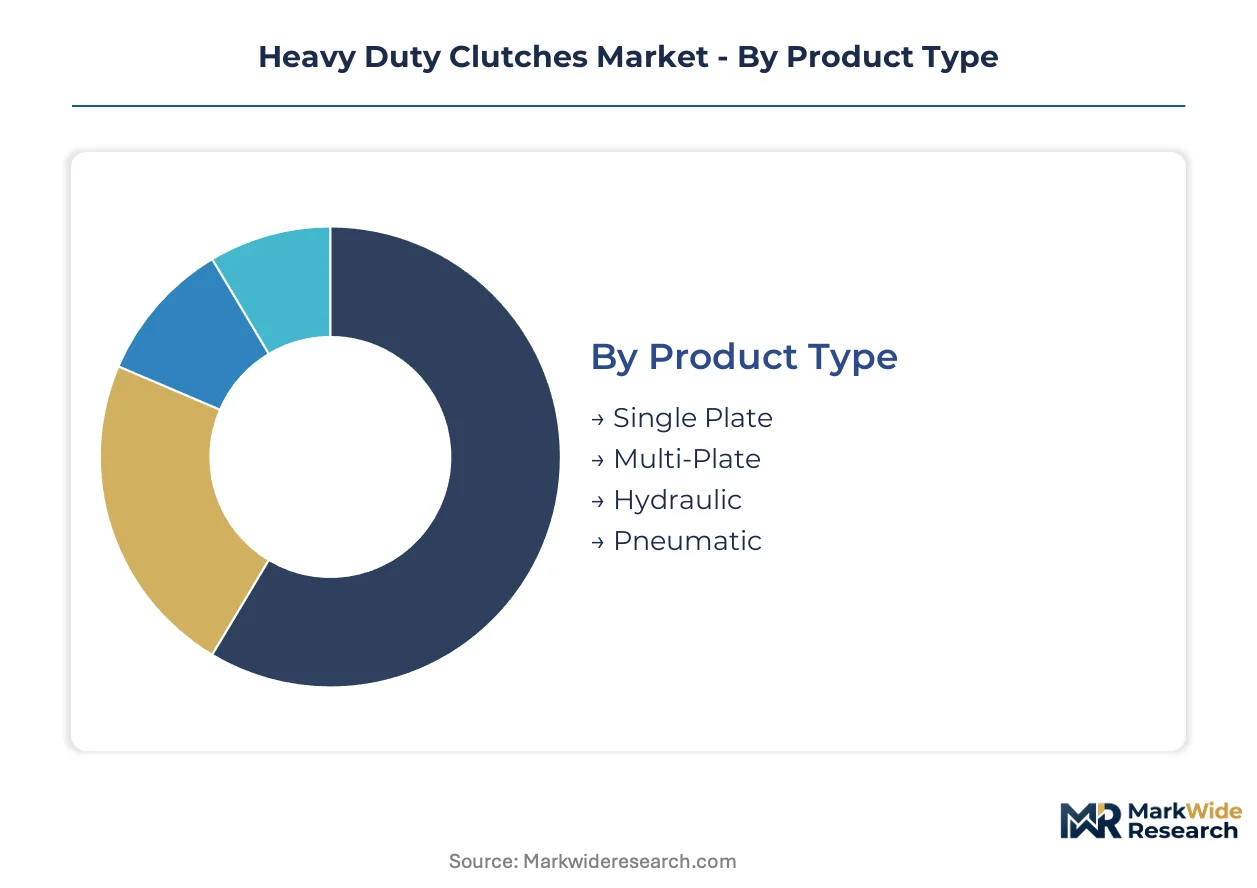
Heavy duty clutch procurement decisions pivot on torque density requirements, actuation method compatibility, and fleet lifecycle economics. Specification authority concentrates differently across construction, mining, and marine applications, with each vertical imposing distinct thermal management and service interval demands.
Product Type:
Fleet operators select actuation architecture based on transmission integration complexity and technician skill availability across their maintenance networks.
- Multi-Plate:Stacked friction disc configurations achieve torque ratings above 3,000 Nm within constrained driveline envelopes. Mining hauler specifications in Australia's Pilbara and Chile's Atacama corridors favor these systems for their heat dissipation surface area, though unit costs run 40-60% above single-plate alternatives.
- Hydraulic:Automated manual transmission integrations command premium positioning through precise engagement control and reduced driver fatigue. European long-haul fleets pursuing fuel efficiency gains specify these systems fastest, with ZF and Eaton capturing specification-influence at the OEM design stage.
- Single Plate:Cost-optimized configurations dominate medium-duty commercial truck production where space constraints are less severe.
- Pneumatic:Compressed air actuation persists in legacy heavy truck fleets and certain off-highway equipment categories with established maintenance protocols.
Multi-Plate leads on scale; Hydraulic leads on momentum.
Application:
End-use thermal cycling intensity and downtime cost exposure determine friction material specification and replacement economics.
- Construction Equipment:Earthmoving fleets in mining and infrastructure corridors impose the highest cyclic loading conditions. Loaders and excavators operating in China's domestic buildouts sustain demand for ceramic-composite friction technology that extends service intervals under high-frequency engagement cycles.
- Marine Vessels:Propulsion systems for tugs and offshore supply vessels require extra-large sizing where heat dissipation engineering determines replacement frequency. Classification society certification requirements lock in supplier relationships for decade-long maintenance contracts.
- Industrial Machinery:Stationary power transmission applications favor standardized configurations with predictable maintenance windows.
- Agricultural Equipment:Seasonal duty cycles and price-sensitive procurement constrain specification complexity in tractor and harvester segments.
Construction Equipment anchors volume concentration; Marine Vessels capture the steepest expansion trajectory from offshore energy investments.
Size:
Driveline packaging constraints and torque transmission requirements segment the market across dimensional categories with divergent margin structures.
- Extra Large:Mining hauler and marine propulsion applications concentrate margin pools where engineering-intensive heat dissipation design commands premium pricing. Australia's iron ore producers and Chile's copper extraction operations specify these systems for 50,000+ hour service life targets.
- Large:Class 8 heavy truck and construction equipment specifications balance torque capacity with packaging efficiency across North American and European corridors.
- Medium:Regional haulage and medium-duty commercial applications standardize on proven friction material stacks with established aftermarket support.
- Small:Compact driveline architectures in light commercial vehicles face displacement pressure from automated transmission alternatives.
Extra Large dominates margin capture; Large maintains the broadest installed base across heavy commercial categories.
End User:
Procurement authority consolidation and warranty term structures are redistributing value capture across channel configurations.
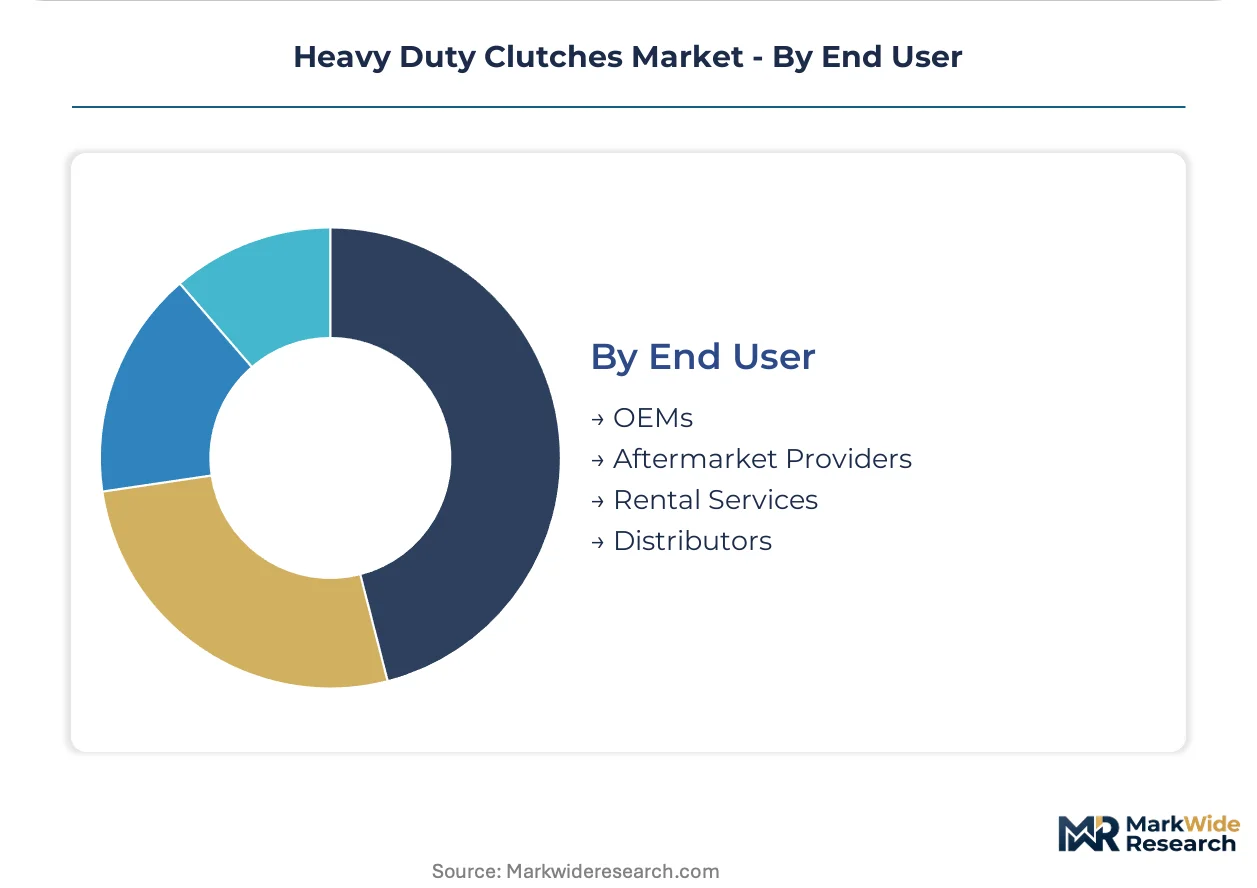
- OEMs:Original equipment manufacturers increasingly lock in friction material chemistry through warranty terms that constrain independent rebuild options. North American megafleets exceeding 10,000 units now specify material chemistry at corporate engineering functions, securing decade-long supplier relationships.
- Aftermarket Providers:Traditional distributor networks face compression as predictive maintenance platforms and OEM subscription models displace scheduled rebuild programs. Independent channels retain strength in legacy mechanical actuation fleets with established technician training infrastructure.
- Rental Services:Fleet utilization optimization drives demand for condition-based replacement scheduling integrated with telematics platforms.
- Distributors:Regional inventory positioning remains critical for emergency replacement scenarios in remote mining and construction operations.
OEMs command specification authority; Aftermarket Providers are gaining fastest in emerging market corridors with aging fleet profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing clutch assembly capacity toward jurisdictions with lower compliance costs, as copper-reduction mandates in mature markets accelerate supplier qualification timelines and compress margins.
United States
Class 8 truck megafleets exceeding 10,000 units now specify friction material chemistry at corporate engineering functions, consolidating decade-long supplier relationships. EPA emissions thresholds cascade into thermal management requirements that extend product development timelines. Manufacturing clusters in Michigan and Ohio concentrate hydraulic actuation production for automated manual transmission integrations.
Germany
Long-haul fleet operators pursuing fuel efficiency gains specify hydraulic systems fastest, with premium positioning commanded through precise engagement control. Euro VI thermal management thresholds force heat-dissipation engineering upgrades in mining hauler specifications. Industrial corridors in Baden-Württemberg and Bavaria anchor ceramic-composite friction technology development for high-cyclic applications.
China
Domestic mining and infrastructure buildouts sustain heavy truck and off-highway production volumes at scale. MIIT mandates domestic content ratios for heavy vehicle subsystems that influence local sourcing decisions for clutch assembly plants. Manufacturing bases in the Yangtze River Delta and Shandong Peninsula concentrate multi-plate production for constrained driveline envelopes in mining equipment.
India
Production-linked incentives for heavy commercial vehicles are creating localized clutch assembly capacity for domestic mining and construction fleets. Central government procurement rules favor domestic content in public infrastructure equipment. Industrial zones in Maharashtra and Gujarat attract component suppliers serving both local OEMs and export markets.
Australia
Mining fleet operators in the Pilbara region adopt sensor-enabled temperature monitoring fastest, driven by unplanned downtime costs exceeding $100,000 per hour. National mining safety regulations mandate predictive maintenance integration for critical powertrain components. Perth-based engineering services clusters support remote maintenance contracts for extra-large sizing applications in iron ore extraction.
Heavy Duty Clutches Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEMs lock in friction material chemistry through warranty terms that constrain independent rebuild channels. The vendor base concentrates around three tiers: integrated powertrain architects capturing specification-influence at the design stage, specialized friction material developers extending service intervals through ceramic-composite technology, and regional assemblers serving aftermarket rebuild programs. Capacity expansion and backward integration into friction-facing production represent the dominant competitive vectors as suppliers seek margin protection against copper and rare earth input volatility.
Within the integrated powertrain tier, ZF Friedrichshafen AG and Eaton Corporation exemplify specification-capture strategies at the OEM design stage. Schaeffler AG occupies a position among specialized friction developers, while Aisin Seiki and Exedy Corporation represent Asian-based manufacturers with established regional production footprints. These anchors illustrate how geographic origin and corporate structure align with distinct strategic archetypes across the competitive map.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Eaton Corporation |
| Valeo |
| BorgWarner |
| Schaeffler AG |
| Aisin Seiki |
| Exedy Corporation |
| F.C.C. Co., Ltd. |
| Haldex |
| Others |
Pricing and Supply Chain Analysis
North American Class 8 megafleets exceeding 10,000 units command contract-based long-term offtake pricing that compresses distributor margins and locks in decade-long supplier relationships through corporate engineering specifications.
Pricing Analysis
Distributor margin compression runs through aftermarket channels as OEM warranty terms restrict independent rebuild programs to original friction chemistry. Three-tier pricing structure across premium ceramic-composite, standard sintered metallic, and economy organic facings separates mining hauler specifications from medium-duty commercial applications. Cost compression in economy tiers intensifies because copper-reduction mandates force R&D reallocation toward compliant formulations. Fleet procurement departments exhibit lowest price sensitivity in extra-large mining segments where unplanned downtime costs dominate total cost-of-ownership calculations.
Supply Chain Analysis
China's MIIT domestic content mandates reshape sourcing patterns for heavy vehicle subsystems, accelerating assembly plant expansion in Shandong Peninsula and Yangtze River Delta manufacturing bases. Friction-facing production draws from copper ore concentrates in Chile and Peru, rare earth processing in China, and specialized ceramic feedstocks in Germany. Single-source vulnerability concentrates in sintered iron-carbon alternatives where million-cycle validation requirements extend supplier qualification timelines. Distribution runs through OEM-direct agreements for megafleets and regional distributor networks for emergency replacement scenarios in remote mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
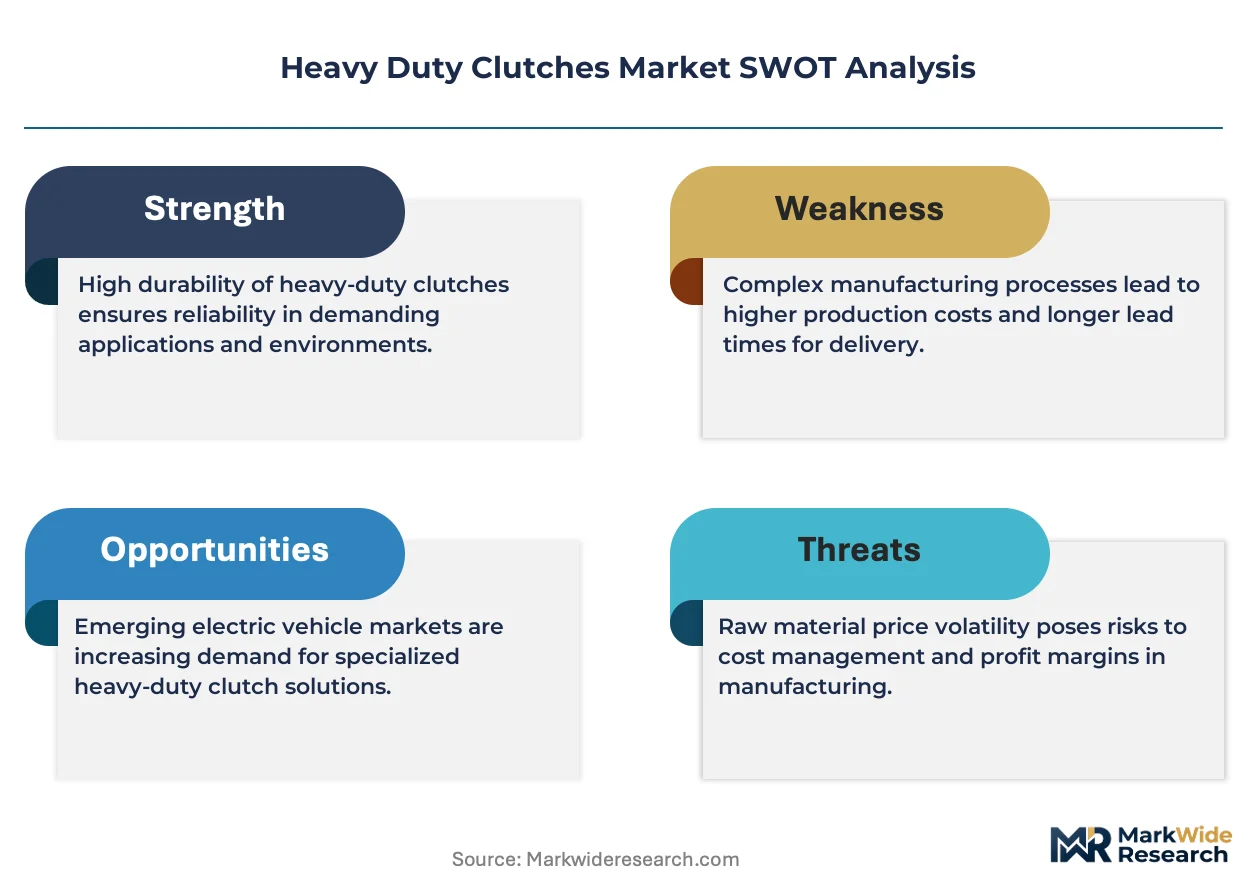
Margin expansion in heavy duty clutches rests on ceramic-composite premium tier adoption and copper-reduction compliance cost recovery through specification lock-in at OEM design stages.
For Market Incumbents: To counter aftermarket channel compression from predictive maintenance platforms, deepen backward integration into friction-facing production and secure captive supply of sintered iron-carbon alternatives ahead of EPA enforcement windows. Prioritize certification investment for multi-standard compliance across EPA, REACH, and emerging GB standards to extend product development timeline advantages over regional competitors. For New Entrants and Emerging Players: The price-point gap between hydraulic AMT integrations and legacy pneumatic actuation creates entry space for mid-tier automated manual transmission clutch assemblies serving India's PLI-subsidized heavy commercial vehicle production. Target white-space in sensor-enabled condition monitoring for rental services and construction fleet telematics platforms where OEM subscription models remain underdeveloped. Pursue go-to-market partnerships with Perth-based engineering services clusters serving Australian Pilbara mining maintenance contracts. For Investors and Strategic Acquirers: Integrated powertrain architects are the most active acquirer in this space, seeking specification-influence at OEM design stages through clutch-to-transmission system integration. Long-term viability favors targets with ceramic-composite friction technology and established qualification pathways for low-copper formulations. Monitor copper price volatility and EPA enforcement timeline clarity as inflection indicators for supplier margin compression versus premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Friction-Facing Production | Captive supply of sintered iron-carbon alternatives insulates margin against copper price volatility. |
| Multi-Standard Certification Investment | Parallel EPA, REACH, and GB compliance accelerates supplier qualification timelines relative to competitors. |
| Sensor-Enabled Predictive Maintenance Platform | Telematics integration with ZF and Eaton fleet management systems compresses traditional aftermarket rebuild economics. |
| Localized Assembly Capacity Expansion | India PLI scheme and China MIIT mandates reward domestic content ratios in heavy commercial vehicle subsystems. |
| Ceramic-Composite R&D Partnership | Schaeffler AG's thermal engineering expertise extends service intervals in high-cyclic mining loader applications. |
Research Methodology
Bottom-up construction and mining equipment fleet modeling reconciled against top-down friction material production tracking forms the analytical core of this study. Primary interviews with maintenance directors at Australian iron ore operators, OEM procurement teams at ZF and Eaton, aftermarket service heads at North American heavy truck distributors, and ceramic-composite R&D directors at Schaeffler AG inform demand-side assumptions. Secondary validation draws from EPA enforcement documents, MIIT domestic content circulars, EU Green Deal embedded carbon rulemaking, customs trade data for copper and rare earth inputs, and SEC filings from listed automotive component suppliers.
Historical trendline analysis of replacement cycle extension patterns and thermal management specification shifts anchors the forecast framework. Segmentation modeling spans product type, application vertical, sizing tier, and end-user channel across the projection horizon. CAGRs derive from torque density requirement trajectories in mining hauler applications and hydraulic actuation penetration rates in automated manual transmission integrations. Industry-specific inputs include unplanned downtime cost thresholds in Pilbara mining operations and Euro VI thermal management threshold compliance timelines.
Caveats apply where copper-reduction mandate enforcement delays, rare earth export quota policy shifts, or OEM specification authority consolidation could materially shift the outlook. Forecasts reflect assumptions about friction material qualification timelines and megafleet procurement centralization patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brake Pad Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Tappet Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Rear Spoiler Market