
 Bearing Steel Balls for New Energy Vehicles Market | 2026-2036
Bearing Steel Balls for New Energy Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Bearing Steel Balls for New Energy Vehicles Market Insights
Automotive OEM direct procurement channels is fragmenting as NEV platforms proliferate and volume commitments splinter across multiple motor suppliers. Tsubaki Nakashima leverages its precision grinding heritage to sustain premium positioning in high-speed spindle applications. Jiangsu Longteng Special Steel Group anchors domestic Chinese supply through integrated melt-to-ball production. SKF competes by extending its bearing system expertise into pre-assembled ball-and-cage modules that reduce customer qualification cycles.
Bearing steel balls for new energy vehicles are precision-ground spheres manufactured from vacuum-degassed chrome steel or silicon nitride ceramic, typically held to Grade 10 or finer sphericity tolerances below 0.25 micrometers, serving to reduce frictional losses in rotating assemblies subjected to cyclic loading at speeds exceeding 15,000 RPM. Chrome steel formulations dominate current volume due to established heat treatment infrastructure and cost structure, though silicon nitride ceramic balls represent the fastest-expanding material category as motor speeds climb and insulation requirements harden. Electric motor applications command the most concentrated margin pool, while transmission system demand matures around conventional planetary gear architectures that impose less severe material specifications.
China's SAMR enforces GB standards for bearing steel metallurgical consistency, while the EU F-Gas Regulation and REACH framework indirectly shape demand by accelerating motor efficiency mandates that cascade into bearing performance requirements. Japan's METI coordinates JIS standards alignment with NEV export markets, creating compliance overlap for multinational suppliers. Stakeholders must monitor how carbon border adjustment mechanisms reshape supplier qualification criteria before committing to long-term capacity allocations.
Market Dynamics
Motor rotational speeds exceeding 15,000 RPM are forcing material transitions from chrome steel to silicon nitride ceramic balls, compressing supplier qualification timelines and fragmenting procurement across multiple motor-gearbox integrators.
Growth Catalysts
- EU F-Gas Regulation:Motor efficiency mandates under this framework cascade into stricter bearing performance specifications, accelerating demand for Grade 10 or finer sphericity tolerances in electric traction motors.
- Silicon nitride ceramic balls:These materials address insulation requirements and thermal stability at extreme rotational speeds, capturing the fastest-expanding material category as OEMs redesign motor architectures.
- Yangtze River Delta cluster:Integrated motor-gearbox assembly plants in this manufacturing hub anchor concentrated regional demand pull, creating localized procurement volumes that sustain dedicated supply capacity.
Market Restraints
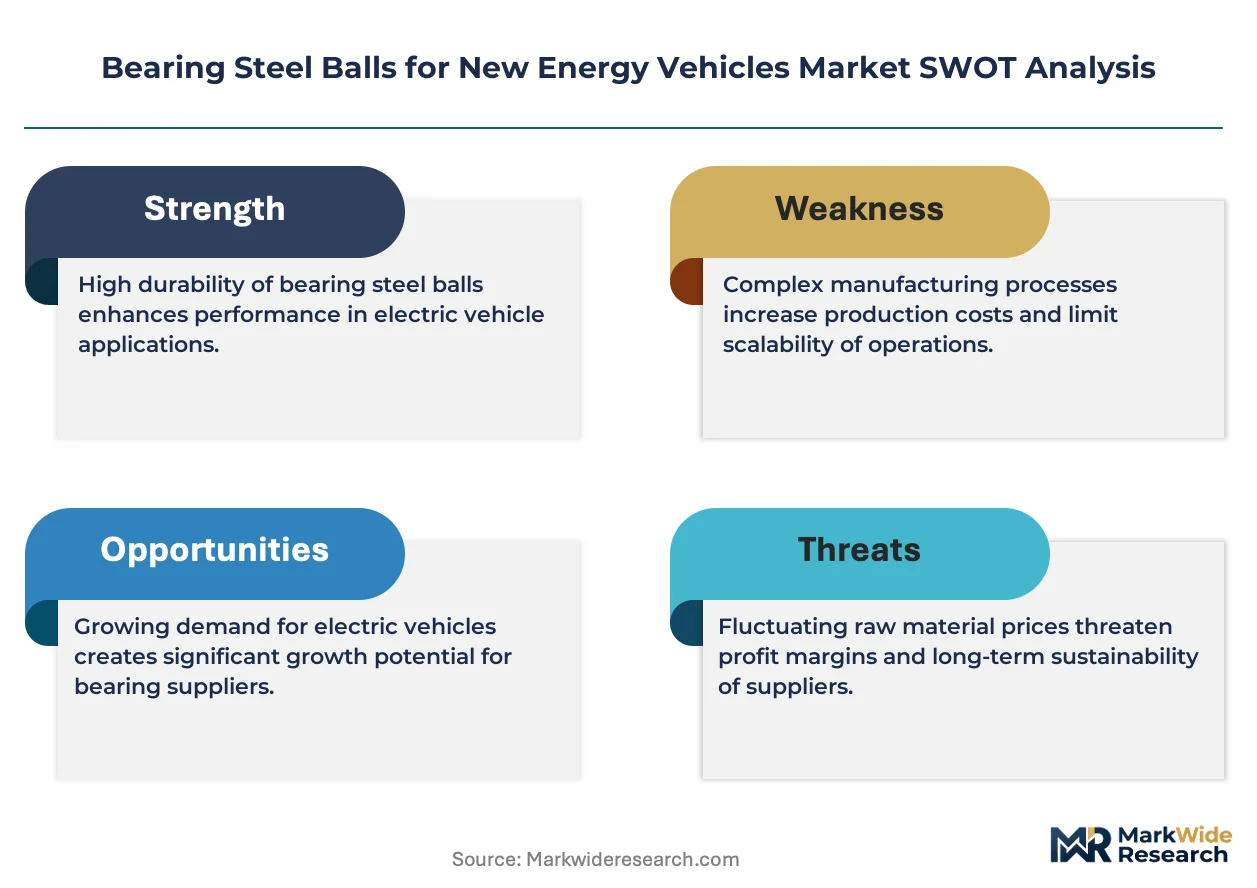
- Vacuum-degassed chrome steel input costs:Metallurgical-grade raw material volatility constrains margin stability for producers serving price-sensitive transmission applications with less severe material specifications.
- Single-region supplier concentration:Domestic Chinese supply dominance through integrated melt-to-ball producers creates exposure to SAMR certification disruptions and carbon footprint verification delays.
- Heat treatment infrastructure lock-in:Established chrome steel processing capabilities represent sunk capital that slows ceramic ball capacity scaling despite superior performance metrics.
Strategic Opportunities
- Pre-assembled ball-and-cage modules:Bearing system integrators can compress customer qualification cycles by delivering certified sub-assemblies rather than commodity spheres.
- Carbon border adjustment mechanisms:Early alignment with verified carbon footprint protocols positions suppliers favorably as EU and North American import criteria harden.
- High-speed spindle aftermarket:Precision grinding heritage capabilities transfer to service replacement demand from NEV fleets reaching warranty thresholds.
Industry Challenges
- Metallurgical consistency certification:GB standards enforcement by SAMR requires documented heat treatment traceability that extends qualification timelines for new supplier entry.
- Multi-standard compliance overlap:JIS alignment with NEV export markets forces simultaneous adherence to Japanese METI coordination protocols and destination-market regulations.
- Sphericity measurement talent scarcity:Sub-0.25 micrometer tolerance verification demands specialized metrology expertise that outpaces vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bearing Steel Balls for New Energy Vehicles Market |
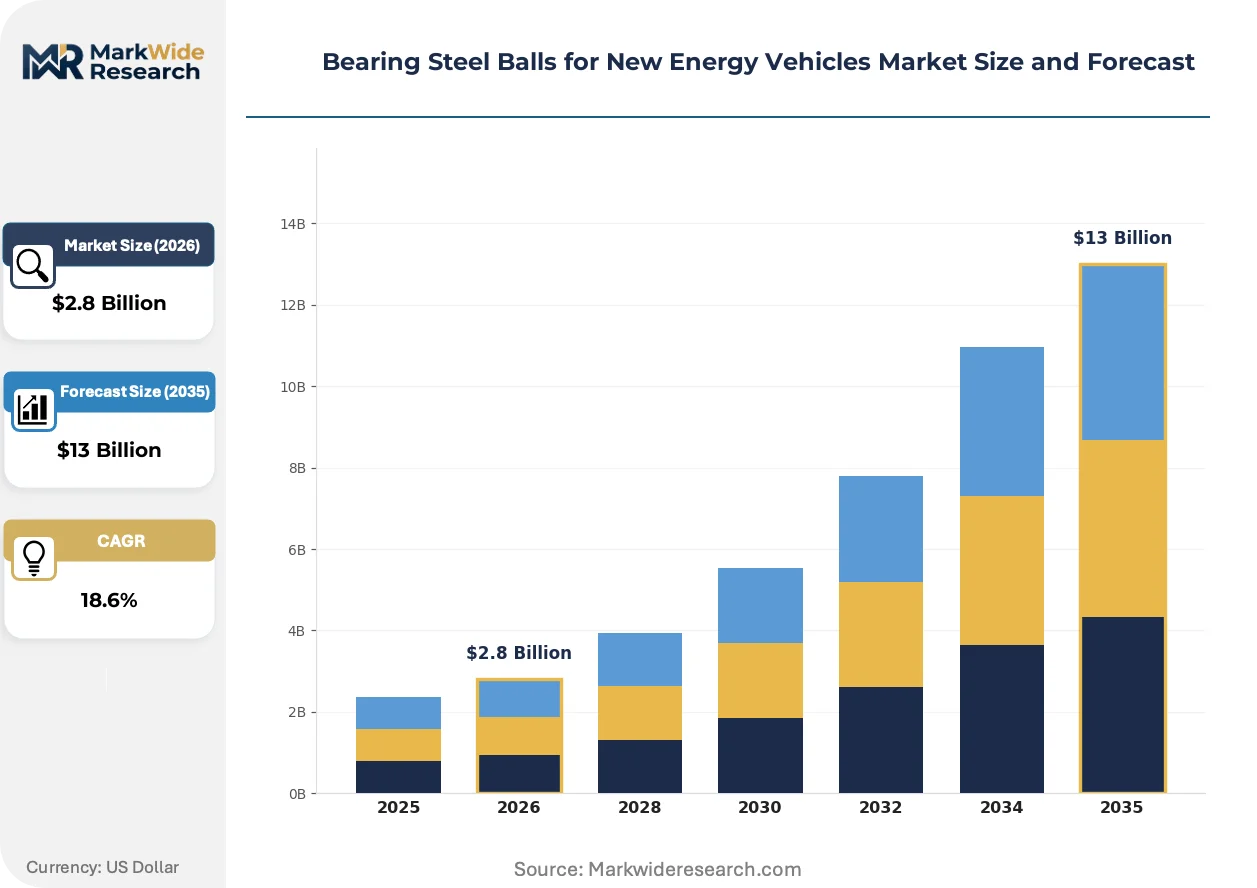
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Chrome Steel, Stainless Steel, Ceramic, Carbon Steel, Silicon Nitride Application: Electric Motors, Transmission Systems, Wheel Hubs, Gearboxes, Suspension Systems End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Maintenance Workshops Surface Treatment: Heat Treatment, Electroplating, Phosphating, Cryogenic Treatment, Shot Peening |
| Companies Covered | Tsubaki Nakashima, Amatsuji Steel Ball Manufacturing, Jiangsu Longteng Special Steel Group, Shandong Dong'e Steel Ball Group, SKF, NSK, NTN, Nachi-Fujikoshi, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bearing Steel Balls for New Energy Vehicles Market Trends and Innovations
Active material substitution and regulatory efficiency mandates are compressing traditional supply relationships while elevating performance verification requirements across the value chain.
Silicon nitride ceramic balls deliver thermal stability and electrical insulation properties essential for next-generation motor designs. OEMs adopting 20,000 RPM architectures are specifying ceramic spheres for rotor support bearings in preference to conventional chrome steel. This material transition is rendering obsolete the established heat treatment infrastructure that anchored prior cost structures.
REACH framework chemical restrictions and EU F-Gas Regulation motor efficiency tiers are cascading into bearing specification sheets. Industrial consequence includes mandatory lifecycle carbon documentation for imported components. Electric motor applications face the most concentrated compliance burden, with suppliers accelerating SAMR and METI parallel certification to maintain market access.
Direct OEM procurement channels are fragmenting as NEV platform proliferation splinters volume commitments across multiple motor suppliers. Tier-1 integrators are consolidating ball purchases into system-level contracts that bundle spheres with cages and lubrication. This pattern concentrates most visibly in China's Yangtze River Delta, where assembly plants negotiate master supply agreements covering complete bearing modules rather than commodity components.
Bearing Steel Balls for New Energy Vehicles Market Segmentation
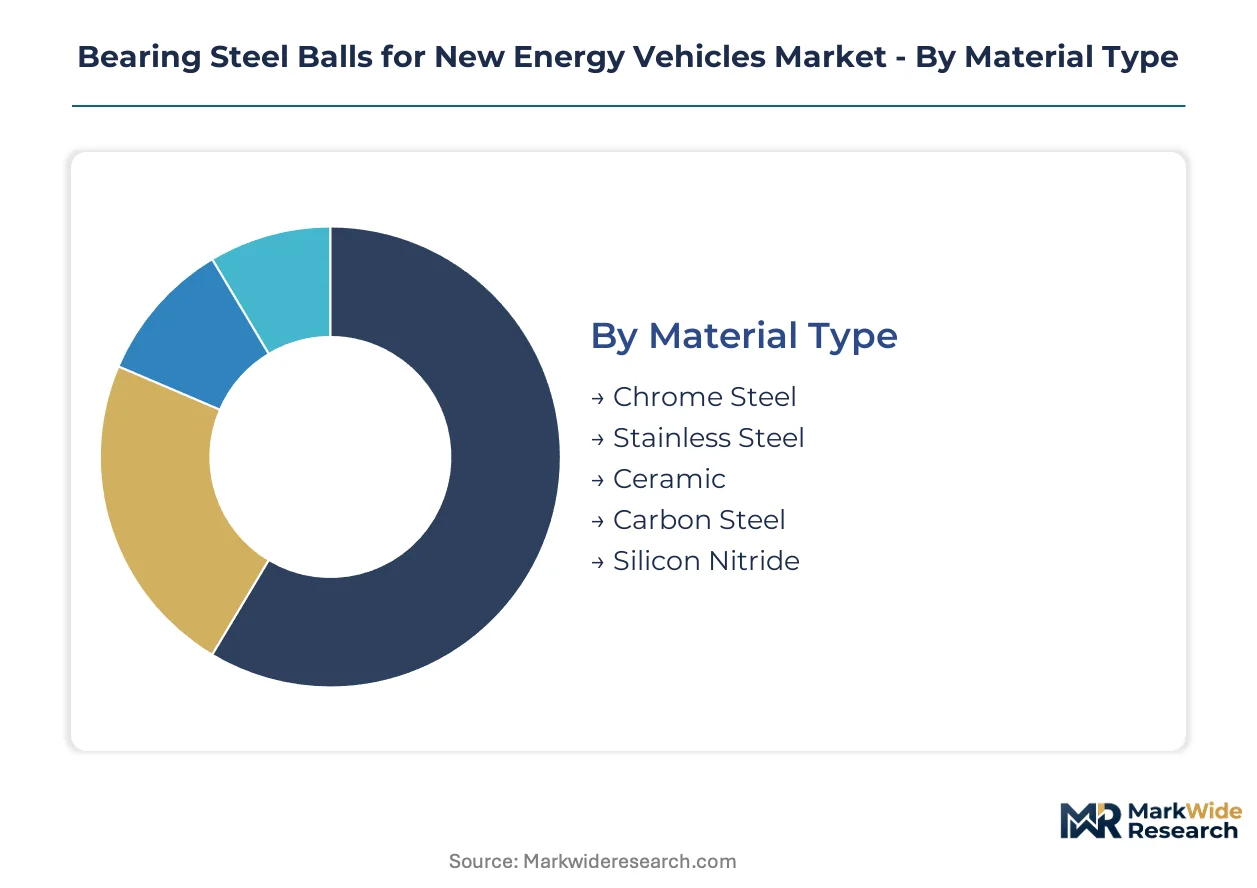
Segmentation in bearing steel balls for new energy vehicles reveals how material science, application severity, and supply chain position interact to create distinct margin pools. Understanding these divisions exposes where procurement power concentrates and where technical differentiation commands pricing leverage.
Material Type:
Mature chrome steel formulations anchor current volume while emerging ceramic alternatives capture design-forward motor architectures.
- Chrome Steel:Vacuum-degassed formulations dominate installed production capacity due to established heat treatment infrastructure and metallurgical-grade supply chains. Demand concentrates in transmission systems and wheel hub applications where rotational speeds remain below 15,000 RPM and cost sensitivity limits material experimentation.
- Silicon Nitride:Ceramic spheres deliver electrical insulation and thermal stability essential for 20,000 RPM motor architectures. OEMs in China's Yangtze River Delta manufacturing cluster are accelerating qualification timelines for silicon nitride rotor support bearings as motor speeds climb and efficiency mandates harden under EU F-Gas Regulation tiers.
- Stainless Steel:Corrosion-resistant formulations serve suspension systems and exposed wheel hub positions where environmental exposure exceeds chrome steel tolerance limits.
- Ceramic:Alumina and zirconia variants occupy niche positions in extreme-temperature gearbox applications requiring thermal expansion matching.
- Carbon Steel:Lower-cost formulations retain position in non-rotating structural bearing positions where load capacity outweighs fatigue life requirements.
Chrome Steel handles the majority of throughput; Silicon Nitride is the fastest mover on share.
Application:
Cost tier stratification separates high-precision motor applications from price-pressured transmission and chassis systems.
- Electric Motors:Rotor support bearings face the most severe performance specifications, requiring Grade 10 or finer sphericity tolerances below 0.25 micrometers. China's SAMR enforces GB standards metallurgical consistency for motor-grade balls, extending qualification timelines but creating compliance moats for certified suppliers.
- Transmission Systems:Planetary gear architectures impose less severe material specifications, allowing chrome steel dominance and competitive pricing pressure from integrated melt-to-ball producers.
- Wheel Hubs:Sealed bearing assemblies prioritize contamination resistance over rotational precision, favoring stainless steel and surface-treated carbon steel formulations.
- Gearboxes:Synchronizer and shift fork applications demand controlled surface hardness profiles achievable through heat treatment and cryogenic processing sequences.
- Suspension Systems:MacPherson strut and multi-link bearings prioritize corrosion resistance and impact load capacity over sustained high-speed operation.
Electric Motors concentrate the premium pricing tier; Gearboxes face the steepest cost-down pressure from vehicle assemblers.
End User Industry:
Customer type determines contract structure, with direct OEM procurement fragmenting as NEV platform proliferation splinters volume commitments.
- OEMs:Direct procurement channels from automotive manufacturers are consolidating toward system-level contracts bundling balls with cages and lubrication, particularly in China's Yangtze River Delta where integrated motor-gearbox assembly plants negotiate master supply agreements.
- Tier-1 Suppliers:Motor-gearbox integrators intermediate between ball producers and vehicle platforms, compressing supplier qualification timelines by demanding pre-assembled ball-and-cage modules.
- Aftermarket Providers:Service replacement demand from NEV fleets approaching warranty thresholds is creating secondary volume for precision grinding specialists with established metrology capabilities.
- Vehicle Assemblers:Final assembly plants maintain limited direct ball procurement, primarily for warranty service inventory and line-side replenishment.
- Maintenance Workshops:Independent repair channels source through distributor networks, with carbon border adjustment mechanisms beginning to shape import qualification criteria for EU-facing suppliers.
Tier-1 Suppliers intermediate the majority of contract value; Aftermarket Providers are expanding most quickly as early NEV fleets mature.
Surface Treatment:
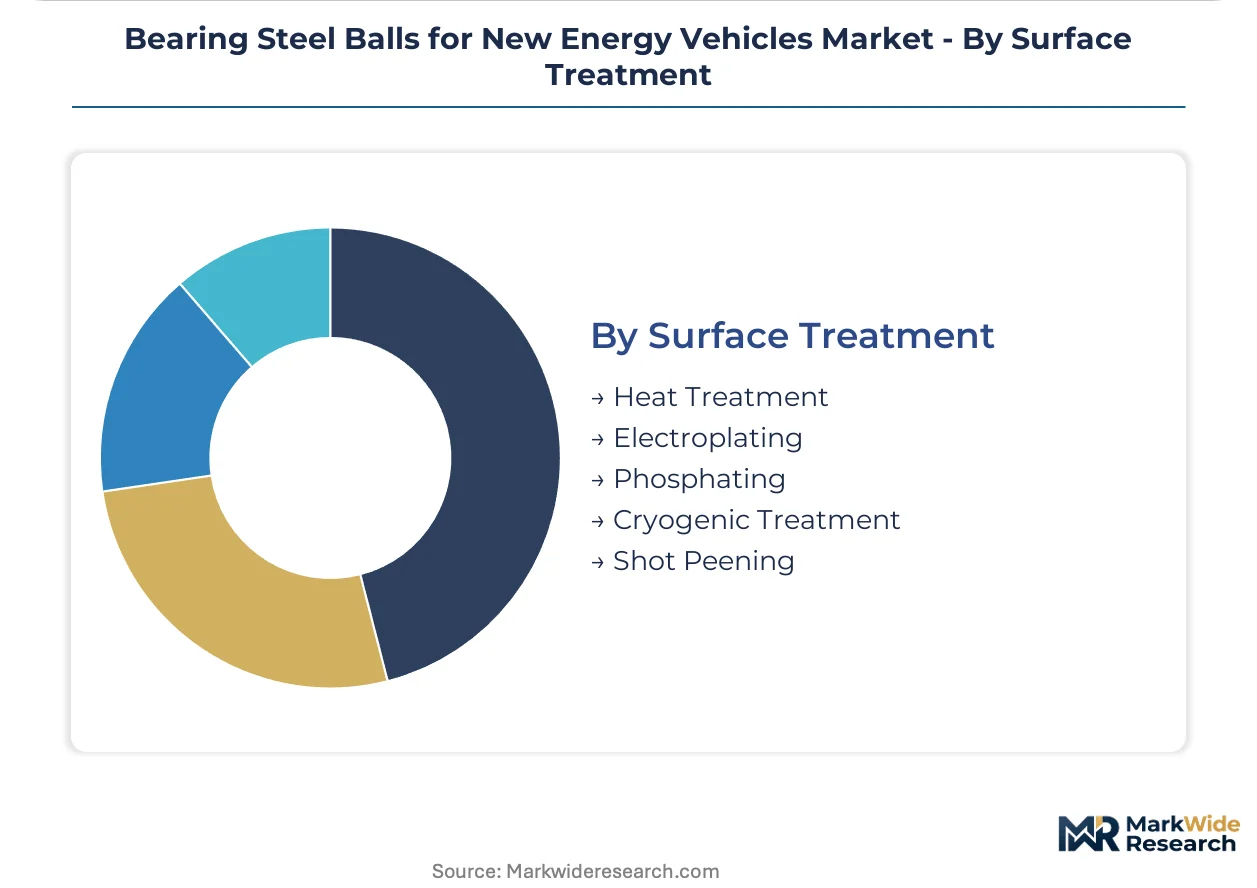
Supply concentration in heat treatment infrastructure is slowing adoption of alternative processing despite performance advantages.
- Heat Treatment:Austenitizing and tempering sequences dominate established capacity, with vacuum furnace availability constraining throughput expansion for Grade 10 and finer sphericity grades.
- Cryogenic Treatment:Deep-cold processing improves dimensional stability and wear resistance for high-speed spindle applications, though equipment scarcity limits geographic distribution of capable suppliers.
- Electroplating:Chrome and nickel deposition provides corrosion barriers for exposed suspension and wheel hub positions.
- Phosphating:Manganese and zinc phosphate conversion coatings improve lubricant retention in gearbox and transmission applications.
- Shot Peening:Controlled surface deformation induces compressive residual stresses that extend fatigue life in cyclic loading environments.
Heat Treatment commands the installed equipment base; Cryogenic Treatment is gaining adoption fastest among precision motor bearing specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex anchors Asia-Pacific supply chain throughput for precision bearing components, while Germany's Rhine-Alpine rail corridor links automotive assembly plants to Eastern European component suppliers. These infrastructure assets determine where procurement power concentrates and where supplier qualification timelines compress.
China
SAMR enforces GB standards metallurgical consistency for motor-grade bearing balls, extending supplier certification timelines. The Yangtze River Delta manufacturing cluster hosts integrated motor-gearbox assembly plants that negotiate master supply agreements for complete bearing modules rather than commodity spheres. Shanghai's port infrastructure enables just-in-time delivery to NEV production lines across Jiangsu and Zhejiang provinces.
Germany
KBA vehicle certification requirements cascade into bearing performance specifications for electric traction motors exported to EU markets. The EU F-Gas Regulation motor efficiency tiers accelerate demand for Grade 10 sphericity tolerances in high-speed spindle applications. Bavaria's automotive engineering corridor connects Munich-area motor developers to Stuttgart-based system integrators.
Japan
METI coordinates JIS standards alignment with NEV export destinations, creating compliance overlap for suppliers serving multiple markets. The Nagoya-Toyota industrial belt concentrates precision grinding capabilities for ceramic ball production. Osaka-based bearing specialists leverage established metrology infrastructure to serve Asian OEM qualification programs.
United States
NHTSA fuel economy standards indirectly shape motor efficiency mandates that flow into bearing specification requirements. The Detroit-to-Chicago manufacturing corridor anchors Midwest NEV assembly capacity. Michigan-based Tier-1 integrators are consolidating ball purchases into system-level contracts bundling spheres with lubrication systems.
South Korea
MFDS industrial quality frameworks intersect with automotive export requirements for bearing component traceability. The Busan-Ulsan heavy industry zone hosts steel processing capacity serving domestic NEV motor manufacturers. Seoul Capital Area engineering centers coordinate ceramic ball qualification for next-generation 20,000 RPM motor architectures.
Bearing Steel Balls for New Energy Vehicles Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: precision grinding specialists with heritage metrology capabilities, integrated melt-to-ball producers controlling upstream metallurgical inputs, and bearing system integrators extending into pre-assembled modules. Competitive moves center on ceramic ball capacity scaling and carbon footprint verification protocols for EU market access.
Among Japanese precision manufacturers, Tsubaki Nakashima and Amatsuji Steel Ball Manufacturing occupy positions within the heritage grinding specialist tier. Chinese integrated producers Jiangsu Longteng Special Steel Group and Shandong Dong'e Steel Ball Group exemplify the melt-to-ball archetype with domestic supply chain control. SKF represents the system integrator vector, extending bearing expertise into module-level supply relationships that compress customer qualification cycles.
| Leading Market Players |
|---|
| Tsubaki Nakashima |
| Amatsuji Steel Ball Manufacturing |
| Jiangsu Longteng Special Steel Group |
| Shandong Dong'e Steel Ball Group |
| SKF |
| NSK |
| NTN |
| Nachi-Fujikoshi |
| Schaeffler |
| Others |
Pricing and Supply Chain Analysis
Vacuum-degassed chrome steel melt capacity in China's Jiangsu and Shandong provinces anchors upstream supply concentration, directing margin capture toward Grade 10 sphericity specialists and ceramic ball producers serving 20,000 RPM motor architectures. Procurement power fragments across motor-gearbox integrators in the Yangtze River Delta, compressing price premiums for commodity-grade transmission balls while elevating pricing leverage for certified motor-grade suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates motor-grade silicon nitride from transmission chrome steel and structural carbon steel positions. Price differentiation hinges on SAMR certification status and volume commitment scale, with annual offtake agreements commanding 12-18% discounts against spot procurement. Cost compression in standard-grade chrome steel is intensifying because integrated melt-to-ball producers leverage captive metallurgical inputs. Tier-1 motor-gearbox integrators exhibit least price sensitivity due to system-level contract bundling, while aftermarket distributors face acute margin pressure from carbon border documentation requirements.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta motor-gearbox integrators are reshaping supplier cash flow profiles, with 90-120 day cycles now standard for certified ball producers. Geographic supply concentration centers on China, Japan, and Germany, with raw material dependencies drawing from metallurgical-grade chrome ore, high-purity silicon nitride powder, and vacuum furnace equipment. Single-region supplier concentration creates exposure to SAMR certification disruptions and carbon footprint verification delays. Distribution runs through Tier-1 bearing system integrators bundling balls with cages and lubrication modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NEV platform proliferation fragments procurement volumes across multiple motor suppliers, creating specialized niches for ceramic ball specialists and carbon-verified suppliers serving EU export markets.
For Market Incumbents: Entrench position through backward integration into vacuum-degassed steel melt capacity and accelerated silicon nitride ceramic ball production scaling. Ceramic substitution technology threatens chrome steel incumbents with stranded heat treatment assets. Priority lever: SAMR parallel certification with METI JIS alignment to compress multi-market qualification timelines. For New Entrants and Emerging Players: Aftermarket service replacement for early NEV fleets approaching warranty thresholds represents the most penetrable entry point, with precision grinding capabilities transferable from industrial spindle applications. Secondary opportunity sits with cryogenic treatment service providers addressing equipment scarcity in high-speed motor bearing specifications. Go-to-market angle: carbon footprint verification protocols aligned with EU border adjustment mechanisms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision grinding specialists possessing heritage metrology infrastructure but lacking ceramic ball capacity. Long-term viability over a 5-10 year window favors suppliers with verified carbon documentation and multi-standard certification overlap. Signal to watch: OEM direct procurement consolidation toward system-level module contracts in China's Yangtze River Delta cluster.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Nitride Capacity Buildout | Addresses 20,000 RPM motor insulation requirements under EU F-Gas Regulation tiers. |
| Carbon Footprint Verification Program | Positions suppliers favorably as EU border adjustment mechanisms harden import criteria. |
| Pre-Assembled Module Supply | Compresses Tier-1 customer qualification cycles by bundling balls with cages and lubrication. |
| SAMR-METI Parallel Certification | Creates compliance moats for multi-market access to China's NEV and Japanese export channels. |
| Cryogenic Treatment Service Expansion | Captures scarcity premium for dimensional stability in high-speed spindle applications. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 motor-gearbox procurement leads, vacuum furnace equipment specialists, and aftermarket service distributors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation drawing from SAMR GB standard filings, METI JIS coordination protocols, EU F-Gas Regulation tier documentation, and vehicle production databases. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Scenario-bracketing around motor speed adoption curves and ceramic ball substitution rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, application severity tier, end-user industry, and surface treatment process. CAGRs derived from slope-consistent growth trajectory analysis incorporating NEV platform rollout schedules, regulatory efficiency mandate timelines, and supplier capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in steel input costs, carbon border enforcement intensity, or NEV subsidy policy would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption rates and regulatory implementation schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Power Steering Oil Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Windshield Repair Kit Market