
 Flat Gaming Monitors Market | 2026-2036
Flat Gaming Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Gaming Monitors Market Insights
Casual home-office buyers are collapsing as the dominant buyer archetype in flat gaming monitors, while esports venues and competitive gamers command larger order volumes. Samsung Electronics leverages in-house OLED panel production to control supply timelines for premium tiers. ASUS specializes in ROG-branded display subsystems with factory-calibrated color accuracy for tournament standards. LG Electronics anchors its position through IPS Black technology leadership in the 240Hz segment.
Flat gaming monitors are non-curved display panels engineered for interactive entertainment, typically incorporating TN, IPS, or OLED matrices with response times under 1ms and refresh rates spanning 60Hz to 240Hz for frame-fluid rendering. OLED panels now capture the fastest expansion trajectory as burn-in mitigation algorithms and manufacturing yield improvements reduce unit costs. The 27-inch screen size dominates volume shipments, though 32-inch variants are gaining share among simulation and strategy gamers who prioritize field-of-view over frame-rate extremity. DisplayPort connectivity leads in premium configurations, while HDMI retains volume presence in console-adjacent segments.
EPA Energy Star specifications and EU Ecodesign requirements now mandate standby power thresholds and material disclosure for displays sold in the United States and European Union, compelling manufacturers to redesign power architectures. China's GB standards for electronic display energy efficiency, enforced by SAMR, create a parallel compliance track for brands serving domestic distribution channels. Stakeholders must monitor how regional efficiency mandates fragment certification burdens and whether refresh-rate marketing claims face tighter advertising scrutiny from the FTC and national consumer authorities.
Market Dynamics
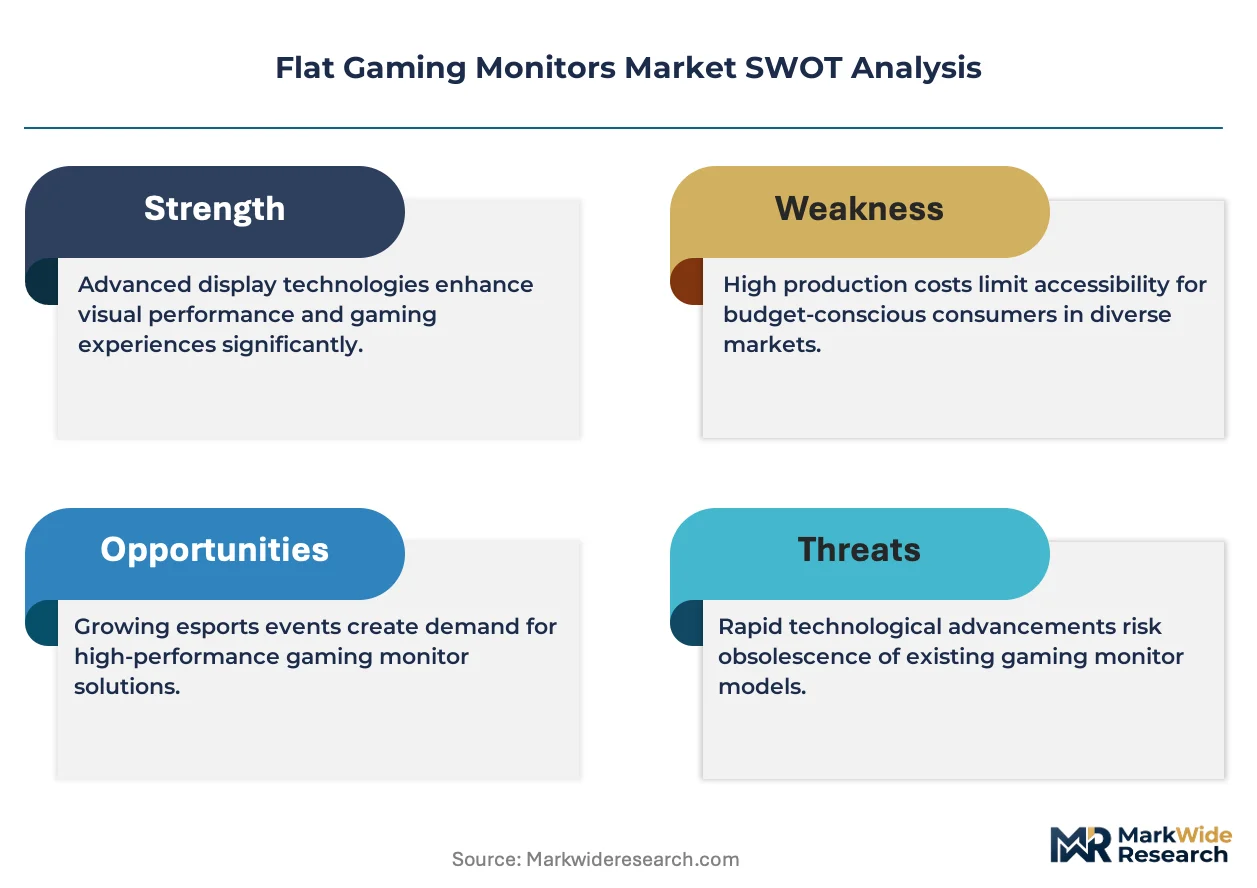
The transition from LCD to OLED panel architectures is compressing manufacturing timelines and redistributing margin pools across the display value chain, forcing incumbents to secure wafer supply or exit premium tiers entirely.
Growth Catalysts
- Esports venue procurement standards:Tournament operators now mandate 240Hz minimum refresh rates for official competition hardware, creating guaranteed offtake for high-performance panel tiers.
- EU Ecodesign standby power thresholds:Mandates below 0.5W standby consumption are accelerating power architecture redesigns that incidentally improve thermal performance for overclocked configurations.
- OLED manufacturing yield improvements:South Korean and Taiwanese fabs are reducing defect rates in vapor deposition processes, expanding addressable supply for mid-priced gaming segments.
Market Restraints
- Indium tin oxide supply concentration:Over 80% of refined indium originates from Chinese smelters, exposing transparent electrode costs to export quota volatility.
- Burn-in mitigation complexity:Pixel-shifting algorithms and luminance limiters add firmware development overhead that extends product validation cycles by 4-6 months.
- HDMI 2.1 licensing fees:Per-unit royalty structures from HDMI LA disproportionately burden sub-$300 price tiers where margin compression is already severe.
Strategic Opportunities
- Cloud gaming lounge chains in Southeast Asia:Indonesia and Vietnam are seeing unmet demand for 144Hz rental terminals that bypass individual ownership cost barriers.
- GB standards compliance as export gateway:SAMR energy efficiency certifications for the China domestic market are becoming de facto prerequisites for brands seeking volume manufacturing partnerships.
- AI-driven adaptive refresh:Frame-rate prediction algorithms paired with variable refresh rate panels are opening premium positioning for machine-learning-enhanced display subsystems.
Industry Challenges
- Color calibration technician scarcity:Factory-level Delta-E certification requires specialized spectrophotometry expertise that panel integrators struggle to staff at scale.
- Dual-certification overhead:Simultaneous EPA Energy Star and EU Ecodesign compliance demands parallel testing streams that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Gaming Monitors Market |
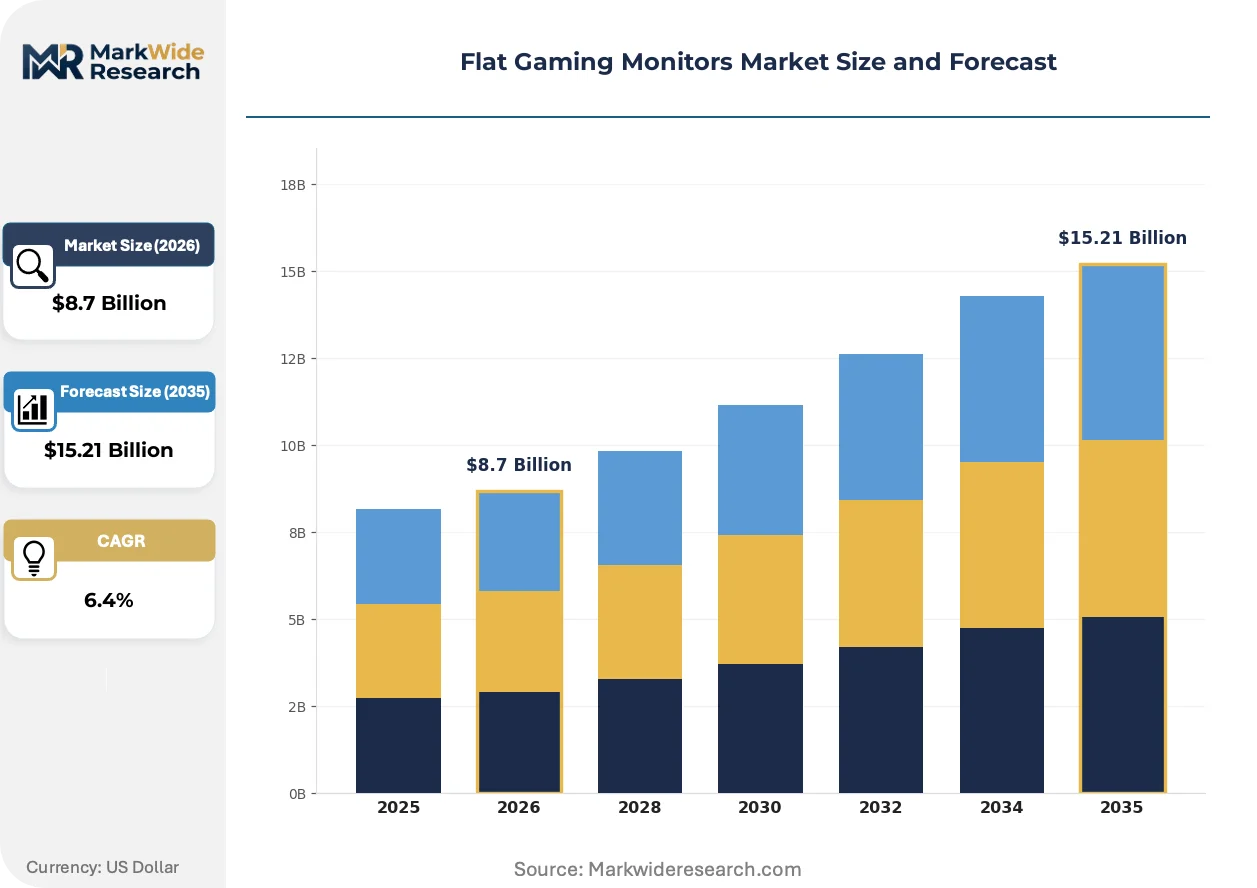
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, LCD, QLED Screen Size: 24 Inches, 27 Inches, 32 Inches, 35 Inches Refresh Rate: 60Hz, 120Hz, 144Hz, 240Hz Connectivity: HDMI, DisplayPort, USB-C, VGA |
| Companies Covered | ASUS, Samsung Electronics, Acer, LG Electronics, Dell Technologies, MSI, BenQ, AOC International, ViewSonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Gaming Monitors Market Trends and Innovations
Panel technologies and connectivity standards are undergoing simultaneous transition, with manufacturing investments chasing performance specifications that outpace current software utilization.
OLED is supplanting IPS Black in the 240Hz premium tier as burn-in mitigation algorithms reach commercial maturity. Esports tournament operators are specifying OLED for flagship competition stations despite 15-20% cost premiums. The technology is compressing LCD fab utilization rates and forcing accelerated depreciation schedules on legacy Gen 8.5 lines.
EPA Energy Star 8.0 specifications now mandate active-mode power metrics alongside standby thresholds, compelling power supply redesigns across all import portfolios. Display manufacturers serving the United States market are consolidating SKU variants to reduce certification fragmentation. The 27-inch segment bears the heaviest compliance burden due to its volume concentration.
Internet cafe chains in China are consolidating procurement through direct manufacturer contracts, bypassing traditional distribution tiers. ASUS and domestic brands like HKC are establishing dedicated fleet-sales divisions to capture this channel shift. The procurement model is most visible in tier-two cities where cafe density supports 500-plus unit single orders.
Flat Gaming Monitors Market Segmentation
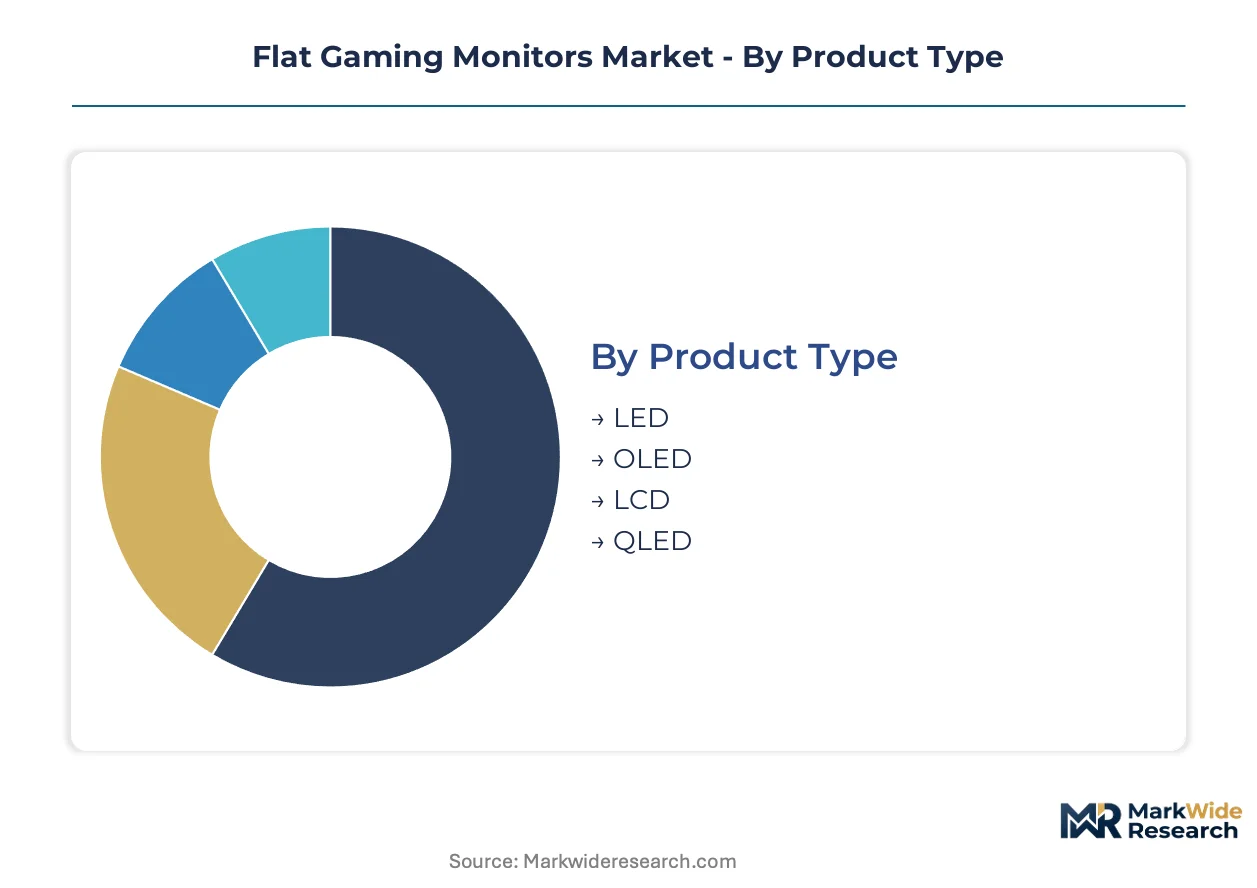
Flat gaming monitors fragment across four technical dimensions that determine pricing architecture and procurement patterns. Panel technology and refresh rate specifications dominate B2B purchasing decisions for esports venues, while screen size and connectivity protocols shape consumer channel inventory. Understanding these segment boundaries reveals where margin pools concentrate and which specifications face commoditization pressure.
Product Type:
OLED and QLED variants flow predominantly through export channels serving North American and European premium tiers, while LED and LCD volumes concentrate in domestic Chinese internet cafe procurement.
- OLED:Self-emissive organic compounds deliver per-pixel dimming with sub-1ms response times and infinite contrast ratios. Esports tournament operators in South Korea and Germany specify OLED for flagship competition stations despite cost premiums, driven by burn-in mitigation algorithm maturity that extends operational lifespan.
- QLED:Quantum dot-enhanced LED backlights expand color gamut coverage to DCI-P3 standards without OLED's burn-in risk. North American retailers stock QLED SKUs heavily for enthusiast consumers prioritizing brightness consistency over absolute black levels.
- LED:Edge-lit and direct-lit configurations serve volume-tier pricing with 60Hz-144Hz refresh ranges.
- LCD:TN and IPS subvariants retain presence in emerging market console-adjacent segments where input lag tolerance is higher.
LED commands the established base. The steepest expansion runs through OLED.
Screen Size:
Procurement patterns split between fleet buyers standardizing on 27-inch formats and individual purchasers upsizing to 32-inch and 35-inch variants for simulation immersion.
- 27 Inches:The dominant volume format balances pixel density at 1440p resolution with desk-space economy. Chinese internet cafe chains execute 500-plus unit orders exclusively in this size, treating it as the default fleet specification for competitive gaming terminals.
- 32 Inches:4K-native panels cater to flight simulator and strategy gamers prioritizing field-of-view over frame-rate extremity. North American and German consumers drive demand for this segment through specialist retailers serving simulation enthusiasts.
- 24 Inches:Compact format retains relevance for dormitory and space-constrained Asian urban environments.
- 35 Inches:Ultrawide 21:9 aspect ratio serves racing simulation and cinematic gaming applications with premium positioning.
27-inch configurations anchor current volume. The steepest expansion trajectory belongs to 32-inch formats.
Refresh Rate:
Cost tier differentiation sharpens above 144Hz, where panel controller complexity and yield requirements fragment manufacturing economics.
- 240Hz:Tournament-grade panels require specialized scaler ASICs and driver ICs with strict frame-time consistency validation. South Korean esports venue operators mandate this tier for official competition hardware, creating guaranteed offtake that stabilizes fab loading for premium panel tiers.
- 144Hz:The mainstream enthusiast standard balances motion clarity with GPU accessibility. Southeast Asian cloud gaming lounges in Indonesia and Vietnam specify 144Hz terminals for rental deployment, bypassing individual ownership cost barriers.
- 120Hz:Console-optimized format aligns with PlayStation and Xbox output capabilities.
- 60Hz:Budget tier retains presence in emerging market general-purpose displays with gaming-adjacent marketing.
144Hz holds the volume center. 240Hz is climbing the fastest through esports procurement standardization.
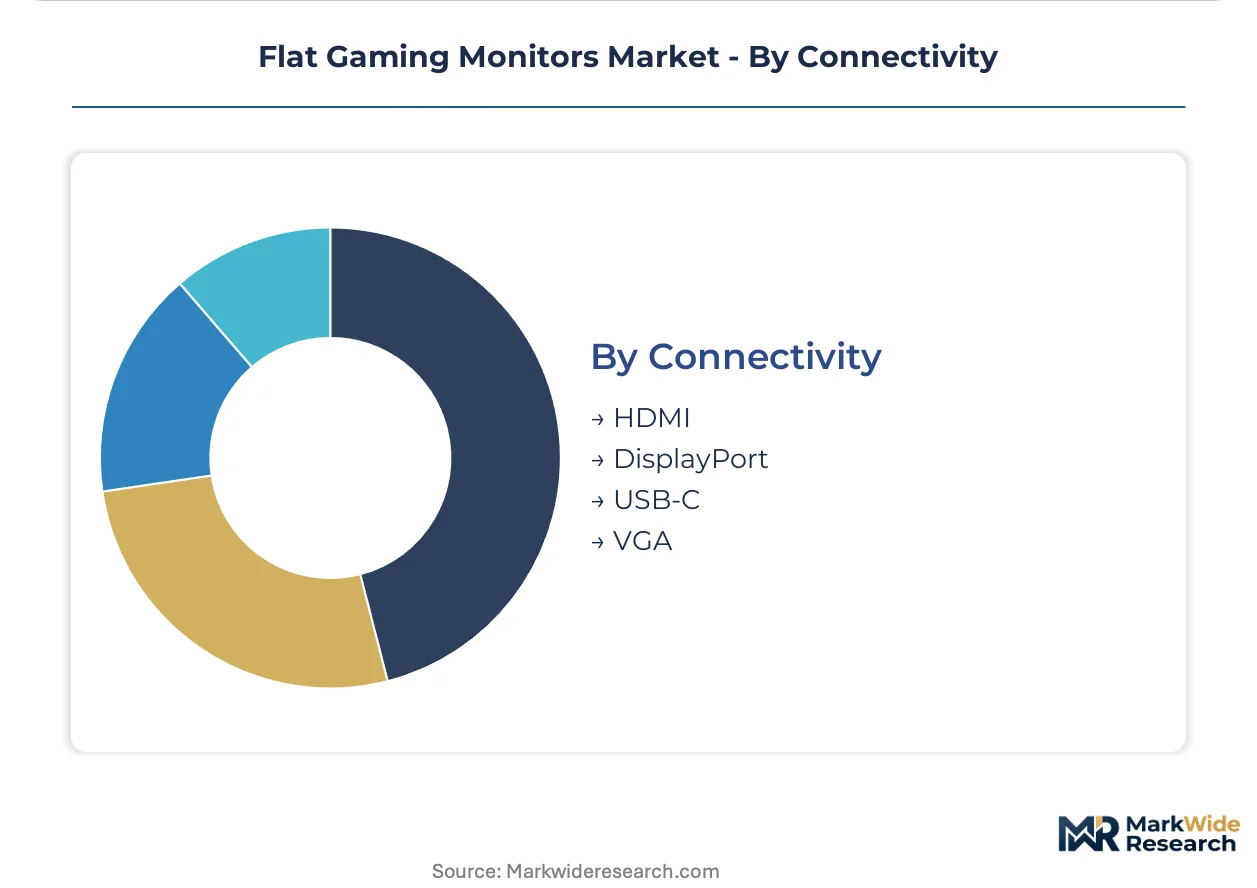
Connectivity:
Protocol selection determines regional certification burdens and royalty cost structures that reshape margin distribution.
- DisplayPort:VESA-standard signaling dominates PC-centric configurations with native adaptive sync support and uncompressed high-bandwidth transmission. European and North American premium SKUs lead with DisplayPort 1.4 and 2.1 implementations to avoid HDMI licensing fee stacking.
- HDMI:Universal compatibility drives inclusion across all price tiers despite HDMI LA per-unit royalties that disproportionately compress sub-$300 margins. Console-adjacent segments in Japan and North America require HDMI 2.1 for 4K 120Hz compatibility.
- USB-C:Single-cable docking for laptop gaming gains traction in corporate and mobile-first consumer segments.
- VGA:Legacy analog support persists only in lowest-cost emerging market SKUs facing rapid phase-out.
HDMI retains volume presence. DisplayPort is gaining share fastest in premium configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex handles the largest share of display panel exports, underwriting China's dominance in flat gaming monitor manufacturing and distribution networks serving Asian and European markets.
China
Domestic internet cafe chains in Chengdu and Wuhan execute 500-plus unit procurement orders for 27-inch 144Hz terminals, bypassing traditional distribution tiers. SAMR enforces GB standards for electronic display energy efficiency that create parallel compliance tracks for brands serving domestic channels. Display panel fabs in Suzhou and Hefei are expanding OLED vapor deposition capacity to serve mid-priced gaming segments.
South Korea
Esports venue operators in Seoul and Busan mandate 240Hz OLED panels for official competition hardware, creating guaranteed offtake that stabilizes premium fab loading. MFDS coordinates with industry associations on electromagnetic compatibility standards for gaming peripherals. Samsung Display's Tangjeong complex anchors domestic OLED wafer supply for captive and external monitor brands.
United States
Specialist retailers in California and Texas drive 32-inch 4K panel demand among flight simulation enthusiasts prioritizing field-of-view specifications. EPA Energy Star 8.0 mandates active-mode power metrics alongside standby thresholds below 0.5W, compelling power supply redesigns across import portfolios. Seattle-area cloud gaming infrastructure providers are testing adaptive refresh algorithms for latency-sensitive streaming applications.
Germany
Tournament operators in Cologne and Hamburg specify OLED displays for flagship esports competition stations despite cost premiums, validating burn-in mitigation algorithm maturity. EU Ecodesign requirements enforce material disclosure and standby power thresholds that fragment certification burdens for non-EU manufacturers. Munich-based system integrators are consolidating procurement for corporate gaming lounge deployments.
Japan
Console-adjacent segments in Tokyo and Osaka require HDMI 2.1 compatibility for PlayStation and Xbox output capabilities, preserving HDMI's volume presence despite royalty cost structures. METI guidelines on display energy efficiency inform domestic retailer stocking decisions. Osaka-based electronics distributors are expanding 120Hz inventory for hybrid work-gaming consumer profiles.
Flat Gaming Monitors Market Competitive Landscape
Concentration sits with diversified electronics conglomerates controlling captive panel supply and specialized gaming peripheral vendors with factory-calibration expertise. The vendor base spans three tiers: integrated display manufacturers with in-house OLED wafer production, monitor assemblers sourcing panels from Taiwanese and Korean fabs, and regional brands serving fleet procurement channels. Strategic moves center on securing long-term wafer supply agreements and establishing dedicated esports venue sales divisions.
Among Asia-Pacific-based conglomerates, Samsung Electronics and LG Electronics anchor the integrated manufacturing tier through captive OLED panel production. ASUS exemplifies the specialized gaming peripheral archetype through ROG-branded display subsystems. These three companies occupy positions that reflect the industry's bifurcation between supply-chain control and tournament-standard calibration capabilities.
| Leading Market Players |
|---|
| ASUS |
| Samsung Electronics |
| Acer |
| LG Electronics |
| Dell Technologies |
| MSI |
| BenQ |
| AOC International |
| ViewSonic |
| Others |
Pricing and Supply Chain Analysis
Gen 8.5 LCD fab utilization compression in Taiwan and South Korea is concentrating wafer supply control among integrated OLED producers, simultaneously elevating price floors for premium tiers and squeezing margin pools for panel assemblers dependent on external sourcing.
Pricing Analysis
Volume-discount tiering structures separate internet cafe fleet procurement from individual retail channels, with 500-plus unit orders commanding 12-18 point differentials off list pricing. Certification-grade differentiation between EPA Energy Star tiers and SAMR GB standards compliance creates parallel pricing tracks for export versus domestic Chinese markets. Cost compression in sub-$300 HDMI 2.1-inclusive SKUs is intensifying because per-unit royalty stacking erodes already thin assembler margins. Esports venue operators demonstrate lowest price sensitivity, prioritizing 240Hz OLED burn-in warranties over unit economics.
Supply Chain Analysis
Strategic stockpiling of indium tin oxide feedstock has replaced just-in-time preferences among Taiwanese panel integrators facing Chinese export quota volatility. Wafer supply concentrates in South Korea's Tangjeong complex and Suzhou-Hefei corridors, with vapor deposition equipment lead times extending procurement horizons. Transparent electrode costs draw from refined indium originating at Chinese smelters, creating single-source vulnerability for transparent conductor layers. Distribution runs through Shenzhen port consolidation for Asian and European markets, while North American volumes bypass through direct fab-to-fulfillment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive sync ecosystem interoperability is shifting competitive advantage toward scaler ASIC developers, as variable refresh rate standardization across GPU architectures creates platform lock-in effects previously absent from display hardware.
For Market Incumbents: Compound captive OLED wafer supply through long-term Tangjeong and Hefei fab offtake agreements to defend against emerging QLED entrants exploiting quantum dot brightness consistency. Prioritize factory-level Delta-E certification investment to maintain tournament-standard positioning as esports operators consolidate procurement around pre-calibrated fleet specifications. For New Entrants and Emerging Players: Cloud gaming lounge hardware-as-a-service gaps in Indonesia and Vietnam represent the most penetrable white-space, where 144Hz rental terminal deployment bypasses individual ownership cost barriers. Pursue direct manufacturer contracts with tier-two Chinese internet cafe chains, leveraging SAMR GB certification as de facto partnership prerequisites for volume manufacturing access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among esports venue fleet operators with multi-year refresh cycles and standardized procurement protocols. Long-term viability across the analysis window favors acquisition targets with backward integration into panel controller ASIC design or established spectrophotometry calibration capabilities. Watch for HDMI LA royalty structure revisions as the inflection signal indicating margin relief or further compression in volume tiers.| Strategic Initiative | Industry Significance |
|---|---|
| OLED Wafer Supply Agreement | Secures Tangjeong or Hefei fab capacity against competitor allocation priority. |
| Esports Venue Sales Division | Captures 240Hz tournament-grade procurement standardization in Seoul and Cologne markets. |
| GB Standards Certification Investment | Enables SAMR-compliant domestic Chinese distribution and manufacturing partnerships. |
| Adaptive Refresh Algorithm Development | Positions machine-learning-enhanced display subsystems for cloud gaming infrastructure providers. |
| Power Architecture Redesign | Meets EPA Energy Star 8.0 active-mode mandates for United States import portfolios. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs export records, and EPA Energy Star certification databases. Interviews with display panel procurement managers at esports venue operators, fab planning executives at Taiwanese and Korean manufacturers, and internet cafe chain fleet buyers informed demand-side assumptions. Top-down market sizing triangulates against bottom-up panel shipment aggregation across OLED, QLED, LED, and LCD technology tiers.
Segmentation dimensions modeled include panel technology architecture, refresh rate specification bands, screen size formats, and connectivity protocol configurations across the projection horizon. CAGRs derive from elasticity-adjusted price-quantity relationships and technology transition curves for OLED yield improvement trajectories. Forecast inputs incorporate esports tournament hardware standardization timelines and regional energy efficiency mandate enforcement patterns.
Forecasts assume regulatory continuity in EPA Energy Star, EU Ecodesign, and SAMR GB standards regimes; material policy shifts would require re-modeling active-mode power thresholds or standby consumption limits. Burn-in mitigation algorithm efficacy and indium export quota volatility represent specific risk factors that could revise volume and value trajectories. Revision becomes warranted when OLED manufacturing yield improvement rates cross below vapor deposition defect reduction thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Southeast Asia Gaming Market
Gaming
Virtual Sports Market
Gaming
Cloud Gaming Market
Gaming
Connected Game Console Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Global Gaming Market
Gaming
Game Applications Market
Gaming
AAA Games Market
Gaming
France Online Gambling Market
Gaming
Casino Gaming Equipment Market
Gaming
Mobile Game Controller Market
Gaming
VR Melee Games Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Asia-Pacific Video Game Software Market
Gaming
Latin America Mobile Gaming Market
Gaming
VR Gaming Accessories Market