
 Playstation Network (PSN) Market | 2026-2036
Playstation Network (PSN) Market Size, Share, and Industry Trends Forecast 2026-2036
Playstation Network (PSN) Market Insights
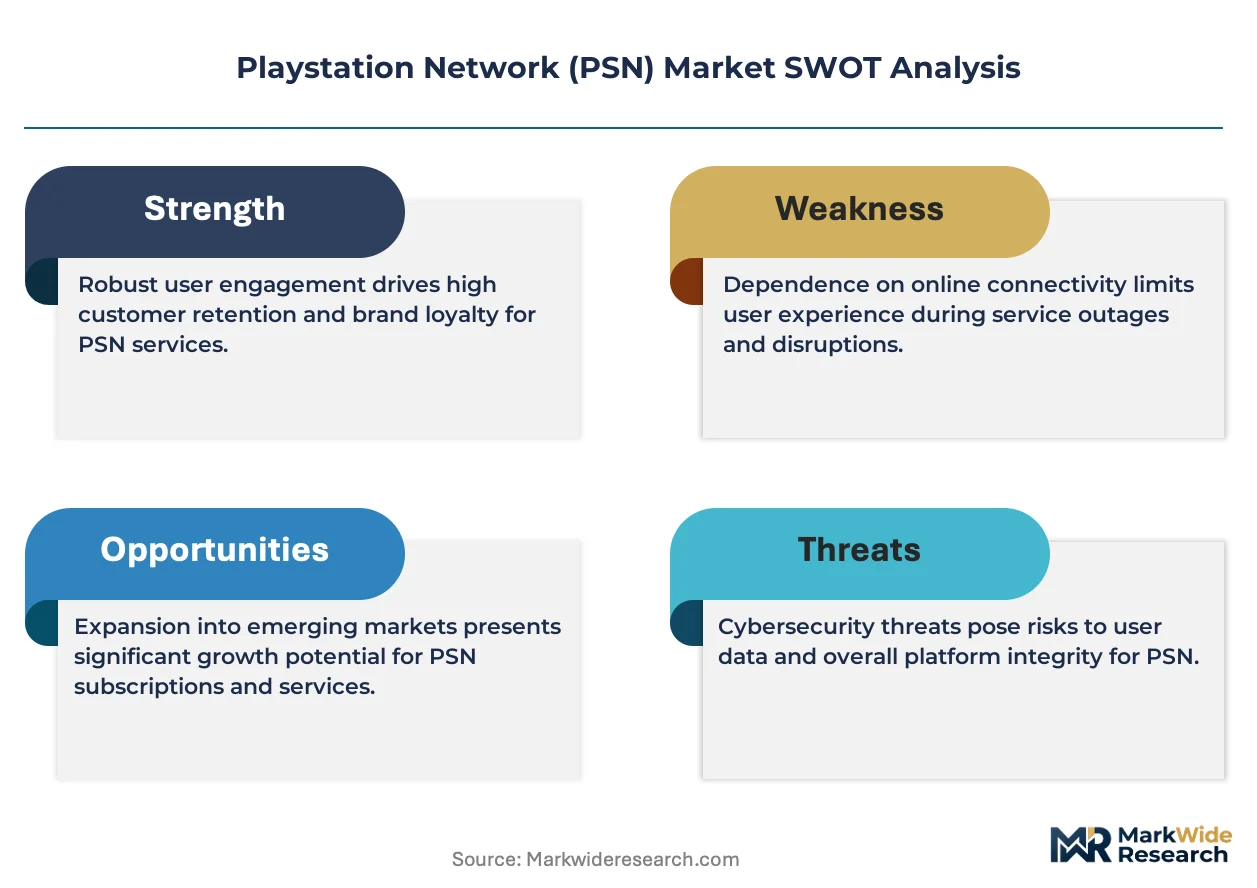
Subscription bundling is recalibrating buyer choice across the Playstation Network ecosystem, as Sony Interactive Entertainment consolidates multiplayer access, cloud streaming, and monthly game catalogs into tiered membership structures. Microsoft competes through cross-platform subscription integration that extends Game Pass reach beyond console boundaries. Nintendo anchors its digital strategy around family-oriented content libraries that resist direct feature parity with rival platforms.
Playstation Network constitutes a digital distribution and online multiplayer infrastructure delivering interactive entertainment through proprietary servers, content delivery networks, and digital rights management protocols supporting 4K streaming and low-latency gameplay. The platform serves commercial purposes spanning game sales, recurring subscription revenue, and microtransaction facilitation across console, mobile, and PC endpoints. Subscription services generate the most predictable revenue streams while game streaming represents the fastest-expanding segment as broadband infrastructure improves. Digital content maintains mature margin pools through downloadable add-ons and cosmetic microtransactions that sustain engagement between major releases.
Japan's Personal Information Protection Commission, the United Kingdom's Information Commissioner's Office under GDPR-aligned frameworks, and the United States Federal Trade Commission each scrutinize digital platform pricing transparency and data handling practices that affect PSN operations. These regulators shape demand by mandating clearer disclosure of recurring charges and restricting certain monetization mechanics targeted at younger users. Stakeholders must monitor evolving classification standards for loot boxes and subscription auto-renewal requirements as enforcement patterns diverge across these jurisdictions.
Market Dynamics
Sony Interactive Entertainment's consolidation of multiplayer access, cloud streaming, and monthly game catalogs into tiered membership structures is recalibrating buyer choice across the Playstation Network ecosystem. This bundling strategy compresses standalone transaction revenue while anchoring lifetime value through recurring subscriptions.
Growth Catalysts
- Cloud gaming infrastructure expansion:Broadband improvements in fiber-optic and 5G networks enable low-latency 4K streaming to console, mobile, and PC endpoints, expanding addressable audiences beyond hardware ownership constraints.
- GDPR-aligned disclosure mandates:The United Kingdom's Information Commissioner's Office and Japan's Personal Information Protection Commission enforce clearer recurring charge transparency, reducing subscription friction and building consumer trust in auto-renewal models.
- First-party content prioritization:Sony Interactive Entertainment's live-service game development concentrates development resources on persistent multiplayer titles that sustain microtransaction revenue between major releases.
Market Restraints
- Data center energy costs:Cloud gaming server farms face electricity price volatility that compresses margins on streaming infrastructure investments.
- Regulatory fragmentation:Divergent loot box classification standards across the United States Federal Trade Commission, United Kingdom ICO, and Japanese PIPIC create compliance complexity for cosmetic microtransaction design.
- Subscription fatigue threshold:Consumer tolerance for recurring entertainment charges faces pressure from competing video, music, and gaming services, capping per-household spending ceilings.
Strategic Opportunities
- Underpenetrated PC distribution:Playstation Network's recent PC porting strategy opens revenue from Steam and Epic Games Store audiences previously unreachable through console exclusivity.
- Mobile endpoint expansion:Cloud streaming to iOS and Android devices captures commuter and casual gaming sessions without dedicated hardware investment.
- FTC auto-renewal enforcement:Clearer cancellation flow requirements reduce churn from accidental renewals while building long-term subscriber trust through transparent billing practices.
Industry Challenges
- Live-service talent scarcity:Persistent multiplayer game development requires specialized server engineering and community management expertise that competes with technology sector hiring.
- Cross-platform certification complexity:Sony Interactive Entertainment must coordinate security patches and content updates across PlayStation 5, PlayStation 4, PC, and mobile endpoints with divergent technical requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Playstation Network (PSN) Market |
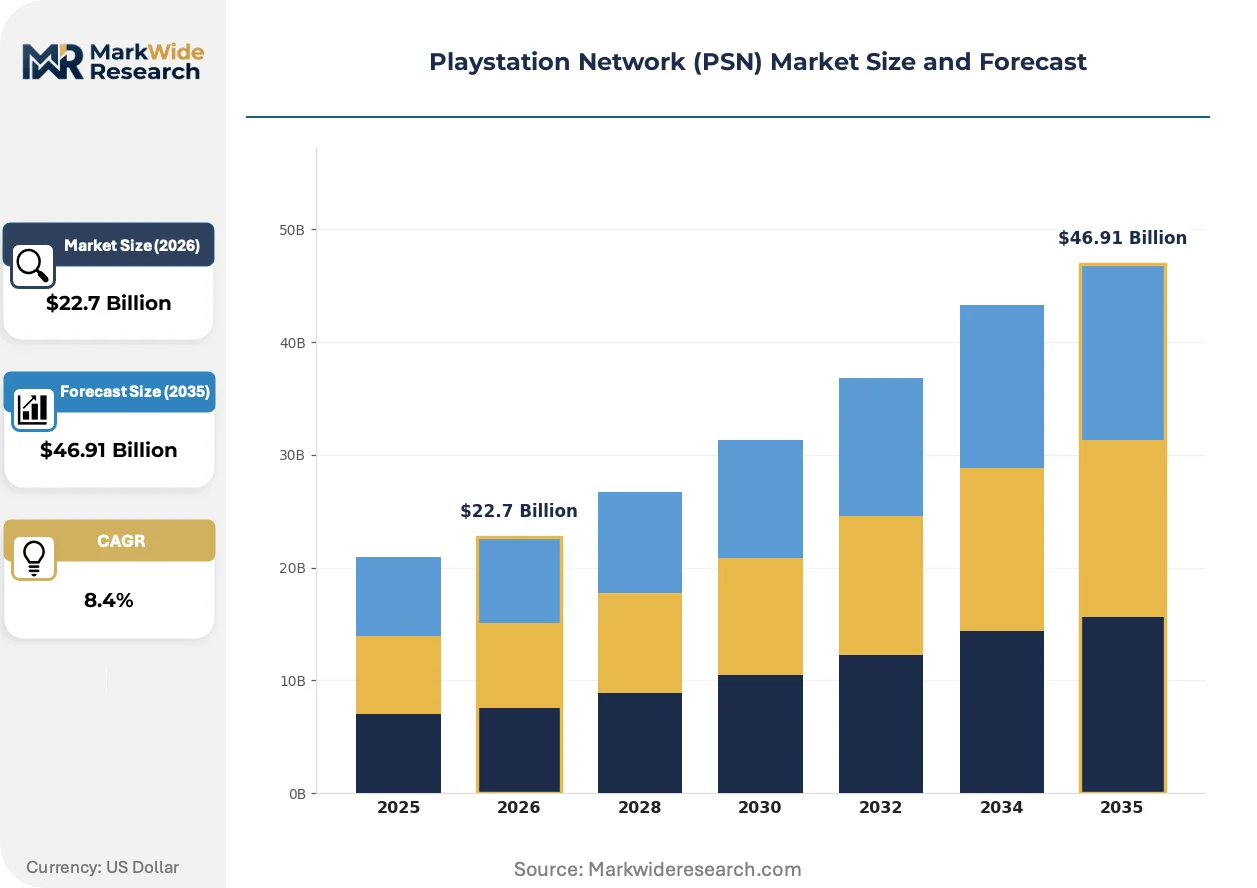
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $46.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Digital Content, Game Streaming, Multiplayer Access End User: Casual Gamers, Hardcore Gamers, Families, Professional Players Content Type: Games, Add-Ons, Themes, Demos Device Type: Console, Mobile, PC, VR Headsets |
| Companies Covered | Sony Interactive Entertainment, Microsoft, Nintendo, Electronic Arts, Activision Blizzard, Ubisoft, Take-Two Interactive, Capcom, Square Enix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Playstation Network (PSN) Market Trends and Innovations
Cloud-native game architecture is rewriting how development studios approach scalability, rendering fidelity, and player persistence. This technological pivot demands new skill sets while compressing traditional console generation cycles.
Adaptive bitrate streaming technology is rewriting content delivery economics for Playstation Network. Sony Interactive Entertainment deploys machine learning-driven compression to maintain visual quality across variable broadband conditions. Mid-tier internet subscribers in suburban United States markets adopt cloud gaming at accelerating rates as latency thresholds drop below 20 milliseconds.
The United Kingdom's Information Commissioner's Office enforcement of GDPR-aligned subscription transparency rules is tightening auto-renewal disclosure requirements. Digital platforms must present cancellation options with equivalent prominence to enrollment flows. Younger user segments in European markets experience reduced accidental subscription lock-in, shifting developer focus toward voluntary retention mechanics.
Consumption patterns among Playstation Network users are fragmenting across synchronous and asynchronous engagement models. Single-player narrative releases now coexist with daily-login live-service titles that monetize through battle passes and cosmetic stores. Japanese and United Kingdom markets show strongest adoption of hybrid engagement, where subscribers maintain both catalog exploration and persistent multiplayer investment simultaneously.
Playstation Network (PSN) Market Segmentation
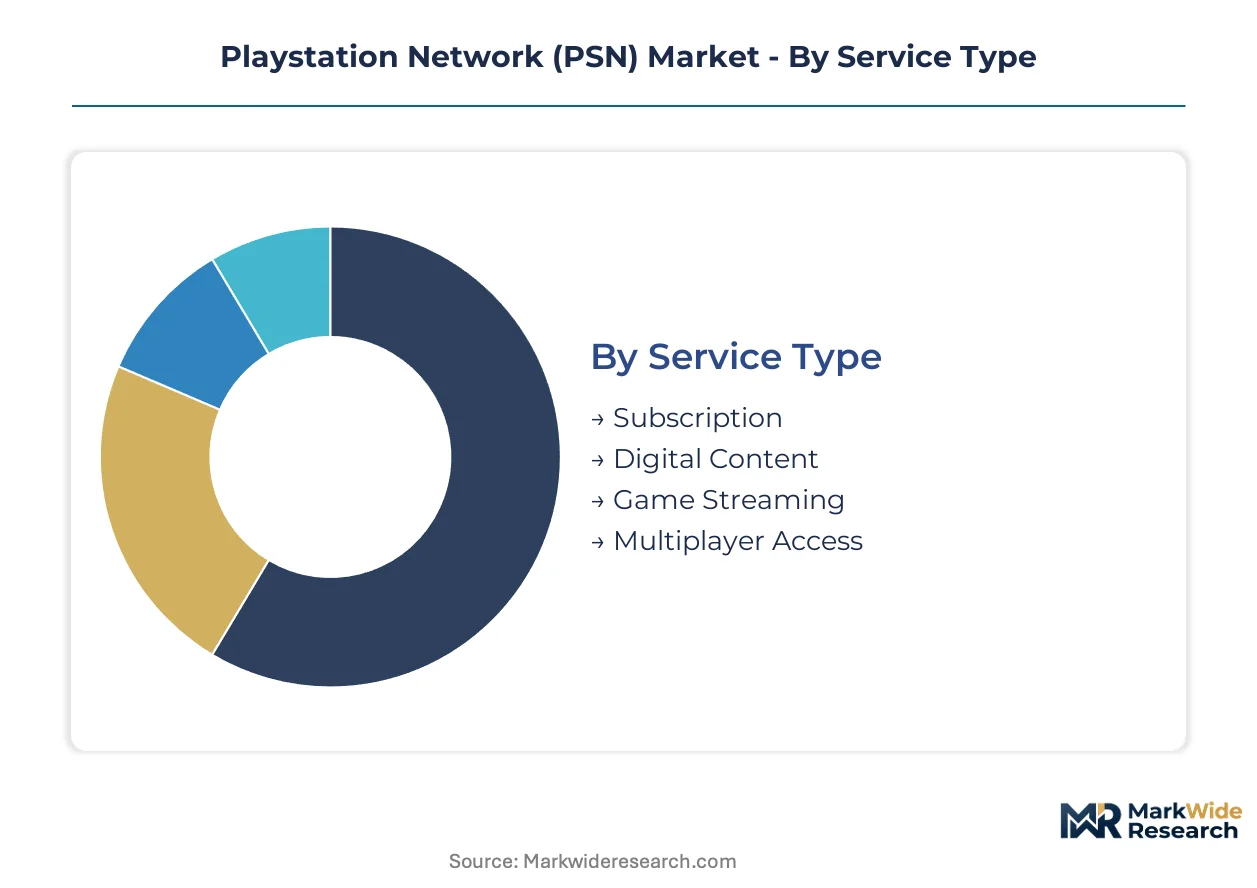
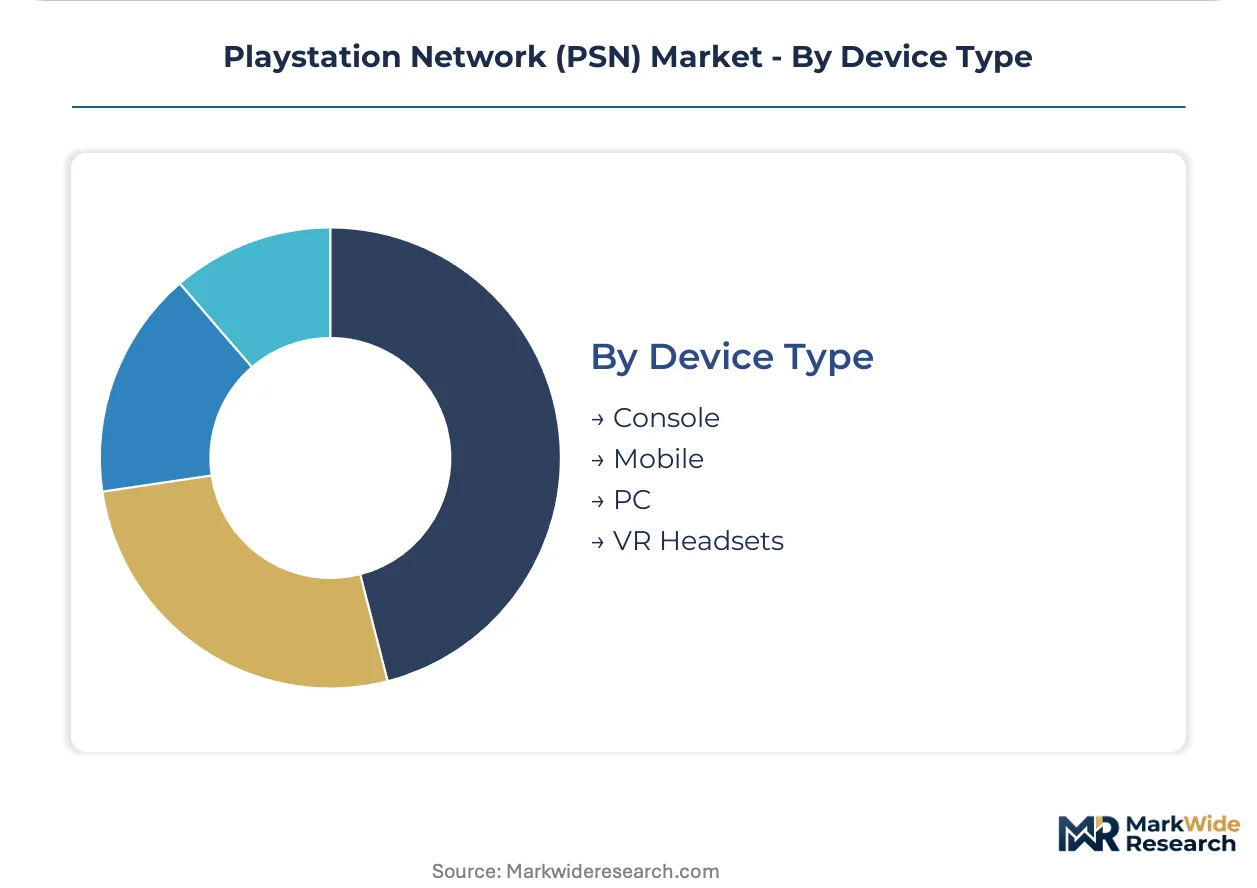
Playstation Network's revenue architecture fragments across service delivery models, user engagement intensity, content formats, and hardware endpoints. Understanding these divisions reveals where Sony Interactive Entertainment allocates server infrastructure and licensing investments.
Service Type:
Capital intensity peaks in streaming infrastructure deployment, where server farm investments and content delivery network expansion consume the largest upfront outlays.
- Subscription:Tiered membership structures consolidate multiplayer access, cloud streaming, and monthly game catalogs into recurring revenue streams. United States households concentrate demand for premium tiers bundling 4K streaming, driven by broadband penetration above 100 Mbps.
- Digital Content:Individual game sales and downloadable add-ons generate transactional revenue with lower infrastructure burden per dollar. Japanese consumers drive disproportionate volume for single-purchase narrative titles, constrained by subscription fatigue thresholds in saturated entertainment markets.
- Game Streaming:Cloud-native delivery to mobile and PC endpoints requires persistent server capacity. United Kingdom adoption accelerates as fiber-optic latency drops below 20 milliseconds.
- Multiplayer Access:Standalone online connectivity fees anchor entry-level engagement. Casual segments in suburban United States markets sustain this tier's volume.
Most installed capacity flows through Subscription. Expansion is steepest in Game Streaming.
End User:
Application intensity varies dramatically, with professional and hardcore segments demanding continuous server uptime while casual users fragment across sporadic sessions.
- Casual Gamers:Sporadic engagement with free-to-play titles and catalog exploration. Mobile endpoints in Japan capture this segment's commuter-driven sessions.
- Hardcore Gamers:Sustained daily investment across live-service titles and competitive multiplayer. United States and United Kingdom markets concentrate this cohort's microtransaction volume and battle pass participation.
- Families:Parental control utilization and shared library access define this segment. Content ratings and spending limits shape purchasing patterns.
- Professional Players:Tournament participation and streaming content creation drive visibility. Esports infrastructure investments target this narrow but influential base.
Revenue per user peaks with Professional Players. Volume concentration sits with Hardcore Gamers.
Content Type:
Margin structures diverge sharply between high-production base games and near-zero-marginal-cost digital add-ons.
- Games:Full-title releases requiring substantial development investment and marketing spend. First-party studios in Japan and California anchor production.
- Add-Ons:Downloadable content packs and expansion passes extend monetization of installed base titles. United Kingdom consumers show strongest adoption of seasonal content drops.
- Themes:Cosmetic interface customization with minimal development overhead. Younger user segments drive transactional volume.
- Demos:Trial versions functioning as acquisition tools rather than revenue centers. Conversion rates to full purchases vary by genre.
Development resources concentrate in Games. Margin expansion is fastest in Add-Ons.
Device Type:
Supply concentration follows hardware ownership patterns, with console endpoints dominating revenue capture while mobile and PC represent expansion frontiers.
- Console:PlayStation 5 and legacy PlayStation 4 hardware anchor the ecosystem. United States and Japanese households sustain the highest per-console spending rates.
- Mobile:iOS and Android streaming endpoints capture commuter and casual sessions without dedicated hardware investment. United Kingdom 5G rollout accelerates adoption.
- PC:Steam and Epic Games Store distribution of ported first-party titles reaches audiences outside console ownership. This channel gains share fastest as Sony Interactive Entertainment relaxes exclusivity windows.
- VR Headsets:PlayStation VR2 and compatible hardware enable immersive experiences with smaller addressable base. Content library depth constrains growth relative to other endpoints.
Transaction volume flows predominantly through Console. User base expansion is climbing the fastest in PC.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sony Interactive Entertainment scaled Playstation Network from its Tokyo headquarters in the mid-2000s, establishing server infrastructure that now spans multiple continents. The platform's revenue geography reflects broadband penetration patterns and console ownership density across developed markets.
United States
Households drive premium-tier subscription adoption where fiber-optic penetration exceeds 100 Mbps in suburban corridors. The Federal Trade Commission enforces auto-renewal transparency rules that shape cancellation flow design. Seattle anchors cloud infrastructure deployment as Microsoft competes through Azure-integrated Game Pass streaming.
Japan
Kanto region commuters sustain mobile streaming sessions during transit hours through 5G network coverage. The Personal Information Protection Commission mandates explicit consent frameworks for youth-targeted microtransactions. Tokyo-based first-party studios concentrate live-service development talent for persistent multiplayer titles.
United Kingdom
Fiber-optic latency below 20 milliseconds accelerates cloud gaming adoption among households outside London. The Information Commissioner's Office applies GDPR-aligned subscription disclosure requirements that reduce accidental renewal lock-in. Manchester and Birmingham clusters support regional data center capacity for low-latency streaming.
Germany
Bavaria and North Rhine-Westphalia concentrate hardcore gamer segments with sustained daily engagement across live-service titles. The country's federal data protection authority enforces strict transparency standards for recurring digital charges. Berlin hosts independent development studios porting content to PC distribution channels.
South Korea
Seoul Capital Area households exhibit highest per-capita microtransaction velocity across battle pass and cosmetic store formats. The Ministry of Science and ICT oversees broadband infrastructure standards that enable sub-15 millisecond cloud gaming latency. Busan-Ulsan corridor anchors esports tournament infrastructure that drives professional player visibility.
Playstation Network (PSN) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across subscription bundling sophistication and first-party content depth. The market structure consolidates around platform holders with proprietary hardware ecosystems while fragmenting across third-party publishers with multi-platform distribution strategies. Three archetypes dominate: vertically integrated console manufacturers, cross-platform subscription aggregators, and specialist live-service developers. Competitive moves concentrate on exclusive content acquisition and cloud infrastructure partnerships.
Within the platform-holder tier, Sony Interactive Entertainment and Microsoft exemplify contrasting ecosystem strategies, with the former anchoring premium first-party exclusivity and the latter pushing cross-platform subscription reach. Nintendo occupies a differentiated position emphasizing family-oriented content libraries that resist direct feature parity. Electronic Arts represents the specialist archetype through live-service sports and multiplayer franchises.
| Leading Market Players |
|---|
| Sony Interactive Entertainment |
| Microsoft |
| Nintendo |
| Electronic Arts |
| Activision Blizzard |
| Ubisoft |
| Take-Two Interactive |
| Capcom |
| Square Enix |
| Others |
Pricing and Supply Chain Analysis
Carbon-neutral data center mandates in the European Union and Japan are gating qualified server farm supply and premium-tier cloud streaming access for Playstation Network operators. These sustainability requirements compress available infrastructure capacity while allowing certified providers to command subscription pricing premiums from environmentally conscious subscriber segments.
Pricing Analysis
Three-tier membership pricing across premium, standard, and economy levels structures buyer choice through bandwidth allocation and content catalog depth differentiation. Price differentiation rests on 4K streaming certification and exclusive first-party release windows as primary drivers. Pricing pressure stems from Microsoft Game Pass cross-platform bundling that forces Sony Interactive Entertainment to enhance value-per-dollar ratios. Casual gamers in suburban United States markets exhibit highest price sensitivity, while hardcore segments in South Korea demonstrate lowest elasticity due to live-service social lock-in effects.
Supply Chain Analysis
Dual-sourcing requirements for content delivery networks mandate Sony Interactive Entertainment qualify multiple CDN providers across United States, Japan, and United Kingdom server clusters. Raw material dependencies center on semiconductor fabrication for PlayStation 5 console production, fiber-optic cable deployment for latency reduction, and rare earth elements for controller haptic hardware. Supply chain risk concentrates in single-source vulnerability for custom AMD processor architectures. Distribution runs through proprietary PlayStation Store infrastructure alongside third-party retail partnerships for hardware and gift card channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Playstation Network's margin expansion narrative rests on cloud infrastructure cost curves declining faster than subscription pricing erosion, enabling operating leverage capture across the installed base.
For Market Incumbents: Anchor lifetime value through exclusive first-party live-service content that resists multi-platform commoditization. Sony Interactive Entertainment must deepen backward integration into cloud server engineering talent pools to defend against Microsoft's Azure-integrated streaming scale. Priority investment in adaptive bitrate compression technology preserves visual quality leadership as broadband conditions fragment across subscriber households.
For New Entrants and Emerging Players: Specialist cloud gaming aggregators represent the most penetrable white-space channel for partnership-based market entry. PC distribution through Steam and Epic Games Store offers lowest barrier-to-entry for catalog-based subscription challengers targeting United States and United Kingdom hardcore segments absent hardware ecosystem investment. Go-to-market positioning should emphasize cross-platform save-state synchronization as differentiation against console-locked incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier live-service developers with proven multiplayer infrastructure but sub-scale marketing reach. Long-term viability over the mid-decade horizon favors studios with persistent game titles generating recurring microtransaction revenue rather than hit-driven single-release models. Regulatory clarity on loot box classification standards across FTC, ICO, and PIPIC jurisdictions serves as the critical signal to watch for monetization model inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Expansion | Low-latency server deployment in Manchester and Seattle reduces streaming latency below 20 milliseconds threshold. |
| First-Party Live-Service Pivot | Tokyo studio concentration on persistent multiplayer titles sustains microtransaction revenue between major releases. |
| PC Distribution Channel Opening | Steam and Epic Games Store ports reach subscriber segments outside PlayStation hardware ownership constraints. |
| Subscription Tier Restructuring | Consolidated multiplayer-cloud-catalog bundling responds to Microsoft Game Pass cross-platform competitive pressure. |
| GDPR-Aligned Transparency Investment | Equivalent prominence cancellation flows reduce ICO enforcement exposure and build subscriber trust in auto-renewal mechanics. |
Research Methodology
Bottom-up engagement intensity modeling reconciled against top-down server capacity tracking forms the analytical core of this study. Primary interviews with platform engineering directors, subscription product managers, cloud infrastructure procurement leads, and competitive intelligence specialists at Sony Interactive Entertainment, Microsoft, and Nintendo were cross-validated against secondary sources including SEC 10-K filings, hyperscaler capex disclosures, and broadband penetration databases from national regulators. Triangulation between subscriber behavioral data and content delivery network expansion timelines ensures segmentation integrity.
Input-output matrices map content development investment through server deployment capacity to subscription revenue recognition across the projection horizon. Segmentation dimensions modeled include service delivery tier, end-user engagement intensity, content format type, and hardware endpoint category. CAGRs derive from installed base growth curves, average revenue per user trajectory analysis, and cloud streaming adoption elasticity functions calibrated against fiber-optic and 5G rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory classification of loot box mechanics and data center energy cost volatility. Deviation in FTC auto-renewal enforcement intensity or Japanese PIPIC youth-targeted transaction consent requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Online Casual Games Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Advanced Digital Gaming Market
Gaming
Mobile Shooter Market
Gaming
AAA Games Market
Gaming
Slot Machine Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
VR Gaming Controller Market
Gaming
Gaming Chair Market
Gaming
Global Battle Royale Games Market
Gaming
Europe Casino Gambling Market
Gaming
Video Game Software Market
Gaming
Australia Gaming Accessories Market
Gaming
South Asia Mobile Gaming Market
Gaming
Global 3D Gaming Console Market
Gaming
Russia in-Game Advertising Market