
 Gaming Hardware Market | 2026-2036
Gaming Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Hardware Market Intelligence
Real-time ray tracing and AI-driven upscaling is tilting the technology stack toward tensor-core architectures and dedicated neural processing units. NVIDIA Corporation leverages its CUDA ecosystem and foundry partnerships to dominate discrete GPU supply for enthusiast builds. Sony Corporation anchors living-room gaming through vertical control over console silicon and first-party content pipelines. Microsoft Corporation competes across cloud, console, and PC segments with its Azure-powered Game Pass infrastructure.
Gaming hardware comprises specialized computing and peripheral equipment engineered for interactive entertainment, typically featuring high refresh rates above 120Hz, sub-20ms input latency, and thermal designs dissipating 200W to 450W in flagship GPUs. Its commercial purpose centers on reducing friction between player intent and on-screen response to sustain engagement in competitive and immersive scenarios. Graphics cards and gaming consoles command the largest revenue pools, with VR headsets representing the fastest structural expansion as pancake lens designs reduce headset weight and improve wearability. Mechanical keyboards and gaming mice remain mature categories where margin concentrates in wireless low-latency variants and limited-edition collaborations with eSports organizations.
The US FCC enforces electromagnetic compatibility and RF exposure standards that gate console and wireless peripheral market entry, while the EU Ecodesign for Sustainable Products Regulation mandates repairability documentation and standardized charging ports. China's MIIT certifies network-connected gaming devices under cybersecurity review protocols that affect cloud gaming latency and data residency architectures. Stakeholders must monitor how right-to-repair legislation and semiconductor export controls reshape component sourcing strategies and regional product availability.
Market Dynamics
Tensor-core architectures and dedicated neural processing units are restructuring competitive advantage around AI inference throughput, while foundry capacity allocation for advanced nodes concentrates supply leverage among GPU designers with pre-paid wafer commitments.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandatory repairability documentation and standardized charging ports are extending hardware replacement cycles and creating aftermarket service revenue pools.
- eSports league expansion:Professional gaming circuits are compressing refresh cycles for monitors, peripherals, and GPUs to maintain competitive parity across tournament infrastructure.
- Pancake lens optical stacks:Reduced headset weight and improved wearability are accelerating VR hardware adoption beyond early enthusiast segments into fitness and enterprise training verticals.
Market Restraints
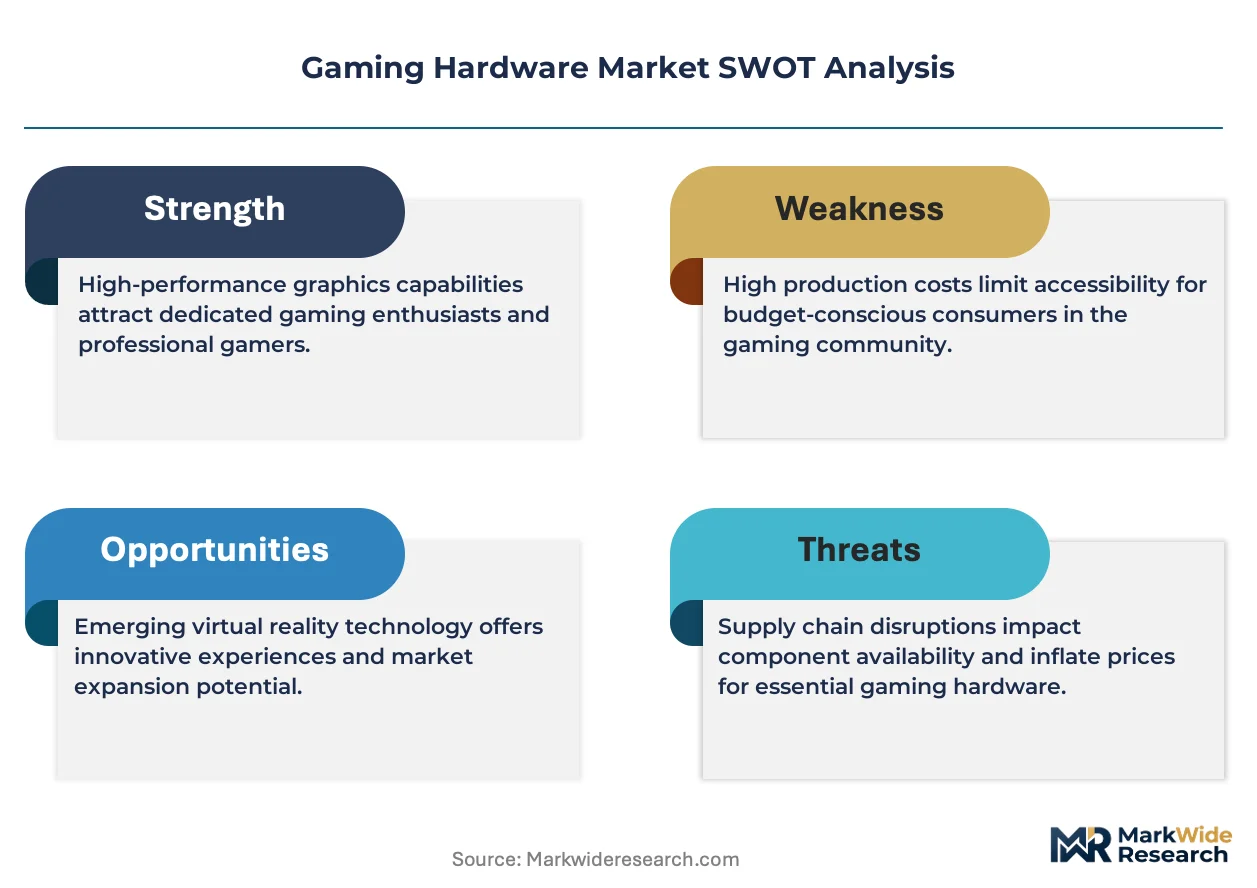
- Advanced node foundry concentration:Taiwan and South Korea control the bulk of 5nm and below capacity, creating single-source vulnerability for flagship GPU and console SoC production.
- GDDR6X and HBM3 memory cost volatility:High-bandwidth memory supply tightness inflates bill-of-materials for enthusiast-grade graphics cards and VR headsets.
- China MIIT cybersecurity certification:Network-connected gaming devices face data residency and latency architecture constraints that complicate cloud gaming service deployment.
Strategic Opportunities
- Modular thermal and power subsystems:Standardized GPU mounting frames and liquid cooling loops enable upgrade paths that comply with right-to-repair mandates while capturing recurring component revenue.
- India's PLI scheme for electronics manufacturing:Incentive structures for semiconductor assembly and testing are attracting console packaging and peripheral production away from traditional East Asian hubs.
- AI-driven upscaler integration:Neural rendering pipelines converging with cloud game streaming infrastructure reduce client-side compute requirements and expand addressable hardware tiers.
Industry Challenges
- Silicon design talent scarcity:Competition for GPU architecture and ray-tracing pipeline engineers from hyperscale cloud operators constrains in-house R&D scaling.
- Electromagnetic compatibility certification timelines:US FCC testing protocols for wireless peripherals and RF-emitting consoles create 4-6 month market entry delays that misalign with holiday retail windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Hardware Market |
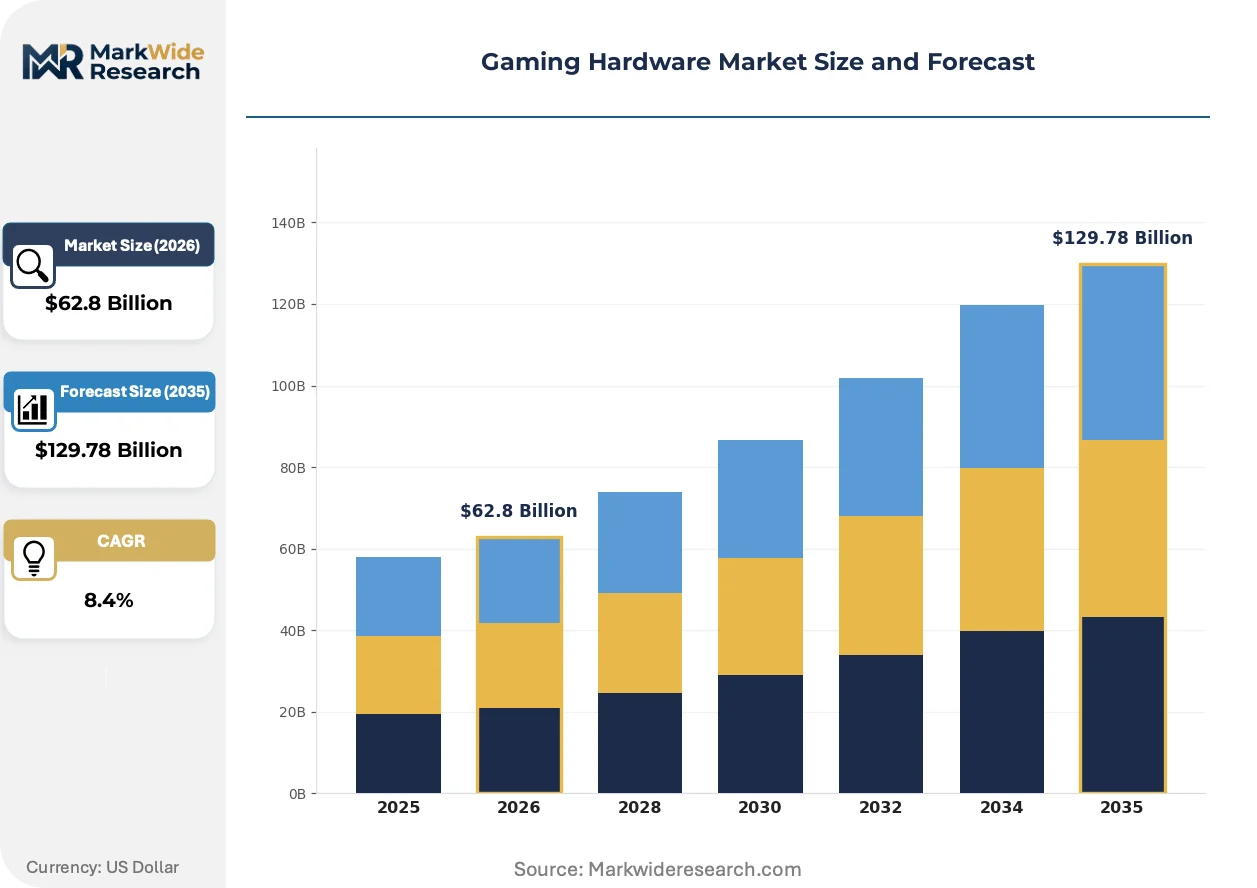
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $129.78 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Cards, Gaming Consoles, Gaming Monitors, Mechanical Keyboards, Gaming Mice, VR Headsets Technology: Ray Tracing, OLED Displays, G-SYNC, RGB Lighting, SSD Storage, Liquid Cooling Application: eSports, Game Development, Streaming, Virtual Reality, Simulations, Content Creation End User: Professional Gamers, Hobbyists, Game Developers, Streamers, Arcade Operators, Cybercafes |
| Companies Covered | NVIDIA Corporation, ASUS, Sony Corporation, Corsair Gaming, Razer Inc., Microsoft Corporation, Logitech International S.A, SteelSeries, Nintendo Co Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Hardware Market Strategic Shifts & Innovations
Real-time rendering pipelines and on-device AI inference are redistributing computational load between cloud infrastructure and local silicon, compressing traditional hardware segmentation boundaries.
Chiplet-based GPU architectures are collapsing monolithic die constraints on yield and reticle limits. NVIDIA and AMD are deploying multi-tile designs with high-speed interconnect fabrics that improve manufacturing economics at the 4nm node. This packaging approach is collapsing the cost-performance gap between flagship and mid-tier graphics cards.
EU Ecodesign for Sustainable Products Regulation mandates modular construction and spare parts availability for networked gaming devices. Manufacturers must publish repair manuals and maintain component inventories for 7-10 years post-sale. Console assemblers are responding by standardizing internal mounting patterns and reducing adhesive-based assembly.
Subscription-based hardware refresh programs are displacing outright purchase models among competitive gamers. End-users in South Korea and Japan are prioritizing guaranteed upgrade paths over ownership, with retailers bundling trade-in guarantees with peripheral and GPU purchases. This preference shift is most visible in monitor and keyboard categories where form-factor evolution accelerates obsolescence.
Gaming Hardware Market Segmentation
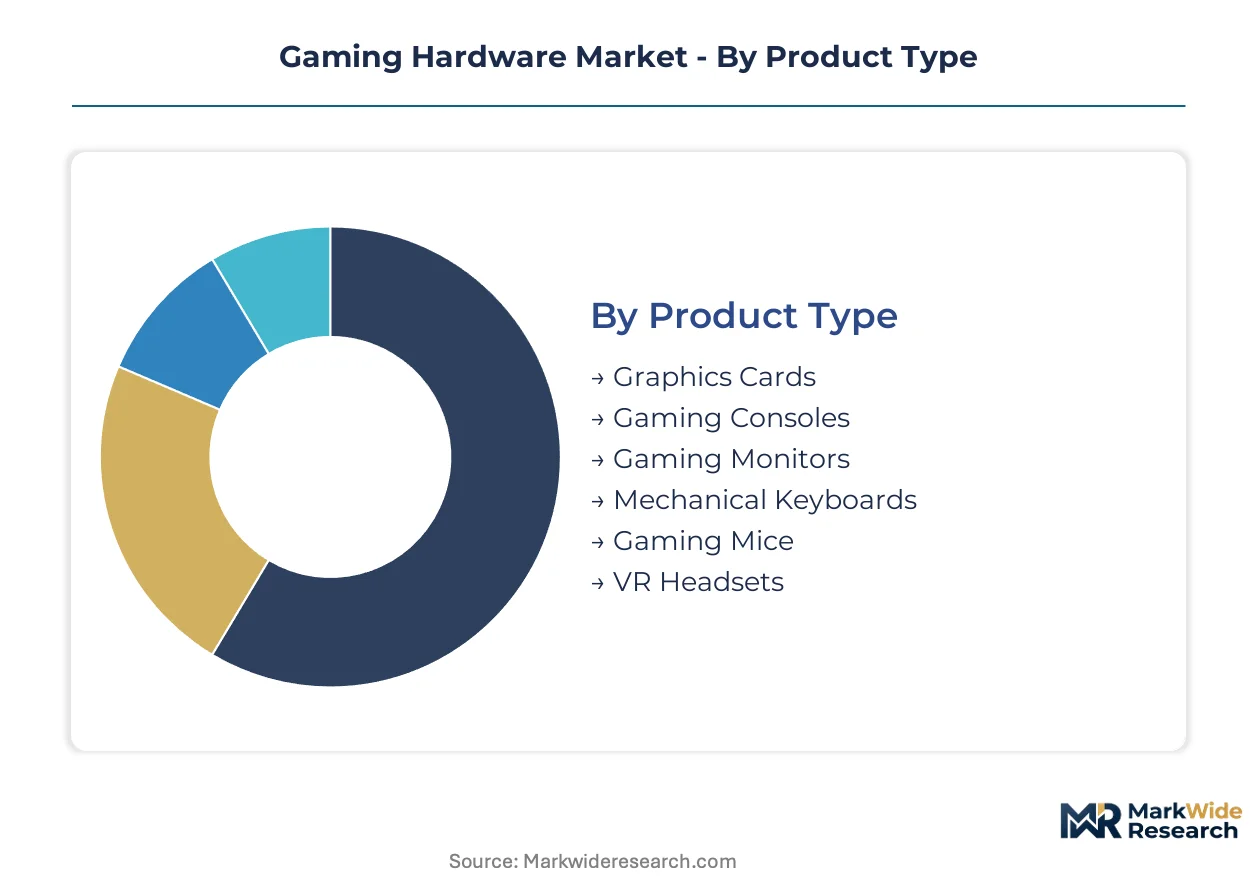
Gaming hardware segmentation tracks how computational load, display fidelity, and input precision requirements fragment across competitive intensity and content creation workflows. Manufacturers calibrate thermal envelopes, refresh rates, and latency specifications to match the friction tolerance of each user archetype.
Product Type:
Mature categories with established replacement cycles coexist alongside emerging form factors that are restructuring hardware refresh economics.
- Graphics Cards:Discrete GPU architectures dissipating 200W to 450W anchor enthusiast builds and professional rendering pipelines. Demand concentrates in the United States and China where tensor-core density for AI inference throughput drives upgrade urgency among competitive players and machine learning practitioners.
- Gaming Consoles:Vertical silicon control and first-party content pipelines define living-room gaming economics. Sony and Microsoft pre-pay wafer commitments at foundries to secure supply leverage for generational launches, with living-room penetration deepest in Japan and South Korea where subscription-based refresh programs are displacing outright purchase models.
- Gaming Monitors:High-refresh panels above 120Hz with sub-20ms input latency serve competitive parity requirements.
- Mechanical Keyboards:Wireless low-latency variants and eSports collaboration editions concentrate margin in a mature peripheral category.
- Gaming Mice:Sensor precision and weight reduction specifications fragment across claw, palm, and fingertip grip archetypes.
- VR Headsets:Pancake lens optical stacks reducing headset weight below 300 grams are accelerating adoption beyond enthusiasts into fitness and enterprise training verticals across Germany and the United Kingdom.
Graphics Cards and Gaming Consoles handle the majority of throughput; VR Headsets are gaining share fastest as pancake lens designs improve wearability.
Technology:
Cost tier stratification separates premium tensor-core implementations from baseline configurations that sacrifice ray-tracing fidelity for frame-rate stability.
- Ray Tracing:Real-time light simulation pipelines demand dedicated RT cores and memory bandwidth above 600 GB/s. Adoption clusters in Germany and France where visual fidelity preferences in single-player narrative titles justify thermal and cost premiums.
- OLED Displays:Sub-millisecond response times and infinite contrast ratios eliminate ghosting in fast-twitch competitive scenarios. South Korean panel foundries supply the bulk of smartphone-derived OLED fabrication repurposed for gaming monitors.
- G-SYNC:Variable refresh rate synchronization eliminates screen tearing through module or software implementation tiers.
- RGB Lighting:Addressable LED ecosystems synchronize across peripheral ecosystems for streamer content aesthetics.
- SSD Storage:NVMe protocols reducing load times to sub-10 seconds are standard in new console and PC builds.
- Liquid Cooling:Custom loop and AIO configurations enable sustained boost clocks on overclocked silicon.
Ray Tracing commands the highest implementation cost; OLED Displays are climbing the fastest as manufacturing scale collapses price premiums against LCD alternatives.
Application:
Volume concentration in competitive gaming contrasts with margin-rich verticals where hardware specifications interface with professional productivity tools.
- eSports:Tournament infrastructure mandates standardized refresh rates, input latency ceilings, and thermal stability across regional qualifiers. League operators in South Korea and Japan compress peripheral and GPU replacement cycles to maintain competitive parity.
- Game Development:Unreal Engine and Unity pipeline optimization requires GPU architectures with robust ray-tracing and mesh shader support. Studios in California and Stockholm drive workstation-class hardware configurations.
- Streaming:Dual-PC or single-PC encoding setups balance capture quality with gameplay performance.
- Virtual Reality:Enterprise training and medical simulation deploy tethered and standalone headsets.
- Simulations:Racing and flight rigs demand force-feedback peripherals and ultrawide or triple-monitor arrays.
- Content Creation:Video editing and 3D rendering workflows overlap with gaming hardware specifications.
eSports generates the highest unit velocity; Game Development carries the steepest expansion trajectory as engine complexity escalates hardware requirements.
End User:
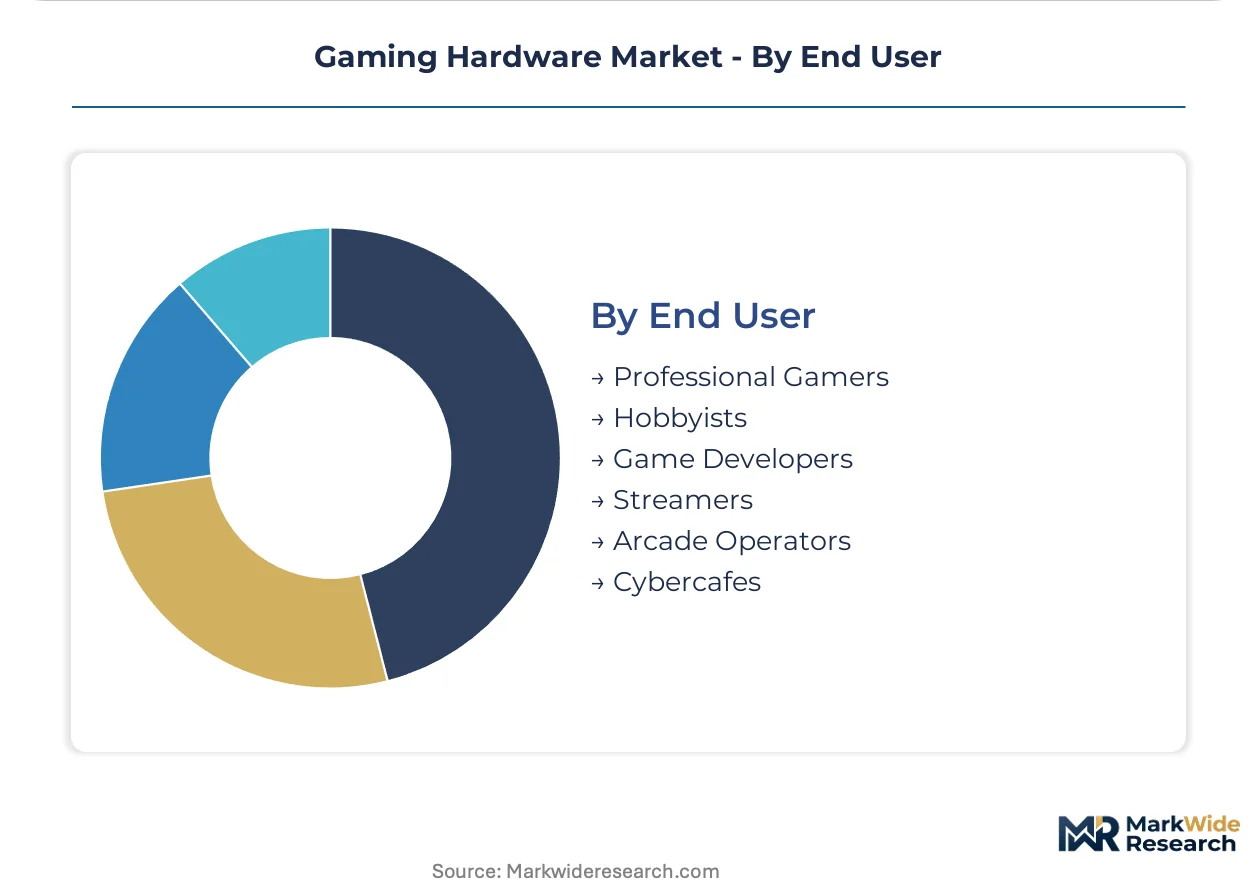
Customer type stratification separates specification-sensitive professionals from price-elastic hobbyists whose upgrade cadence tracks blockbuster release schedules.
- Professional Gamers:Contracted eSports athletes and full-time streamers treat hardware as depreciable competitive infrastructure. Teams in South Korea and Denmark provide standardized peripheral and GPU configurations to eliminate equipment variance as a performance variable.
- Hobbyists:Enthusiast builders prioritize customization and thermal headroom over warranty coverage. This segment concentrates in the United States and Germany where component retail density supports iterative upgrade paths.
- Game Developers:Indie and AAA studios require debug and profiling hardware matching target platform specifications.
- Streamers:Content creators balance capture card integration with audience-visible aesthetic configurations.
- Arcade Operators:Location-based entertainment venues prioritize durability and anti-tamper enclosures over peak specifications.
- Cybercafes:Pay-per-hour gaming venues in India and Southeast Asia standardize mid-tier configurations with aggressive refresh cycles to maintain competitive pricing.
Hobbyists represent the largest installed base; Professional Gamers are expanding most quickly as league franchising formalizes equipment standardization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enthusiast builders and eSports professionals drive hardware procurement intensity across concentrated urban technology corridors. Regulatory frameworks for repairability and data residency reshape product availability and service architectures in each jurisdiction.
United States
Competitive gaming leagues and content creation studios sustain premium GPU and peripheral demand in California and Texas. The FCC enforces electromagnetic compatibility certification timelines that create 4-6 month market entry delays for wireless peripherals. Austin and Los Angeles anchor console assembly and game development workstation procurement respectively.
China
Cybercafes and cloud gaming venues compress refresh cycles for mid-tier configurations in tier-one cities. MIIT cybersecurity review protocols mandate data residency architectures that affect latency-sensitive streaming services. Shenzhen and Shanghai concentrate GPU foundry partnerships and console packaging capacity.
Japan
Subscription-based hardware refresh programs displace outright purchase models among competitive gamers in Tokyo and Osaka. METI standards for energy efficiency influence thermal design specifications for living-room consoles. Kyoto and Tokyo house integrated silicon design and first-party content pipeline operations.
Germany
Visual fidelity preferences in single-player narrative titles justify ray-tracing GPU premiums in Berlin and Munich. The EU Ecodesign for Sustainable Products Regulation mandates 7-10 year spare parts availability for networked gaming devices. Dresden and Frankfurt anchor display panel fabrication and peripheral distribution hubs.
South Korea
Professional eSports athletes demand standardized peripheral configurations to eliminate equipment variance. The country's national telecommunications regulator enforces network performance standards affecting cloud gaming latency. Seoul and Busan concentrate tournament infrastructure and monitor panel foundry output.
Gaming Hardware Market Key Industry Players
Channel-controlling players compete with product-specialist players across tensor-core GPU, console silicon, and peripheral ecosystems. The vendor base separates into three strategic tiers: foundry-integrated semiconductor designers, living-room platform operators with captive silicon pipelines, and peripheral specialists leveraging eSports collaboration licensing. Capacity pre-commitments at advanced nodes and modular thermal subsystem standardization represent the dominant competitive vectors.
Within the semiconductor architecture tier, NVIDIA Corporation and Sony Corporation exemplify contrasting approaches to silicon supply security. Among peripheral specialists, Razer Inc. and Corsair Gaming occupy positions defined by wireless low-latency technology and eSports partnership ecosystems. Microsoft Corporation sits across multiple competitive vectors through cloud infrastructure, console platforms, and subscription service integration.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| ASUS |
| Sony Corporation |
| Corsair Gaming |
| Razer Inc. |
| Microsoft Corporation |
| Logitech International S.A |
| SteelSeries |
| Nintendo Co Ltd. |
| Others |
Cost & Logistics Intelligence
Taiwan and South Korea control the bulk of 5nm and below foundry capacity, anchoring margin pools in pre-paid wafer commitments and long-term offtake agreements with GPU designers and console platform operators. This upstream concentration funnels pricing power toward semiconductor architects while compressing assembler margins downstream.
Pricing Analysis
Cost-plus contracts with GDDR6X and HBM3 memory indexation dominate flagship graphics card procurement. Three-tier pricing structure across premium, standard, and economy levels segments by tensor-core density and ray-tracing certification tier. Pricing pressure stems from advanced node foundry concentration and memory cost volatility. Cybercafe operators in India and Southeast Asia exhibit highest price sensitivity; professional eSports teams in South Korea and Denmark show lowest sensitivity due to equipment standardization mandates.
Supply Chain Analysis
US semiconductor export controls restricting advanced GPU and AI accelerator flows to China reshape component sourcing strategies and regional product availability. Taiwan, South Korea, and the United States anchor supply for 4nm GPU tiles, HBM3 memory stacks, and OLED display panels. Foundry capacity allocation, memory substrate shortages, and FCC certification timelines constitute primary structural risks. Distribution runs through direct-to-consumer channels, eSports retailer networks, and cloud gaming infrastructure providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU architecture and ray-tracing pipeline engineering talent scarcity constrains in-house R&D scaling across incumbent and challenger positions alike. Foundry pre-commitments and modular thermal subsystem IP now separate defendable market positions from commodity exposure.
For Market Incumbents: Entrench silicon supply security through captive foundry partnerships and multi-year wafer pre-payments at TSMC and Samsung. Standardize internal mounting patterns and liquid cooling loop interfaces to capture recurring component revenue under EU Ecodesign repairability mandates. Threat substitution from chiplet-based mid-tier architectures demands accelerated tensor-core density roadmaps. For New Entrants and Emerging Players: Build out modular thermal and power subsystem ecosystems targeting India's PLI scheme for electronics manufacturing assembly and testing incentives. India's peripheral production gap offers the most penetrable geography. Go-to-market through eSports league equipment standardization contracts and subscription-based refresh program partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed peripheral specialists holding wireless low-latency patent portfolios and eSports collaboration licensing networks. Long-term viability hinges on AI-driven upscaler integration and cloud gaming infrastructure convergence. Watch for MIIT cybersecurity certification delays affecting China market entry as inflection signal for regional revenue exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Pre-commitment | Secures 4nm wafer allocation at TSMC against console and GPU generational launch windows. |
| Modular Thermal Subsystem Standardization | Enables GPU upgrade paths compliant with EU Ecodesign 7-10 year spare parts mandates. |
| AI Upscaler Cloud Integration | Reduces client-side compute requirements for NVIDIA and expands addressable hardware tiers. |
| eSports League Equipment Partnership | Locks in standardized peripheral refresh cycles with South Korean and Japanese tournament operators. |
| India PLI Manufacturing Relocation | Captures console packaging and peripheral assembly incentives away from East Asian hubs. |
Research Approach
The analysis maps graphics card, gaming console, VR headset, and peripheral sub-sectors, each validated through semiconductor procurement directors, eSports league operations managers, and foundry account executives. Primary interviews with GPU architecture leads, console platform strategists, and peripheral R&D heads combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and MIIT certification databases. Bottom-up unit shipment modeling and top-down value chain triangulation anchored volume and value estimates.
Assumptions held fixed include foundry yield curves at 4nm nodes, EU Ecodesign implementation timelines, and FCC certification protocol stability; varied assumptions encompass China MIIT cybersecurity review durations and GDDR6X memory contract pricing bands. Segmentation dimensions modeled span product type, technology tier, application intensity, and end-user archetype across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated eSports league franchise expansion schedules and cloud gaming infrastructure deployment trajectories.
Stress conditions across foundry capacity allocation shocks, memory substrate supply disruptions, and right-to-repair legislative acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding tensor-core adoption curves and VR headset weight reduction trajectories. Semiconductor export control escalation and electromagnetic compatibility certification timeline extensions constitute specific risk factors that could revise projections. Cross-checking against hyperscaler datacenter GPU procurement disclosures and eSports tournament infrastructure investment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Galgames Market
Gaming
Online Casino Market
Gaming
Global 3D Gaming Console Market
Gaming
United Kingdom Online Gambling Market
Gaming
Global Casino Market
Gaming
VR Gaming Console Market
Gaming
Traditional Casual Games Market
Gaming
Global Gaming Headset Market
Gaming
Global Online Board Games Market
Gaming
United States Gaming Accessories Market
Gaming
VR Racing Gaming Market
Gaming
Arcade Games Market
Gaming
VR Melee Games Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Video Game Software Market