
 Casino Gaming Equipment Market | 2026-2036
Casino Gaming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Casino Gaming Equipment Market Analysis
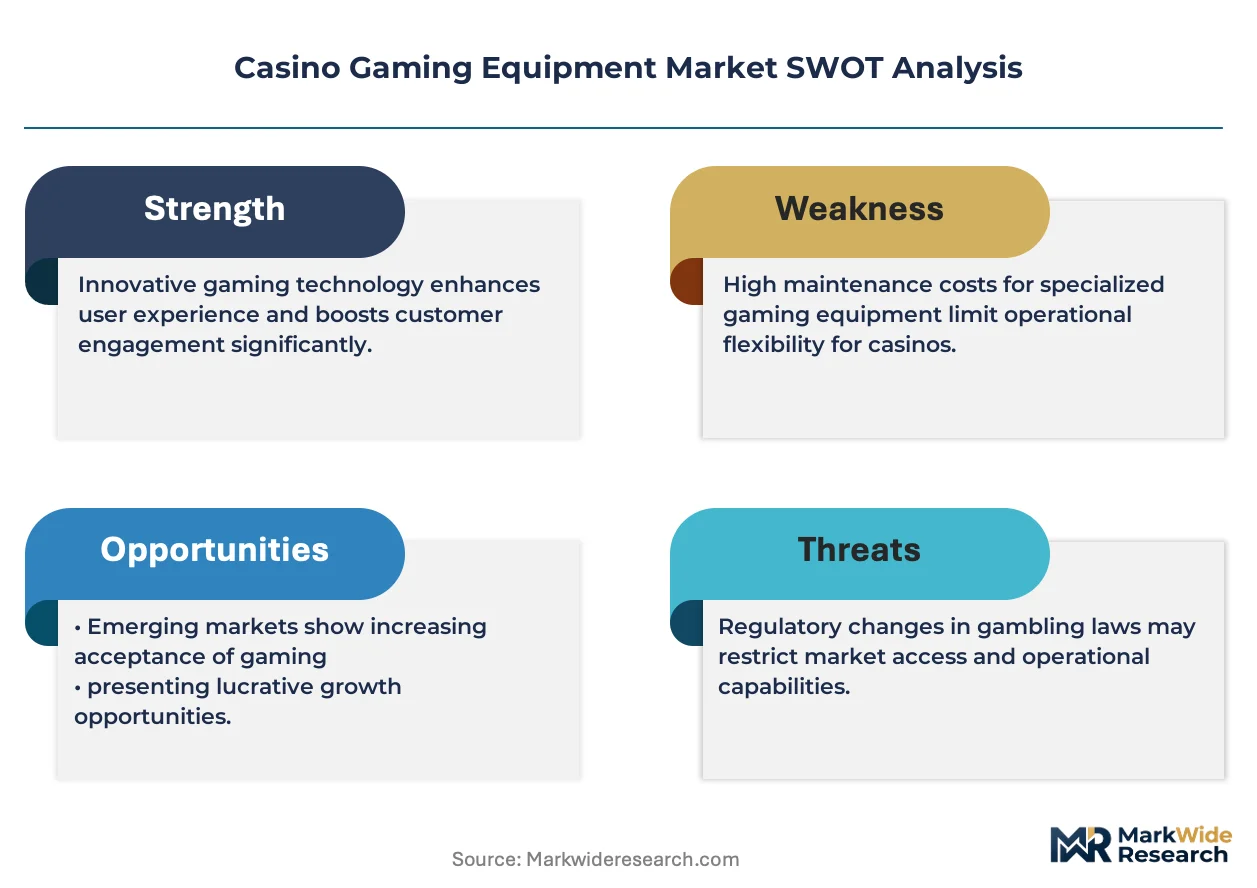
The split between premium experiential hardware and commoditized electronic terminals is shifting the competitive landscape for manufacturers. Aristocrat Leisure dominates the premium slot segment through its linked-progressive systems and licensed content portfolio. International Game Technology PLC anchors the systems infrastructure layer with its casino management platforms that integrate player tracking across properties. Novomatic AG competes aggressively in the electronic gaming machine tier through its Greentube interactive division and regional manufacturing footprint.
Casino gaming equipment encompasses electromechanical and digital apparatus designed for wagering entertainment, including slot machines with certified random number generators operating at precise return-to-player percentages, electronic table interfaces, and back-of-house management systems that monitor real-time gaming floor activity. Slot machines command the largest installed base across commercial and tribal properties, while casino management systems capture disproportionate margin pools through recurring software maintenance and compliance reporting modules. Electronic gaming machines represent the fastest-growing product category as operators replace legacy mechanical reels with server-based platforms that enable dynamic game libraries and remote configuration.
The Nevada Gaming Commission enforces stringent technical standards for all devices deployed in licensed facilities, including mandatory RNG testing by independent laboratories and continuous audit trail requirements. The Philippine Amusement and Gaming Corporation imposes localization rules that favor domestic assembly for certain equipment categories, shaping supplier market access strategies. Tribal gaming compact negotiations across multiple US jurisdictions add another compliance layer that equipment vendors must navigate for Class III device approvals. Stakeholders should monitor the divergence between regulatory treatment of cashless wagering systems and traditional ticket-in-ticket-out protocols, as this technical transition will determine replacement cycle timing and vendor selection criteria across the next decade.
Market Dynamics
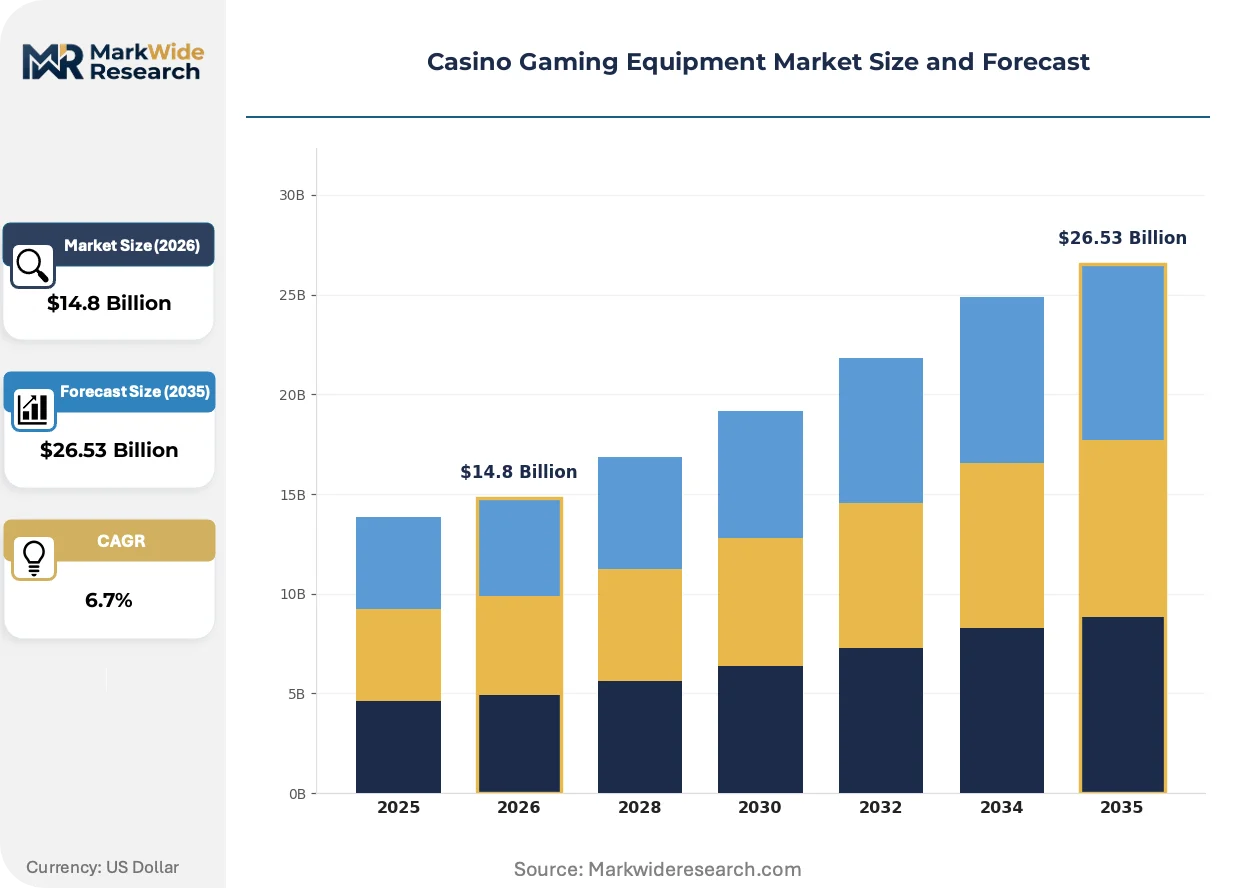
Server-based gaming platforms are compressing replacement cycles across commercial and tribal properties, forcing manufacturers to pivot from hardware margins toward recurring software revenue streams anchored by remote configuration capabilities and dynamic content libraries.
Growth Catalysts
- Macau Integrated Resort Expansion:Operators in this special administrative region are reallocating floor space toward electronic gaming machines, creating sustained demand for premium slot and ETG deployments.
- Philippine Entertainment City Buildout:The Philippine Amusement and Gaming Corporation licensing framework is accelerating premium table game capacity additions across Manila Bay complex developments.
- Nevada RNG Certification Mandate:The Nevada Gaming Commission's rigorous technical standards for random number generator validation are institutionalizing recurring laboratory testing revenue for compliant equipment suppliers.
Market Restraints
- Semiconductor Supply Concentration:Gaming machine logic boards depend on specialized chip fabrication concentrated in East Asian foundries, exposing deployment timelines to geopolitical disruption.
- Extended Certification Pipelines:Tribal gaming compact negotiations across multiple US jurisdictions layer additional Class III device approval timelines atop federal and state requirements.
- Legacy Mechanical Reel Depreciation:Operators face stranded asset risk on aging electromechanical slot bases as server-based platforms render prior generation hardware obsolete.
Strategic Opportunities
- Cashless Wagering Regulatory Divergence:Jurisdictions relaxing restrictions on digital wallet integration versus traditional ticket-in-ticket-out protocols will determine vendor selection criteria and replacement timing.
- Back-of-House Systems Integration:Casino management platforms that unify player tracking, compliance reporting, and real-time floor monitoring represent underpenetrated recurring revenue pools.
- Server-Based Platform Convergence:The intersection of remote game library management with dynamic return-to-player configuration is enabling operator-specific customization at scale.
Industry Challenges
- Embedded Firmware Talent Scarcity:The specialized skill set bridging gaming mathematics, security architecture, and regulatory compliance commands premium compensation and extended recruitment timelines.
- Multi-Jurisdictional Certification Complexity:Equipment vendors must navigate divergent technical standards across state, tribal, and international regulatory bodies without standardized mutual recognition frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casino Gaming Equipment Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slot Machines, Table Games, Electronic Gaming Machines, Casino Management Systems Technology: Random Number Generator, Mobile Gaming, Virtual Reality, Online Gaming End User: Casinos, Online Operators, Retail Outlets, Arcades Distribution Channel: Direct Sales, Distributors, Online Retail, Auction |
| Companies Covered | International Game Technology PLC, Aristocrat Leisure, Scientific Games Corporation, PlayAGS, Everi Holdings, Konami Holdings Corporation, Novomatic AG, Incredible Technologies, AGS LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casino Gaming Equipment Market Emerging Trajectories
Cashless wagering infrastructure is actively reshaping capital deployment patterns across gaming floor renovations, with regulatory divergence between jurisdictions creating asymmetric competitive windows for platform-ready suppliers.
Server-based gaming architecture is electrifying the transition from fixed game libraries to dynamically configurable content delivery. Integrated resort operators in Macau and Las Vegas are deploying these platforms at accelerated refresh rates. This technology is compressing the traditional seven-year hardware replacement cycle toward four-year software-driven upgrade intervals.
The Nevada Gaming Commission's continuous audit trail requirements are mandating real-time transaction logging and immutable record retention across all deployed devices. Equipment manufacturers must embed compliant logging subsystems at the firmware level before market entry. Slot machine and electronic table game categories face the steepest compliance engineering cost inflation.
Buyer concentration among integrated resort operators is consolidating procurement leverage and demanding unbundled service contracts. After-sales maintenance and software subscription modules are separating from initial hardware purchases. This pattern is most visible in the Philippines and Singapore where single-operator campus developments dominate new capacity additions.
Casino Gaming Equipment Market Segmentation
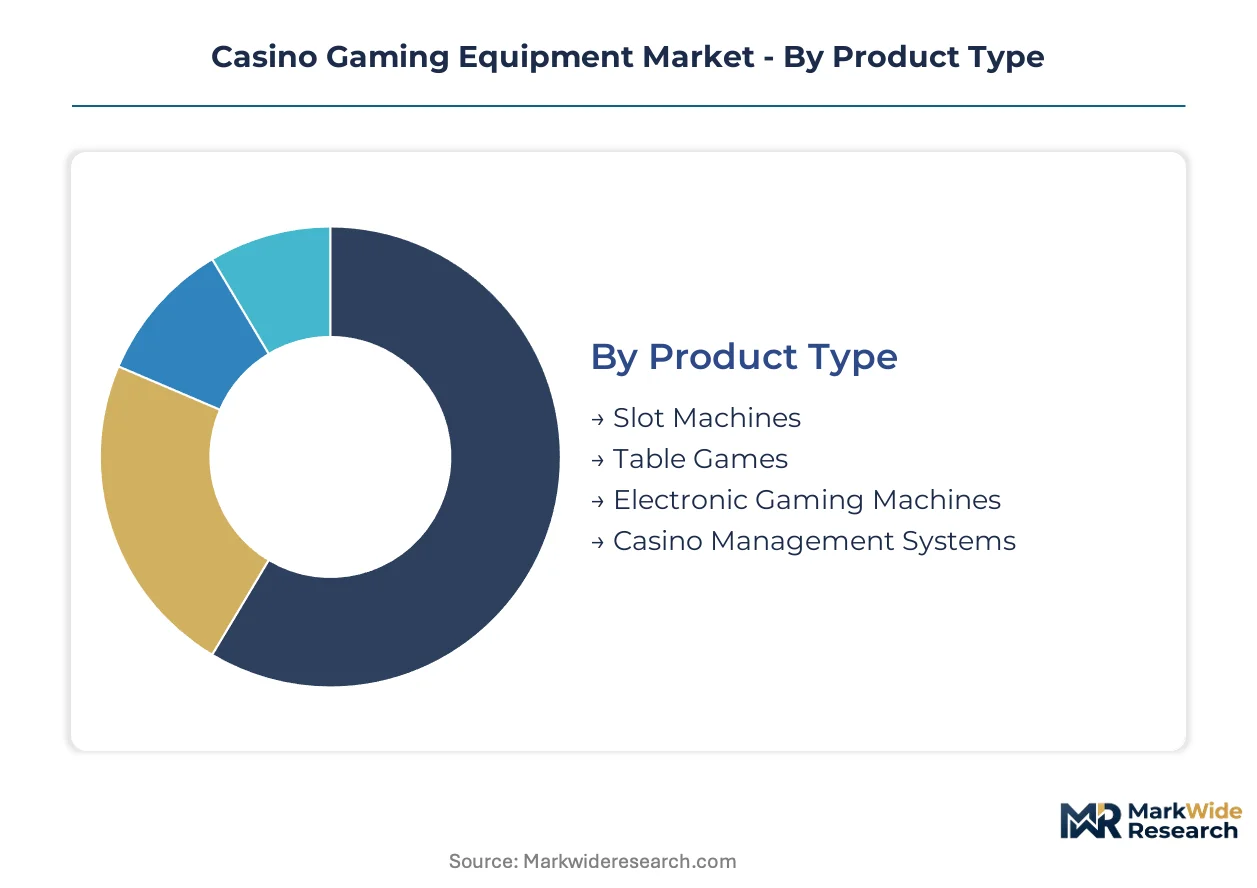
Segmentation in casino gaming equipment reveals how regulatory certification burdens, technology refresh cycles, and procurement channel economics concentrate margin capture across distinct product tiers. Manufacturers must align R&D roadmaps with the divergent compliance timelines and replacement dynamics governing each segment cluster.
Product Type:
Slot machines carry the heaviest certification burden through Nevada Gaming Commission RNG mandates and tribal compact approvals, while casino management systems face lighter hardware scrutiny but deeper software audit requirements.
- Slot Machines:Electromechanical and digital wagering terminals with certified random number generators operating at precise return-to-player percentages. Demand concentrates in Macau integrated resorts expanding electronic gaming floor space, driven by linked-progressive system deployments and licensed content refresh cycles.
- Electronic Gaming Machines:Server-based platforms enabling dynamic game libraries and remote configuration capabilities. Philippine Entertainment City complexes anchor procurement volume as operators replace legacy mechanical reels with configurable electronic terminals.
- Table Games:Physical gaming apparatus including cards, dice, and specialized furniture for premium wagering experiences.
- Casino Management Systems:Back-of-house infrastructure integrating player tracking, compliance reporting, and real-time floor monitoring across properties.
Slot machines sit at the top of the volume ranking, with electronic gaming machines climbing the fastest.
Technology:
Cost tier stratification separates foundational RNG certification from emerging immersive technologies requiring substantial R&D investment without guaranteed regulatory clearance.
- Random Number Generator:Core algorithmic engines governing outcome unpredictability in digital wagering devices. Nevada's independent laboratory testing mandate institutionalizes recurring validation revenue for compliant subsystem suppliers.
- Mobile Gaming:Smartphone and tablet-optimized wagering interfaces extending casino floor engagement beyond physical premises.
- Virtual Reality:Immersive headset-based gaming environments requiring substantial content development and hardware integration investment.
- Online Gaming:Internet-delivered wagering platforms operating under distinct jurisdictional licensing frameworks separate from land-based equipment approval pathways.
Random number generator technology captures the largest installed base, while mobile gaming gains share fastest as jurisdictions relax remote wagering restrictions.
End User:
Customer type determines procurement scale and service contract structure, with integrated resort operators wielding concentrated leverage against fragmented retail and arcade accounts.
- Casinos:Licensed commercial and tribal gaming properties deploying comprehensive equipment portfolios across slot, table, and electronic categories. Macau and Las Vegas strip properties drive premium segment demand through accelerated refresh cycles.
- Online Operators:Digital-first wagering platforms sourcing software infrastructure and remote gaming server capacity rather than physical hardware.
- Retail Outlets:Limited-scale wagering venues including lottery terminals and restricted gaming licenses in convenience and hospitality settings.
- Arcades:Skill-based amusement and social gaming establishments operating under distinct regulatory classifications from casino gaming.
Casinos dominate procurement volume, with online operators expanding most quickly as regulatory frameworks accommodate remote licensing.
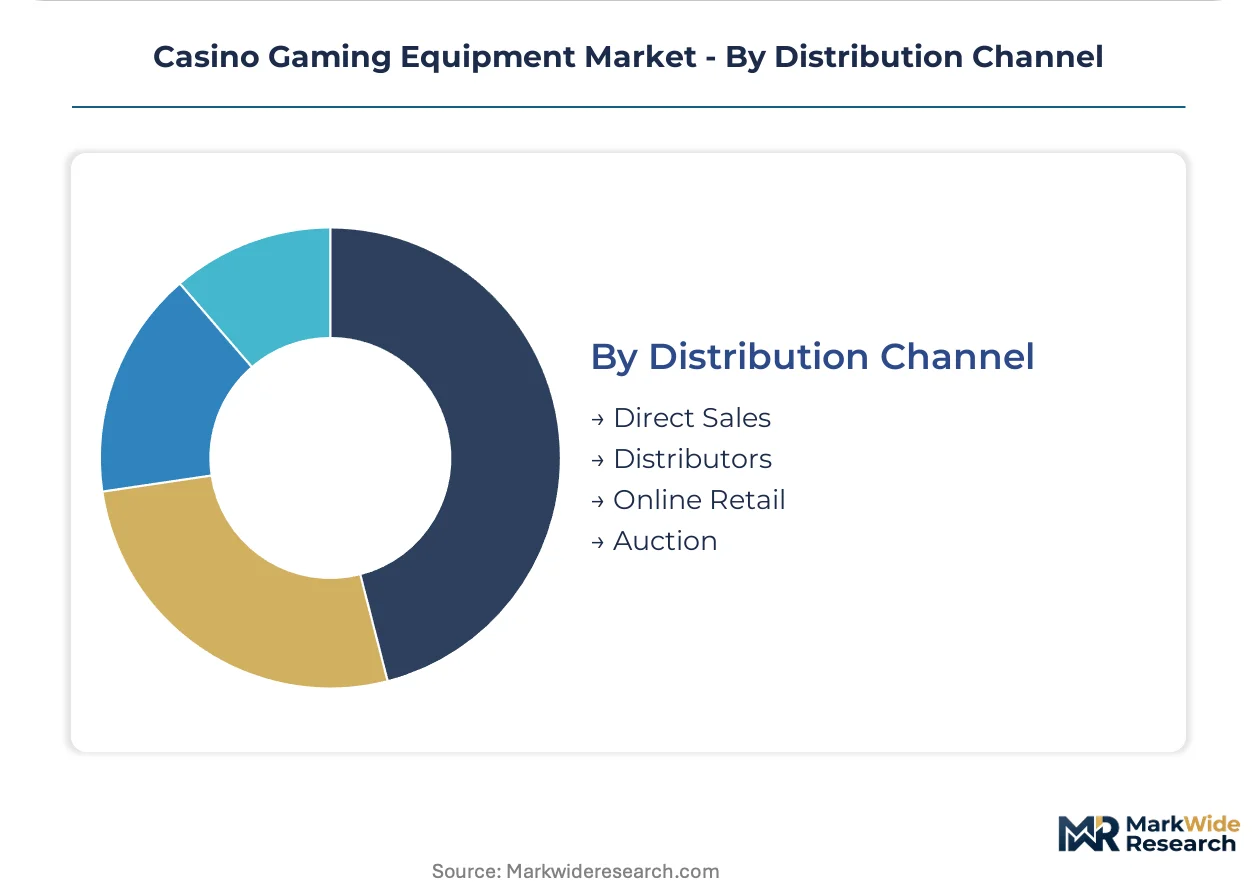
Distribution Channel:
Supply concentration shapes channel economics, with direct sales capturing integrated resort accounts while distributor networks penetrate geographically dispersed tribal and smaller commercial properties.
- Direct Sales:Manufacturer-to-operator relationships serving large-scale integrated resort and multi-property casino groups. Philippine Entertainment City developments and Singapore campus operators increasingly demand unbundled service contracts through direct procurement channels.
- Distributors:Regional intermediaries managing logistics, installation, and after-sales support for fragmented account bases.
- Online Retail:Digital procurement platforms primarily serving replacement parts, consumables, and secondary market equipment transactions.
- Auction:Secondary market disposition channels for depreciated mechanical reel equipment displaced by server-based platform upgrades.
Direct sales anchor revenue concentration, with distributor channels maintaining steepest expansion trajectory as tribal gaming compacts multiply addressable jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in gaming mathematics and embedded firmware cluster in Las Vegas, Macau, and Manila, anchoring the industry's technical workforce concentration. Regulatory complexity across jurisdictions demands localized compliance expertise that resists pure offshoring. Equipment procurement patterns track directly to these talent hubs and the integrated resort developments they service.
United States
Tribal gaming compacts across Oklahoma and California drive Class III device procurement volume, while Nevada's commercial strip properties accelerate refresh cycles. The Nevada Gaming Commission enforces continuous audit trail mandates that institutionalize recurring firmware validation costs. Las Vegas anchors the premium segment, with Strip operators demanding server-based platforms that compress replacement timelines.
Philippines
Entertainment City complexes in Manila Bay add premium table game capacity under PAGCOR licensing frameworks that favor domestic assembly partnerships. The Philippine Amusement and Gaming Corporation imposes localization rules shaping supplier market access strategies. Manila's integrated resort operators wield concentrated procurement leverage, unbundling hardware purchases from service contracts.
Macau
Integrated resort operators reallocate floor space toward electronic gaming machines, displacing traditional VIP baccarat positions. The Gaming Inspection and Coordination Bureau maintains technical standards aligned with Nevada benchmarks but administered through Macau-specific laboratory partnerships. Cotai Strip properties anchor demand for linked-progressive slot systems and licensed content deployments.
Japan
Integrated resort implementation delays in Osaka and Yokohama have compressed near-term equipment procurement timelines into concentrated windows. The Casino Administration Committee establishes technical standards for random number generator certification that mirror international benchmarks. Osaka's Yumeshima Island development anchors the first wave of large-scale integrated resort equipment deployments.
Australia
Tribal and commercial properties across Queensland and New South Wales replace legacy mechanical reels with server-based electronic gaming machines. State-level gaming regulators enforce return-to-player percentage disclosures that shape product configuration requirements. Sydney and Brisbane anchor the premium metropolitan demand cluster, with regional venues following technology adoption lags.
Casino Gaming Equipment Market Vendor Landscape
Top-tier vendors anchor the premium slot and systems infrastructure layers, while mid-tier specialists compete on electronic gaming machine volume and regional manufacturing proximity. The vendor base stratifies across three functional tiers: integrated platform providers with casino management system portfolios, licensed content specialists with linked-progressive networks, and regional fabricators with cost-optimized electronic terminal production. Competitive positioning hardens through M&A consolidation of content libraries and strategic partnerships for cashless wagering platform integration.
Among the integrated platform tier, International Game Technology PLC and Aristocrat Leisure occupy positions that exemplify divergent strategic archetypes—IGT anchoring systems infrastructure while Aristocrat concentrates licensed content and linked-progressive deployment. Novomatic AG sits within the electronic gaming machine volume tier, competing through regional manufacturing footprint and Greentube interactive capabilities. These three entities represent the structural segmentation governing vendor selection criteria across procurement channels.
| Leading Market Players |
|---|
| International Game Technology PLC |
| Aristocrat Leisure |
| Scientific Games Corporation |
| PlayAGS |
| Everi Holdings |
| Konami Holdings Corporation |
| Novomatic AG |
| Incredible Technologies |
| AGS LLC |
| Others |
Supply Flow & Price Mechanics
Captive assembly partnerships in the Philippines anchor both supply positioning and pricing power for equipment vendors serving Entertainment City developments. PAGCOR's localization mandates force foreign manufacturers into domestic joint ventures, compressing margins on hardware while preserving premium capture for software modules. This integration choice simultaneously satisfies regulatory compliance and limits price competition from pure imports.
Pricing Analysis
The bundled-versus-unbundled service split now governs procurement economics across integrated resort operators. Hardware purchases separate from software subscriptions and after-sales maintenance contracts, with Philippine and Singapore campus developments demanding the cleanest unbundling. Price differentiation rests on certification grade—Nevada Gaming Commission RNG validation commands substantial premiums over baseline jurisdictional approvals. Cost compression in the electronic gaming machine tier intensifies as regional fabricators compete on volume, while casino management systems retain pricing power through recurring revenue lock-in. Tribal gaming properties exhibit highest price sensitivity due to compact-negotiated capital constraints, whereas Macau integrated resorts prioritize compliance assurance over unit cost.
Supply Chain Analysis
Warehouse-distribution layers concentrate around Las Vegas, Macau, and Manila to service integrated resort clusters with minimized logistics lead times. Gaming machine logic boards draw from Taiwan and South Korea for specialized semiconductor fabrication, with final assembly anchored in China and the Philippines. Firmware components, display panels, and precision mechanical parts constitute critical input dependencies. Single-source vulnerability in East Asian foundry capacity exposes deployment timelines to geopolitical disruption. Distribution runs through direct sales channels for large-scale operators and regional distributor networks for fragmented tribal and commercial properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where each new jurisdiction adopting Nevada-grade RNG certification standards expands the addressable premium equipment base. The Nevada Gaming Commission's continuous audit trail mandate exemplifies this pattern, institutionalizing recurring validation revenue.
For Market Incumbents: To counter server-based platform commoditization, deepen software subscription attach rates through casino management system integration. Backward integration into firmware development capabilities preserves margin capture against regional electronic gaming machine specialists. Prioritize certification investment in emerging cashless wagering jurisdictions to secure first-mover pricing power.
For New Entrants and Emerging Players: Digital-channel routes through online retail and secondary auction platforms offer lowest-friction entry for replacement parts and refurbished mechanical reel equipment. The tribal gaming compact pipeline across Oklahoma and California represents the most penetrable geography, with distributors serving fragmented procurement patterns. Target casino management system modules as the go-to-market angle, where incumbent switching costs remain lower than in certified hardware.
For Investors and Strategic Acquirers: Roll-up economics work for licensed content specialists because intellectual property portfolios compound player engagement metrics across operator deployments. Five-to-ten-year viability hinges on regulatory divergence around cashless wagering protocols. Acquisition targets should demonstrate embedded firmware talent density and multi-jurisdictional certification track records. The signal to watch is PAGCOR or Macau Gaming Inspection and Coordination Bureau adoption of digital wallet integration standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Server-Based Platform Migration | Enables dynamic RTP configuration and compresses replacement cycles for Macau operators. |
| Multi-Jurisdictional Certification Investment | Secures market access across tribal, commercial, and international regulatory frameworks. |
| Cashless Wagering Infrastructure Partnership | Positions vendors for regulatory divergence between digital wallet and ticket-in-ticket-out protocols. |
| Licensed Content Portfolio Expansion | Builds linked-progressive network effects that lock in operator loyalty and recurring revenue. |
| Regional Manufacturing Footprint Expansion | Satisfies PAGCOR localization requirements and reduces logistics exposure in Philippine market. |
Methodological Framework
Multiple input streams—executive interviews with casino operations directors, procurement leads at integrated resort groups, regulatory affairs specialists at gaming commissions, and firmware engineering heads—were reconciled against secondary validation. Primary fieldwork encompassed discussions with tribal gaming compact negotiators, Nevada Gaming Commission technical auditors, and Philippine Amusement and Gaming Corporation licensing officers. Secondary sources included SEC filings from publicly traded equipment vendors, state gaming board device approval databases, and customs records tracking gaming machine component trade flows. Bottom-up equipment deployment tallies and top-down casino capital expenditure surveys were cross-referenced for triangulation.
Historical replacement cycle patterns were cross-referenced against panel input from casino operators regarding planned refresh timelines. The analytical framework modeled segmentation across product type, technology tier, end-user category, and distribution channel throughout the projection horizon. CAGRs were derived from curve-fitting across disclosed vendor revenue trajectories and operator capital commitment pipelines. Server-based platform penetration rates and cashless wagering regulatory adoption curves served as industry-specific forecast inputs.
Regulatory timeline delays, semiconductor supply disruptions, and jurisdictional licensing reversals are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding technology substitution rates and compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile Gaming Market
Gaming
Metaverse in Gaming Market
Gaming
Europe Serious Gaming Market
Gaming
Arcade Games Market
Gaming
China Subscription-Based Gaming Market
Gaming
Video Game Software Market
Gaming
Serious Games Market
Gaming
GCC Gaming Headsets Market
Gaming
VR Melee Games Market
Gaming
Playstation Network (PSN) Market
Gaming
Latin America Gaming Headsets Market
Gaming
Russia in-Game Advertising Market
Gaming
Global Casino and Gaming Market
Gaming
North America Casino Gambling Market
Gaming
3D Gaming Technology Market
Gaming
Global Battle Royale Games Market