
 Global Game Testing Service Market | 2026-2036
Global Game Testing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Game Testing Service Market Foresight
Subscription-based live-service validation is realigning how game testing contracts are structured, shifting revenue from one-time pre-launch fees to recurring retainers tied to seasonal content drops. Keywords Studios leverages its geographic footprint across multiple production hubs to sustain round-the-clock testing cycles for AAA publishers. TestFort competes on specialized console certification testing, occupying a niche where first-party platform compliance creates high switching costs. iXie Gaming anchors its model with deep backward integration into art production and co-development, extending QA into earlier pipeline stages.
Game testing services encompass systematic defect detection, performance benchmarking, and platform compliance verification executed across software builds prior to commercial release. Functional parameters include frame-rate stability thresholds, memory leak detection protocols, and network latency tolerance bands measured against target hardware profiles. Functionality testing and compatibility testing together command the largest share of contracted hours, though security testing is gaining share as live-service economies attract exploitation attempts. Mobile platform testing generates the highest volume of discrete test cases, while virtual reality testing commands premium pricing due to specialized motion-sickness thresholds and controller tracking precision requirements.
The EU AI Act, GDPR, and REACH frameworks collectively shape how automated testing tools process player behavioral data and how testing facilities manage hardware disposal across European operations. The FCC in the United States imposes electromagnetic compatibility standards that console and peripheral testing must satisfy before retail distribution. Stakeholders must monitor how emerging algorithmic accountability rules in multiple jurisdictions will expand documentation burdens for AI-assisted bug detection systems.
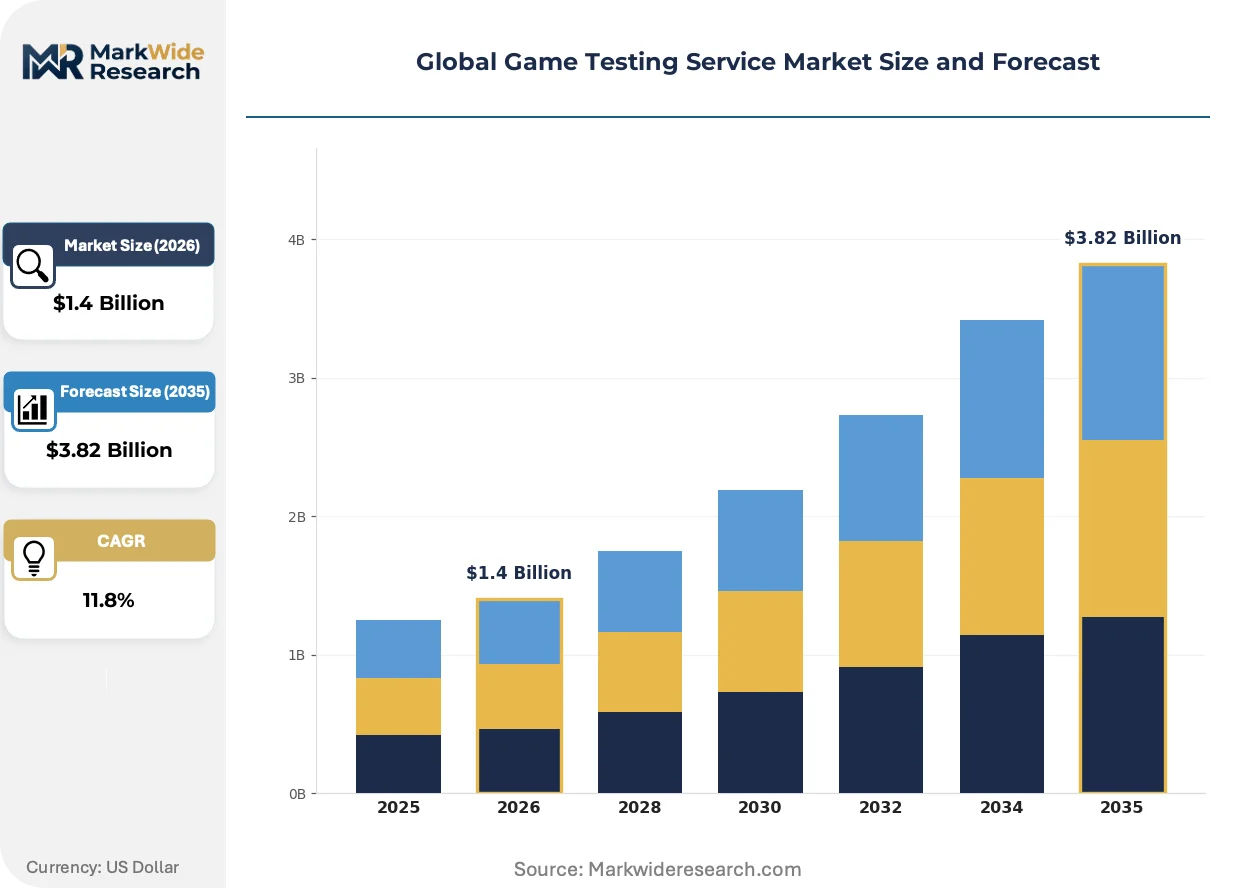
Market Dynamics
Live-service game models are compressing release cycles from annual to quarterly, forcing testing providers to abandon milestone-based contracts in favor of continuous validation pipelines that operate across 24-hour production cycles.
Growth Catalysts
- EU AI Act compliance mandates:Automated testing tools processing player behavioral data now require algorithmic transparency documentation, creating specialized demand for GDPR-compliant validation services across European operations.
- Esports infrastructure density in South Korea:Government-backed game industry clusters in Seoul and Busan sustain concentrated testing ecosystems with direct pipeline access to competitive multiplayer titles requiring real-time network stress validation.
- Cloud-native development pipelines:Containerized build systems enable parallel test execution across distributed hardware profiles, reducing certification cycle times for multi-platform releases.
Market Restraints
- First-party platform certification concentration:Sony, Microsoft, and Nintendo each maintain proprietary technical requirement checklists and submission portals, creating vendor lock-in and redundant compliance costs for multi-platform publishers.
- Specialized motion-sickness threshold testing:Virtual reality validation requires expensive biometric monitoring equipment and controlled laboratory environments that cannot be replicated through distributed remote testing models.
- REACH framework hardware disposal:European testing facilities face escalating costs for compliant disposal of obsolete console development kits and peripheral test equipment containing restricted substances.
Strategic Opportunities
- India's emerging mobile game production hubs:Bangalore and Hyderabad are attracting outsourcing contracts from Western publishers seeking cost-competitive functional testing for high-volume Android device fragmentation matrices.
- Security testing for live-service economies:Virtual currency systems and player-to-player marketplaces attract exploitation attempts, creating premium-priced penetration testing demand that extends beyond traditional QA scopes.
- AI-assisted bug triage convergence:Machine learning classification of crash reports is converging with automated reproduction scripting, enabling testing providers to compress initial defect investigation timelines.
Industry Challenges
- Console certification timeline unpredictability:First-party platform holders maintain opaque submission review queues that disrupt publisher release schedules and force testing vendors to absorb rush fees for expedited re-submissions.
- Biometric lab technician scarcity:Virtual reality motion-sickness testing requires specialized personnel trained in physiological response measurement, with limited certification programs producing qualified candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Game Testing Service Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Functionality Testing, Compatibility Testing, Performance Testing, Security Testing, Localization Testing Game Platform: PC, Console, Mobile, Cloud Gaming, Virtual Reality Testing Model: In-house, Outsourced, Crowdsourced, Automated, Manual End User: Game Developers, Publishers, Independent Studios, Educational Institutions |
| Companies Covered | TestFort, QATestLab, Qualitest Group, KiwiQA, BugRaptors, Keywords Studios, QAble, Starloop Studios, iXie Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Game Testing Service Market Shifts & Advancements
Automated testing architectures are displacing manual execution for regression suites, while regulatory pressure on algorithmic systems forces documentation standards that reshape vendor-client contractual relationships.
Machine learning-based defect prediction is converging with continuous integration pipelines to enable preemptive test case generation before code commits reach build servers. Mid-tier mobile publishers in Southeast Asia are adopting these tools fastest, driven by compressed update cycles for seasonal event content. This convergence is compressing the traditional separation between development and quality assurance functions, forcing testing providers to embed personnel earlier in production timelines.
The EU AI Act's algorithmic accountability requirements are mandating technical documentation for automated testing tools that process player behavioral data or generate synthetic test inputs. Testing vendors must now maintain audit trails demonstrating how AI-assisted bug detection systems arrive at classification decisions. European operations face the steepest compliance burden, with France's CNIL and Germany's data protection authorities already issuing preliminary guidance on documentation standards.
Subscription-based validation contracts are displacing per-milestone pricing as live-service publishers demand continuous coverage across seasonal content drops. This restructuring compresses revenue recognition timelines and forces testing providers to maintain dedicated team allocations for single clients. The shift is most visible in South Korea, where esports-tournament-driven update cycles leave no gap between content releases.
Global Game Testing Service Market Segmentation
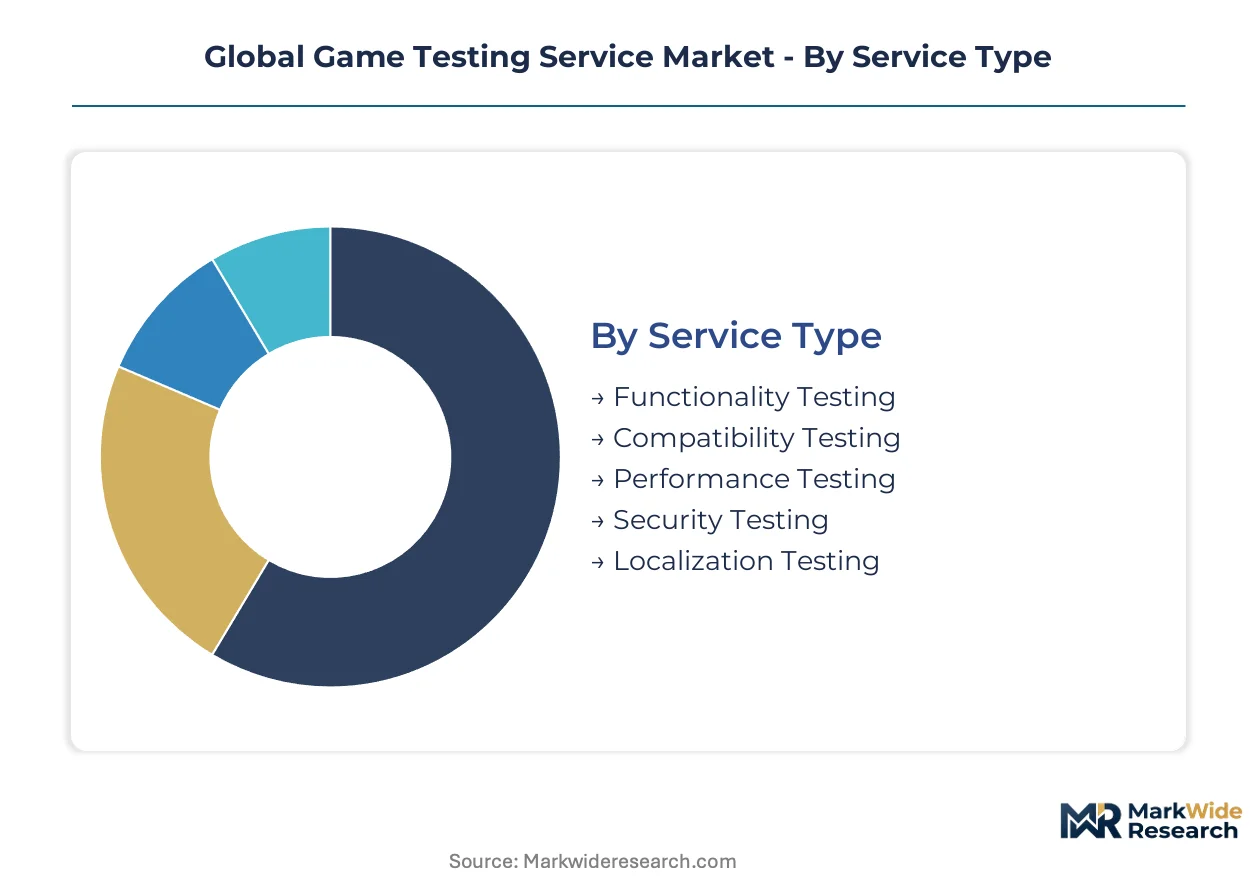
Game testing services fragment across four critical dimensions that determine contract structure, pricing models, and vendor selection criteria. Service type and platform combinations dictate technical capability requirements, while testing model choices reflect trade-offs between speed, cost, and compliance documentation burdens.
Service Type:
Standalone validation services operate at arm's length from development pipelines, whereas embedded testing functions integrate directly into continuous build systems.
- Functionality Testing:Systematic verification of game mechanics, user interface responsiveness, and progression system integrity against design specifications. Demand concentrates in mobile game studios across Bangalore and Hyderabad facing Android device fragmentation matrices that require exhaustive input validation across touch-screen form factors.
- Compatibility Testing:Cross-platform validation ensuring consistent performance across hardware configurations, operating system versions, and peripheral combinations. South Korean publishers with esports-tournament-driven release cycles purchase the highest volumes, as competitive multiplayer titles demand real-time network stress validation across heterogeneous PC builds.
- Performance Testing:Frame-rate stability benchmarking and memory leak detection under sustained load conditions.
- Security Testing:Penetration testing for virtual currency systems and player-to-player marketplace integrity.
- Localization Testing:Cultural adaptation verification for text, audio, and visual assets across linguistic markets.
Functionality testing leads volumes today; security testing is gaining share fastest as live-service economies attract exploitation attempts.
Game Platform:
Platform selection drives certification complexity, with first-party technical requirement checklists creating divergent cost structures across vendor portfolios.
- Mobile:Highest-volume discrete test case generation driven by Android device fragmentation and iOS version compatibility matrices. Indian production hubs in Bangalore and Hyderabad attract outsourcing contracts from Western publishers seeking cost-competitive functional validation.
- Console:Sony, Microsoft, and Nintendo proprietary submission portals create vendor lock-in and redundant compliance costs. TestFort occupies a specialized niche in first-party platform certification where high switching costs protect incumbent positions.
- PC:Open hardware ecosystem testing across graphics driver combinations and peripheral configurations.
- Cloud Gaming:Network latency tolerance validation and streaming quality assurance under variable bandwidth conditions.
- Virtual Reality:Motion-sickness threshold testing and controller tracking precision validation commanding premium pricing due to specialized biometric monitoring equipment requirements.
Mobile platform testing generates the most contracted hours; virtual reality commands the steepest per-hour pricing premiums.
Testing Model:
Model selection reflects organizational trade-offs between capital intensity, intellectual property exposure, and regulatory documentation requirements.
- In-house:Captive QA teams embedded within publisher development studios, prevalent among AAA publishers with sufficient release volume to amortize fixed personnel costs.
- Outsourced:Third-party contracted testing services, with Keywords Studios leveraging geographic footprint across multiple production hubs to sustain round-the-clock cycles.
- Crowdsourced:Distributed tester networks accessing builds through cloud-based distribution platforms.
- Automated:Script-driven regression suites and AI-assisted bug triage systems, with EU AI Act compliance mandates reshaping documentation requirements for behavioral data processing.
- Manual:Human-executed exploratory testing for subjective quality assessment and emergent gameplay issue detection.
Outsourced models dominate contract value today; automated testing is climbing the fastest as machine learning classification converges with continuous integration pipelines.
End User:
Customer type determines contract scale, with live-service publishers shifting from milestone-based fees to recurring retainers tied to seasonal content drops.
- Game Developers:Studios requiring comprehensive validation across development milestones, with iXie Gaming extending QA into earlier pipeline stages through backward integration into art production.
- Publishers:Multi-title organizations consolidating testing spend across portfolio releases, driving demand for continuous validation pipelines operating across 24-hour production cycles.
- Independent Studios:Smaller developers purchasing targeted certification testing for platform compliance.
- Educational Institutions:Universities and training programs acquiring testing services for curriculum development and student project validation.
Publishers represent the largest contract value segment; independent studios are expanding their share fastest as middleware tools lower barriers to commercial release.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's esports infrastructure generates denser testing demand per capita than the United States, where fragmented studio geography spreads contracts across multiple regional hubs.
United States
FCC electromagnetic compatibility standards govern console and peripheral testing protocols for retail distribution. The FCC mandates pre-certification documentation that extends timeline predictability for testing vendors. Seattle and Austin host concentrated publisher headquarters that sustain captive QA teams and outsourced contract pipelines.
South Korea
Government-backed game industry clusters in Seoul and Busan sustain esports-tournament-driven update cycles with no gap between releases. The Ministry of Culture, Sports and Tourism operates direct subsidy programs for testing facility infrastructure. Pangyo Techno Valley anchors a dense ecosystem with pipeline access to competitive multiplayer titles requiring real-time network stress validation.
India
Bangalore and Hyderabad attract Western publisher outsourcing for cost-competitive functional testing across Android device fragmentation matrices. The central government's PLI scheme for electronics manufacturing indirectly supports testing hardware procurement. Karnataka's startup density produces technical talent pipelines for automated testing tool development.
Germany
GDPR and the EU AI Act impose algorithmic transparency documentation burdens on automated testing tools processing player behavioral data. Germany's Federal Data Protection Authority issues preliminary guidance on AI-assisted bug detection audit trails. Berlin and Munich host publisher satellite offices that purchase compliance-heavy European validation services.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification tracks for UK and EU market releases. The Information Commissioner's Office enforces GDPR-equivalent standards on behavioral data processing. London's financial services crossover produces fintech-game hybrid ventures that demand security testing for virtual currency systems.
Global Game Testing Service Market Competitive Landscape
Top-tier vendors anchor multi-hub geographic footprints, while mid-tier specialists occupy certification niches with high switching costs. The vendor base stratifies across three functional tiers: platform certification specialists, embedded co-development partners, and volume-driven functional testing providers. Strategic differentiation concentrates on geographic coverage density, backward integration into art production, and proprietary automated tool development. Consolidation pressure favors vendors with dedicated team allocation capacity for recurring live-service retainers.
Within the certification-specialist tier, TestFort occupies a position exemplifying first-party platform compliance concentration. Keywords Studios anchors the multi-hub geographic coverage archetype with round-the-clock cycle capability. iXie Gaming represents the backward-integrated model extending QA into earlier pipeline stages through art production control.
| Leading Market Players |
|---|
| TestFort |
| QATestLab |
| Qualitest Group |
| KiwiQA |
| BugRaptors |
| Keywords Studios |
| QAble |
| Starloop Studios |
| iXie Gaming |
| Others |
Supply & Pricing Matrix
Biometric monitoring equipment costs for virtual reality testing cascade through pricing tiers as South Korean and Indian facilities absorb divergent hardware procurement burdens. Labor arbitrage in Bangalore and Hyderabad compresses functional testing price floors, while EU AI Act compliance documentation inflates automated testing premiums across European operations.
Pricing Analysis
Capacity additions in India are reshaping price floors for mobile platform testing as Bangalore and Hyderabad facilities expand Android device fragmentation matrices. Three-tier pricing structure across premium, standard, and economy levels separates virtual reality motion-sickness validation from console certification and crowdsourced functional testing. Cost compression in standard-tier compatibility testing intensifies as cloud-native pipelines reduce certification cycle times. Independent studios exhibit the highest price sensitivity, while AAA publishers with live-service retainers prioritize dedicated team allocation over per-hour rates.
Supply Chain Analysis
Freight costs for obsolete console development kit disposal under REACH framework obligations inflate European testing facility operating expenses. Hardware procurement concentrates in South Korea, Taiwan, and China for biometric sensors, development kits, and automated testing infrastructure. Specialized motion-sickness monitoring equipment and controlled laboratory environments draw from medical device supply chains, creating cross-industry competition for scarce components. Single-source vulnerability around first-party platform certification tools disrupts multi-platform publisher timelines. Distribution runs through direct publisher contracts and esports tournament pipeline access in Seoul and Busan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic accountability mandates compound testing demand by forcing documentation standards that reshape vendor-client contractual relationships across European operations.
For Market Incumbents: Cement round-the-clock coverage advantages by expanding dedicated team allocations for live-service publishers with quarterly release cycles. Invest in GDPR-compliant automated testing tool development before France's CNIL and Germany's Federal Data Protection Authority finalize audit trail standards. Absorb biometric lab technician scarcity through captive training partnerships with Seoul and Busan educational institutions. For New Entrants and Emerging Players: The price-point gap between premium virtual reality validation and economy-tier mobile functional testing creates entry space for mid-market security testing specialization. Target India's emerging mobile game production hubs in Bangalore and Hyderabad with cost-competitive automated regression suites. Pursue penetration testing for live-service virtual currency systems as the most penetrable segment with premium pricing tolerance. For Investors and Strategic Acquirers: Roll-up economics work for regional certification specialists because first-party platform compliance creates high switching costs that protect incumbent positions. Five-to-ten year viability hinges on consolidation of vendors with dedicated team allocation capacity for recurring live-service retainers. Watch for AI-assisted bug triage convergence with continuous integration pipelines as the inflection signal compressing initial defect investigation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| AI Compliance Documentation Investment | EU AI Act mandates algorithmic transparency for tools processing player behavioral data in European operations. |
| Biometric Lab Capacity Expansion | Virtual reality motion-sickness testing commands premium pricing due to specialized equipment and technician scarcity. |
| Live-Service Retainer Conversion | Subscription-based contracts displace milestone pricing as esports-driven update cycles eliminate release gaps. |
| Security Testing Capability Buildout | Penetration testing for virtual currency systems attracts exploitation attempts and premium pricing. |
| India Hub Geographic Expansion | Bangalore and Hyderabad attract Western publisher outsourcing for Android device fragmentation matrices. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with QA directors at Keywords Studios and TestFort, platform certification leads at first-party console holders, esports tournament operators in Seoul, and automated testing tool developers with secondary validation against SEC filings, FCC electromagnetic compatibility databases, EU AI Act regulatory texts, and Korean Ministry of Culture subsidy program disclosures. Bottom-up service-type segmentation triangulated against top-down publisher spending pattern analysis.
Historical reference periods anchored the projection horizon through verified contract value flows and vendor capacity utilization rates across functionality, compatibility, performance, security, and localization testing service types. Modeled dimensions spanned platform ecosystem, testing model archetype, and end-user category with CAGRs derived from regression analysis of live-service content validation frequency and automated tool adoption curves. Forecast inputs incorporated esports tournament calendar density and cloud-native pipeline penetration rates.
Caveats apply where first-party platform certification timeline unpredictability or biometric lab technician scarcity could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Game Applications Market
Gaming
Social Gaming Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Europe Video Game Software Market
Gaming
Serious Games Market
Gaming
Global Casino and Gaming Market
Gaming
LAMEA Gaming Posters Market
Gaming
Global Tarot Cards Market
Gaming
Virtual Sports Market
Gaming
Chinese Gaming Industry Market
Gaming
United States Gaming Market
Gaming
Game Engine Management Market
Gaming
3D Gaming Technology Market
Gaming
North America Casino Gambling Market
Gaming
Flat Gaming Monitors Market