
 Global Online Simulation Games Market | 2026-2036
Global Online Simulation Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Simulation Games Market Foresight
Revenue weight from education and corporate training verticals is shifting upward as institutions adopt simulation modules for workforce readiness. Electronic Arts sustains dominance in sports simulation through annual franchise cycles and live service architecture. Tencent leverages its super-app ecosystem to distribute management simulations across WeChat and QQ channels. Epic Games anchors technical credibility through Unreal Engine licensing that powers third-party simulation developers.
Global online simulation games are interactive software environments that model real-world systems, processes, or scenarios through physics engines, procedural generation, and networked multiplayer architecture, serving entertainment, training, and research purposes. The platform dimension shows cloud gaming emerging as the fastest-expanding delivery mechanism, though PC retains the deepest margin pools from hardware-tied spending. Management simulations within the game type category occupy a mature but stable position, while flight simulation experiences disproportionate growth from cross-licensing partnerships with aviation manufacturers. The monetization model landscape stratifies around freemium and in-game purchases, where live service content pipelines extract recurring revenue from engaged player bases.
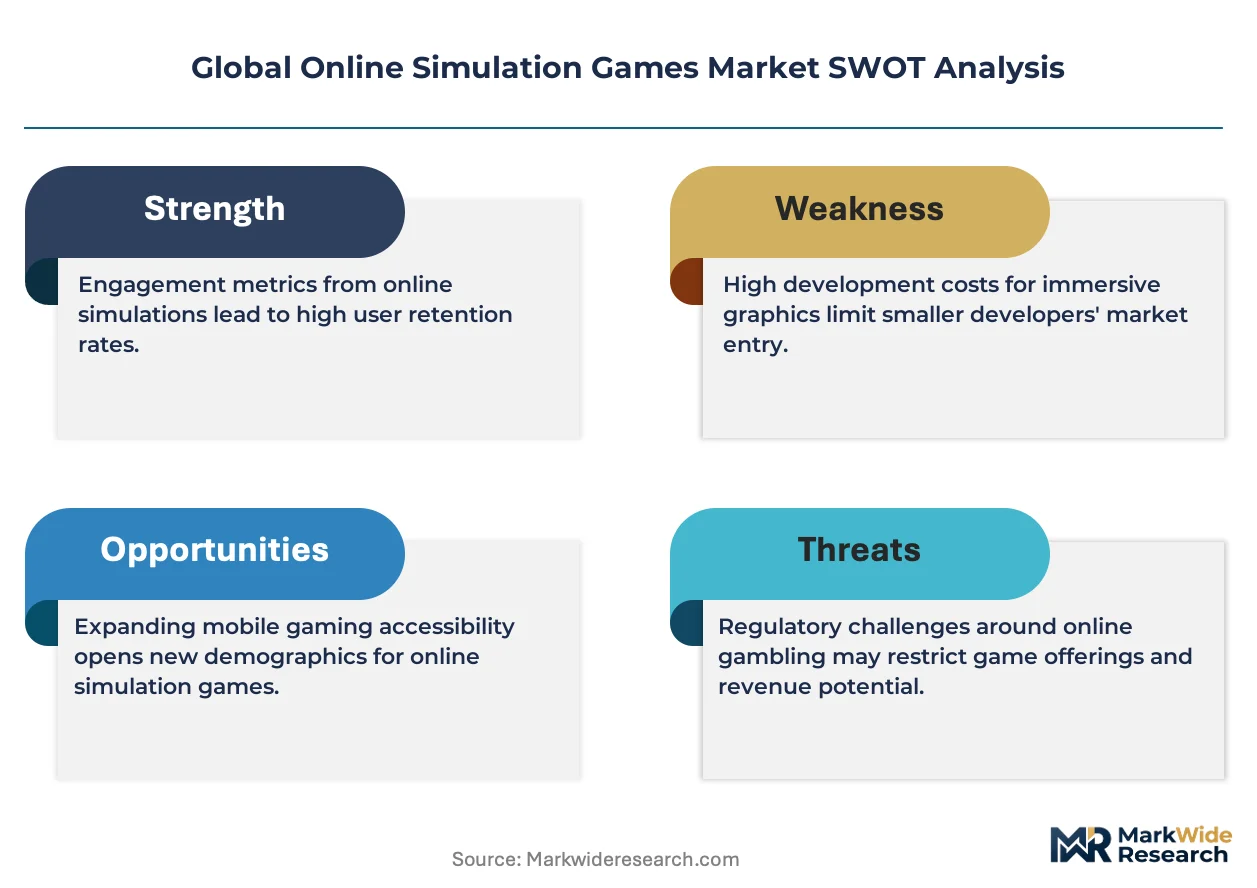
The US Federal Trade Commission scrutinizes in-game purchase mechanics and dark pattern design, pressuring studios to disclose odds and implement parental controls. China's National Press and Publication Administration enforces strict approval quotas and playtime limits for minors, constraining release velocity and youth-targeted monetization. South Korea's Game Rating and Administration Committee mandates probability disclosures for randomized content, shaping how gacha-style mechanics penetrate simulation titles. Stakeholders must monitor evolving classification frameworks that could reclassify certain simulation mechanics as gambling-adjacent, triggering jurisdiction-specific compliance costs and platform distribution restrictions.
Market Dynamics
Cloud gaming infrastructure is compressing hardware barriers and redistributing value capture from device manufacturers to streaming platform operators and content licensors.
Growth Catalysts
- Education Sector Integration:Universities and vocational institutes deploy simulation modules for workforce readiness training, creating institutional procurement pipelines that bypass consumer volatility.
- China's Dual Carbon Goals:Studios optimize server energy consumption to align with MEE emissions targets, unlocking green financing and state-backed data center partnerships.
- 5G Rollout in South Korea:KT Corporation and SK Telecom infrastructure investments enable sub-20ms latency for competitive multiplayer simulations, driving premium subscription uptake.
Market Restraints
- GPU Supply Concentration:Taiwan-based foundry capacity constraints inflate cloud rendering costs and extend server deployment timelines for new entrants.
- China's Approval Quotas:NPPA release velocity caps constrain monetization from youth-targeted titles and compress foreign studio market access.
- Technical Talent Scarcity:Physics engine specialists and network synchronization engineers command compensation premiums that strain mid-tier development budgets.
Strategic Opportunities
- India's Underpenetrated Market:Jio's fiber expansion and affordable smartphone penetration create first-mover advantages for localized management simulations.
- Aviation Cross-Licensing:Boeing and Airbus partnerships for certified flight training modules open B2B revenue streams with regulatory moats against consumer competitors.
- AI-NPC Convergence:Large language model integration with procedural generation enables persistent, adaptive simulation environments that extend session duration.
Industry Challenges
- Live Service Pipeline Burnout:Continuous content delivery demands exhaust creative teams and inflate operational overhead for sustained player retention.
- Probability Disclosure Compliance:South Korea's GRAC randomized content mandates require architectural overhauls of gacha mechanics, delaying feature releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Simulation Games Market |
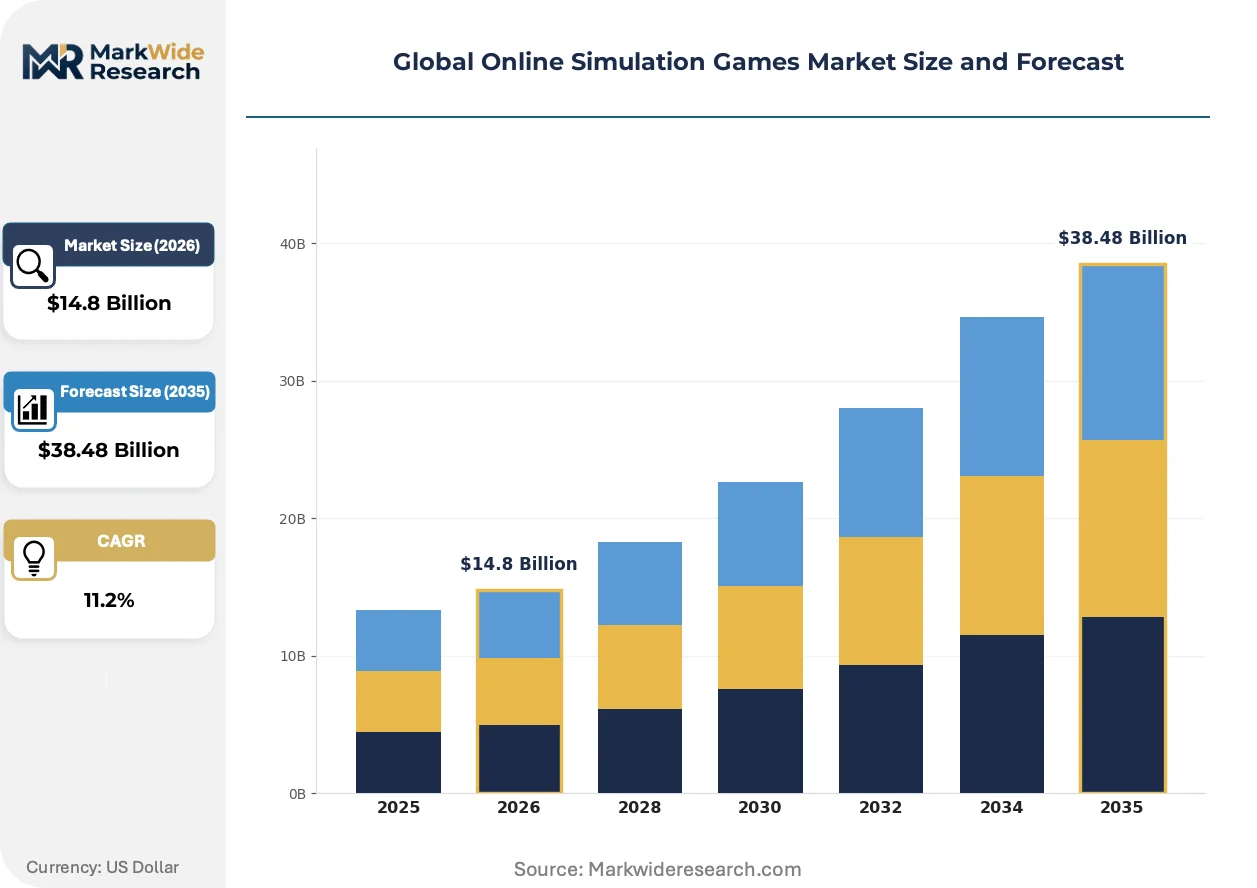
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Role-Playing, Racing, Flight, Management Platform: PC, Mobile, Console, Cloud Gaming Monetization Model: Freemium, Subscription, One-Time Purchase, In-Game Purchases Target Audience: Casual Gamers, Competitive Players, Educators, Trainers |
| Companies Covered | Take-Two Interactive, Sony Interactive Entertainment, Epic Games, Nintendo, NetEase Games, Electronic Arts, Tencent, Zynga, Roblox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Simulation Games Market Shifts & Advancements
Neural rendering and edge computing architectures are dissolving the boundary between local and cloud execution, forcing studios to redesign monetization around session continuity rather than ownership.
Neural radiance fields (NeRF) are electrifying environmental asset creation by compressing photogrammetry pipelines from weeks to hours. Mid-sized studios in Poland and Canada adopt NeRF workflows to match AAA visual fidelity without expanding art teams. This compression is electrifying competitive parity between independent developers and franchise incumbents, fragmenting genre leadership.
The EU AI Act's risk classification framework imposes transparency obligations on procedural content systems that adapt difficulty or generate narrative branches. Studios must document training data provenance and algorithmic decision logic for titles distributed in Germany and France. Management simulation developers face particular scrutiny where AI-driven NPC economic behaviors could be classified as high-risk automated decision-making.
Subscription bundling is consolidating player spending into platform ecosystems rather than title-specific purchases. Microsoft and Sony integrate simulation titles into Game Pass and PS Plus catalogs, displacing unit sales with engagement-based revenue shares. This reconfiguration is most visible in the US and UK, where AAA sports simulation franchises now derive majority revenue from platform licensing rather than direct consumer transactions.
Global Online Simulation Games Market Segmentation
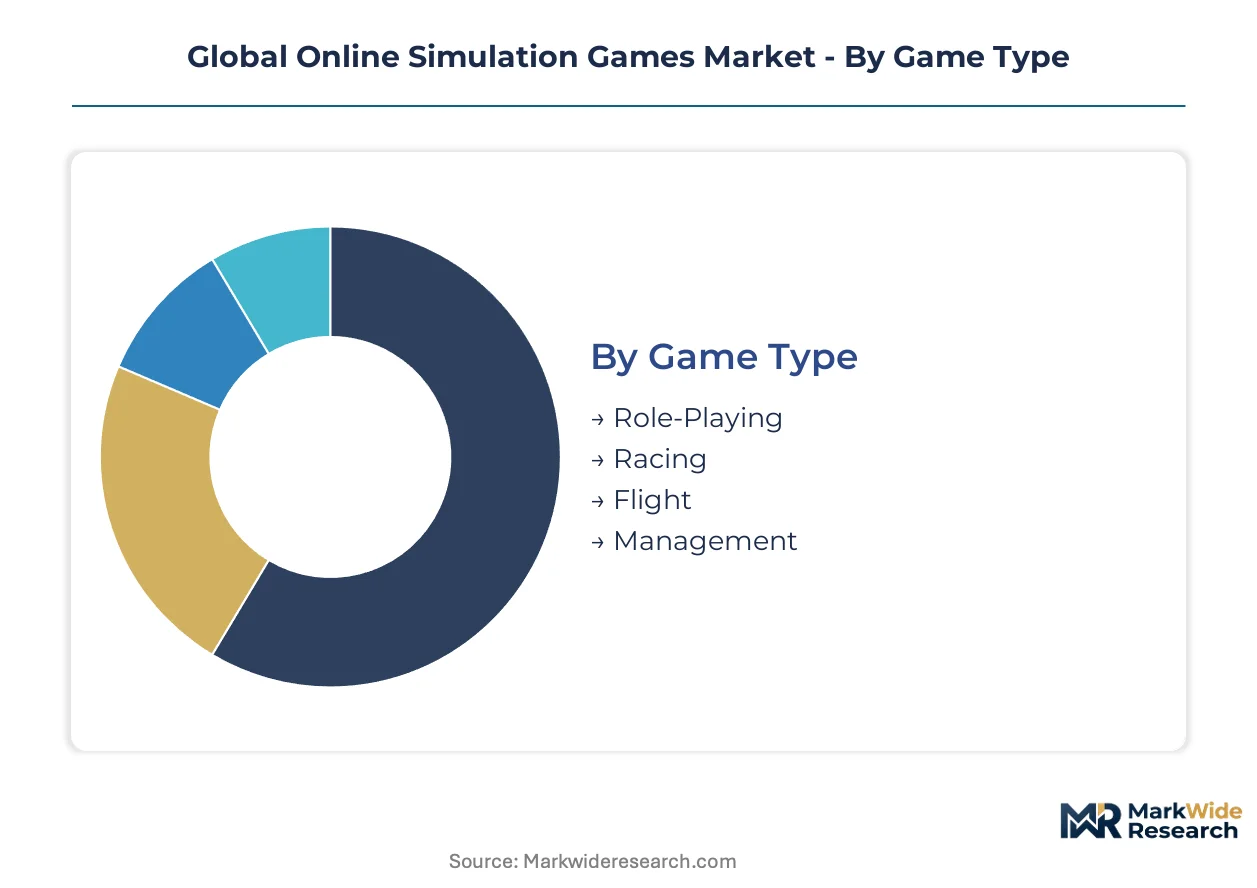
Segmentation in online simulation games reveals how technical architecture and audience behavior split revenue across incompatible business models. Platform choice determines latency tolerance and monetization ceiling. Game type alignment with real-world skill transferability creates divergent growth trajectories across consumer and institutional buyers.
Game Type:
Upgrade cycles in simulation subgenres track hardware refresh patterns and licensing partnership maturity rather than narrative content exhaustion.
- Role-Playing:Persistent world architecture with avatar progression systems and social economy layers. South Korean PC bang culture sustains concentrated demand for MMORPG-style simulations with competitive ranking ladders. The upgrade cycle compresses as live service content replaces boxed releases.
- Flight:Physics-engine fidelity demands specialist input from aviation manufacturers for certification-grade training modules. Cross-licensing partnerships with Boeing and Airbus concentrate procurement in US and European flight schools and defense contractors. Regulatory moats protect B2B revenue streams from consumer competitor erosion.
- Racing:Tire-wear algorithms and aerodynamic modeling differentiate premium titles. Console-first release strategies dominate mass-market positioning.
- Management:Economic system depth and scenario branching drive institutional adoption for workforce training. Mature but stable positioning reflects saturated consumer penetration.
Management simulations sit at the top of the volume ranking, with flight simulations climbing the fastest.
Platform:
Cost tier stratification separates hardware-captive spending from streaming-enabled access democratization.
- PC:Modifiable client architecture supports deep simulation complexity and community content extensions. The deepest margin pools derive from GPU-tied spending on visual fidelity and peripheral integration. Steam and Epic Games Store distribution concentrates revenue in North America and Western Europe.
- Cloud Gaming:Edge computing infrastructure compresses hardware barriers for latency-tolerant simulation genres. Microsoft xCloud and NVIDIA GeForce NOW licensing redistributes value capture from device manufacturers to platform operators. 5G rollout in South Korea and fiber expansion in India accelerate geographic penetration.
- Mobile:Touch interface constraints simplify control schemes for casual management and role-playing formats. Super-app distribution through WeChat and QQ channels dominates Chinese market access.
- Console:Controller-optimized physics implementations prioritize accessibility over simulation depth. Subscription bundling into Game Pass and PS Plus catalogs displaces unit sales with engagement-based revenue shares.
PC retains the largest revenue base, while cloud gaming gains share fastest.
Monetization Model:
Customer type divergence splits predictable institutional procurement from volatile consumer spending patterns.
- Freemium:Gated progression systems with optional acceleration purchases. South Korea's GRAC probability disclosure mandates reshape randomized content architecture for simulation titles with gacha-style mechanics.
- In-Game Purchases:Cosmetic and functional microtransactions sustain live service pipelines. FTC scrutiny of dark pattern design pressures studios to disclose odds and implement parental controls.
- Subscription:Platform-integrated catalogs displace title-specific ownership. Engagement-based revenue shares now constitute majority revenue for AAA sports simulations in US and UK markets.
- One-Time Purchase:Boxed release model persists for certification-dependent flight training modules with regulatory update obligations.
In-game purchases dominate consumer revenue, with subscription models expanding most quickly.
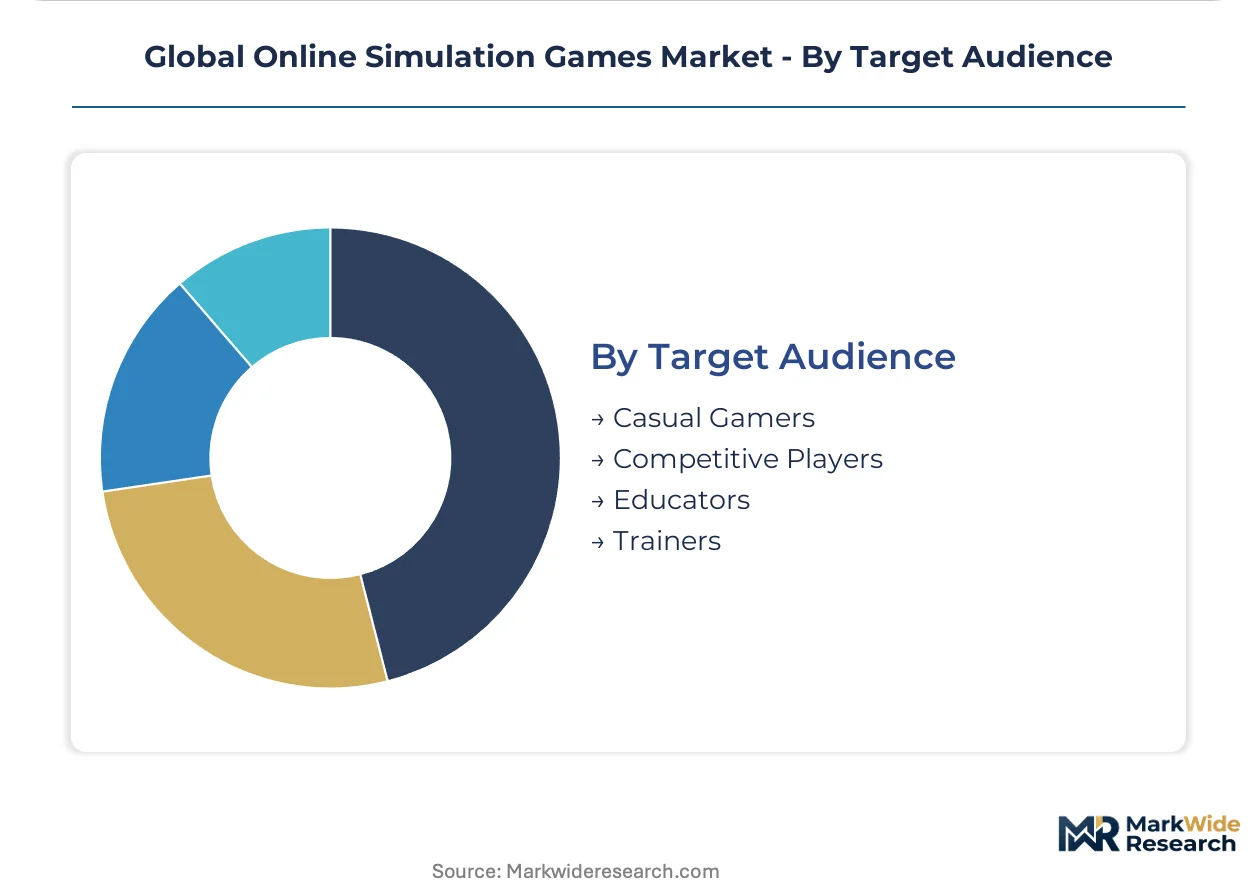
Target Audience:
Application maturity separates saturated entertainment consumption from emerging institutional procurement pipelines.
- Casual Gamers:Session-brief mobile and cloud-accessible simulations with simplified control schemes. Jio's fiber expansion in India targets this segment with localized management titles.
- Competitive Players:Ranked ladder systems and esports infrastructure dependence. KT Corporation and SK Telecom 5G investments in South Korea enable sub-20ms latency requirements.
- Educators:Simulation modules for workforce readiness training in universities and vocational institutes. Institutional procurement bypasses consumer spending volatility with multi-year licensing agreements.
- Trainers:Certified skill transfer modules with regulatory compliance documentation. Aviation and medical simulation verticals concentrate in US and European defense and healthcare contracting.
Casual gamers represent the largest addressable base, with educators gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the competitive multiplayer simulation infrastructure through KT Corporation and SK Telecom 5G deployments that enable sub-20ms latency for esports-grade titles.
United States
Institutional procurement from universities and vocational institutes drives simulation-based workforce training adoption. The FTC scrutinizes in-game purchase mechanics and dark pattern design, pressuring studios to disclose odds and implement parental controls. Greater Los Angeles and Seattle metro areas concentrate development studios building live service architectures for sports and management simulations.
China
Super-app distribution through WeChat and QQ channels dominates management simulation access for mobile-first audiences. The National Press and Publication Administration enforces strict approval quotas and playtime limits for minors, constraining release velocity and youth-targeted monetization. Shanghai and Shenzhen studios optimize server energy consumption to align with MEE emissions targets under dual carbon goals.
South Korea
PC bang culture sustains concentrated demand for MMORPG-style simulations with competitive ranking ladders. The Game Rating and Administration Committee mandates probability disclosures for randomized content, reshaping gacha-style mechanics in simulation titles. Busan-Ulsan corridor hosts infrastructure investments enabling premium subscription uptake for cloud-streamed competitive simulations.
Germany
Aviation cross-licensing partnerships with Airbus concentrate procurement for certified flight training modules in European flight schools. The EU AI Act imposes transparency obligations on procedural content systems, requiring documentation of training data provenance for titles distributed nationwide. Munich and Hamburg clusters specialize in regulatory-compliant simulation modules for defense and healthcare contracting.
India
Jio's fiber expansion and affordable smartphone penetration create first-mover advantages for localized management simulations targeting casual gamers. The central bank's digital payment infrastructure supports microtransaction monetization models. Maharashtra and Karnataka states concentrate development talent for mobile-optimized simulation content.
Global Online Simulation Games Market Competitive Landscape
Live service content pipeline investments dominate the current landscape as studios compete for sustained player retention through continuous feature delivery. The vendor base stratifies across three tiers: franchise incumbents with annual release cycles, platform operators with subscription bundling leverage, and independent developers leveraging neural rendering workflows for visual parity. Strategic archetypes include ecosystem-integrated distributors, engine-technology licensors, and certification-dependent B2B specialists. Technology licensing agreements and subscription catalog integrations represent the dominant competitive moves reshaping value capture.
Among ecosystem-integrated distributors, Tencent and NetEase Games occupy positions defined by super-app distribution leverage and regulatory navigation expertise. Epic Games exemplifies the engine-technology licensor archetype through Unreal Engine penetration across third-party simulation developers. Electronic Arts represents the franchise incumbent model with annualized sports simulation cycles and live service monetization infrastructure.
| Leading Market Players |
|---|
| Take-Two Interactive |
| Sony Interactive Entertainment |
| Epic Games |
| Nintendo |
| NetEase Games |
| Electronic Arts |
| Tencent |
| Zynga |
| Roblox |
| Others |
Supply & Pricing Matrix
Institutional procurement pipelines for workforce training modules are compressing price elasticity as universities and vocational institutes prioritize multi-year licensing stability over per-unit cost optimization, forcing studios to restructure cost bases around recurring revenue predictability rather than transactional margin capture.
Pricing Analysis
GPU foundry capacity constraints in Taiwan and memory supply volatility are passing through to cloud rendering costs that studios must absorb or distribute across subscription tiers. Pricing stratifies across premium certification-grade flight modules, standard live-service management simulations, and economy-tier mobile casual titles. Cost compression in the economy tier is intensifying because Jio's fiber expansion in India is democratizing access and triggering volume-based competition. Casual mobile gamers exhibit highest price sensitivity, while defense contractors and aviation training centers demonstrate inelastic demand for regulatory-compliant modules.
Supply Chain Analysis
Physics engine licensing rests on concentrated expertise pools in Poland, Canada, and South Korea where neural rendering specialists command compensation premiums. Raw material dependencies span semiconductor fabrication for cloud infrastructure, specialized motion-capture hardware for animation pipelines, and aviation manufacturer IP for certified flight modules. Single-source vulnerability concentrates around Taiwan-based foundry capacity for GPU provisioning that underpins cloud streaming architectures. Distribution runs through platform-integrated subscription catalogs that displace direct studio-to-consumer relationships with engagement-based revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in online simulation games hinges on shifting revenue mix toward institutional procurement with predictable multi-year cycles, while cloud infrastructure cost compression unlocks premium-tier accessibility for previously hardware-constrained segments.
For Market Incumbents: Lock in exclusive aviation cross-licensing partnerships with Boeing and Airbus to erect regulatory moats against consumer-grade competitors. Deepen backward integration into proprietary cloud rendering infrastructure to reduce dependency on Taiwan foundry capacity and capture value migrating from device manufacturers to platform operators. The threat of AI-NPC convergence from well-capitalized technology entrants demands accelerated investment in large language model integration for persistent world architectures. For New Entrants and Emerging Players: Cloud platform operators represent the critical channel partner for bypassing hardware distribution barriers and accessing subscription bundling revenue pools. India's underpenetrated management simulation segment offers the most accessible white-space target given Jio's fiber expansion and localized content gaps. A direct-to-educator go-to-market angle targeting vocational institutes with workforce readiness modules bypasses consumer marketing spend intensity. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier studios possessing neural rendering workflows and aviation certification expertise that larger franchises must acquire to fill capability gaps. Long-term viability over the coming decade favors entities with institutional procurement relationships and regulatory compliance documentation rather than pure consumer entertainment exposure. Watch for inflection in South Korea's GRAC enforcement patterns that could reclassify gacha-style mechanics as gambling-adjacent and trigger jurisdiction-specific compliance cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Aviation Cross-Licensing Agreement | Boeing and Airbus partnerships erect regulatory moats protecting B2B revenue streams from consumer competitor erosion. |
| Neural Rendering Workflow Adoption | NeRF compression pipelines enable mid-sized Polish and Canadian studios to match AAA visual fidelity without expanding art teams. |
| Cloud Platform Integration | Microsoft xCloud and NVIDIA GeForce NOW licensing redistributes value capture from device manufacturers to content licensors. |
| Institutional Procurement Pipeline | University and vocational institute contracts bypass consumer spending volatility with predictable multi-year revenue visibility. |
| AI-NPC Convergence Investment | Large language model integration with procedural generation extends session duration and live service monetization potential. |
Research Methodology
Multiple input streams — executive interviews with live service operations directors, platform partnership leads, and educational procurement officers — were reconciled against secondary validation from SEC filings, hyperscaler capex disclosures, and regional regulatory filings. Physics engine specialists, network synchronization engineers, and cloud infrastructure architects provided technical architecture perspectives. Bottom-up title-level revenue modeling and top-down sectoral expenditure analysis were triangulated to constrain forecast variance.
Historical trajectory patterns were cross-referenced against panel input from industry stakeholders to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include game type, platform architecture, monetization model, and target audience vertical. CAGRs were derived through iterative convergence of demand-side adoption curves and supply-side capacity constraints. Forecast inputs incorporated 5G rollout velocity in South Korea, NPPA approval quota dynamics in China, and Jio fiber penetration metrics in India.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory reclassification of randomized content mechanics and foundry capacity allocation shifts in Taiwan. Forecasts reflect documented assumptions regarding institutional procurement adoption rates and cloud infrastructure cost trajectories. Material deviation in GRAC enforcement patterns or NPPA release velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Virtual Sports Market
Gaming
Gaming Chair Market
Gaming
Australia Casino Tourism Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Serious Games Market
Gaming
Cloud Gaming Market
Gaming
VR Gaming Console Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Global Casino Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Playstation Network (PSN) Market
Gaming
Global Gaming Market
Gaming
Europe Gaming Peripherals Market
Gaming
China Gaming Headsets Market
Gaming
Australia Gaming Gadgets Market
Gaming
Germany Gaming Headset Market