
 Video Game Software Market | 2026-2036
Video Game Software Market Size, Share, and Industry Trends Forecast 2026-2036
Video Game Software Market Outlook
Japanese console development pipelines is hardening as semiconductor allocation prioritizes flagship hardware cycles. Sony Interactive Entertainment leverages exclusive intellectual property to sustain premium pricing power across generations. Tencent Interactive Entertainment anchors mobile free-to-play monetization through gacha mechanics and social distribution networks. Electronic Arts competes on annual sports franchise iteration with live service content calendars.
Video game software comprises executable code, digital assets, and runtime engines designed to render interactive experiences across computing devices. Modern builds require shader compilation, physics simulation, and networked multiplayer synchronization at frame rates exceeding 60 Hz for competitive validity. The platform dimension shows PC and console segments commanding the highest per-user revenue through upfront purchases and downloadable content. Mobile dominates unit volume through microtransaction economies, while VR remains nascent with hardware dependency constraining addressable audience scale.
FDA content rating guidelines in the United States, PEGI standards across European markets, and China's NMPA title approval framework collectively govern market access and content eligibility. These regimes enforce age-gating, spending limits, and cultural review that directly shape product design budgets and localization priorities. Stakeholders must monitor evolving classification criteria and platform-holder enforcement shifts to anticipate portfolio reallocation requirements.
Market Dynamics
Cloud streaming infrastructure is compressing hardware dependency cycles while China's NMPA approval bottlenecks extend go-to-market timelines for foreign publishers.
Growth Catalysts
- Subscription service penetration:Xbox Game Pass and PlayStation Plus normalize recurring revenue models. Publishers secure predictable cash flows independent of unit sales volatility.
- Mobile microtransaction maturation:Gacha mechanics and battle pass systems in Southeast Asia drive sustained per-user monetization. Social distribution networks amplify organic acquisition at minimal marketing cost.
- Cross-platform engine standardization:Unreal Engine 5 and Unity runtime deployments reduce porting overhead. Development teams ship simultaneous releases across PC, console, and mobile from unified codebases.
Market Restraints
- Semiconductor allocation constraints:Foundry capacity prioritization for flagship console SoCs delays mid-cycle hardware revisions. Supply scarcity elevates component costs for peripheral manufacturers.
- Content approval latency:China's NMPA review queues extend localization timelines by 12-18 months. Publishers defer Chinese market entry or accept revenue recognition delays.
- Platform holder gatekeeping:Apple App Store and Google Play commission structures compress mobile developer margins. Alternative distribution channels face technical and contractual friction.
Strategic Opportunities
- India's underpenetrated mobile base:Reliance Jio infrastructure expansion reduces data cost barriers. Localized content in Hindi and regional languages unlocks first-time gamer cohorts.
- Generative AI asset pipelines:Procedural texture generation and NPC dialogue systems compress art production timelines. Mid-size studios close quality gaps with AAA production values.
- VR enterprise training verticals:Healthcare simulation and industrial safety applications bypass consumer hardware adoption constraints. B2B contracts deliver guaranteed revenue without retail channel dependency.
Industry Challenges
- Live service operational complexity:Persistent content calendars demand 24/7 server infrastructure and community management. Talent scarcity in DevOps and data engineering elevates compensation costs.
- IP licensing fragmentation:Music rights, athlete likenesses, and vehicle manufacturer approvals require multi-party negotiations. Sports franchises face renewal uncertainty that disrupts annual release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Game Software Market |
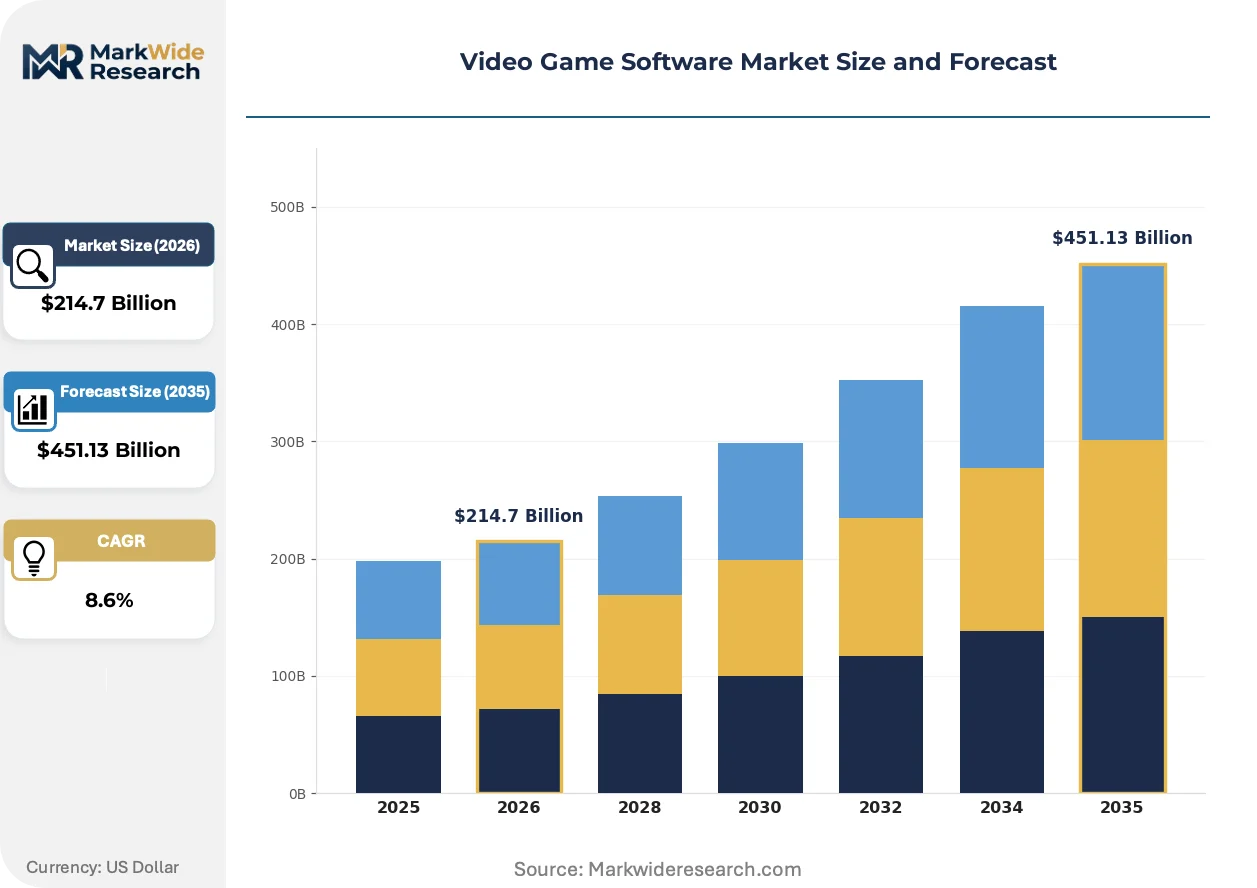
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $451.13 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action, Adventure, RPG, Simulation Distribution Channel: Digital Download, Retail Store, Subscription Service, Cloud Streaming End User: Casual Gamers, Professional Players, Educational Institutions, Streaming Platforms Platform: PC, Console, Mobile, VR |
| Companies Covered | NetEase Games, Electronic Arts, Sony Interactive Entertainment, Epic Games, Valve Corporation, Tencent Interactive Entertainment, Nintendo, Take-Two Interactive, Microsoft Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Game Software Market Strategic Shifts
Real-time rendering pipelines and AI-assisted production tools are compressing development timelines while regulatory fragmentation forces parallel compliance architectures.
Neural network-based upscaling is unifying visual fidelity across hardware tiers. NVIDIA DLSS and AMD FSR adoption spans indie studios and AAA publishers alike. Frame generation technology enables 4K output on mid-range GPUs, extending active install base viability and reducing mandatory hardware upgrade cycles.
China's NMPA content review framework tightens eligibility criteria for foreign titles. Approval quotas and cultural compliance requirements elevate localization budgets. Publishers pre-position simplified Chinese builds and censorship-compliant asset variants to minimize post-submission revision cycles.
Game-as-a-service monetization supersedes upfront purchase models in competitive multiplayer segments. Cosmetic economies and seasonal content drops replace boxed product launches. Free-to-play entry points dominate user acquisition in Brazil and Indonesia, where disposable income constraints favor zero-barrier entry with discretionary spending depth.
Video Game Software Market Segmentation
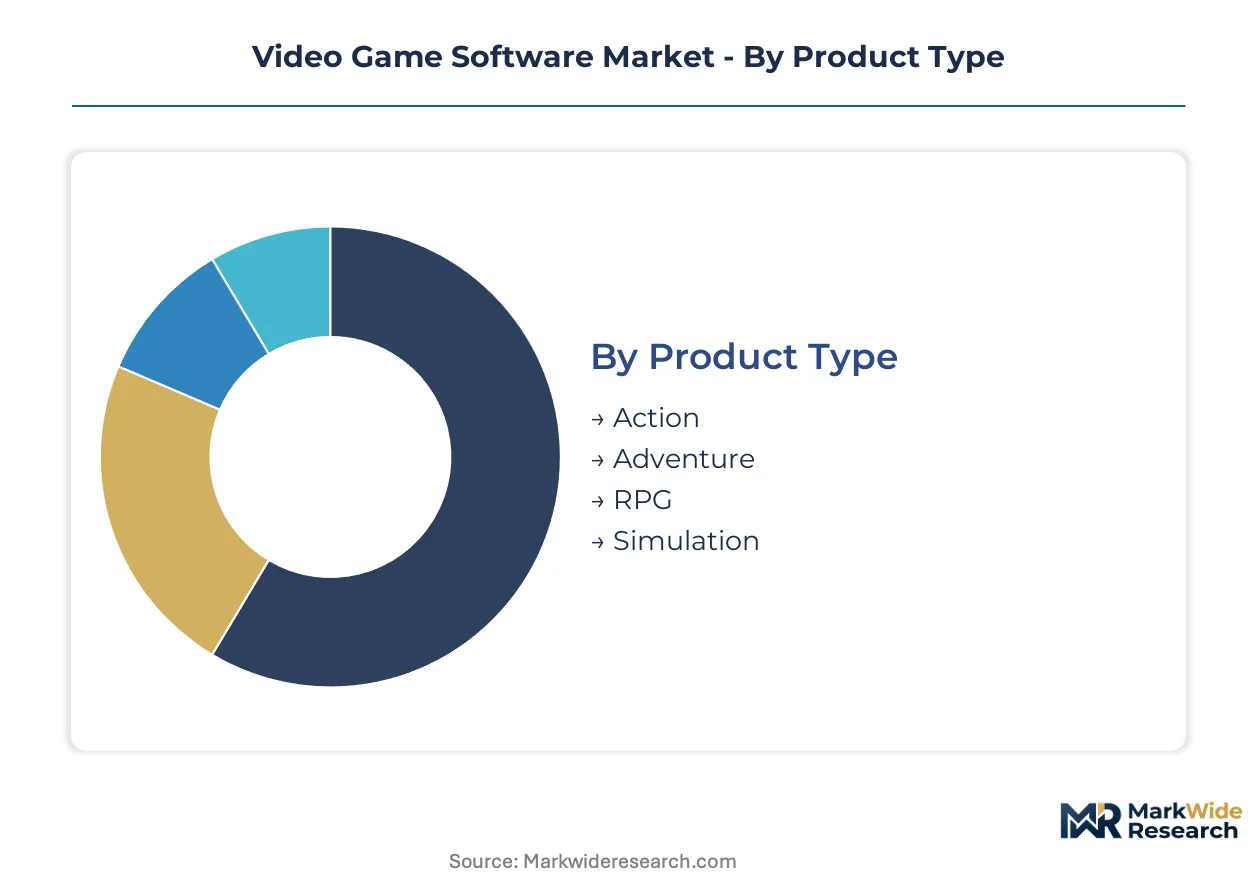
Platform economics fragment the video game software market into divergent monetization architectures. Product design specifications, distribution infrastructure, and user engagement patterns vary dramatically across segments, forcing publishers to maintain parallel development pipelines and compliance frameworks.
Product Type:
Volume concentrates in multiplayer service titles while premium pricing persists in narrative-driven single-player experiences.
- Action:Fast-twitch combat systems and competitive multiplayer frameworks dominate development resource allocation. Demand clusters in Southeast Asia and Brazil where free-to-play battle royale titles monetize through cosmetic economies and seasonal battle passes.
- Adventure:Environmental storytelling and puzzle mechanics require concentrated art production cycles. Japan and Western Europe sustain premium upfront pricing for narrative-heavy releases, though development timelines extend 4-6 years for flagship franchises.
- RPG:Character progression systems and branching dialogue trees generate the highest per-user session durations. China's NMPA approval requirements disproportionately impact RPG content due to narrative complexity and cultural review sensitivity.
- Simulation:Physics engines and emergent gameplay systems attract dedicated hobbyist communities. Niche addressable audiences limit marketing budgets but sustain premium pricing through enthusiast loyalty and modding ecosystem support.
Action titles command current revenue concentration. RPG systems are climbing the fastest as live service mechanics infiltrate traditionally single-player formats.
Distribution Channel:
Margin compression accelerates where platform holders extract commission rents, favoring direct-to-consumer infrastructure investments.
- Digital Download:Immediate fulfillment and dynamic pricing algorithms maximize revenue per user. Steam, Epic Games Store, and platform-native marketplaces compete on developer revenue share splits and exclusive release windows.
- Retail Store:Physical media production and logistics networks retain relevance in collector editions and hardware bundle strategies. Japan and parts of Eastern Europe maintain retail dependency due to payment infrastructure constraints.
- Subscription Service:Xbox Game Pass and PlayStation Plus normalize library access over ownership. Publishers sacrifice unit margin for guaranteed minimum guarantees and discovery algorithm placement.
- Cloud Streaming:Server-side rendering eliminates hardware dependency but demands low-latency network infrastructure. Southeast Asian 5G rollouts and India's Jio fiber expansion unlock addressable audiences previously excluded by GPU scarcity.
Digital download infrastructure anchors present monetization. Cloud streaming represents the steepest expansion trajectory as edge computing density improves.
End User:
Engagement depth and spending velocity separate recreational participants from vocationally committed users.
- Casual Gamers:Mobile-first session patterns and intermittent play frequencies dominate unit volume. Hyper-casual titles and match-3 mechanics monetize through interstitial advertising and optional microtransactions.
- Professional Players:Esports competitors and content creators demand frame-rate consistency and input latency minimization. Hardware sponsorships and tournament prize pools concentrate spending in South Korea, China, and Nordic markets.
- Educational Institutions:Serious games and simulation-based learning modules require curriculum alignment and administrative procurement cycles. Institutional volume remains constrained by budget approval timelines and technology integration requirements.
- Streaming Platforms:Content creators and broadcasters drive derivative demand for spectator-friendly titles. Twitch and YouTube Gaming algorithm preferences reshape development priorities toward watchability and viral moment design.
Casual gamers generate absolute volume leadership. Professional players are gaining share fastest as esports infrastructure matures and sponsorship pools deepen.
Platform:
Development cost tiers and addressable audience scale operate in inverse proportion across hardware categories.
- PC:Open hardware standards and modding ecosystem support sustain the highest per-user lifetime value. Steam Workshop integration and user-generated content extend title longevity without publisher content investment.
- Console:Fixed hardware specifications enable optimization efficiency and simultaneous release scheduling. Sony and Microsoft first-party exclusives concentrate premium pricing power through controlled distribution.
- Mobile:Touch interface constraints and session length limitations dominate design paradigms. Apple's App Store and Google Play commission structures compress developer margins while user acquisition costs escalate.
- VR:Headset penetration rates and motion sickness mitigation constrain addressable market scale. Enterprise training verticals in healthcare and industrial safety bypass consumer adoption bottlenecks through B2B contract structures.
Mobile platforms sustain volume dominance through microtransaction economies. VR systems are expanding most quickly from negligible base as hardware costs decline and enterprise applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA approval bottlenecks stretch release timelines while the United States sustains premium pricing power through subscription service maturation. Japan's semiconductor allocation priorities favor flagship console cycles over mid-tier hardware revisions. India's infrastructure expansion unlocks first-time gamer cohorts previously excluded by data cost barriers.
United States
Subscription service penetration normalizes recurring revenue models independent of unit sales volatility. The FTC monitors platform-holder commission structures for anticompetitive conduct. Seattle and Austin anchor development clusters where live service operational expertise concentrates among DevOps talent pools.
China
Mobile microtransaction maturation drives sustained per-user monetization through gacha mechanics and social distribution networks. NMPA content review quotas and cultural compliance requirements elevate localization budgets by 12-18 months. Shenzhen and Hangzhou development hubs pre-position simplified Chinese builds and censorship-compliant asset variants to minimize revision cycles.
Japan
Console development pipelines harden as semiconductor foundry capacity prioritizes flagship hardware SoC allocation. METI industrial policy supports domestic IP export through content localization subsidies. Tokyo and Osaka metropolitan areas sustain premium upfront pricing for narrative-heavy releases with 4-6 year development timelines.
India
Reliance Jio infrastructure expansion reduces data cost barriers for mobile-first session patterns. TRAI spectrum allocation decisions shape 5G rollout density for cloud streaming viability. Bangalore and Hyderabad development studios localize content in Hindi and regional languages to unlock underpenetrated first-time gamer cohorts.
South Korea
Professional player infrastructure and esports tournament prize pools concentrate hardware sponsorship demand. MFDS content rating guidelines govern age-gating and spending limit enforcement for mobile titles. Seoul anchors competitive gaming culture where frame-rate consistency and input latency minimization drive hardware upgrade cycles.
Video Game Software Market Competitive Environment
Japanese and American producers anchor premium console and PC tier development; Chinese specialists hold dominant positions in mobile free-to-play monetization architectures. The vendor base stratifies across three tiers: platform holders controlling distribution infrastructure, multinational publishers with annual franchise iteration capabilities, and mid-size studios leveraging cross-platform engine standardization. Competitive positioning depends on exclusive IP licensing, live service operational scale, and regulatory compliance pre-positioning in approval-constrained markets.
Within the platform holder tier, Sony Interactive Entertainment and Microsoft Gaming exemplify hardware-software integration strategies, while Tencent Interactive Entertainment anchors mobile monetization expertise through social distribution network leverage. Electronic Arts and Nintendo occupy positions defined by annual sports franchise iteration and exclusive first-party IP premium pricing respectively. These entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| NetEase Games |
| Electronic Arts |
| Sony Interactive Entertainment |
| Epic Games |
| Valve Corporation |
| Tencent Interactive Entertainment |
| Nintendo |
| Take-Two Interactive |
| Microsoft Gaming |
| Others |
Value Chain & Pricing Dynamics
Platform-holder commission bifurcation separates premium direct-to-consumer channels from mobile storefront compression, manifesting in divergent margin structures and supply chain investment priorities. Steam and Epic Games Store revenue-share negotiations anchor PC distribution economics while Apple App Store and Google Play extraction rates force mobile developers toward alternative payment infrastructure.
Pricing Analysis
Direct-to-consumer margin layers preserve publisher pricing power against platform-holder commission compression. Subscription services normalize recurring revenue models through Xbox Game Pass and PlayStation Plus minimum guarantees, while free-to-play monetization hinges on gacha mechanic depth and battle pass velocity in Southeast Asian markets. Cost compression in mobile user acquisition intensifies as iOS privacy frameworks degrade targeting efficiency. Casual mobile gamers exhibit highest price sensitivity; professional esports competitors demonstrate lowest sensitivity due to hardware sponsorship subsidization.
Supply Chain Analysis
Regional distribution center deployment patterns concentrate physical retail logistics in Japan and Eastern Europe where payment infrastructure constraints sustain disc-based fulfillment. Semiconductor foundry capacity draws from Taiwan, South Korea, and the United States for flagship console SoC production. Art production pipelines rest on Eastern European and Southeast Asian outsourcing clusters for asset generation. Single-source vulnerability in NVIDIA GPU allocation creates downstream hardware scarcity. Distribution runs through platform-native digital marketplaces with cloud streaming infrastructure bypassing retail channel dependency entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in video game software rests on generative AI compression of art production timelines and subscription service penetration normalizing predictable cash flows over unit sales volatility.
For Market Incumbents: To counter cloud streaming infrastructure commoditization, Sony Interactive Entertainment and Microsoft Gaming should deepen exclusive IP licensing moats and pre-position NMPA-compliant asset variants for Chinese market entry. Live service operational scale remains the priority lever for retention economics. For New Entrants and Emerging Players: Begin with India's underpenetrated mobile base where Reliance Jio data cost reduction unlocks first-time gamer cohorts in Hindi and regional language localization. Cloud streaming bypasses hardware dependency for GPU-scarce markets. Direct-to-consumer payment infrastructure circumvents mobile storefront commission extraction. For Investors and Strategic Acquirers: Consolidation pressure builds where live service operational complexity exceeds mid-size studio DevOps capabilities. Five-to-ten year viability favors publishers with annual franchise iteration calendars and established esports infrastructure. Watch NMPA approval queue velocity as inflection indicator for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unreal Engine 5 runtime deployments reduce porting overhead across PC, console, and mobile codebases. |
| Geographic Expansion | India's Jio fiber expansion enables cloud streaming viability for previously excluded GPU-scarce audiences. |
| Strategic Partnership | Healthcare simulation contracts bypass consumer VR hardware adoption constraints through B2B structures. |
| Acquisition of Specialist Firm | AI-assisted asset generation studios compress art production timelines for mid-size quality parity. |
| Product Launch | Subscription service library placement secures guaranteed minimums independent of unit sales volatility. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with game development executives, platform engineering leads, regulatory affairs specialists at multinational publishers, and esports tournament operators with secondary validation against SEC filings, NMPA approval databases, Steam hardware survey telemetry, and App Annie mobile revenue estimates. Bottom-up title-level revenue modeling and top-down platform-holder disclosure triangulation anchored market sizing.
Comparable historical periods anchored the projection horizon across the analysis window, with segmentation dimensions spanning platform type, monetization architecture, geographic regulatory cluster, and end-user engagement depth. CAGRs derived from installed base growth curves, ARPU trajectory modeling, and content approval velocity assumptions. Cloud streaming infrastructure density and semiconductor foundry capacity allocation served as industry-specific forecast inputs.
Caveats apply where NMPA approval queue extensions, semiconductor supply constraints, or platform-holder policy shifts could materially shift the outlook. Forecasts reflect documented assumption sets around subscription penetration rates and mobile microtransaction maturation curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
VR Gaming Controller Market
Gaming
RPG Games Market
Gaming
Mobile Shooter Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Puzzle Video Game Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Online Casino Market
Gaming
Game API Market
Gaming
Serious Games Market
Gaming
Playstation Network (PSN) Market
Gaming
Gaming Chair Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Advanced Digital Gaming Market
Gaming
Gaming Controller Market