
 Shooter Game Market | 2026-2036
Shooter Game Market Size, Share, and Industry Trends Forecast 2026-2036
Shooter Game Market Insights
Buyer concentration among esports organizations and streaming platform operators is restructuring procurement patterns for live-service shooter titles. Activision Blizzard leverages its captive tournament ecosystem to sustain multi-year engagement cycles across flagship franchises. Valve Corporation anchors competitive integrity through proprietary anti-cheat infrastructure and Steam distribution control. Krafton dominates mobile battle royale monetization in Asian markets with localized content pipelines.
A shooter game is an interactive software application built on real-time rendering engines with latency thresholds below 50 milliseconds, designed primarily for competitive or cooperative combat simulation against AI or human opponents. First-Person Shooter titles occupy the deepest margin pools through seasonal battle pass architectures and cosmetic microtransactions. Mobile platform deployment represents the fastest-expanding segment as 5G latency reduction enables cross-platform parity previously limited to PC and console ecosystems.
China's National Press and Publication Administration (NPPA) and South Korea's Game Rating and Administration Committee (GRAC) impose distinct content approval and playtime restriction frameworks that directly shape market access and youth-targeted design parameters. The Entertainment Software Rating Board (ESRB) in the United States and Pan European Game Information (PEGI) system govern age-gating mechanics that influence monetization feature visibility. Stakeholders must monitor regulatory divergence around loot box probability disclosure mandates and real-money transaction limits as these frameworks crystallize across major publishing territories.
Market Dynamics
Cloud streaming infrastructure is restructuring how shooter titles reach audiences without dedicated hardware, collapsing the traditional console-PC barrier and forcing publishers to architect latency-tolerant netcode for sub-50ms thresholds across heterogeneous devices.
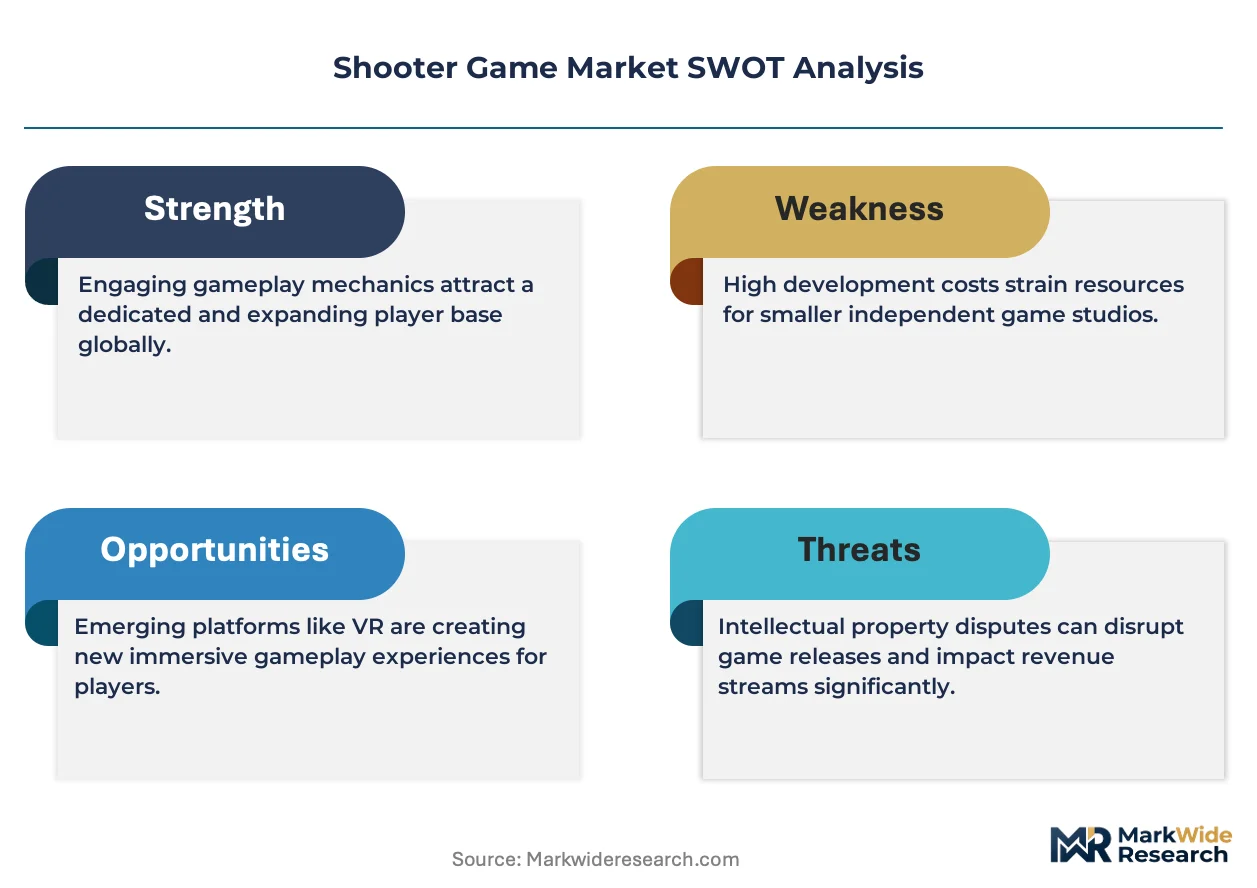
Growth Catalysts
- 5G latency reduction:South Korean carriers deploy millimeter-wave infrastructure enabling mobile battle royale parity with PC ecosystems, sustaining premium monetization at PC bang venues.
- Esports tournament expansion:Competitive viewership scaling creates captive buyer concentration among tournament organizers demanding multi-year live-service engagement architectures.
- GRAC content frameworks:South Korea's rating committee provides predictable approval pathways that reduce time-to-market for youth-targeted shooter variants with compliant playtime mechanics.
Market Restraints
- Input cost volatility:Semiconductor fabrication constraints elevate GPU and mobile SoC pricing, compressing hardware attach rates in price-sensitive emerging markets.
- Regulatory friction:China's NPPA approval backlog extends content launch timelines, forcing publishers to maintain parallel build versions for distinct territorial compliance.
- Technical limitation:Sub-20ms competitive integrity thresholds resist cloud streaming adoption for professional esports, preserving dedicated hardware dependency at the tournament tier.
Strategic Opportunities
- Underpenetrated geography:India's TRAI spectrum allocation for 5G gaming creates first-mover positioning for localized mobile battle royale content pipelines.
- Technology convergence:AI-driven procedural map generation merges with anti-cheat neural networks to compress live-service content production cycles.
- Distribution innovation:Platform-agnostic subscription bundles bypass traditional storefront gatekeeping, enabling direct publisher-audience relationships outside Steam and console marketplaces.
Industry Challenges
- Netcode engineering scarcity:Specialized talent for authoritative server architectures and rollback synchronization commands premium compensation, constraining mid-tier studio expansion.
- Compliance timeline compression:Loot box probability disclosure mandates across multiple rating jurisdictions require real-time backend infrastructure for dynamic storefront adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shooter Game Market |
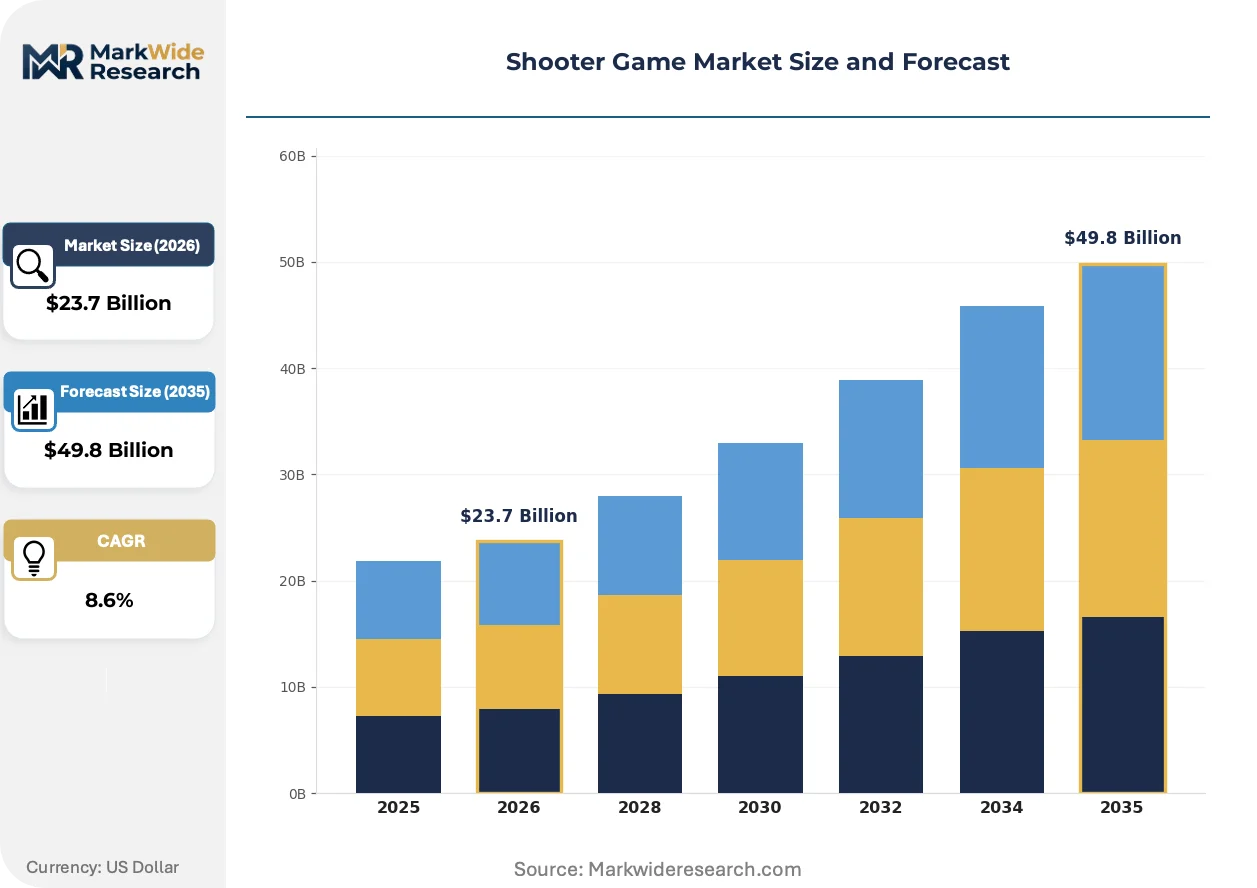
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: First-Person Shooter, Third-Person Shooter, Tactical Shooter, Battle Royale Platform: PC, Console, Mobile, Cloud Gaming Monetization Model: Premium, Free-to-Play, Subscription, In-Game Purchases Player Mode: Single Player, Multiplayer, Co-op, Online |
| Companies Covered | Activision Blizzard, Valve Corporation, Rockstar Games, Ubisoft, Epic Games, Nexon, Gameloft, Krafton, NetEase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shooter Game Market Trends and Innovations
Real-time rendering pipelines are undergoing fundamental restructuring as neural inference displaces traditional rasterization pathways, compressing the boundary between cloud and local computation for competitive latency requirements.
AI-driven matchmaking and behavioral moderation is automating player retention optimization at scale. Publishers deploy machine learning models to predict churn vectors and dynamically adjust engagement rewards. This automation is compressing the traditional data science function into embedded runtime systems that operate without human intervention.
The EU AI Act's risk classification framework imposes transparency obligations on algorithmic systems affecting player behavior. Publishers must document training data provenance and decision logic for matchmaking and monetization prompts. Titles with loot box mechanics face heightened scrutiny under the high-risk system category, forcing architectural separation between gameplay and commerce algorithms.
Consumption patterns among core shooter audiences rotate toward creator-driven discovery rather than platform curation. Streamer and esports personality endorsements displace traditional advertising as the primary acquisition channel. South Korea and Brazil exhibit the most pronounced shift, where platform-native influencers command larger aggregate reach than official publisher marketing.
Shooter Game Market Segmentation
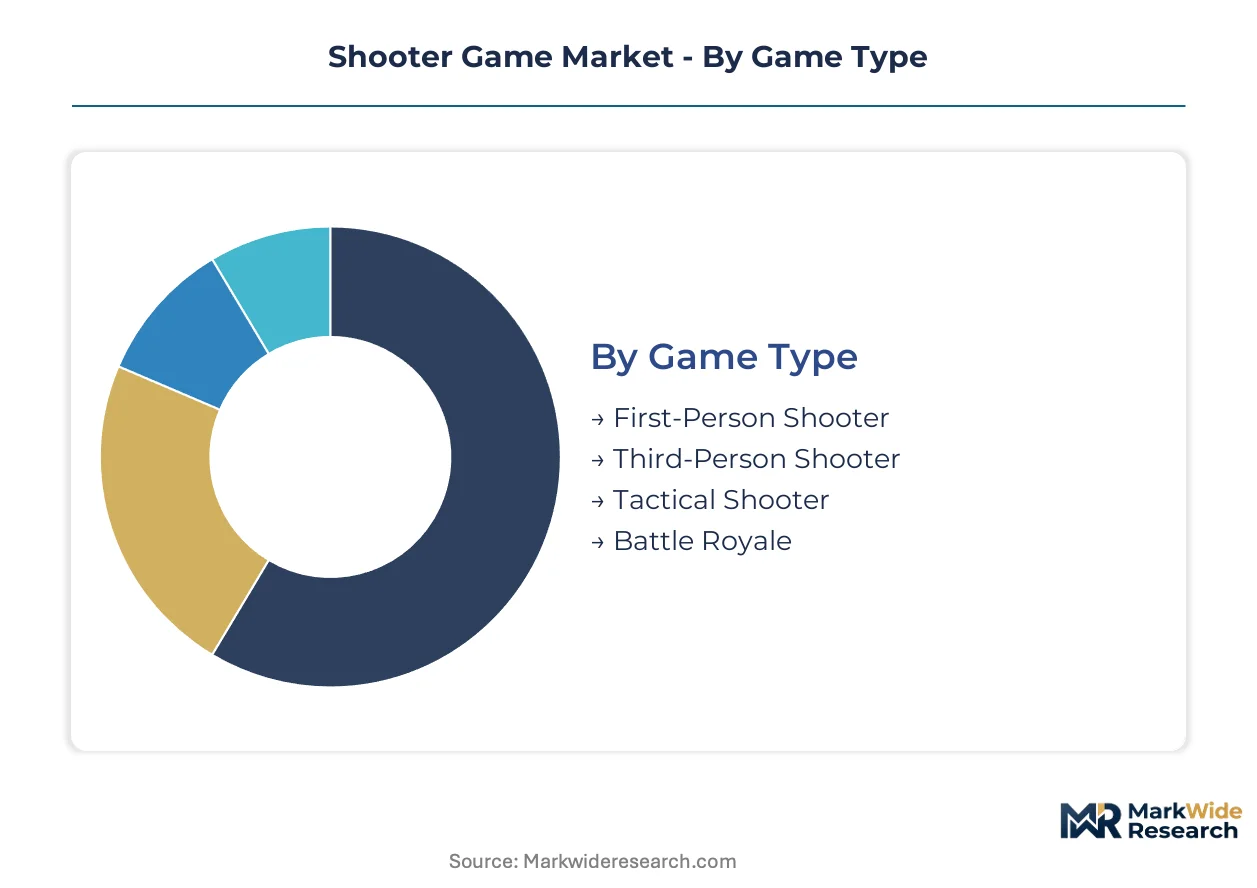
Shooter game publishers architect distinct technology stacks and monetization pathways for each segment, creating divergent margin profiles and engagement half-lives. Platform and monetization model selection determines netcode infrastructure requirements, anti-cheat deployment costs, and regional regulatory exposure.
Game Type:
Real-time rendering architectures differentiate competitive integrity thresholds across mechanical frameworks.
- First-Person Shooter:Camera-locked perspective demands sub-50ms input-to-display latency for competitive parity. South Korean PC bang venues sustain premium monetization through seasonal battle pass architectures and cosmetic microtransactions in flagship franchises.
- Battle Royale:Procedural map generation and 100-player server instances require authoritative netcode with dynamic zone compression. Mobile deployment in India and Brazil drives fastest expansion as 5G infrastructure enables cross-platform parity.
- Third-Person Shooter:Over-the-shoulder camera systems enable broader animation fidelity and cover-based mechanics.
- Tactical Shooter:Round-based elimination mechanics with permadeath constraints emphasize precise hit registration and server authority.
Mature deployment sits with First-Person Shooter. Newer deployment is concentrated in Battle Royale.
Platform:
Hardware dependency curves shape distribution economics and audience reach.
- Mobile:ARM-based SoC optimization and touch-control haptic systems dominate Asian volume. India's TRAI 5G spectrum allocation creates first-mover positioning for localized battle royale content pipelines with reduced latency thresholds.
- PC:Discrete GPU architectures and peripheral ecosystem openness sustain deepest margin pools through direct storefront relationships. South Korean PC bang culture anchors professional competitive infrastructure with premium hourly monetization.
- Console:Closed hardware cycles with standardized controller inputs enable optimized netcode but impose storefront gatekeeping fees.
- Cloud Gaming:Edge-compute streaming collapses hardware barriers while demanding latency-tolerant architectures for sub-50ms thresholds across heterogeneous devices.
Volume concentrates in Mobile. Margin depth remains with PC.
Monetization Model:
Revenue recognition timing and regulatory exposure vary sharply across payment architectures.
- Free-to-Play:Zero-friction acquisition with battle pass and cosmetic microtransaction layering. China's NPPA playtime restrictions and loot box probability disclosure mandates impose compliance infrastructure costs on real-money transaction systems.
- In-Game Purchases:À la carte virtual goods with dynamic storefront pricing. EU AI Act transparency obligations force architectural separation between gameplay algorithms and commerce prompts for high-risk system classification.
- Premium:Upfront box price with limited post-launch revenue capture.
- Subscription:Recurring access fees bundled across title libraries, reducing per-game visibility.
Revenue capture is shifting toward Free-to-Play. Regulatory scrutiny intensifies on In-Game Purchases.
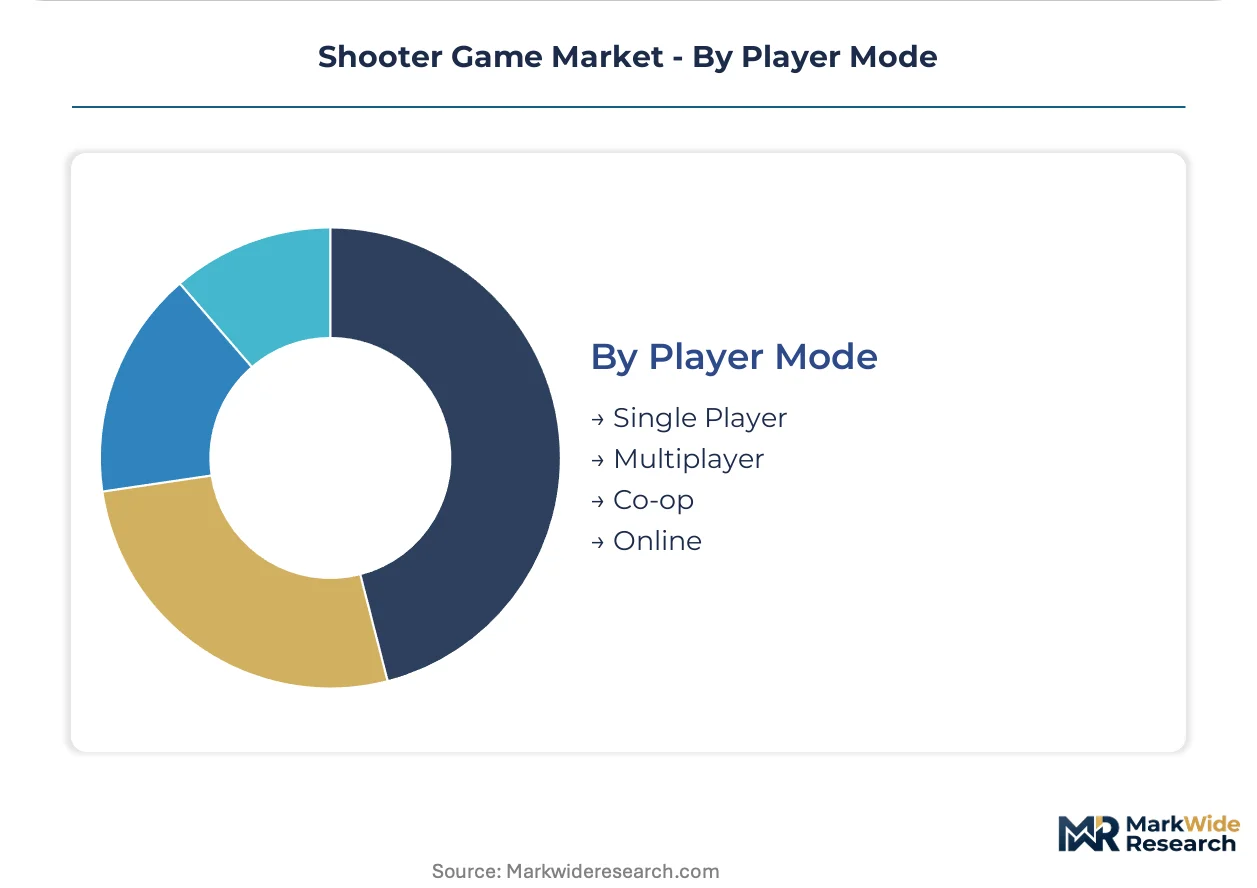
Player Mode:
Network topology requirements and server cost structures diverge by social configuration.
- Multiplayer:Authoritative server architectures with matchmaking pools scaling to millions of concurrent users. Esports tournament organizers demand multi-year live-service engagement architectures with ranked competitive integrity.
- Online:Persistent world states with cloud-hosted progression systems. AI-driven behavioral moderation automates retention optimization through churn prediction and dynamic reward adjustment.
- Single Player:Local computation with optional cloud-save synchronization.
- Co-op:Small-party PvE instances with reduced server authority requirements compared to competitive multiplayer.
Engagement duration peaks in Multiplayer. Infrastructure investment flows toward Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure investment anchors North American shooter game distribution, while Seoul's PC bang culture and Shenzhen's mobile development clusters concentrate competitive development gravity across the Pacific Rim.
United States
Esports tournament organizers in Los Angeles and Austin drive captive buyer concentration for live-service titles. The FTC monitors loot box mechanics under consumer protection frameworks, forcing probability disclosure adaptations. Seattle hosts cloud gaming infrastructure development for latency-tolerant netcode architectures.
South Korea
GRAC rating pathways accelerate youth-targeted shooter approvals while PC bang venues sustain premium hourly monetization. The Game Rating and Administration Committee mandates playtime restriction mechanics for compliant releases. Seoul anchors professional competitive infrastructure with millimeter-wave 5G deployment enabling mobile-PC parity.
China
NPPA approval backlogs compress content launch timelines for publishers maintaining parallel build versions. The National Press and Publication Administration enforces real-money transaction limits and youth playtime caps. Shenzhen clusters mobile battle royale development studios serving domestic distribution through state-approved platforms.
Japan
METI 5G spectrum allocation enables low-latency mobile shooter deployment across metropolitan corridors. The Ministry of Economy, Trade and Industry promotes esports professionalization through regulatory clarity on prize pools. Tokyo hosts publisher headquarters architecting seasonal content pipelines for Asian market penetration.
India
TRAI 5G spectrum allocation creates first-mover positioning for localized mobile battle royale content pipelines. The Telecom Regulatory Authority of India governs latency-critical infrastructure deployment for competitive gaming. Bangalore clusters game development studios targeting price-sensitive hardware ecosystems with ARM-optimized titles.
Shooter Game Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native distribution and AI-driven content generation. The vendor base stratifies across captive tournament ecosystems, proprietary storefront operators, and mobile-first publishers. Three archetypes dominate: platform-integrated incumbents with hardware-software control, live-service specialists with multi-year engagement architectures, and regional publishers with localized compliance expertise. Competitive moves concentrate on exclusive content licensing for subscription bundles and edge-compute partnerships for streaming latency reduction.
Within the platform-integrated tier, Valve Corporation and Epic Games exemplify divergent distribution philosophies—one anchoring open PC ecosystems through storefront control, the other pursuing direct-to-audience relationships outside traditional gatekeeping. Activision Blizzard occupies a position representing captive tournament ecosystem leverage, using competitive viewership scaling to sustain multi-year engagement cycles. Krafton exemplifies the mobile-first archetype with Asian market concentration, while NetEase represents regional compliance specialists navigating NPPA frameworks for territorial access.
| Leading Market Players |
|---|
| Activision Blizzard |
| Valve Corporation |
| Rockstar Games |
| Ubisoft |
| Epic Games |
| Nexon |
| Gameloft |
| Krafton |
| NetEase |
| Others |
Pricing and Supply Chain Analysis
Netcode engineering talent concentration in South Korea and Sweden creates labor-cost differentials that widen pricing-tier spreads between premium live-service titles and mid-tier releases. Publishers with captive server architecture teams in these clusters command sustained margin premiums through reduced outsourcing dependency.
Pricing Analysis
Volume concentrates in free-to-play mobile battle royale deployments across India and Brazil, while margin depth remains with PC-based first-person shooter franchises monetizing through seasonal battle passes. Price differentiation rests on anti-cheat infrastructure sophistication and tournament ecosystem integration. Pricing pressure stems from GPU and mobile SoC cost compression in price-sensitive emerging markets. Esports tournament organizers exhibit lowest price sensitivity; casual mobile audiences in Southeast Asia show highest.
Supply Chain Analysis
China's NPPA content approval mandates reshape sourcing for publishers maintaining parallel build versions with compliant playtime mechanics. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. Raw material dependencies span advanced node GPUs, high-bandwidth memory modules, and millimeter-wave 5G infrastructure components. Single-source vulnerability sits with TSMC's advanced node capacity for flagship console and PC silicon. Distribution runs through platform-native storefronts, cloud streaming services, and PC bang venue licensing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is supply-constrained by specialized netcode engineering scarcity, with authoritative server architecture talent commanding premium compensation that props pricing across live-service tiers.
For Market Incumbents: Anchor competitive positioning through proprietary anti-cheat neural network development and captive tournament ecosystem control. Valve Corporation's Steam distribution leverage exemplifies storefront gatekeeping as defensive moat. Invest in Seoul-based server engineering capacity to offset talent scarcity compression. Backward integration into edge-compute partnerships reduces cloud streaming latency vulnerability. For New Entrants and Emerging Players: Capture white-space in India's TRAI 5G-enabled mobile battle royale segment before infrastructure maturity saturates first-mover positioning. Brazil's creator-driven discovery channels offer penetrable acquisition economics outside traditional platform curation. Pursue direct-to-audience distribution through platform-agnostic subscription bundles bypassing Steam and console marketplace fees. For Investors and Strategic Acquirers: The window for entry favors regional compliance specialists with NPPA navigation expertise and localized content pipeline capabilities. Long-term viability hinges on AI-driven procedural content generation compressing live-service production cycles. Watch GRAC approval timeline acceleration as inflection signal for South Korean market access premium normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Anti-Cheat Infrastructure | Neural network-driven behavioral detection reduces tournament integrity risk and sustains premium monetization. |
| Edge-Compute Streaming Partnership | Millimeter-wave 5G deployment in Seoul and Tokyo enables sub-50ms latency parity across heterogeneous devices. |
| Localized Content Pipeline | NPPA-compliant build versions with youth playtime mechanics unlock China's state-approved platform distribution. |
| Creator-Driven Acquisition Channel | Streamer and esports personality endorsements displace traditional advertising in South Korea and Brazil. |
| AI Procedural Map Generation | Machine learning compresses live-service content production cycles for battle royale zone dynamics. |
Research Methodology
Document review covered publisher SEC filings, platform revenue disclosures, and esports tournament viewership data, complemented by interviews with live-service game directors, netcode engineering leads, esports tournament organizers, and cloud infrastructure architects. Secondary validation drew from Steam concurrent player statistics, GRAC approval databases, and 5G spectrum allocation filings. Bottom-up title-level monetization modeling triangulated with top-down regional market sizing.
Segmented outputs across game type, platform, monetization model, and player mode dimensions informed the analytical framework throughout the projection horizon. CAGRs derived from historical engagement half-life curves and live-service content pipeline velocity. Forecast inputs incorporated semiconductor fabrication capacity constraints, NPPA approval backlog duration estimates, and millimeter-wave infrastructure deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence around loot box probability disclosure mandates and real-money transaction limits. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Social Gaming Market
Gaming
Mobile Game Software Market
Gaming
Online Casino Market
Gaming
Gaming Simulation Market
Gaming
Serious Games Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Gaming Gadgets Market
Gaming
Playstation Network (PSN) Market
Gaming
Global Esports Market
Gaming
Gaming Accessories Market
Gaming
Console Games Market
Gaming
United Kingdom Online Gambling Market
Gaming
MMORPG Gaming Market
Gaming
Slot Machine Market
Gaming
Gaming Controller Market
Gaming
Europe Gaming Peripherals Market