
 Traditional Casual Games Market | 2026-2036
Traditional Casual Games Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional Casual Games Market Analytics
Mobile app store distribution is reshaping how traditional casual games reach audiences, with platform fees and discovery algorithms dictating publisher economics. Playrix leverages its puzzle portfolio to sustain organic user acquisition across European markets. King Digital Entertainment anchors the match-three segment through Candy Crush's decade-long brand equity. Electronic Arts competes by extending its EA Mobile label across card and board game adaptations.
Traditional casual games encompass puzzle, card, board, and word titles designed for short-session play with minimal learning curves, typically running on HTML5 or native mobile engines with file sizes under 500 MB to enable instant downloads. Their commercial purpose centers on maximizing lifetime value through repeated micro-engagement rather than narrative depth. The puzzle segment dominates revenue pools due to its aging player base and proven monetization mechanics. Mobile platform distribution represents the fastest-growing structural channel, while desktop web browser access matures as a retention-focused secondary touchpoint. Ad-supported monetization captures volume in emerging markets, though in-app purchase models yield superior margins in North America and East Asia.
The Federal Trade Commission scrutinizes dark pattern design in free-to-play interfaces, pressuring studios to clarify purchase flows. The EU AI Act and GDPR jointly constrain behavioral targeting and automated content recommendation systems, elevating compliance costs for user acquisition teams. China's National Press and Publication Administration enforces minor protection rules that cap daily playtime and restrict monetization from underage accounts. Stakeholders must monitor how platform gatekeepers adapt store policies to these divergent regulatory regimes.
Market Dynamics
Mobile platform gatekeepers have concentrated distribution power, with Apple and Google extracting 15-30% of in-app revenue while algorithmic discovery determines which titles achieve organic scale. This structural dependency forces publishers to optimize for platform-specific engagement metrics rather than standalone product quality.
Growth Catalysts
- GDPR-driven first-party data strategies:European publishers are rebuilding user acquisition around consented cohorts and contextual targeting, reducing reliance on deprecated third-party identifiers.
- HTML5 instant play technology:Browser-based game streaming eliminates app store friction, enabling publishers to bypass platform fees and deploy direct-to-consumer distribution channels.
- Japan's aging mobile gamer demographic:Sustained spending power among players over 45 sustains premium puzzle monetization with lower churn than younger cohorts.
Market Restraints
- Platform fee compression:Apple and Google's 30% standard cuts erode margins on in-app purchases, with alternative payment system litigation yielding limited relief.
- IDFA deprecation:Apple's App Tracking Transparency framework has degraded lookalike audience targeting precision, elevating customer acquisition costs for performance marketers.
- Regulatory fragmentation:China's minor protection rules, Europe's AI Act constraints, and US FTC dark pattern scrutiny create incompatible compliance requirements across major revenue markets.
Strategic Opportunities
- India's prepaid mobile economy:Ad-supported hyper-casual formats align with data-conscious users and UPI-enabled microtransactions for emerging middle-class segments.
- Cloud gaming infrastructure convergence:Integration of 5G edge computing with instant play HTML5 engines enables console-quality casual experiences without native installation.
- EU Digital Services Act transparency mandates:Algorithmic accountability requirements may level discovery playing fields for mid-tier publishers against incumbent platform favorites.
Industry Challenges
- Live operations talent scarcity:Competition for data scientists and economy designers capable of sustaining multi-year title lifecycles exceeds supply in key development clusters.
- Cross-platform identity resolution:Fragmented player profiles across mobile, web, and emerging channels complicate unified progression systems and monetization optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional Casual Games Market |
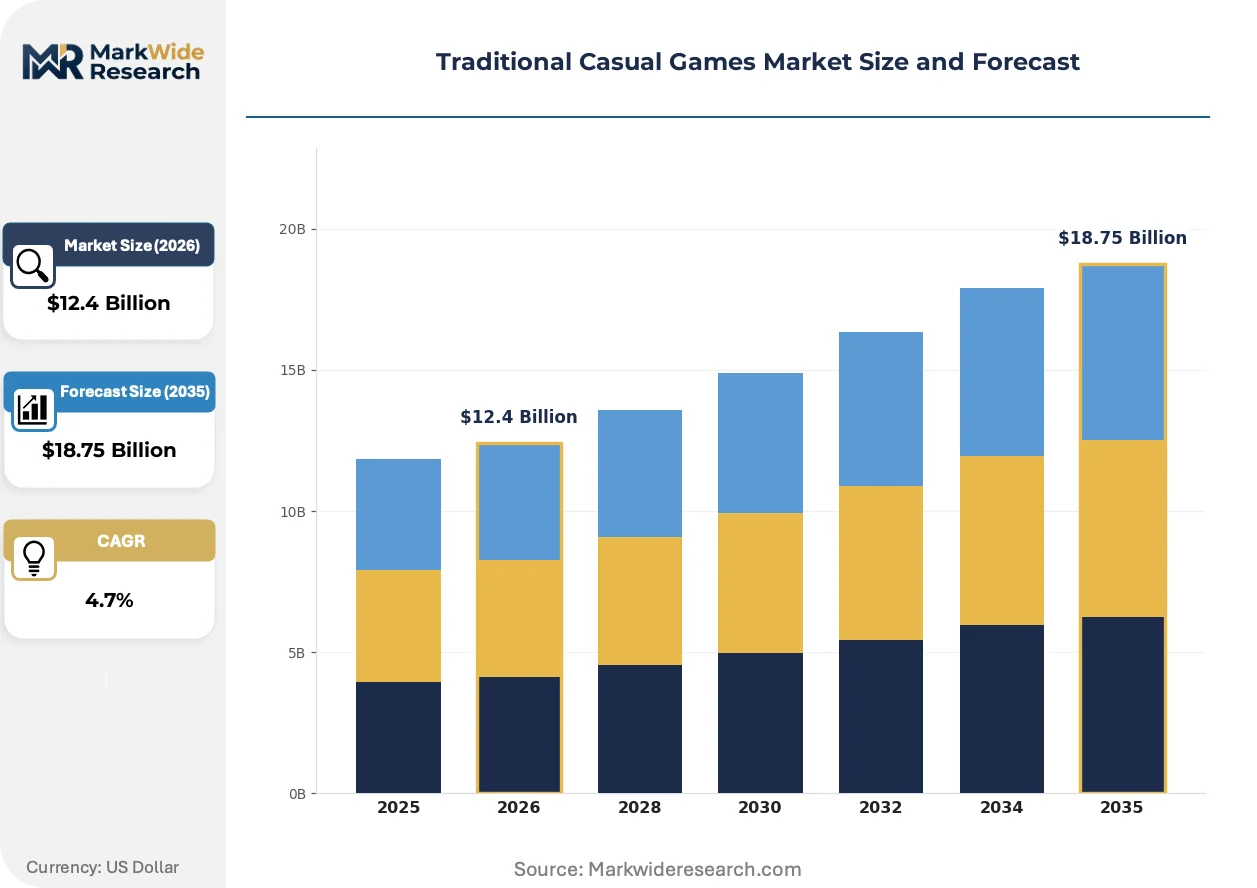
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Puzzle, Card, Board, Word User Demographic: Adults, Teens, Children, Seniors Platform: Mobile, Desktop, Console, Web Monetization Model: Free-to-Play, Subscription, In-App Purchase, Ad-Supported |
| Companies Covered | Zynga (Take-Two Interactive), Playrix, Electronic Arts (EA), Outfit7, Scopely, Activision Blizzard, King Digital Entertainment, Peak Games, Roblox Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional Casual Games Market Evolving Landscape
Generative AI tools are compressing content production timelines while regulatory pressure on behavioral design is forcing monetization model experimentation. Publishers are simultaneously pursuing efficiency gains and defensive compliance positioning.
AI-assisted art pipelines are digitizing asset creation workflows for match-three and hidden-object titles. Mid-size European studios deploy these tools to maintain weekly content drop cadences without proportional headcount expansion. This compression is eroding the historical cost advantage of outsourced art houses in Southeast Asia.
The EU AI Act's risk classification system for automated recommendation engines imposes documentation and human oversight obligations on personalized game feeds. Publishers serving European players must now maintain algorithmic audit trails and explainability mechanisms for content ranking decisions. The puzzle segment faces highest exposure given its reliance on difficulty-tuned level sequencing.
Subscription bundling is displacing standalone title purchases as primary access models. Apple Arcade and Google Play Pass aggregate casual catalogs for flat monthly fees, shifting publisher revenue from per-transaction to participation-based pools. This reconfiguration is most advanced in North American markets where subscription fatigue has yet to penetrate mobile entertainment.
Traditional Casual Games Market Segmentation
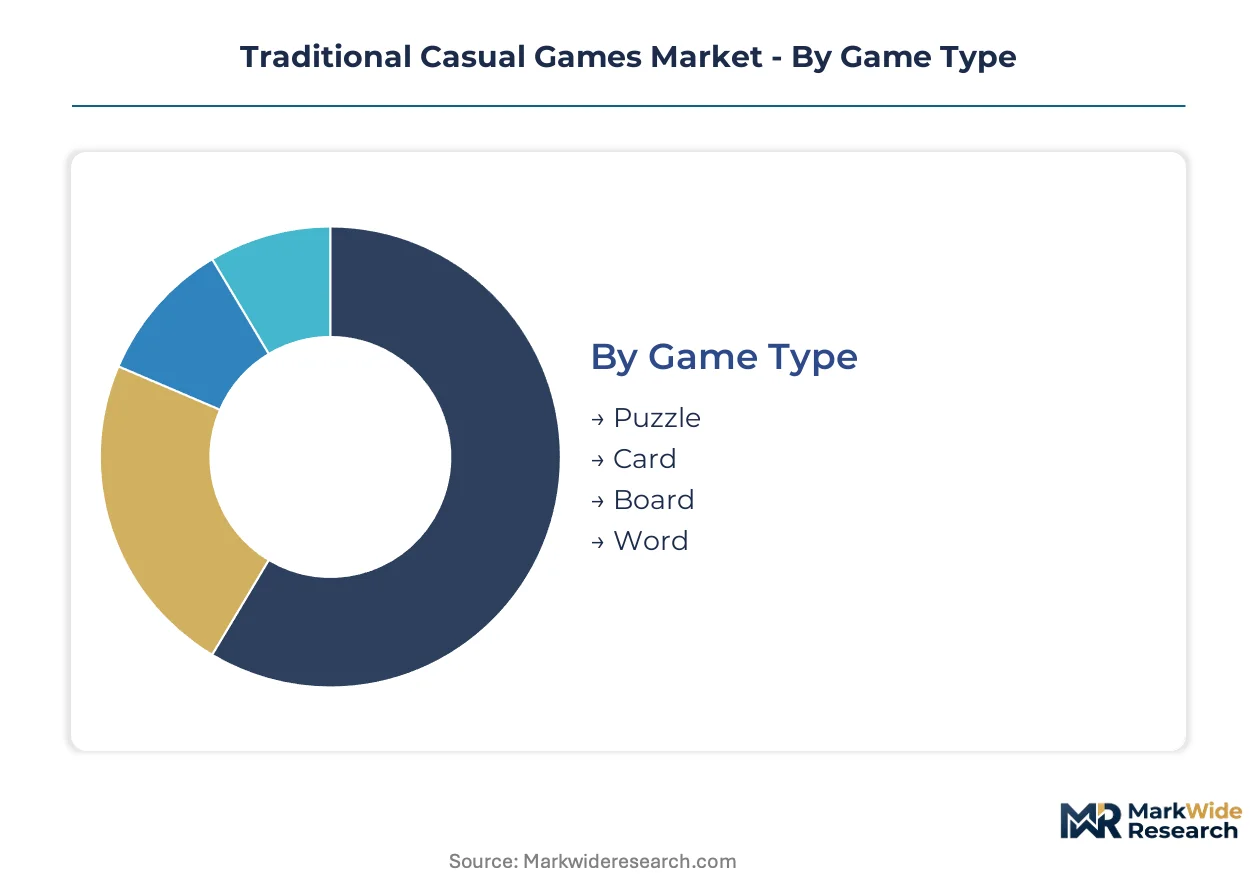
Segmentation in traditional casual games determines monetization architecture and distribution strategy. Publishers must align game mechanics, session length, and payment friction with distinct player expectations across demographic and platform boundaries.
Game Type:
Cost tier differentiation separates premium puzzle mechanics from lightweight card formats with minimal development overhead.
- Puzzle:Match-three and hidden-object mechanics dominate revenue pools through aging player bases with proven spending patterns. Japan's over-45 mobile demographic sustains premium monetization with lower churn than younger cohorts.
- Card:Solitaire and poker variants leverage existing rule familiarity to minimize tutorial friction. European publishers deploy these titles for GDPR-compliant contextual targeting without behavioral data dependencies.
- Board:Digital adaptations of classics like chess and backgammon emphasize asynchronous multiplayer retention.
- Word:Crossword and anagram formats attract educated demographics with higher disposable income concentration.
Puzzle holds installed capacity. Card is rotating up the share rankings.
User Demographic:
Application context varies sharply between commuter adults seeking micro-sessions and retired seniors pursuing extended engagement.
- Adults:Commuter segments drive mobile platform adoption through subway and bus-based session patterns. China's National Press and Publication Administration minor protection rules indirectly benefit adult-targeted titles by restricting youth monetization.
- Seniors:Players over 55 exhibit highest lifetime value in puzzle categories due to extended session tolerance and reduced price sensitivity. Japan's aging mobile gamer base sustains premium monetization with lower churn characteristics.
- Teens:Social mechanics and competitive leaderboards dominate acquisition strategies for this cohort.
- Children:COPPA and GDPR-K constraints limit data collection, forcing reliance on parental gatekeeping and subscription bundling.
Adults command current spending volume. Seniors are climbing the fastest as a revenue contributor.
Platform:
Volume distribution concentrates on mobile, yet margin profiles diverge significantly across installation and browser-based access modes.
- Mobile:Native iOS and Android applications capture dominant revenue share through app store distribution. Apple's App Tracking Transparency framework has degraded lookalike audience targeting precision, elevating customer acquisition costs for performance marketers.
- Web:HTML5 instant play technology eliminates app store friction and platform fees. European publishers leverage browser distribution to bypass Apple's 30% standard cuts and deploy direct-to-consumer channels.
- Desktop:Steam and direct download retain niche audiences for premium board game adaptations.
- Console:Nintendo Switch and PlayStation casual catalogs serve family co-play occasions with higher price points.
Mobile holds installed capacity. Web is gaining share fastest through HTML5 infrastructure expansion.
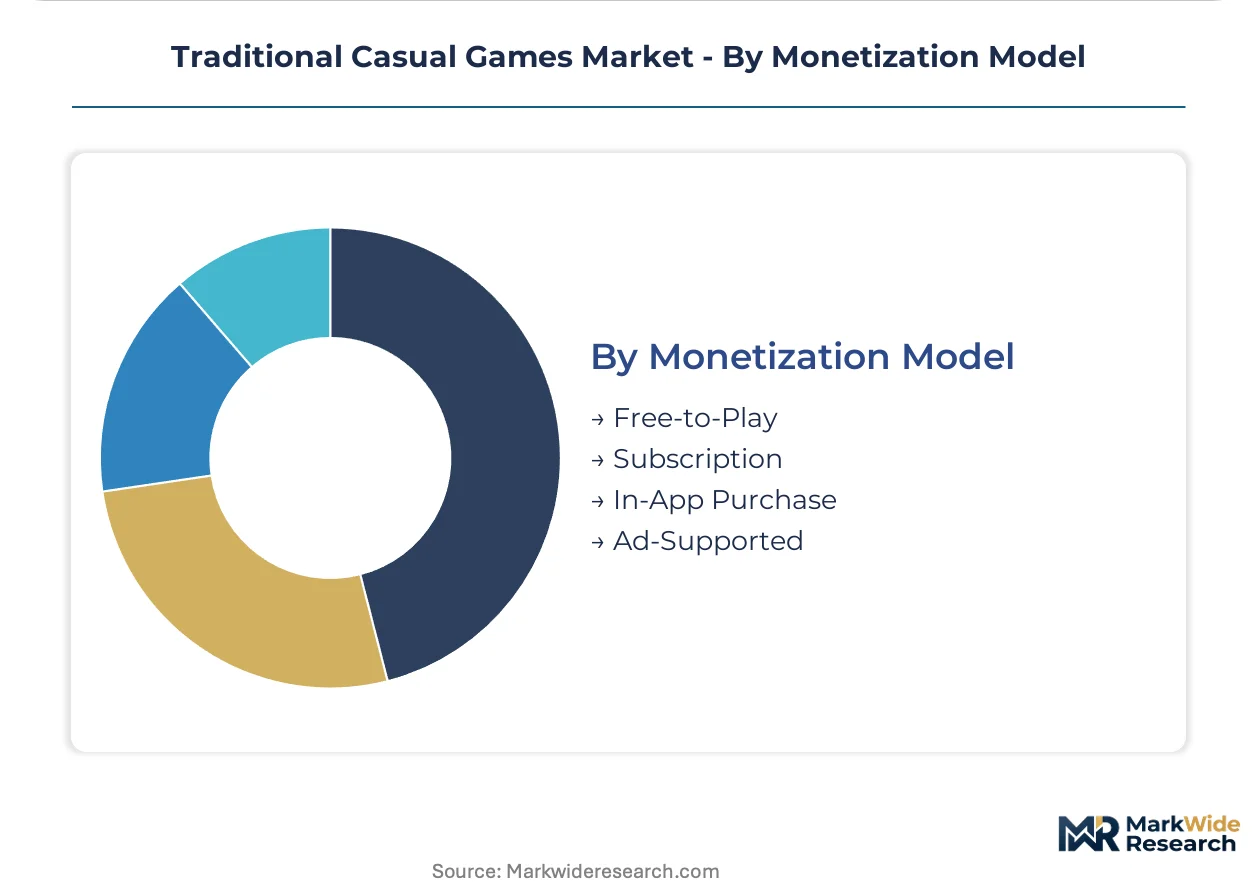
Monetization Model:
Customer type and payment psychology dictate whether publishers optimize for whale extraction or volume-based advertising yield.
- In-App Purchase:Gacha and power-up mechanics maximize lifetime value through repeated micro-engagement. The FTC's dark pattern scrutiny pressures studios to clarify purchase flows and eliminate ambiguous subscription renewals.
- Ad-Supported:Rewarded video and interstitial formats align with India's prepaid mobile economy and data-conscious users. UPI-enabled microtransactions bridge ad-supported and purchase models for emerging middle-class segments.
- Free-to-Play:Hybrid models combine limited ad exposure with optional purchase gates.
- Subscription:Apple Arcade and Google Play Pass aggregate catalogs for flat monthly fees, shifting revenue from per-transaction to participation-based pools.
In-App Purchase holds installed capacity. Ad-Supported is rotating up the share rankings in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's aging mobile gamer base while India's prepaid mobile economy compresses average revenue per user. European publishers navigate GDPR-compliant user acquisition as Chinese studios adapt to minor protection rule caps on youth monetization.
United States
Commuter adults in New York and San Francisco drive mobile platform adoption through subway-based micro-sessions. The FTC scrutinizes dark pattern design in free-to-play interfaces, pressuring studios to clarify purchase flows. Los Angeles hosts King Digital Entertainment's live operations teams sustaining Candy Crush's decade-long brand equity.
China
Adult-targeted titles benefit indirectly from the National Press and Publication Administration's minor protection rules that restrict youth monetization. Shanghai's mobile studios pivot toward consented cohort strategies as behavioral targeting degrades under regulatory pressure. Beijing's tech corridor concentrates HTML5 instant play development for browser-based distribution.
Japan
Players over 45 sustain premium puzzle monetization with lower churn characteristics than younger cohorts. METI guidelines on consumer protection shape in-app purchase disclosure requirements. Tokyo anchors the region's highest lifetime value player base, with Osaka studios specializing in match-three retention mechanics.
Germany
GDPR-driven first-party data strategies rebuild user acquisition around contextual targeting without third-party identifiers. The EU AI Act imposes documentation obligations on personalized game feeds and algorithmic recommendation engines. Berlin's mid-size studios deploy generative AI tools to maintain weekly content cadences.
India
UPI-enabled microtransactions bridge ad-supported and purchase models for emerging middle-class segments in Mumbai and Bangalore. TRAI's data pricing regulations influence prepaid mobile economy dynamics. Hyderabad's development clusters specialize in rewarded video integration for hyper-casual formats.
Traditional Casual Games Market Competitive Landscape
Portfolio consolidators and single-franchise specialists split the market into divergent risk-return profiles. King Digital Entertainment anchors the match-three segment through sustained live operations investment. Electronic Arts extends its EA Mobile label across card and board game adaptations. Competitive moves center on subscription bundling negotiations with platform gatekeepers and HTML5 infrastructure development for direct-to-consumer distribution.
Within the puzzle-specialist tier, Playrix leverages its portfolio for organic user acquisition across European markets, while Peak Games occupies a position exemplifying regional market dominance through culturally localized mechanics. Zynga, operating under Take-Two Interactive's ownership structure, represents the scale-driven archetype pursuing multi-genre portfolio breadth. Scopely anchors the licensed IP adaptation segment, demonstrating how external entertainment properties translate into casual game retention frameworks.
| Leading Market Players |
|---|
| Zynga (Take-Two Interactive) |
| Playrix |
| Electronic Arts (EA) |
| Outfit7 |
| Scopely |
| Activision Blizzard |
| King Digital Entertainment |
| Peak Games |
| Roblox Corporation |
| Others |
Value Network & Pricing Analysis
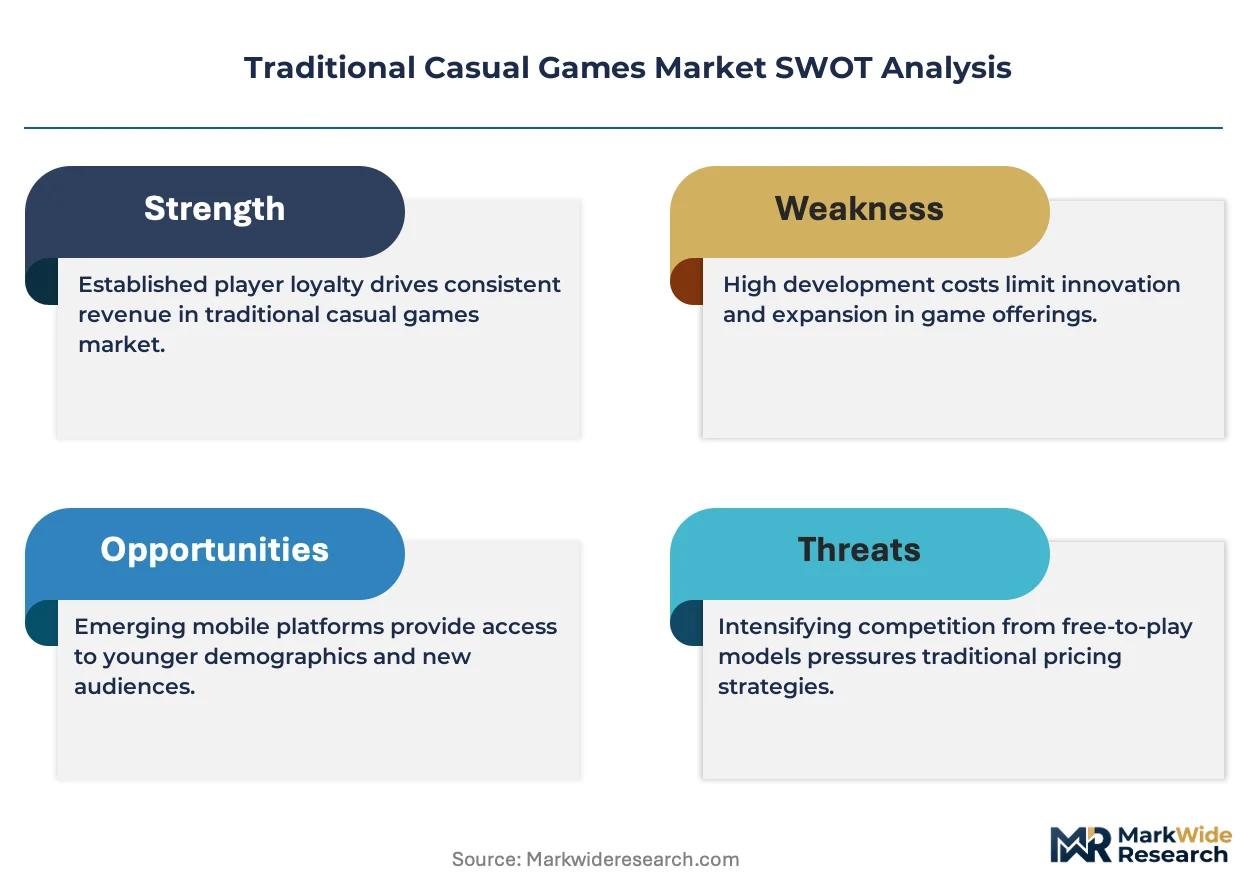
Platform fee compression risk determines both pricing tier spreads and supply chain shape in traditional casual games, as Apple's 30% standard cuts force publishers to segment monetization architectures while restructuring content delivery around direct-to-consumer channels that bypass gatekeeper economics entirely.
Pricing Analysis
Configured-to-order pricing versus standard pricing separates premium puzzle mechanics with personalized difficulty tuning from ad-supported hyper-casual formats with minimal development overhead. Subscription bundling through Apple Arcade and Google Play Pass now dominates standard access, while customized live operations packages command premium participation fees from high-engagement cohorts. Cost compression in the ad-supported tier intensifies because IDFA deprecation degraded targeting precision and elevated customer acquisition expenses. Emerging market players exhibit highest price sensitivity due to prepaid mobile economy constraints, whereas Japan's aging mobile gamer base shows least sensitivity with sustained premium spending tolerance.
Supply Chain Analysis
Extended payment terms from platform gatekeepers and supply-chain finance facilities anchor working capital management for mid-size European studios navigating GDPR compliance costs. Development talent concentrates in Germany, Japan, and India's Hyderabad cluster, while art production draws from Southeast Asian outsourcing houses facing generative AI displacement. Unity and Unreal engine licensing fees, cloud infrastructure subscriptions, and user acquisition ad spend constitute the primary input dependencies. Single-source vulnerability sits with Apple's App Store and Google's Play Store duopoly controlling distribution chokepoints. Distribution runs through mobile native applications as the dominant downstream structure, with HTML5 browser channels emerging as direct alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traditional casual games face acute substitution pressure from cloud gaming infrastructure and AI-generated interactive entertainment that threaten to displace short-session puzzle mechanics with more immersive alternatives.
For Market Incumbents: Build data moats through first-party cohort analytics that survive IDFA deprecation and GDPR constraints. Consolidate live operations talent in Berlin and Tokyo development clusters to sustain multi-year title lifecycles against hyper-casual churn. Deepen backward integration into proprietary HTML5 streaming engines that reduce platform fee exposure and enable direct-to-consumer distribution channels outside Apple and Google's extraction layers. For New Entrants and Emerging Players: India's UPI-enabled microtransaction segment represents the most penetrable entry point for ad-supported formats bridging to purchase models. Browser-based instant play distribution in European markets bypasses app store friction and 30% revenue cuts that compress incumbent margins. Partner with regional telecom operators for zero-rated data bundles that reduce user acquisition friction in prepaid mobile economies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors portfolio consolidators with proven live operations infrastructure over single-title specialists. Long-term viability hinges on multi-genre breadth and cross-platform identity resolution capabilities that unify player progression systems. Watch HTML5 infrastructure investment velocity as the inflection indicator signaling which publishers escape platform gatekeeper dependency.| Strategic Initiative | Industry Significance |
|---|---|
| HTML5 Infrastructure Development | Browser-based distribution bypasses Apple's 30% platform fees and enables direct monetization. |
| First-Party Data Platform Investment | GDPR-compliant cohort analytics reduces reliance on deprecated third-party identifiers for targeting. |
| Live Operations Talent Acquisition | Berlin and Tokyo clusters concentrate data scientists capable of sustaining multi-year title lifecycles. |
| Subscription Bundling Negotiation | Apple Arcade and Google Play Pass participation shifts revenue from transaction to recurring pools. |
| Generative AI Content Pipeline | Mid-size European studios deploy automated asset creation to maintain weekly content drop cadences. |
Research Methodology
Initial hypotheses were tested against primary input from game studio executives, user acquisition specialists, live operations directors, and platform partnership managers and refined through secondary validation against App Annie mobile revenue data, Sensor Tower download metrics, SEC 10-K filings from Take-Two Interactive and Electronic Arts, and EU regulatory documentation on GDPR and AI Act implementation. Bottom-up title-level revenue modeling triangulated with top-down market sizing from platform gatekeeper disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning game type, user demographic, platform access mode, and monetization model. CAGRs were derived from installed base growth curves and spending intensity trends rather than simple extrapolation. Cloud gaming infrastructure deployment schedules and 5G edge computing rollout timelines served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in discretionary entertainment spending and mobile data pricing would shift the trajectory for ad-supported and premium tiers respectively. Forecasts reflect documented assumptions on platform fee structures and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Hardware Market
Gaming
Gaming Controller Market
Gaming
Game Engine Management Market
Gaming
Board Games Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Latin America Gaming Headsets Market
Gaming
Puzzle Video Game Market
Gaming
Europe Serious Gaming Market
Gaming
Gaming Software Market
Gaming
Gaming Console Market
Gaming
Lottery Market
Gaming
Global Esports Market
Gaming
Europe Gaming Peripherals Market
Gaming
Global Casino and Gaming Market
Gaming
VR Gaming Accessories Market
Gaming
Middle East and Africa Gaming Headsets Market