
 Global Water Based Acrylates Copolymer Rheology Modifiers Market | 2026-2036
Global Water Based Acrylates Copolymer Rheology Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Based Acrylates Copolymer Rheology Modifiers Market Foresight
Modular additive packages is expanding as a preferred procurement format among mid-sized paint manufacturers seeking simplified formulation workflows. BASF leverages its integrated acrylic acid chain to supply consistent monomer feedstock for captive rheology modifier production. Dow Chemical anchors its position through broad emulsion polymerization expertise that extends into adjacent dispersant technologies. Lubrizol differentiates via specialized associative thickener architectures optimized for high-shear industrial coatings.
Water based acrylates copolymer rheology modifiers are alkali-swellable or hydrophobically modified acrylic polymers that thicken aqueous systems through chain entanglement or associative network formation, typically achieving target viscosities at solids loadings below five percent. These additives primarily enable application properties such as sag resistance, spatter control, and storage stability in packaged goods. Associative thickeners command premium positioning in architectural coatings due to superior flow and leveling balance, while non-associative grades sustain volume leadership in cost-sensitive detergent applications. The associative-nonassociative hybrid category is gaining traction among adhesive producers seeking to bridge performance gaps without dual-inventory complexity.
EPA regulations on architectural coating volatile organic compound limits reinforce water-based formulation mandates across US manufacturing. ECHA's REACH framework restricts specific monomer chemistries, compelling reformulation investments among European additive suppliers. China's MEE enforces progressively tighter VOC ceilings on industrial coatings produced in the Yangtze River Delta and Pearl River Delta clusters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant product registration costs.
Market Dynamics
Architectural coatings manufacturers are consolidating additive procurement around associative thickener packages that simplify formulation workflows while meeting tightening VOC mandates across multiple jurisdictions.
Growth Catalysts
- China's GB Standards:Progressive VOC ceilings on industrial coatings produced in the Yangtze River Delta and Pearl River Delta clusters are accelerating water-based system adoption over solvent alternatives.
- Associative Thickener Technology:Hydrophobically modified acrylic polymers deliver superior sag resistance and spatter control in high-build architectural coatings, commanding premium positioning among Asia-Pacific paint manufacturers.
- Domestic Production Scaling:China's coating production capacity expansion is concentrating demand for rheology modifiers within domestic supply chains, reducing import dependency.
Market Restraints
- Acrylic Acid Feedstock Volatility:Monomer supply fluctuations tied to propylene derivatives create margin pressure for additive producers lacking captive feedstock integration.
- REACH Compliance Burden:ECHA's framework restricts specific monomer chemistries, compelling European suppliers to absorb reformulation costs and redundant product registration expenses.
- Non-Associative Grade Commoditization:Cost-sensitive detergent applications sustain volume leadership for legacy alkali-swellable polymers, compressing pricing power in bulk segments.
Strategic Opportunities
- Hybrid Thickener Architectures:Associative-nonassociative hybrids bridge performance gaps for adhesive producers seeking to eliminate dual-inventory complexity without sacrificing application properties.
- Modular Additive Packages:Simplified formulation workflows are expanding as a preferred procurement format among mid-sized paint manufacturers, creating white space for integrated solution providers.
- EPA Architectural Coating Mandates:Federal VOC limits reinforce water-based formulation requirements across US manufacturing, opening substitution windows for compliant rheology systems.
Industry Challenges
- Regulatory Divergence Monitoring:Stakeholders must track jurisdictional differences between EPA, ECHA, and MEE frameworks to avoid stranded inventory and redundant compliance investments.
- High-Shear Formulation Expertise:Industrial coatings optimized for extreme shear conditions require specialized associative thickener architectures, creating talent scarcity in polymer design functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Based Acrylates Copolymer Rheology Modifiers Market |
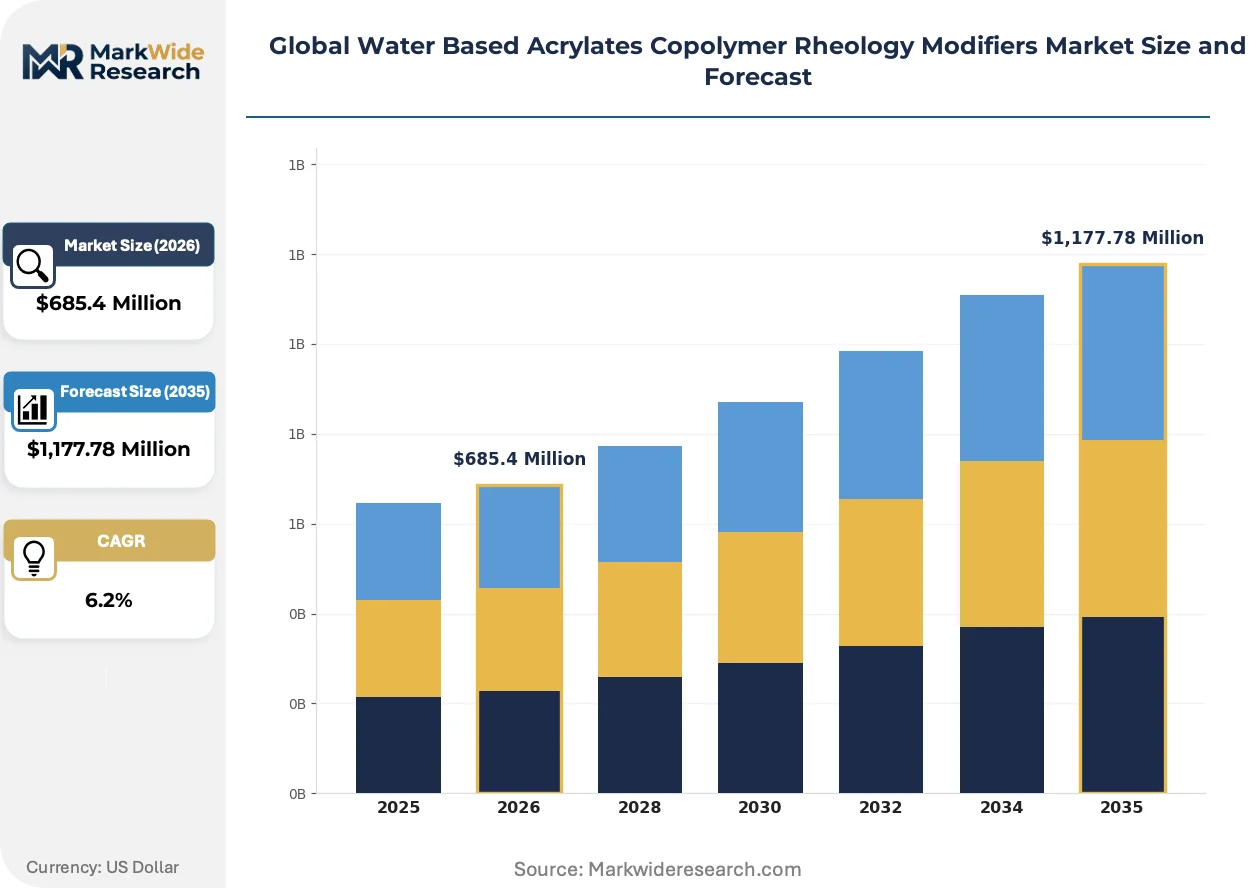
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Associative, Associative, Associative-Nonassociative Hybrid, Carbomer, Cellulose Derivative Application: Paint & Coatings, Adhesives & Sealants, Personal Care, Detergents, Textile Finishing End User: Paint Manufacturers, Adhesive Producers, Cosmetic Manufacturers, Detergent Suppliers, Fabric Treatment Firms Form: Liquid, Emulsion, Dispersion, Powder, Gel |
| Companies Covered | Arkema, BASF, Dow Chemical, Lubrizol, AkzoNobel, BYK Additives & Instruments, Euclid Chemicals, Ashland, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Based Acrylates Copolymer Rheology Modifiers Market Shifts & Advancements
Formulation chemistry is pivoting toward hybrid architectures that reconcile conflicting performance demands while additive procurement consolidates around integrated packages that reduce technical complexity.
Associative thickener technology is consolidating its position in architectural coatings through hydrophobically modified acrylic polymers that thicken via network formation rather than chain entanglement. Premium paint manufacturers in China and Southeast Asia are accelerating adoption for high-build applications demanding precise flow and leveling balance. This consolidation is compressing demand for standalone non-associative grades in decorative segments while elevating technical barriers for commodity suppliers.
REACH restrictions on specific monomer chemistries are compelling European additive suppliers to reformulate product lines and absorb redundant registration costs. The industrial consequence extends beyond compliance investments into stranded inventory risk for legacy formulations. Architectural coatings segments in Germany and France are responding fastest, with manufacturers pre-qualifying alternative thickeners ahead of phased substance restrictions.
Mid-sized paint manufacturers are unbundling traditional technical service relationships in favor of modular additive packages that embed formulation guidance. Distributor channels in North America and Western Europe are being disrupted by direct procurement platforms offering standardized thickener bundles with embedded compatibility data. This behavioral shift is most visible among regional architectural coatings producers seeking to compress R&D cycle times without expanding internal polymer expertise.
Global Water Based Acrylates Copolymer Rheology Modifiers Market Segmentation
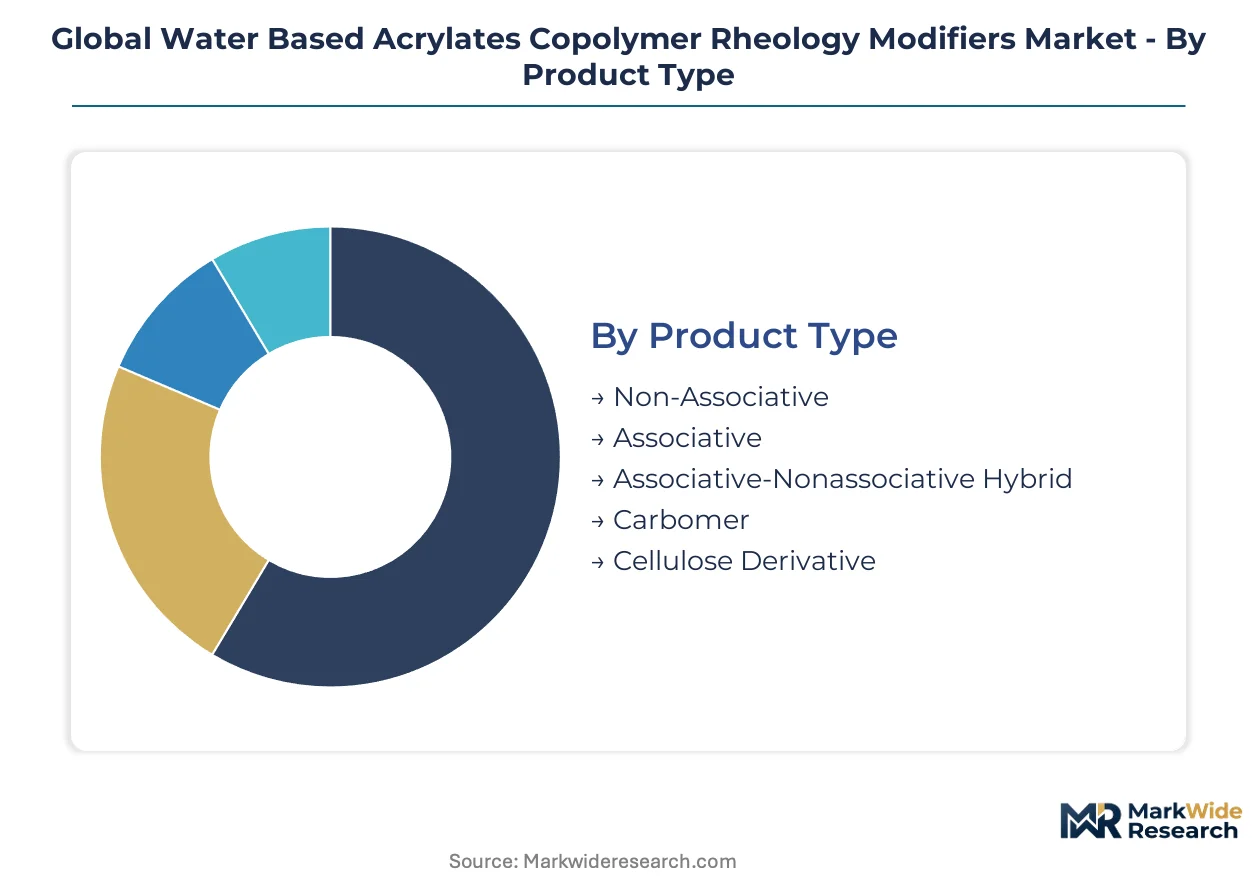
Segmentation in water based acrylates copolymer rheology modifiers reveals how formulation chemistry and procurement complexity fragment demand across divergent buyer workflows. Technical specifications for associative thickeners in high-build architectural coatings differ fundamentally from the cost-optimized requirements of bulk detergent applications.
Product Type:
Purchasing decisions pivot on viscosity build mechanism and formulation compatibility with existing aqueous systems.
- Non-Associative:Alkali-swellable acrylic polymers thicken through chain entanglement in neutralized aqueous media. Paint manufacturers in China deploy these grades in cost-sensitive interior emulsions where sag resistance requirements remain moderate. ECHA REACH restrictions on specific monomer chemistries are compelling European suppliers to reformulate legacy product lines.
- Associative:Hydrophobically modified acrylic polymers achieve viscosity through hydrophobic group association into micellar networks. Demand concentrates among Asia-Pacific architectural coatings producers seeking superior flow and leveling balance in high-build exterior systems. China's MEE VOC ceilings on Yangtze River Delta production clusters accelerate substitution away from solvent-borne alternatives.
- Associative-Nonassociative Hybrid:Dual-mechanism architectures bridge performance gaps for adhesive producers seeking to eliminate dual-inventory complexity.
- Carbomer:Crosslinked polyacrylic acid polymers deliver high clarity and ionic tolerance for personal care emulsions.
- Cellulose Derivative:Non-acrylic alternatives sustain niche positioning in legacy textile finishing applications with established compatibility protocols.
Volume sits with Non-Associative grades; growth tilts toward Associative technology.
Application:
End-use performance requirements dictate thickener selection more than raw material cost in premium segments.
- Paint & Coatings:Architectural formulations demand precise balance between sag resistance at rest and flow under shear. Manufacturers across China's Pearl River Delta cluster are consolidating procurement around associative thickener packages that simplify VOC-compliant workflows. EPA architectural coating mandates reinforce water-based formulation requirements across US manufacturing.
- Adhesives & Sealants:Pressure-sensitive and structural adhesive applications require tunable rheology across broad shear rate ranges. Hybrid thickener architectures are gaining traction among mid-sized producers in Germany and France seeking to bridge performance gaps without expanding technical service relationships. ECHA's phased substance restrictions are accelerating pre-qualification of alternative thickeners.
- Personal Care:Carbomer-based systems dominate sensory and stability requirements for skin care emulsions.
- Detergents:Cost-sensitive liquid laundry and dish formulations sustain volume demand for non-associative alkali-swellable polymers.
- Textile Finishing:Legacy cellulose derivative compatibility maintains position in fabric softener and finishing baths.
Paint & Coatings commands revenue concentration; Adhesives & Sealants exhibits the steepest expansion trajectory.
End User:
Scale and technical capability determine whether buyers source standalone thickeners or integrated additive packages.
- Paint Manufacturers:Large architectural coatings producers in China and Southeast Asia are accelerating adoption of associative thickeners for high-build exterior systems. Mid-sized regional producers in North America and Western Europe are unbundling traditional technical service relationships in favor of modular additive packages with embedded formulation guidance.
- Adhesive Producers:Industrial sealant formulators require specialized associative thickener architectures optimized for extreme shear conditions.
- Cosmetic Manufacturers:Premium skin care brands in South Korea and Japan specify carbomer grades for clarity and sensory performance.
- Detergent Suppliers:Bulk liquid laundry producers in India and Brazil prioritize non-associative grades for cost-optimized viscosity build.
- Fabric Treatment Firms:Textile finishing houses in Turkey and Bangladesh maintain cellulose derivative specifications for established process compatibility.
Paint Manufacturers anchor procurement volume; Adhesive Producers are gaining share fastest.
Form:
Supply chain logistics and handling infrastructure shape format preferences across geographic markets.
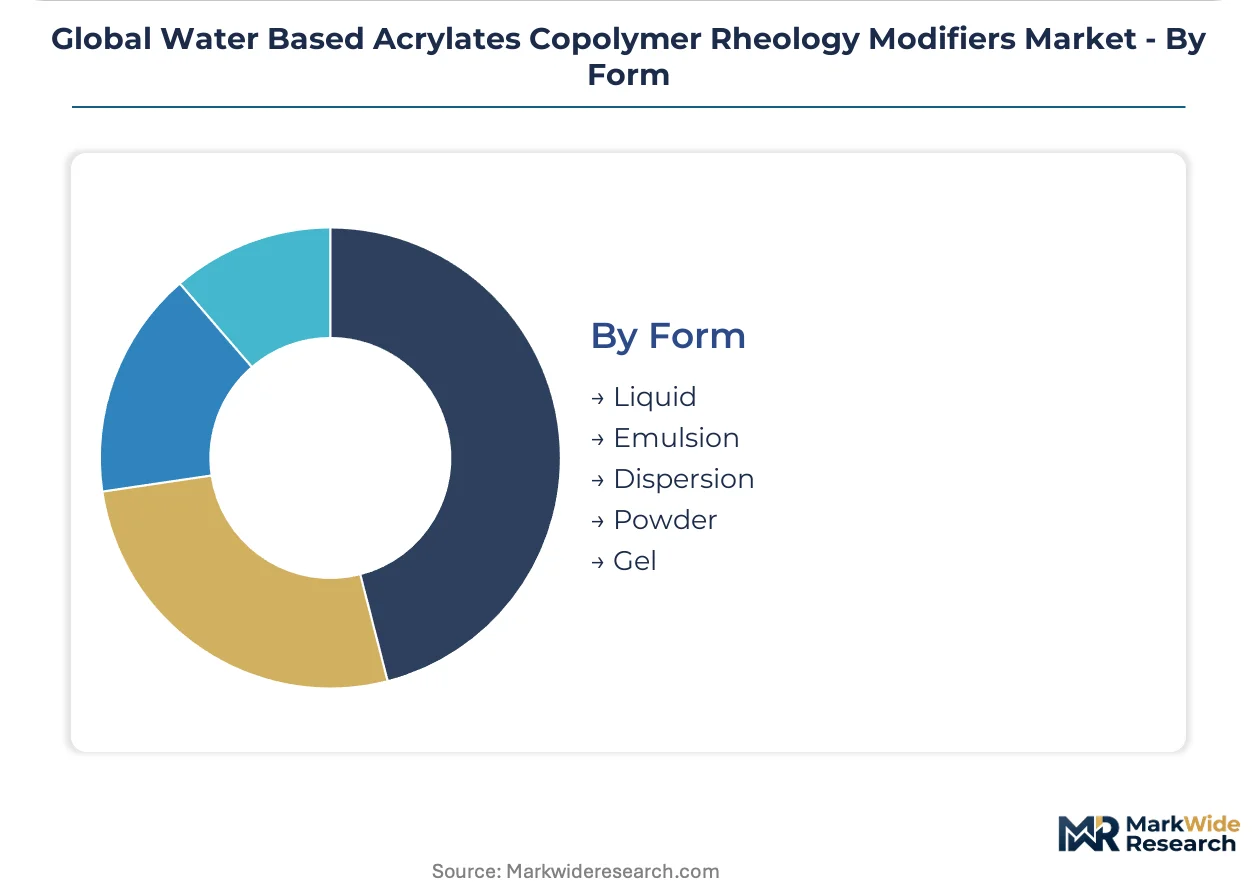
- Liquid:Pumpable associative thickener dispersions dominate high-volume architectural coatings production in China. Domestic coating capacity scaling concentrates demand for liquid formats that integrate directly into continuous manufacturing workflows.
- Emulsion:Pre-dispersed hydrophobically modified polymers simplify incorporation for mid-sized paint manufacturers lacking high-shear mixing equipment.
- Dispersion:Concentrated associative thickener slurries reduce transport costs for regional distributors serving fragmented adhesive producer bases.
- Powder:Carbomer and cellulose derivatives sustain solid format preference in personal care and detergent applications.
- Gel:High-solids carbomer gels serve specialized cosmetic formulation requirements.
Liquid formats dominate volume; Emulsion formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of water-based rheology modifiers consumed across Asia-Pacific, while the United States and Germany remain critical formulation technology centers despite lower domestic additive production volumes.
China
Paint producers in the Yangtze River Delta and Pearl River Delta clusters drive concentrated demand for associative thickeners in high-build architectural coatings. The Ministry of Ecology and Environment enforces progressively tighter VOC ceilings on industrial coatings manufactured in these regions. Domestic coating capacity scaling in Jiangsu and Guangdong provinces is reducing import dependency for rheology modifiers.
United States
Architectural coatings manufacturers consolidate procurement around water-based systems to comply with federal mandates. The Environmental Protection Agency maintains strict VOC limits on architectural coatings produced across the country. Formulation expertise concentrates in the Great Lakes industrial corridor, where mid-sized paint producers adopt modular additive packages.
Germany
Industrial adhesive formulators seek hybrid thickener architectures to bridge performance requirements without dual-inventory complexity. The European Chemicals Agency's REACH framework restricts specific monomer chemistries, compelling domestic suppliers to absorb reformulation investments. Production and technical service capabilities cluster in North Rhine-Westphalia's chemical manufacturing belt.
Japan
Premium cosmetic manufacturers specify carbomer-based rheology systems for skin care emulsions requiring high clarity and sensory performance. The Ministry of Economy, Trade and Industry oversees chemical substance management aligned with international frameworks. Formulation development concentrates in the Kanto region around Tokyo, where personal care brands maintain rigorous quality specifications.
South Korea
Domestic paint producers accelerate adoption of associative thickeners for exterior architectural systems. The Ministry of Environment implements VOC control programs for industrial coatings that favor water-based alternatives. Manufacturing activity concentrates in the Seoul Capital Area and Busan-Ulsan corridor, where coating production capacity continues expanding.
Global Water Based Acrylates Copolymer Rheology Modifiers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The market structure shows moderate consolidation around integrated chemical producers with captive acrylic acid supply chains. Three archetypes dominate: multinational diversified chemical groups with backward integration into monomer feedstock, specialty additive houses with concentrated rheology expertise, and regional distributors bundling modular formulation packages. Competitive dynamics center on securing consistent feedstock supply and embedding technical service capabilities into procurement relationships.
Among the diversified chemical conglomerates, BASF and Dow Chemical occupy positions anchored by integrated acrylic acid production capabilities. Arkema represents the specialty additive house archetype with concentrated expertise in rheology modifier architectures. Lubrizol sits within the performance-focused tier, exemplifying differentiation through specialized associative thickener designs for demanding industrial applications.
| Leading Market Players |
|---|
| Arkema |
| BASF |
| Dow Chemical |
| Lubrizol |
| AkzoNobel |
| BYK Additives & Instruments |
| Euclid Chemicals |
| Ashland |
| Evonik |
| Others |
Supply & Pricing Matrix
Propylene derivative price indices cascade directly through acrylic acid monomer costs into tiered pricing structures for water-based rheology modifiers, compressing margins for non-integrated additive suppliers while amplifying procurement leverage for paint manufacturers with volume scale.
Pricing Analysis
Margin tightening in non-associative grades reflects propylene derivative volatility and commoditization pressure from detergent formulators in India and Brazil. Three-tier pricing structure across premium associative, standard hybrid, and economy non-associative levels separates performance tiers by shear stability and VOC compliance certification. Cost-down pressure on mid-tier hybrid architectures accelerates as adhesive producers consolidate procurement around single-source thickener packages. Detergent suppliers exhibit highest price sensitivity due to bulk volume requirements and minimal formulation complexity, while premium architectural coatings manufacturers in China's Pearl River Delta absorb moderate premiums for REACH-compliant associative systems.
Supply Chain Analysis
China's domestic-content mandates for chemical manufacturing in Jiangsu and Guangdong provinces reshape sourcing patterns for multinational paint producers operating in Asia-Pacific. Manufacturing concentration centers on China, Germany, and the United States, with acrylic acid feedstock drawing from propylene crackers in the US Gulf Coast and Middle Eastern petrochemical complexes. Single-source vulnerability persists for hydrophobically modified monomers supplied through limited European specialty chemical channels. Distribution runs through direct procurement platforms and regional distributor networks serving fragmented mid-sized paint manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Associative thickener technology is displacing legacy alkali-swellable systems in architectural coatings, creating asymmetric reward structures for suppliers with hydrophobic modification expertise versus commodity polymer producers.
For Market Incumbents: Anchor market position through captive acrylic acid integration and specialized high-shear formulation capabilities for industrial coatings. Defend against hybrid architecture commoditization by embedding technical service into modular additive packages for mid-sized paint manufacturers in North America and Western Europe. Prioritize MEE VOC compliance pre-certification for Yangtze River Delta supply contracts. For New Entrants and Emerging Players: Enter via white-space positioning in adhesive producer segments seeking dual-mechanism thickeners without legacy technical service dependencies. Target mid-tier hybrid architectures for pressure-sensitive adhesive formulators in Germany and France facing REACH-driven reformulation timelines. Deploy direct procurement platforms with embedded compatibility databases to bypass established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty additive houses with concentrated rheology expertise in European regulatory compliance corridors. Long-term viability hinges on backward integration into monomer feedstock or exclusive hydrophobic modification IP. Monitor ECHA substance restriction announcements as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive propylene derivative supply secures margin stability for BASF and Dow Chemical against feedstock volatility. |
| Hybrid Thickener Architecture Development | Dual-mechanism polymers bridge performance gaps for Henkel and Arkema adhesive customers eliminating dual inventory. |
| REACH Compliance Pre-Certification | Early ECHA substance restriction alignment reduces stranded inventory risk for European additive suppliers. |
| Direct Procurement Platform Launch | Digital distribution disrupts traditional technical service relationships for mid-sized paint manufacturers in North America. |
| High-Shear Industrial Coating Specialization | Lubrizol's extreme shear expertise commands premium positioning in automotive and protective coatings segments. |
Research Methodology
Document review covered trade association publications from ACC and Cefic, customs databases, and SEC filings, complemented by interviews with plant managers at rheology modifier production facilities, procurement leads at downstream paint manufacturers, and technical R&D directors at additive suppliers. Bottom-up volume modeling triangulated against top-down market sizing from regulatory filing analysis and industry production capacity surveys.
Output projections span volume and value across the analysis window, with segmentation dimensions including associative versus non-associative mechanism, paint versus adhesive versus personal care application, liquid versus powder format, and regional production hub. CAGRs derived from historical trajectory analysis adjusted for regulatory phase-in schedules and domestic capacity buildout announcements in China. Forecast inputs incorporated MEE VOC ceiling enforcement timelines and ECHA substance restriction pre-announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene price spike scenarios or accelerated REACH substance bans. Projections reflect assumptions regarding coating production capacity scaling in Jiangsu and Guangdong and hybrid thickener adoption curves among European adhesive formulators. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
India Prussian Blue Market