
 Dehazer Market | 2026-2036
Dehazer Market Size, Share, and Industry Trends Forecast 2026-2036
Dehazer Market Outlook
Aftermarket service revenue is narrowing as manufacturers push integrated dehazer-substrate systems that reduce standalone chemical replenishment cycles. BASF SE leverages its polymer additive portfolio to bundle dehazer chemistries with coating resins, capturing recurring formulation demand. Evonik Industries AG specializes in silicone-based surface modifiers that command premium positioning in optical applications. Dow Chemical Company anchors North American supply through captive siloxane production and direct OEM qualification programs.
A dehazer is a surface-active chemical agent, typically comprising modified silicone polymers or fluorinated compounds at 0.1-5% active concentration, that eliminates micro-droplet haze from transparent substrates by reducing interfacial tension and promoting film formation. Its primary industrial purpose is to restore or maintain optical transmission efficiency in automotive windshields, aircraft canopies, and display panels. Chemical dehazers retain the largest volume share in automotive surface treatment, though water-based formulations are gaining fastest as VOC regulations tighten across manufacturing jurisdictions. Optical dehazers command the highest margin pool in aerospace and precision optics where nanometer-scale clarity thresholds apply.
EPA TSCA chemical notification requirements in the United States and REACH substance registration in Europe constrain novel dehazer ingredient introduction, extending development timelines and favoring incumbents with established dossiers. China's MEE environmental standards and GB formulation labeling rules are pushing domestic producers toward aqueous systems and away from solvent-heavy legacy products. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments as compliance thresholds decouple.
Market Dynamics
Automotive OEMs are consolidating dehazer procurement into multi-year coating system contracts, compressing standalone chemical margins while favoring suppliers with integrated formulation capabilities.
Growth Catalysts
- EV Windshield Complexity:Electric vehicle panoramic glass roofs and augmented reality head-up displays require precision optical clarity, expanding specification-grade dehazer volumes.
- REACH SVHC Restrictions:Europe's Substances of Very High Concern framework is phasing out legacy fluorinated surfactants, creating replacement demand for compliant silicone-based alternatives.
- China GB Standards:The country's mandatory aqueous formulation labeling rules under MEE oversight are accelerating domestic production line conversions.
Market Restraints
- Siloxane Feedstock Concentration:Specialty silicone intermediate supply clusters in Germany and Japan expose formulators to concentrated input risk.
- EPA TSCA Notification Timelines:New chemical substance review periods in the United States extend 18-24 months, delaying novel ingredient commercialization.
- Water-Based Performance Gap:Aqueous dehazer formulations still trail solvent systems in extreme humidity performance, limiting aerospace adoption.
Strategic Opportunities
- India Automotive Manufacturing:The country's PLI scheme for auto components is drawing coating operations that need localized dehazer supply.
- Optical Polymer Convergence:Dehazer chemistries are integrating with anti-reflective and anti-fingerprint coatings in single-application systems.
- Direct OEM Qualification:Bypassing tiered coating distributors through captive technical service teams captures specification influence.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in silicone-polymer interfacial chemistry remains concentrated among aging specialists in Germany and Japan.
- Dual Certification Burden:Aerospace dehazers require simultaneous FAA airworthiness and OEM optical qualification, extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehazer Market |
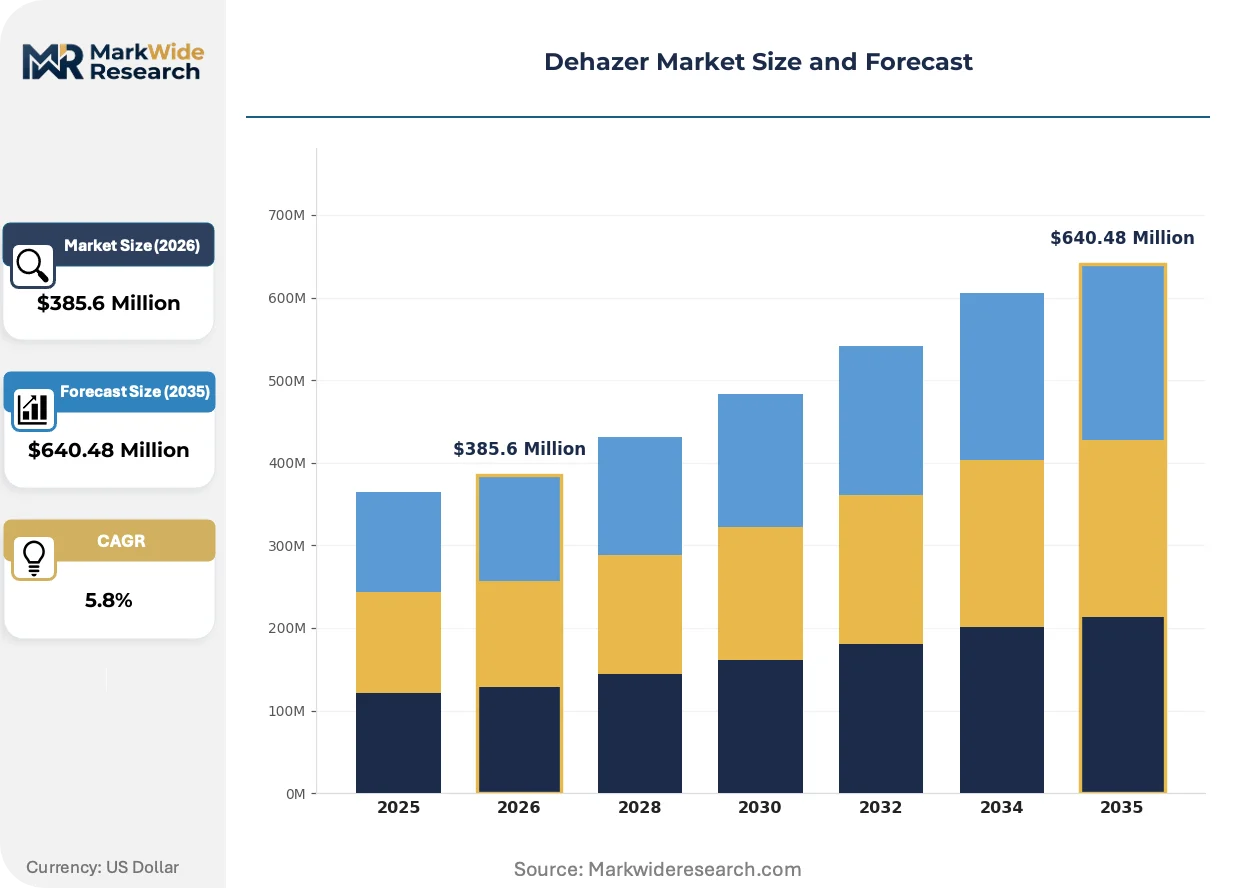
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Dehazers, Optical Dehazers, Water-based Dehazers, Powder Dehazers End User: Aerospace, Automotive, Manufacturing, Marine Application: Surface Treatment, Image Processing, Optical Devices, Automotive Lenses Technology: UV Treatment, Chemical Reaction, Mechanical Filtration, Electrodynamic |
| Companies Covered | BASF SE, 3M Company, Dow Chemical Company, Evonik Industries AG, Ecolab Inc., Henkel AG & Co. KGaA, Stepan Company, Valvoline Inc., WD-40 Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehazer Market Strategic Shifts
Digital twin modeling of coating application processes is compressing formulation development cycles while regulatory divergence between jurisdictions is fragmenting product portfolios.
Self-assembling monolayer (SAM) dehazer technology is virtualizing traditional multi-step surface preparation by enabling single-dip optical clarity restoration. Automotive glass manufacturers in South Korea and Germany are piloting SAM systems for windshield pre-treatment. This convergence is virtualizing the boundary between cleaning and coating operations, collapsing process equipment footprints.
China's MEE is tightening volatile organic compound emission caps for industrial coating facilities under its dual carbon policy framework. Manufacturers operating in Jiangsu and Guangdong provinces face mandated solvent reduction targets of 30% by 2025. Waterborne dehazer formulations are capturing specification share in domestic automotive OEM contracts as compliance deadlines approach.
Buyers are unbundling after-sales chemical replenishment from original equipment supply agreements. Fleet operators and aftermarket glass installers now source dehazer concentrates directly from chemical distributors rather than through captive coating system vendors. This disintermediation is most pronounced in North American commercial vehicle windscreen replacement channels.
Dehazer Market Segmentation
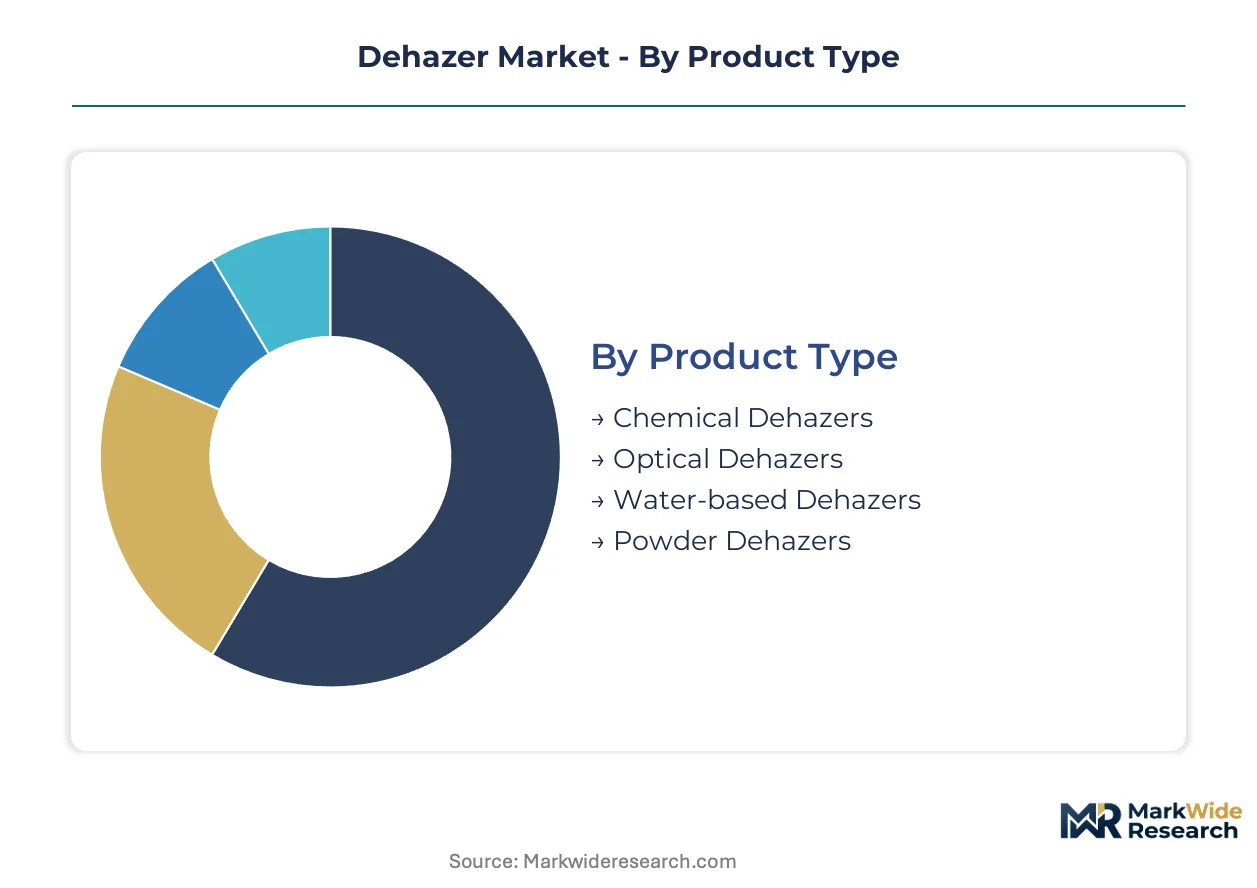
Dehazer procurement cycles vary dramatically across product categories and end-use applications. Understanding these velocity differences helps suppliers align inventory and technical service resources with actual consumption patterns.
Product Type:
Water-based formulations turn over fastest as regulatory deadlines force line conversions, while optical dehazers move slowest due to aerospace qualification timelines.
- Chemical Dehazers:Modified silicone-polymer concentrates at 0.1-5% active loading dominate automotive surface treatment volumes. Demand concentrates in China where EV glass production scales under MEE emission caps. This segment dominates installed base.
- Optical Dehazers:Nanometer-precision fluorinated and silicone-based systems command premium positioning in aerospace canopies and precision optics. Germany's optical cluster and South Korean display manufacturers drive specification-grade procurement. Dual FAA-OEM certification extends replacement cycles to 5-7 years. This segment is where expansion concentrates.
- Water-based Dehazers:Aqueous systems are climbing the fastest as REACH SVHC restrictions and China's GB labeling rules displace solvent alternatives.
- Powder Dehazers:Solid concentrate formats serve remote marine and industrial applications where liquid shipping faces hazmat constraints.
Chemical dehazers dominate installed base. Water-based formulations are where expansion concentrates.
End User:
Automotive applications generate the highest absolute volumes, while aerospace commands the steepest margin tier due to certification barriers.
- Automotive:OEM windshield and panoramic roof treatment represents the volume anchor. China EV production and Germany's premium vehicle glass clusters drive specification demand. Integrated coating-dehazer systems are compressing standalone chemical margins.
- Aerospace:Canopy and flight deck optical clarity requirements impose nanometer-scale specifications. FAA airworthiness qualification and OEM optical validation create dual certification burdens that favor incumbent suppliers with established dossiers.
- Manufacturing:Display panel and precision optical component production in South Korea and Taiwan consumes specification-grade surface treatment chemicals.
- Marine:Bridge window and vessel glazing applications favor powder concentrate formats for logistics simplicity in port-distributed supply chains.
Automotive anchors volume throughput. Aerospace represents the steepest margin tier.
Application:
Surface treatment applications scale with manufacturing output, while image processing links to semiconductor and display capital expenditure cycles.
- Surface Treatment:Pre-coating substrate preparation for automotive glass and aerospace canopies constitutes the foundational demand pool. China Jiangsu and Guangdong coating facilities drive aqueous formulation uptake under dual carbon policy enforcement.
- Automotive Lenses:Head-up display and camera lens clarity requirements are expanding fastest as ADAS penetration deepens.
- Optical Devices:Precision instrument and medical device glazing applications command specification premiums in Germany and Switzerland.
- Image Processing:Semiconductor lithography and display manufacturing process fluids represent a specialized, low-volume, high-purity niche.
Surface treatment dominates current procurement. Automotive lens applications are gaining share fastest.
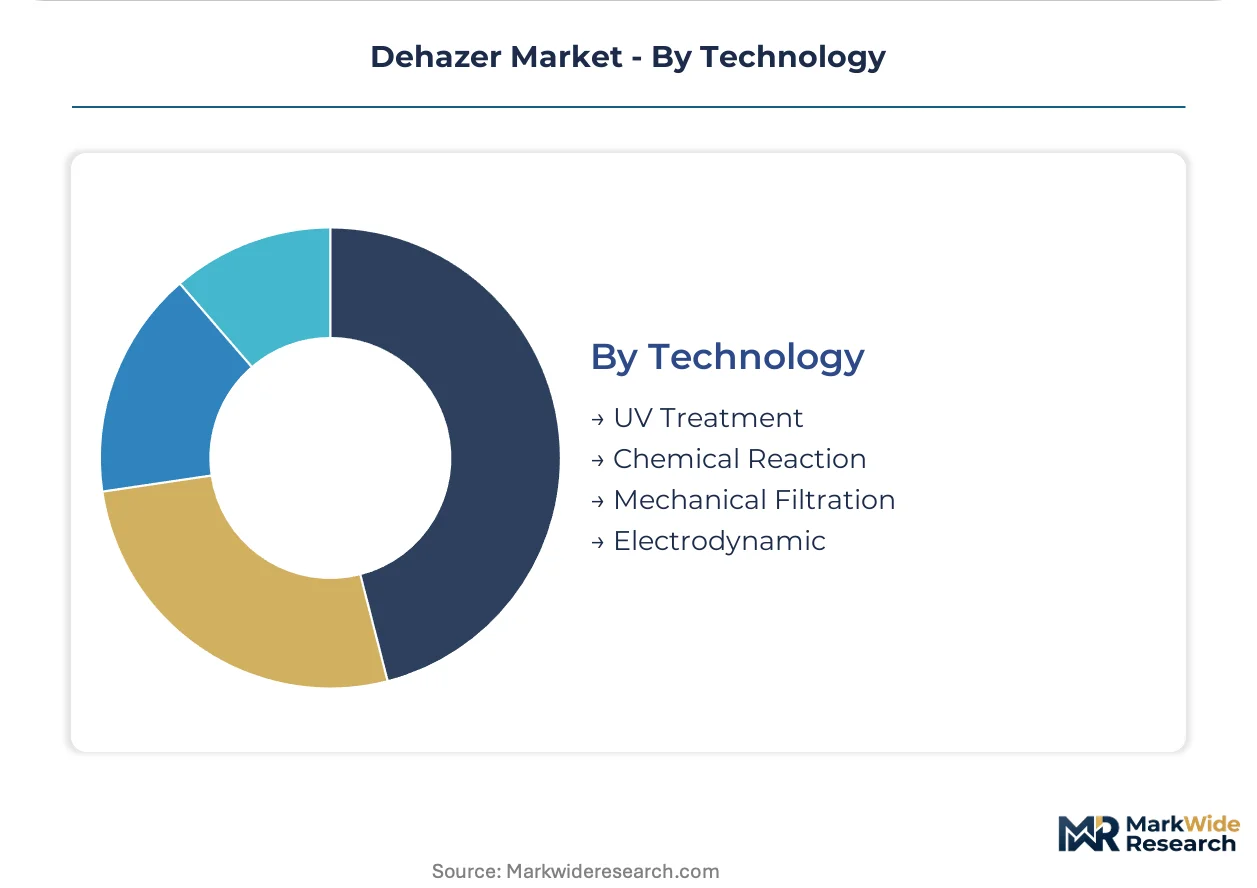
Technology:
Chemical reaction systems enjoy broadest compatibility, while electrodynamic approaches remain confined to specialized semiconductor process applications.
- Chemical Reaction:Silicone-polymer interfacial tension reduction represents the mainstream technology with established supply chains in Germany and Japan. EPA TSCA notification requirements constrain novel ingredient introduction.
- UV Treatment:Photocatalytic surface activation serves high-throughput automotive lines where process speed outweighs capital intensity.
- Mechanical Filtration:Physical droplet separation complements chemical approaches in heavy-contamination marine and industrial settings.
- Electrodynamic:Electric field-driven haze removal serves specialized semiconductor wafer processing with extreme purity requirements.
Chemical reaction systems dominate installed base. UV treatment is where capacity additions concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in China demonstrate the highest price elasticity as domestic manufacturers optimize coating costs at scale, while aerospace buyers in Germany and the United States absorb premium pricing for dual-certified optical-grade formulations without volume negotiation leverage.
China
Electric vehicle production at BYD and Tesla Shanghai drives specification-grade dehazer procurement for panoramic glass roofs. MEE enforcement of GB formulation labeling rules and dual carbon policy solvent reduction targets of 30% by 2025 accelerates aqueous system adoption. Jiangsu and Guangdong province coating facilities dominate domestic manufacturing conversion timelines.
Germany
Premium automotive OEM optical clarity specifications from BMW and Mercedes-Benz sustain demand for nanometer-precision formulations. ECHA REACH SVHC restrictions on legacy fluorinated surfactants create replacement demand for compliant silicone-based alternatives. The Baden-Württemberg optical cluster anchors specification-grade supply chain qualification protocols.
United States
Commercial fleet windscreen replacement channels drive aftermarket dehazer concentrate procurement through direct chemical distributor relationships. EPA TSCA notification requirements extend novel ingredient development timelines to 18-24 months. Michigan and Ohio automotive manufacturing corridors concentrate captive OEM qualification programs.
Japan
Precision optical component manufacturers in display and semiconductor capital equipment sustain low-volume, high-purity dehazer demand. METI industrial chemical standards align with international aerospace certification requirements. The Nagoya-Chubu manufacturing belt specializes in silicone-polymer interfacial chemistry expertise.
South Korea
Samsung Display and LG Chem drive specification-grade surface treatment chemical procurement for panel manufacturing. MFDS chemical substance management integrates with export market REACH compliance requirements. The Gyeonggi-Seoul capital area concentrates automotive glass OEM technical service operations.
Dehazer Market Competitive Environment
Integrated chemical conglomerates and specialty silicone formulators split the market along capability lines. The vendor base concentrates around three tiers: multinational diversified chemical suppliers with captive raw material positions, mid-cap specialists in fluorinated and silicone-polymer surface modifiers, and regional formulators serving localized automotive coating operations. Dominant competitive moves include backward integration into siloxane feedstock production and direct OEM qualification bypassing tiered coating distributors.
Within the integrated chemical tier, BASF SE and Dow Chemical Company exemplify multinational scale advantages through polymer additive portfolio bundling and captive siloxane production respectively. Evonik Industries AG occupies a specialist position in silicone-based surface modifiers. These three entities anchor the competitive structure through differentiated access to formulation chemist expertise concentrated in Germany and Japan.
| Leading Market Players |
|---|
| BASF SE |
| 3M Company |
| Dow Chemical Company |
| Evonik Industries AG |
| Ecolab Inc. |
| Henkel AG & Co. KGaA |
| Stepan Company |
| Valvoline Inc. |
| WD-40 Company |
| Others |
Value Chain & Pricing Dynamics
Single-source siloxane dependency in Germany and Japan determines both the premium spread for optical-grade formulations and the geographic clustering of captive production facilities. EPA TSCA notification timelines and REACH SVHC compliance costs widen pricing tiers between established dossier-holders and novel ingredient developers, compressing margins for non-integrated formulators while rewarding backward-integrated suppliers with in-house silicone intermediate production.
Pricing Analysis
After-sales chemical replenishment contracts drive lifetime value capture as fleet operators and aftermarket installers disintermediate captive coating vendors. Three-tier pricing structure separates aerospace dual-certified optical grades from automotive specification formulations and economy water-based concentrates. Cost compression in automotive surface treatment intensifies as OEMs bundle dehazer chemistries into multi-year coating system agreements. Commercial vehicle windscreen replacement channels in North America demonstrate highest price elasticity, while German aerospace buyers absorb premium positioning without volume leverage.
Supply Chain Analysis
Extended payment terms from automotive OEMs strain working capital for mid-cap formulators lacking supply-chain finance facilities. Specialty silicone intermediate production concentrates in Germany, Japan, and China's Jiangsu province, with formulation expertise clustering around the Nagoya-Chubu belt. Siloxane feedstock dependency creates single-source vulnerability when geopolitical friction disrupts German-Japanese chemical trade. Distribution runs through tiered coating distributors in mature markets, while direct chemical distributor relationships dominate North American aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne formulation mandates across China's MEE enforcement and Europe's REACH SVHC framework constitute a regulatory inflection reshaping competitive positioning. Suppliers with established aqueous system dossiers capture specification share as solvent-heavy legacy products face phased withdrawal.
For Market Incumbents: Pre-empt margin erosion in automotive surface treatment by deepening captive siloxane production and accelerating direct OEM qualification programs. BASF SE's polymer additive bundling strategy and Dow Chemical's captive production models demonstrate defensive positioning against integrated coating-dehazer system consolidation. Certification investment in dual FAA-OEM aerospace dossiers preserves premium tier access.
For New Entrants and Emerging Players: India's PLI scheme for auto components offers underpenetrated coating operations requiring localized dehazer supply. Technical service partnerships with emerging EV glass manufacturers in Jiangsu and Guangdong provinces provide qualification pathways without incumbent distributor relationships. Self-assembling monolayer technology pilots in South Korea and Germany represent white-space entry angles for novel process convergence.
For Investors and Strategic Acquirers: REACH SVHC restrictions on fluorinated surfactants reshape the acquisition landscape toward silicone-based formulation specialists with compliant alternative portfolios. Mid-cap German and Japanese surface modifier firms with aging specialist workforces present consolidation targets. Watch MEE dual carbon policy enforcement timelines as inflection indicators for aqueous formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Captive silicone intermediate production insulates BASF SE and Dow Chemical from German-Japanese supply concentration risk. |
| Direct OEM Qualification Programs | Bypassing tiered coating distributors captures specification influence in Michigan and Ohio automotive manufacturing corridors. |
| Waterborne Formulation Line Conversion | MEE solvent reduction targets in Jiangsu and Guangdong provinces force domestic Chinese producers toward aqueous systems. |
| Dual FAA-OEM Certification Investment | Simultaneous airworthiness and optical validation extends replacement cycles to 5-7 years in aerospace canopy applications. |
| SAM Technology Pilot Partnerships | Self-assembling monolayer pilots with South Korean and German automotive glass manufacturers collapse process equipment footprints. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive OEM procurement leads, aerospace coating specification engineers, chemical distribution channel managers, and silicone-polymer R&D directors. Secondary validation drew from EPA TSCA chemical substance inventories, ECHA REACH registration databases, China MEE emission compliance filings, and ACC specialty chemical trade data. Bottom-up consumption modeling and top-down production capacity estimates were triangulated to anchor volume projections.
Calibration against historical formulation adoption curves and regulatory phase-in timelines shaped the analytical framework across the projection horizon. Segmentation dimensions included product type tier, end-use industry vertical, application method, and regional regulatory cluster. CAGRs were derived from fitted diffusion curves incorporating EV glass production scaling, aqueous system line conversion rates, and aerospace qualification cycle durations. Siloxane feedstock capacity additions and MEE enforcement intensity served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates or accelerated REACH SVHC restriction timelines would shift outcomes. Macroeconomic deviation in automotive production, regulatory enforcement intensity variation, or breakthrough SAM technology commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Acetum Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Phosphatidylcholine Market