
 Lithium Difluoro(Oxalato)Borate Market | 2026-2036
Lithium Difluoro(Oxalato)Borate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Difluoro(Oxalato)Borate Market Analytics
Subscription-based electrolyte formulation services is realigning how lithium salt producers monetize technical expertise beyond commodity sales. Solvay S.A. leverages its fluorochemistry heritage to sustain premium positioning in European battery supply chains. Guangzhou Tinci Materials Technology Co., Ltd. anchors volume production through captive integration with downstream electrolyte blending. Soulbrain Co., Ltd. differentiates via ultra-high-purity grades targeting South Korean cell makers.
Lithium difluoro(oxalato)borate is a boron-based lithium salt with a molecular structure combining difluoroborate and oxalate ligands, synthesized through controlled fluorination and complexation reactions to achieve battery-grade purity exceeding 99.9 percent; it functions primarily as an electrolyte additive and conductivity salt in lithium-ion cells, forming stable solid-electrolyte interphase layers that suppress aluminum corrosion at high voltages above 4.3 volts. Powder grades currently dominate commercial shipments due to compatibility with standard dry-mixing protocols and extended shelf stability, while solution formats are gaining fastest in pilot-line environments where direct liquid dosing reduces contamination risk. The energy storage application segment carries concentrated margin pools as grid-scale battery projects specify additive loading rates that exceed consumer electronics thresholds.
China's SAMR enforces GB/T standards for electrolyte salt purity that effectively gate market access for uncertified imports, while the EU's REACH framework and Battery Regulation impose full supply-chain disclosure obligations on additive suppliers serving European cell plants. Japan's METI coordinates national R&D consortia that pre-qualify domestic producers for automotive qualification programs. Stakeholders must monitor evolving cathode chemistry transitions—particularly high-nickel and lithium-metal architectures—to anticipate reformulation demands that could obsolete current additive specifications.
Market Dynamics
High-voltage cathode chemistries above 4.3 volts are forcing electrolyte reformulation across lithium-ion cell manufacturing, compressing qualification timelines for additive suppliers serving automotive and grid-scale energy storage programs.
Growth Catalysts
- EU Battery Regulation:Mandatory supply-chain disclosure obligations and recycled-content thresholds are accelerating additive qualification for European cell plants seeking compliant electrolyte formulations.
- High-nickel cathode penetration:NMC 811 and NCA chemistries require aluminum corrosion suppression that LiDFOB provides at elevated operating voltages, pulling additive volumes into automotive battery supply chains.
- Jiangsu-Guangdong production clusters:Co-location of cathode foundries and electrolyte blenders in these Chinese provinces creates dense procurement networks that reduce logistics friction for salt suppliers.
Market Restraints
- Fluorinated precursor volatility:Lithium hexafluorophosphate price swings transmit directly to LiDFOB production economics, compressing margin visibility for non-integrated salt manufacturers.
- Single-source fluorination capacity:Battery-grade difluoroborate intermediate production concentrates among Chinese chemical specialists, creating geographic supply vulnerability for downstream additive producers.
- Moisture sensitivity:LiDFOB hydrolysis rates above 50 ppm water content necessitate hermetic packaging and controlled-atmosphere handling that elevates distribution costs versus conventional lithium salts.
Strategic Opportunities
- Solid-state battery interfaces:Lithium-metal anode architectures under development at South Korean and Japanese cell makers specify oxalato-borate additives for interphase stabilization, opening pre-qualification channels.
- GB/T certification arbitrage:Uncertified import restrictions under China's SAMR standards create protected market access for domestic producers with accredited testing facilities.
- Solution-format dosing systems:Direct liquid injection equipment at pilot-scale cell lines eliminates powder-handling contamination risks, enabling premium pricing for pre-dissolved additive formulations.
Industry Challenges
- Electrolyte formulation chemist scarcity:Cross-functional expertise spanning fluorochemistry, electrochemistry, and cell engineering concentrates among senior researchers at established battery material firms, constraining talent mobility.
- Automotive qualification timelines:OEM cell validation protocols spanning 24-36 months delay revenue recognition for additive suppliers targeting electric vehicle supply chains, stretching working capital cycles.
- IP thickets around synthesis routes:Patent estates covering controlled fluorination and complexation methods create licensing friction for new entrants seeking battery-grade purity above 99.9 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Difluoro(Oxalato)Borate Market |
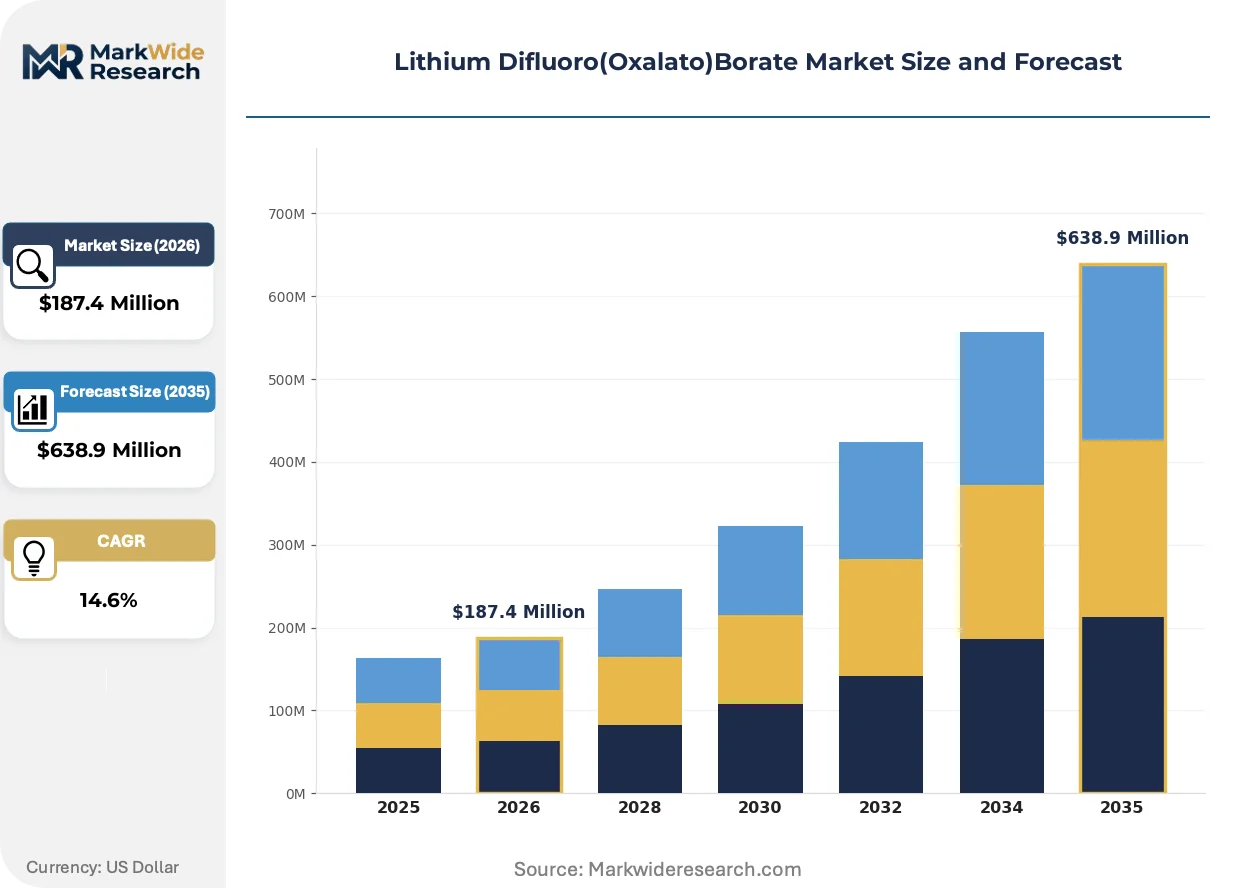
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Solution, Crystals, Granules End User: Batteries, Electronics, Aerospace, Automotive Application: Energy Storage, High-Performance Fluids, Coatings, Lubricants Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Solvay S.A., Guangzhou Tinci Materials Technology Co., Ltd., Shenzhen Capchem Technology Co., Ltd., Mitsubishi Chemical Corporation, Nippon Shokubai Co., Ltd., Guotai Huarong New Chemical Materials Co., Ltd., Soulbrain Co., Ltd., Jiangsu Ruitai New Energy Materials Co., Ltd., Shida Shinghwa Advanced Material Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Difluoro(Oxalato)Borate Market Evolving Landscape
Electrolyte additive architecture is fragmenting into application-specific formulations as cell chemistry diversity expands beyond standardized NMC-graphite systems, forcing suppliers to abandon one-size-fits-all product strategies.
Solution-format LiDFOB delivery is modularizing how electrolyte blenders manage additive incorporation. Pre-dissolved concentrates eliminate powder aerosolization risks in dry rooms. Korean and Chinese pilot lines are adopting direct liquid dosing at 50-200 liter scale. This format compression is collapsing the traditional separation between salt production and electrolyte compounding, enabling additive suppliers to capture blending-margin pools.
REACH Article 33 disclosure requirements are tightening substance transparency across European battery supply chains. Suppliers must now document full constituent composition down to 0.1 percent weight concentration. Automotive cell plants in Germany and Hungary are imposing extended safety data sheet obligations on additive vendors. The compliance burden falls most heavily on powder-grade shipments where surface coating chemistries require additional hazard classification.
Cell makers are consolidating supplier relationships around electrolyte formulation partners rather than discrete chemical vendors. Japanese automotive battery programs now specify qualified electrolyte blends rather than component-level procurement, compressing the number of approved salt suppliers per cell platform. South Korean energy storage projects are following this pattern, awarding multi-year formulation service contracts to integrated material suppliers with in-house salt production and blending capabilities.
Lithium Difluoro(Oxalato)Borate Market Segmentation
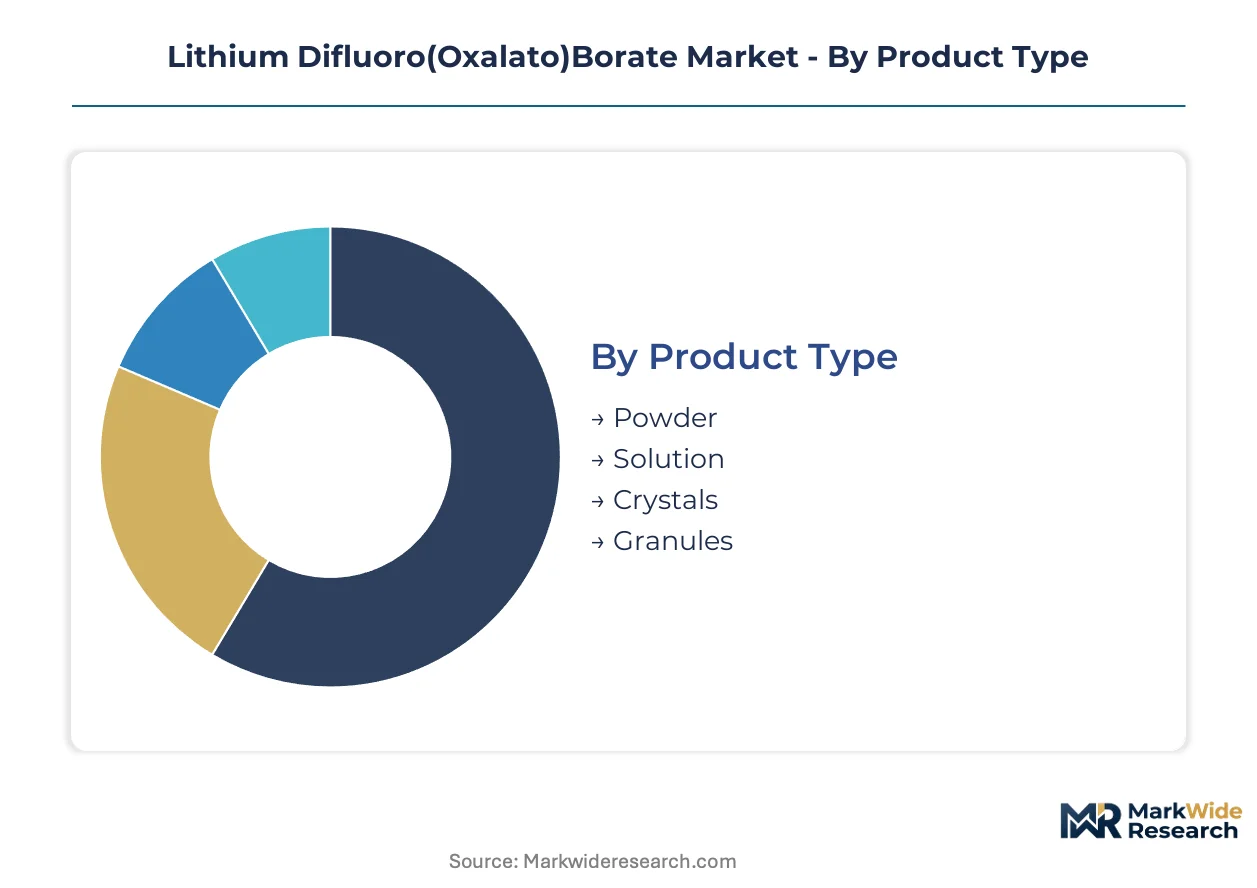
Segmentation in the lithium difluoro(oxalato)borate market reflects divergent purity requirements, handling protocols, and supply-chain integration levels across battery-grade and industrial-grade applications. Suppliers must align product formats with customer technical capabilities and contamination risk tolerances.
Product Type:
Powder formats dominate volume shipments while solution formats command premium positioning in integrated electrolyte operations.
- Powder:Dry crystalline material with particle sizes optimized for dry-room mixing protocols. Jiangsu and Guangdong cathode plants specify powder grades for compatibility with established material handling systems. Automotive cell qualification programs favor powder for batch-to-batch consistency documentation.
- Solution:Pre-dissolved concentrates in carbonate solvents eliminate aerosolization hazards and enable direct liquid dosing. Korean pilot lines at 50-200 liter scale are adopting this format fastest, collapsing the boundary between salt production and electrolyte compounding.
- Crystals:Large-format single crystals for specialized electrochemical research and solid-state battery interface studies.
- Granules:Free-flowing agglomerated particles for automated dispensing in high-throughput electrolyte blending operations.
Today's leader: Powder. Tomorrow's challenger: Solution.
End User:
Customer technical sophistication determines specification stringency and qualification timeline intensity.
- Batteries:Lithium-ion cell manufacturers require 99.9 percent purity with moisture content below 50 ppm. China's SAMR enforces GB/T standards that gate market access for uncertified imports, while EU Battery Regulation imposes full supply-chain disclosure on additive suppliers.
- Electronics:Consumer device battery pack assemblers specify additive loading rates lower than grid-scale thresholds but demand faster procurement cycles.
- Aerospace:Satellite and aviation battery systems prioritize thermal stability documentation and extended safety data sheet obligations.
- Automotive:OEM cell validation protocols spanning 24-36 months delay revenue recognition, stretching working capital cycles for additive suppliers targeting electric vehicle supply chains.
Batteries absorb the dominant share of qualified volumes. Automotive programs carry the steepest expansion trajectory as high-nickel cathode penetration accelerates.
Application:
Performance requirements fragment sharply between electrochemical stability demands and conventional chemical functionality.
- Energy Storage:Grid-scale battery projects specify additive loading rates exceeding consumer electronics thresholds, carrying concentrated margin pools. Aluminum corrosion suppression at voltages above 4.3 volts drives specification intensity.
- High-Performance Fluids:Thermal management and dielectric applications in industrial equipment.
- Coatings:Surface treatment formulations leveraging boron-fluorine chemistry for corrosion resistance.
- Lubricants:Extreme-pressure additives for specialized mechanical systems.
Energy Storage commands premium positioning. High-Performance Fluids offers diversification for non-qualified suppliers.
Distribution Channel:
Channel selection tracks customer scale, technical support requirements, and contamination risk management capabilities.
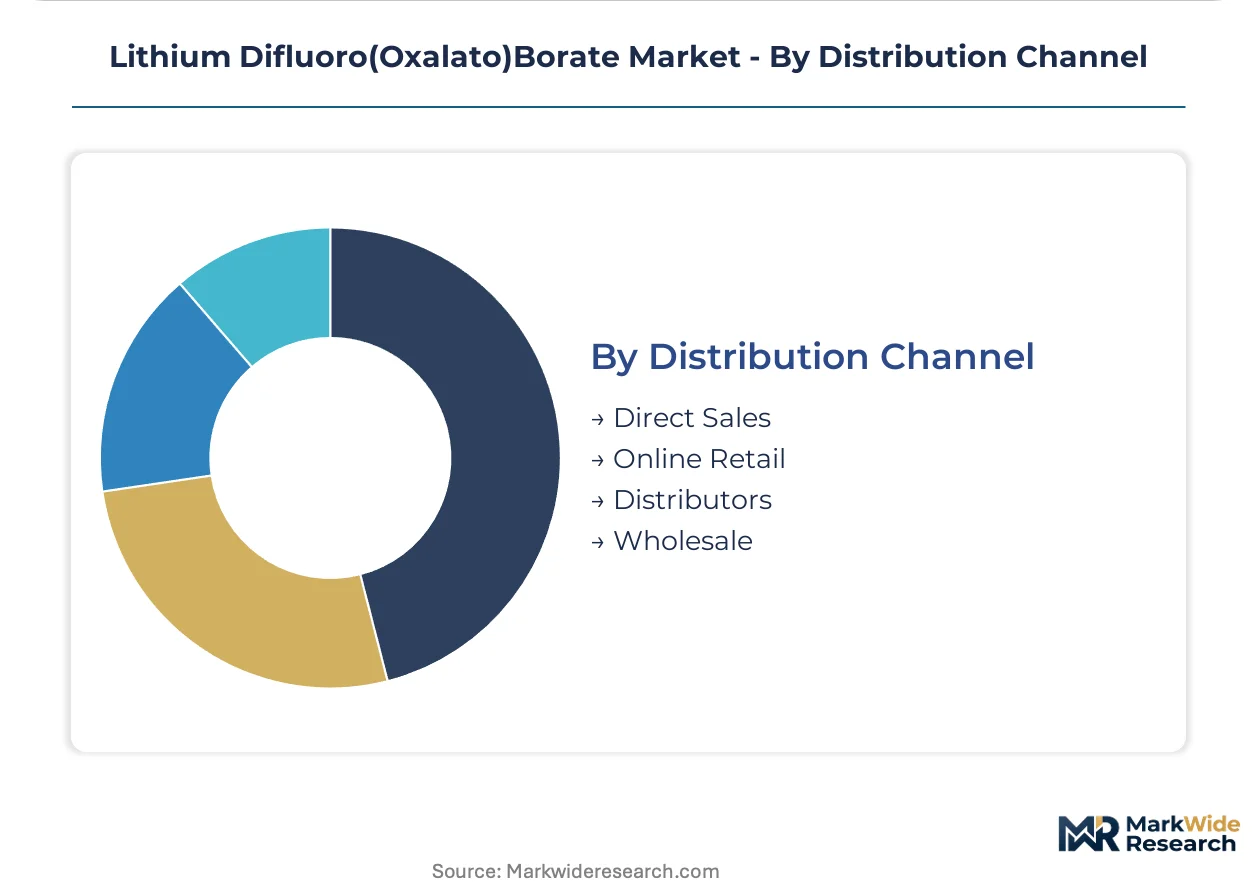
- Direct Sales:Large electrolyte blenders and automotive cell plants procure through long-term supply agreements with technical service attachments. Japanese automotive battery programs now specify qualified electrolyte blends rather than component-level procurement.
- Distributors:Regional chemical distributors serve mid-scale battery material compounders with localized inventory and handling expertise.
- Wholesale:Bulk material traders facilitate spot market access for qualified buyers with established storage infrastructure.
- Online Retail:Small-lot procurement for research institutions and pilot-scale operations.
Direct Sales locks in automotive qualification pipelines. Distributors capture mid-market electrolyte blender expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands additive procurement volumes while South Korea concentrates premium-grade qualification programs for automotive cell supply chains.
China
Jiangsu and Guangdong provinces host co-located cathode foundries and electrolyte blenders that drive dense procurement networks. SAMR enforces GB/T standards for electrolyte salt purity that gate market access for uncertified imports. Suzhou and Shenzhen clusters reduce logistics friction for salt suppliers through integrated material handling infrastructure.
South Korea
Soulbrain Co., Ltd. anchors ultra-high-purity production targeting domestic cell makers with automotive qualification pipelines. METI-coordinated R&D consortia indirectly influence Korean technical specifications through shared automotive customer requirements. Busan-Ulsan industrial complexes concentrate fluorination capacity for downstream additive production.
Japan
Mitsubishi Chemical Corporation and Nippon Shokubai Co., Ltd. leverage fluorochemistry heritage to sustain premium positioning in regional battery supply chains. METI coordinates national R&D consortia that pre-qualify domestic producers for automotive programs. Kanto and Kansai regions concentrate electrolyte formulation expertise for next-generation cell architectures.
Germany
Automotive cell plants in Bavaria and Lower Saxony impose extended safety data sheet obligations on additive vendors under REACH Article 33. EU Battery Regulation mandates supply-chain disclosure and recycled-content thresholds that accelerate additive qualification. ECHA frameworks require full constituent documentation down to 0.1 percent weight concentration.
United States
EPA and OSHA guidelines govern fluorinated chemical handling for domestic electrolyte compounders serving energy storage projects. The Inflation Reduction Act's domestic content provisions incentivize localized additive sourcing for grid-scale battery deployments. Texas and California industrial corridors concentrate pilot-scale cell manufacturing that specifies direct liquid dosing formats.
Lithium Difluoro(Oxalato)Borate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated material suppliers capturing formulation service contracts while discrete salt producers compete on purity certification. The vendor base concentrates among fluorochemistry heritage firms and Chinese electrolyte integrators, creating tiered access to automotive qualification pipelines. Three archetypes dominate: European specialty chemical multinationals with REACH compliance infrastructure, Chinese producers with captive downstream integration, and Korean-Japanese specialists targeting ultra-high-purity automotive grades. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing fluorinated precursor supply agreements and pre-qualifying for solid-state battery programs.
Among European specialty chemical multinationals, Solvay S.A. exemplifies the fluorochemistry heritage archetype that sustains premium positioning through regulatory compliance infrastructure. Within the integrated Chinese producer tier, Guangzhou Tinci Materials Technology Co., Ltd. and Shenzhen Capchem Technology Co., Ltd. represent volume-oriented specialists with captive electrolyte blending capabilities. Soulbrain Co., Ltd. occupies a position within the Korean ultra-high-purity segment, anchoring qualification relationships with domestic automotive cell makers.
| Leading Market Players |
|---|
| Solvay S.A. |
| Guangzhou Tinci Materials Technology Co., Ltd. |
| Shenzhen Capchem Technology Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Nippon Shokubai Co., Ltd. |
| Guotai Huarong New Chemical Materials Co., Ltd. |
| Soulbrain Co., Ltd. |
| Jiangsu Ruitai New Energy Materials Co., Ltd. |
| Shida Shinghwa Advanced Material Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in China's Jiangsu and Guangdong provinces anchor volume production, translating captive fluorination capacity into pricing discipline that resists commoditization pressure from non-integrated importers. Their hermetic packaging investments and SAMR certification infrastructure sustain premium capture against uncertified competitors while GB/T compliance costs erect barriers that protect domestic margin pools.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for ultra-high-purity grades serving automotive qualification pipelines. Three-tier pricing structure across battery-grade certified, industrial-grade standard, and research-grade economy levels stratifies by purity threshold and moisture specification. Cost compression in powder formats is intensifying because Jiangsu producers are expanding fluorination throughput. Electronics assemblers exhibit highest price sensitivity due to compressed procurement cycles, while automotive cell plants prioritize qualification stability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German and Hungarian automotive cell plants are mandating multi-supplier qualification across Chinese, South Korean, and Japanese additive producers. Raw material dependencies center on lithium hexafluorophosphate precursor streams, difluoroborate intermediates, and carbonate solvent carriers. Single-source vulnerability concentrates in battery-grade difluoroborate intermediate production among Chinese chemical specialists. Distribution runs through direct long-term supply agreements with technical service attachments for large electrolyte blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Battery Regulation compliance costs in Germany and Hungary create protected margin pools against lower-certification Chinese spot supply.
For Market Incumbents: Acquire fluorination capacity in Busan-Ulsan industrial corridors to secure precursor supply against Chinese single-source concentration. Consolidate formulation service contracts with Japanese automotive battery programs before cell makers complete supplier consolidation around integrated electrolyte partners. Soulbrain's ultra-high-purity positioning demonstrates how automotive qualification pipelines defend against commodity substitution. For New Entrants and Emerging Players: Capture solution-format dosing system contracts at Korean and Chinese pilot lines where direct liquid injection eliminates powder-handling contamination risks. White-space concentration sits in solid-state battery interface pre-qualification channels at South Korean and Japanese cell makers developing lithium-metal architectures. Lead with pre-dissolved concentrate technical service bundles rather than commodity salt positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated salt manufacturers without captive electrolyte blending or automotive qualification pipelines. Long-term viability hinges on backward integration into fluorinated precursor production or forward integration into formulation services. Watch for solid-state battery program qualification announcements as the inflection signal separating durable premium capture from commoditization exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorination | Secures difluoroborate intermediate supply against Chinese geographic concentration risk. |
| Solution-Format Capacity Expansion | Captures pilot-line direct liquid dosing demand at Korean and Chinese cell manufacturing facilities. |
| GB/T Certification Investment | Unlocks protected market access under SAMR enforcement in Jiangsu and Guangdong procurement clusters. |
| Automotive Qualification Pipeline | Pre-qualifies for 24-36 month OEM cell validation protocols at German and Hungarian plants. |
| Solid-State Battery Interface R&D | Positions for lithium-metal anode additive specifications under development at Japanese and Korean consortia. |
Research Methodology
Coverage spans China, South Korea, Japan, Germany, and the United States, with primary inputs from each market's electrolyte blender procurement leads, fluorination plant technical directors, automotive cell platform engineers, and SAMR certification specialists. Secondary validation draws from customs trade data, SEC 10-K filings of listed chemical producers, ECHA REACH registration databases, and METI-coordinated R&D consortium disclosures. Bottom-up volume builds triangulate against top-down electrolyte formulation demand models.
Rate-of-change decomposition separates volume drivers from value migration across the projection horizon. Segmentation dimensions include product format tier, end-use application intensity, purity certification level, and regional regulatory cluster. CAGRs derive from electrolyte additive loading rate trajectories, cathode chemistry transition timelines, and automotive qualification pipeline maturation curves. Industry-specific inputs encompass high-nickel cathode penetration rates and solid-state battery development milestones.
Fluorinated precursor price volatility, automotive qualification timeline extensions, and cathode chemistry obsolescence are the dominant revision risks across the modeling period. Deviation in solid-state battery commercialization pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market