
 Stearates Market | 2026-2036
Stearates Market Size, Share, and Industry Trends Forecast 2026-2036
Stearates Market Outlook
Technical service contracts for lubricity optimization and custom blending are expanding what buyers purchase beyond commodity stearate volumes. Baerlocher GmbH leverages its European manufacturing footprint to sustain long-term supply agreements with polymer compounders. Peter Greven GmbH & Co. KG anchors its position through backward integration into fatty acid feedstocks. PMC Biogenix, Inc. competes on pharmaceutical-grade certification depth across North American and Asian markets.
Stearates are metallic salts of stearic acid, typically produced via direct fusion or precipitation reactions, with melting points ranging from 120°C to 180°C depending on the cation; they function primarily as lubricants, release agents, and acid scavengers in polymer processing and pharmaceutical tableting. Magnesium stearate dominates pharmaceutical applications due to its superior lubricity coefficient, while zinc stearate leads plastics and rubber segments where thermal stability during extrusion matters most. Calcium stearate maintains mature volume positions in construction and PVC stabilization, though margin pools increasingly shift toward food-grade and personal-care-certified grades.
REACH in Europe and FDA cGMP standards in the United States enforce heavy-metal limits and batch consistency that elevate compliance costs for uncertified producers. India's BIS quality marks and China's GB standards create additional regional entry barriers for imported stearate formulations. Stakeholders must monitor feedstock price volatility in palm and tallow derivatives, as these inputs dictate cost structures more directly than finished-product pricing power.
Market Dynamics
Pharmaceutical tablet production expansion and REACH-driven purity mandates are restructuring stearate procurement patterns, forcing compounders to qualify suppliers against heavy-metal thresholds and batch consistency protocols rather than commodity pricing alone.
Growth Catalysts
- REACH compliance thresholds:European ECHA enforcement of heavy-metal limits and impurity caps is disqualifying uncertified producers, concentrating volume among pharmaceutical-grade certified suppliers.
- India and China plastics processing:PVC extrusion and rubber compounding operations in these markets are absorbing zinc stearate volumes as polymer conversion rates accelerate.
- Direct fusion process optimization:Energy-efficient reactor designs are lowering unit production costs for magnesium stearate, improving margin capture for lubricant-grade output.
Market Restraints
- Palm and tallow derivative volatility:Feedstock cost swings in fatty acid inputs compress converter margins more acutely than finished-product pricing power can recover.
- European supply concentration:Polymer compounders in Germany and Belgium face limited qualified supplier pools for REACH-compliant zinc stearate, creating single-source vulnerability.
- Calcium stearate substitution pressure:Alternative acid scavengers in PVC stabilization are eroding volume positions for construction-grade calcium stearate formulations.
Strategic Opportunities
- Food-grade certification expansion:Personal-care and nutraceutical applications in North America are absorbing higher-margin stearate grades with Kosher and Halal compliance.
- Technical service contracting:Lubricity optimization and custom blending services are expanding addressable revenue beyond commodity volume sales to polymer processors.
- India BIS quality mark penetration:Domestic pharmaceutical manufacturers are upgrading from industrial-grade to certified magnesium stearate, opening premium positioning for compliant suppliers.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA cGMP validation and batch record documentation requirements extend supplier qualification cycles to 18-24 months.
- Legacy equipment retrofit costs:Precipitation reactor upgrades for heavy-metal reduction demand capital deployment that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stearates Market |
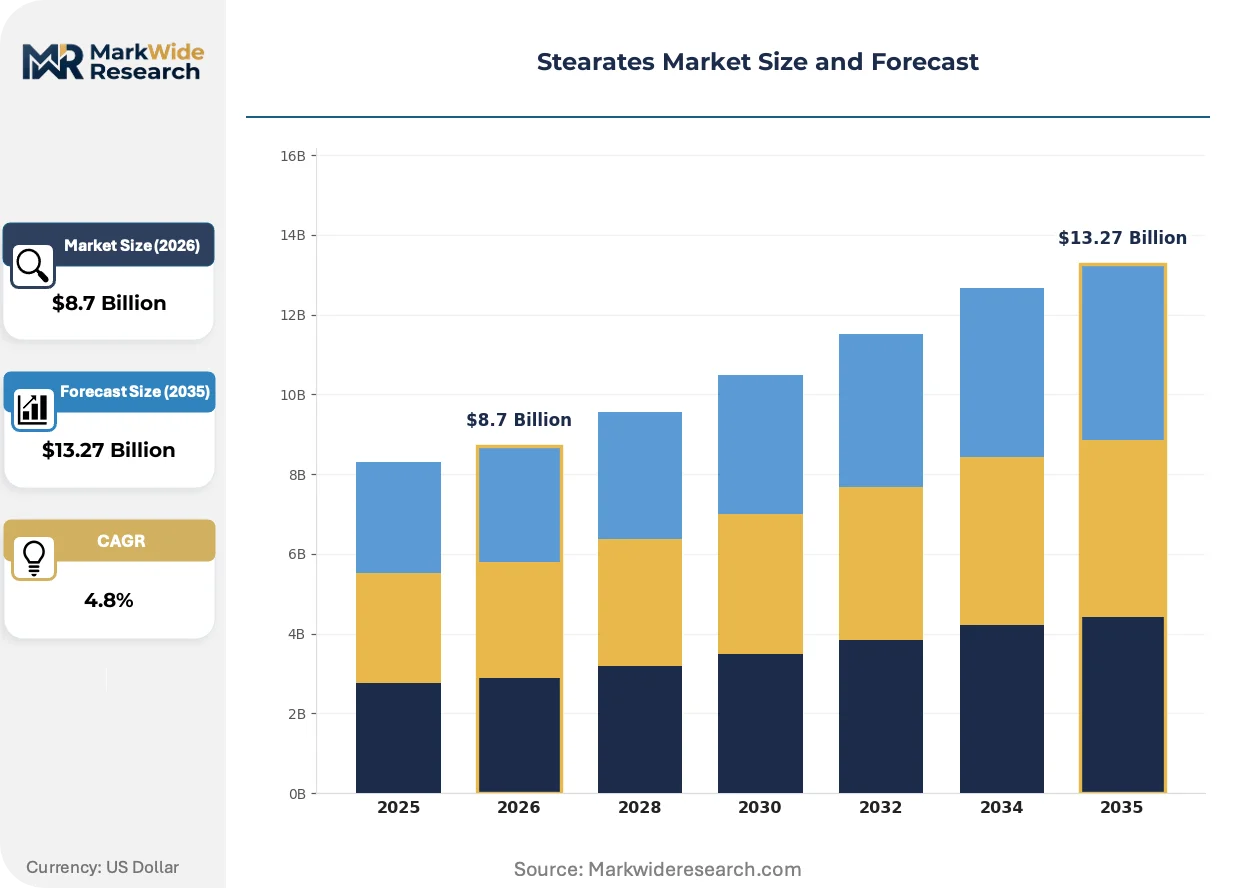
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Stearate, Magnesium Stearate, Sodium Stearate, Zinc Stearate Application: Food Additives, Pharmaceuticals, Cosmetics, Plastics End User: Food Industry, Healthcare, Personal Care, Manufacturing Form: Powder, Granules, Liquid, Emulsions |
| Companies Covered | Baerlocher GmbH, FACI S.p.A., Dover Chemical Corporation, Peter Greven GmbH & Co. KG, PMC Biogenix, Inc., Sun Ace Kakoh (Pte.) Ltd., Valtris Specialty Chemicals, Norac Additives, Inc., CHNV Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stearates Market Strategic Shifts
Process intensification and regulatory digitization are compressing supplier qualification cycles while expanding the service component of stearate contracts beyond base chemical delivery.
Continuous-flow reactor technology for direct fusion stearate production is consolidating batch-process capacity in developed markets. German and US polymer compounders are adopting these systems to reduce energy intensity and improve lot-to-lot consistency. The technology is consolidating smaller-scale precipitation operations into fewer, higher-throughput facilities with captive fatty acid supply.
REACH SVHC candidate list expansion and SCIP database requirements are forcing reformulation of zinc stearate grades for polymer applications. European compounders must now document full substance composition across supply tiers. Automotive interior trim suppliers in Germany and Czechia are switching to certified low-impurity grades to preempt downstream liability.
Buyers are unbundling technical service from commodity supply, contracting lubricity audits and custom blending separately from base chemical volumes. Polymer processors in Italy and Spain are sourcing magnesium stearate from one supplier while retaining formulation optimization from specialized service providers. This pattern is most visible in pharmaceutical tableting operations where FDA cGMP compliance complexity favors external technical partnerships over in-house expertise development.
Stearates Market Segmentation
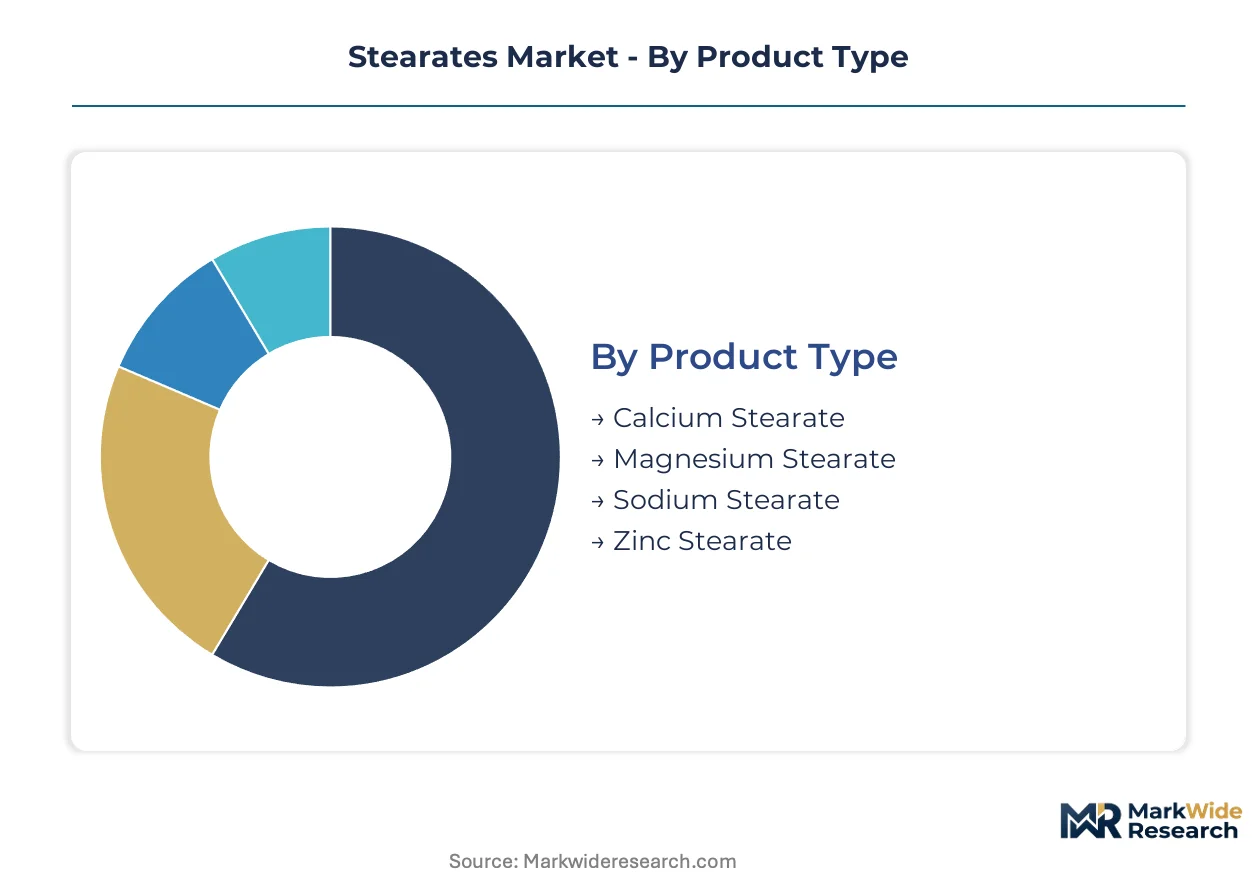
Stearates function across divergent performance specifications, from pharmaceutical-grade lubricity coefficients to industrial PVC stabilization. Segmentation reveals how formulation chemistry, physical form, and end-use certification requirements create distinct margin pools and supplier qualification barriers.
Product Type:
Customization intensity varies from commodity construction grades to precision pharmaceutical specifications, with metal cation selection determining thermal stability, lubricity performance, and regulatory compliance burden.
- Magnesium Stearate:Hydrophobic salt with superior lubricity coefficient and minimal impact on tablet dissolution profiles. Pharmaceutical tablet production in India and China drives qualification demand against FDA cGMP and BIS purity thresholds.
- Zinc Stearate:Metallic soap delivering thermal stability above 120°C during polymer extrusion. PVC compounding operations across Germany and Belgium absorb volumes where REACH SVHC documentation mandates certified low-impurity grades.
- Calcium Stearate:Acid scavenger for construction-grade PVC stabilization facing substitution pressure from alternative stabilizers.
- Sodium Stearate:Water-soluble variant serving personal care emulsification and soap manufacturing with lower certification barriers.
Leading the category by volume: Zinc Stearate. Growing fastest: Magnesium Stearate.
Application:
End-use certification requirements stratify suppliers into pharmaceutical-grade, food-grade, and industrial tiers with incompatible capital equipment and documentation systems.
- Pharmaceuticals:Tablet lubrication and glidant functions demanding heavy-metal limits below 10 ppm and batch consistency documentation. FDA cGMP validation cycles extend supplier qualification to 18-24 months, concentrating volume among certified producers.
- Plastics:PVC stabilization and polymer processing where thermal degradation resistance determines specification. German automotive interior trim suppliers preempt downstream liability through documented low-impurity formulations.
- Food Additives:Anti-caking and emulsification functions requiring Kosher, Halal, and national food safety certifications.
- Cosmetics:Personal care formulations absorbing higher-margin emulsification grades with allergen disclosure requirements.
Dominant by revenue concentration: Pharmaceuticals. Expanding most quickly: Food Additives.
End User:
Procurement sophistication separates commodity volume buyers from technical service contractors seeking lubricity optimization partnerships beyond base chemical supply.
- Healthcare:Pharmaceutical manufacturers and contract development organizations with mandatory supplier audits and batch record traceability. North American and European facilities enforce ICH Q7 guidelines that disqualify uncertified producers.
- Manufacturing:Polymer compounders and rubber processors sourcing zinc stearate for extrusion stability. Italian and Spanish processors increasingly unbundle technical service from commodity supply.
- Food Industry:Processors and ingredient blenders requiring national food safety certifications with regional variation in permissible additive loadings.
- Personal Care:Cosmetic formulators and contract manufacturers absorbing certified emulsification grades with clean-label positioning requirements.
Highest procurement sophistication: Healthcare. Fastest service unbundling: Manufacturing.
Form:
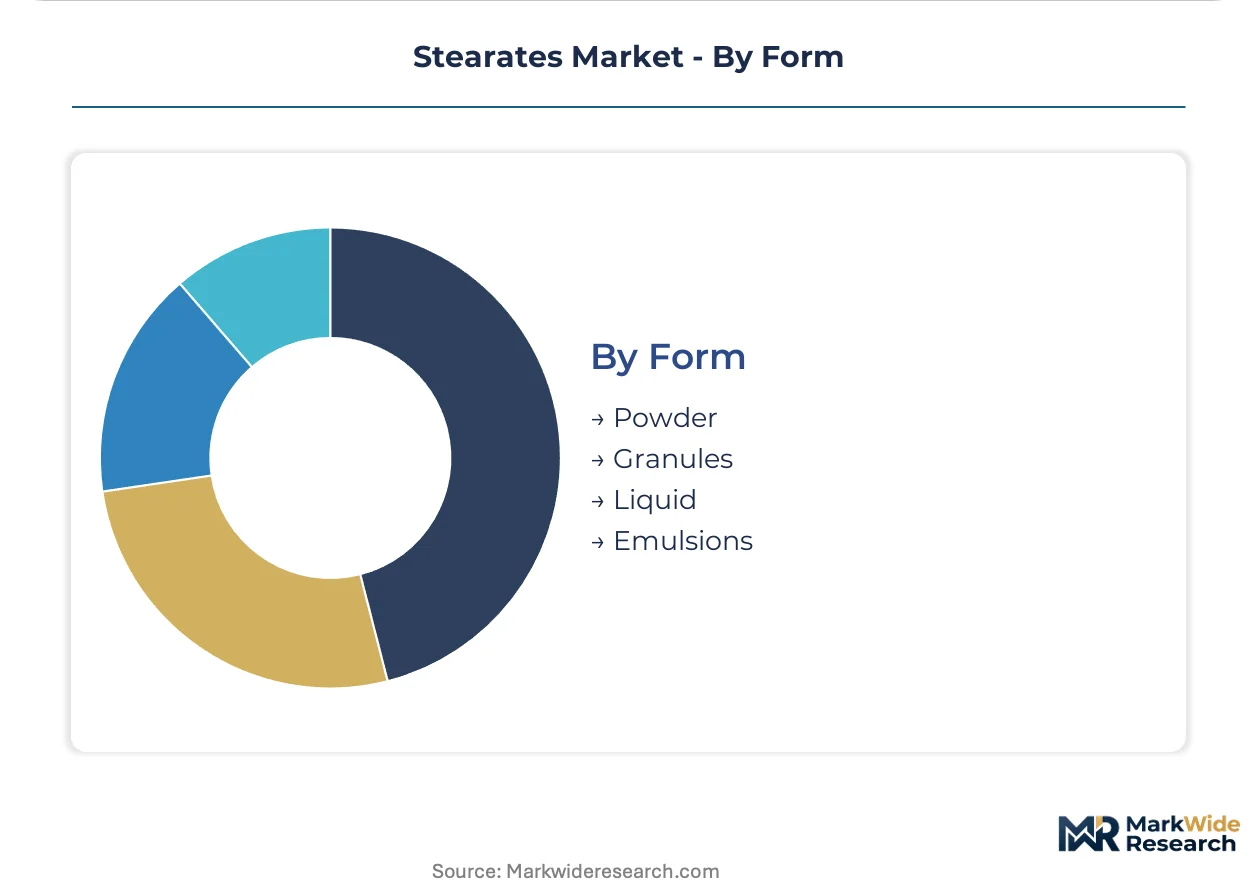
Physical state selection balances dispersion efficiency, dust exposure regulation, and processing equipment compatibility across continuous-flow and batch reactor outputs.
- Powder:Standard pulverized form for pharmaceutical tableting and dry blending operations with occupational exposure control requirements.
- Granules:Low-dust agglomerated form preferred in high-speed polymer compounding where dispersion uniformity affects extrusion quality.
- Liquid:Dispersed or dissolved preparations for coatings and liquid formulations eliminating dust handling infrastructure.
- Emulsions:Aqueous suspensions serving cosmetic and food applications where immediate dispersion and visual clarity matter.
Widest specification range: Powder. Steepest expansion trajectory: Granules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates stearate production capacity while Germany and India absorb disproportionate pharmaceutical-grade consumption. This production-consumption divide shapes regional trade flows and supplier qualification requirements.
China
PVC compounding and rubber processing operations in Jiangsu and Zhejiang provinces drive zinc stearate absorption. GB standards enforcement through SAMR tightens heavy-metal documentation for export-bound formulations. The Yangtze River Delta cluster hosts precipitation reactor capacity serving both domestic polymer processors and pharmaceutical tablet manufacturers upgrading to certified magnesium stearate grades.
Germany
Automotive interior trim suppliers and polymer compounders in North Rhine-Westphalia demand REACH-compliant zinc stearate with documented SVHC screening. ECHA enforcement of SCIP database requirements forces reformulation of legacy grades. The Cologne-Düsseldorf industrial corridor concentrates technical service contracting for lubricity optimization, unbundling formulation support from base chemical procurement.
India
Domestic pharmaceutical manufacturers in Maharashtra and Gujarat are upgrading from industrial-grade to BIS-certified magnesium stearate for tablet production. CDSCO alignment with ICH Q7 guidelines extends supplier qualification timelines. The Mumbai-Pune pharma belt drives premium-grade penetration as contract development organizations enforce batch record traceability.
United States
FDA cGMP validation requirements concentrate pharmaceutical-grade supply among certified producers serving North American tablet manufacturers. EPA oversight of fatty acid derivative processing affects cost structures for domestic precipitation operations. The New Jersey-Pennsylvania chemical corridor maintains blending and technical service capacity for polymer compounders seeking custom lubricity formulations.
Belgium
Polymer compounders in the Antwerp-Ghent axis face limited qualified supplier pools for REACH-compliant zinc stearate, creating single-source vulnerability. ECHA enforcement of heavy-metal limits disqualifies uncertified import volumes. The port of Antwerp facilitates feedstock flows for European direct fusion reactor operations while downstream formulation increasingly shifts to certified low-impurity grades.
Stearates Market Competitive Environment
Capital-heavy producers compete with asset-light technical service providers across divergent margin pools. The vendor base stratifies into three tiers: integrated fatty acid producers with captive stearate output, specialized precipitation operators serving pharmaceutical certification requirements, and regional compounders blending custom formulations. Dominant competitive moves include backward integration into palm and tallow derivative supply and geographic expansion of technical service contracting beyond commodity volumes.
Among European-integrated producers, Baerlocher GmbH and Peter Greven GmbH & Co. KG occupy positions anchored by manufacturing footprint and feedstock control. FACI S.p.A. exemplifies the Mediterranean specialist archetype. These three represent distinct strategic postures: German-integrated, German-backward-integrated, and Italian-specialist. Their positioning reflects how regional feedstock access and certification depth determine competitive viability across pharmaceutical, polymer, and food-grade segments.
| Leading Market Players |
|---|
| Baerlocher GmbH |
| FACI S.p.A. |
| Dover Chemical Corporation |
| Peter Greven GmbH & Co. KG |
| PMC Biogenix, Inc. |
| Sun Ace Kakoh (Pte.) Ltd. |
| Valtris Specialty Chemicals |
| Norac Additives, Inc. |
| CHNV Technology |
| Others |
Value Chain & Pricing Dynamics
Palm fatty acid distillate and tallow derivative costs cascade through stearate pricing tiers, with feedstock volatility compressing converter margins more acutely than pharmaceutical-grade certification premiums can recover. REACH-compliant zinc stearate commands substantial markups over industrial grades as European polymer compounders absorb scarcity-driven premiums from limited qualified supplier pools.
Pricing Analysis
Margin tightening in industrial-grade calcium stearate traces to alternative acid scavenger substitution eroding volume positions and pricing power. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial levels separates certified producers from commodity suppliers. Pricing pressure intensifies in construction applications as PVC stabilizer buyers shift toward lower-cost alternatives. Pharmaceutical manufacturers exhibit lowest price sensitivity due to mandatory FDA cGMP validation cycles and batch record traceability requirements that lock in supplier relationships.
Supply Chain Analysis
Fatty acid feedstock supply rests on Malaysian and Indonesian palm oil processing capacity tethered to commodity derivative markets. Precipitation reactor operations in China, Germany, and India convert these inputs into metallic stearate salts. Single-source vulnerability concentrates in REACH-compliant zinc stearate as European compounders face disqualified import volumes under ECHA enforcement. Distribution runs through polymer processor direct contracts and pharmaceutical ingredient distributor networks with regional technical service overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade certification capacity scarcity props pricing across magnesium stearate tiers as FDA cGMP validation timelines extend supplier qualification cycles.
For Market Incumbents: To counter feedstock cost volatility, secure backward integration into palm and tallow derivative supply through long-term offtake agreements with Southeast Asian processors. Expand technical service contracting capacity in the Cologne-Düsseldorf corridor to capture unbundled lubricity optimization revenue beyond commodity volumes. For New Entrants and Emerging Players: Domestic pharmaceutical manufacturers in Maharashtra and Gujarat represent an underserved buyer archetype upgrading from industrial-grade to BIS-certified magnesium stearate. Penetrate this segment through CDSCO-aligned batch documentation capabilities and Mumbai-Pune pharma belt distribution partnerships. For Investors and Strategic Acquirers: ECHA expansion of the SVHC candidate list is the leading indicator that REACH compliance depth will concentrate volume among certified producers. Target precipitation operators with existing pharmaceutical-grade infrastructure and captive fatty acid supply. Watch for SCIP database enforcement triggering reformulation mandates across automotive interior trim supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive palm fatty acid distillate access insulates margin compression from commodity derivative volatility. |
| Pharmaceutical-Grade Certification Investment | FDA cGMP validation extends supplier qualification barriers that concentrate volume among certified producers. |
| Technical Service Contracting Expansion | Unbundled lubricity optimization partnerships capture revenue beyond commodity stearate volumes in polymer processing. |
| REACH-Compliant Capacity Addition | ECHA enforcement of heavy-metal limits disqualifies uncertified imports from European polymer compounder procurement. |
| Joint Venture in Yangtze River Delta | SAMR-aligned GB standards compliance positions export-bound formulations for pharmaceutical tablet manufacturer upgrading. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this stearate market assessment. Primary interviews with plant managers at precipitation reactor operations, procurement leads at polymer compounders, pharmaceutical regulatory affairs directors, and distribution channel partners validated supply-side capacity and demand-side qualification requirements. Bottom-up modeling of magnesium, zinc, and calcium stearate volumes triangulated against top-down fatty acid derivative consumption trends from ACC and Cefic reports.
Segment-level granularity modeled product type, application, and end-user dimensions across the projection horizon. Pharmaceutical-grade, food-grade, and industrial tiers were separately forecasted with grade-specific certification timelines and pricing premiums. CAGRs derived from regression analysis against polymer processing rates, pharmaceutical tablet production indices, and construction PVC consumption patterns. Feedstock price elasticity and REACH compliance cost pass-through assumptions informed margin trajectory modeling.
Revisions become necessary when ECHA accelerates SVHC candidate list expansion, FDA extends cGMP validation timelines, or palm oil derivative markets experience sustained volatility beyond historical bands. A small set of regulatory enforcement triggers and feedstock supply disruptions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Specialty Biocides Market