
 Marine Hyaluronic Acid Market | 2026-2036
Marine Hyaluronic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hyaluronic Acid Market Analytics
China's Shandong Peninsula biopolymer corridor is narrowing the supply gap between fermentation-derived and marine-extracted hyaluronic acid. Bloomage Biotechnology anchors domestic raw material security through captive kelp-processing infrastructure. Seikagaku Corporation competes on enzymatic extraction precision for ophthalmic-grade specifications. Galderma sustains European formulation leadership by integrating marine-derived grades into its injectable portfolio.
Marine hyaluronic acid denotes a glycosaminoglycan extracted from fish roe, mollusk connective tissue, or macroalgal fermentation, characterized by molecular weights spanning 50 kDa to 3,000 kDa and distinctive sulfate modifications absent in terrestrial analogues. Its primary commercial purpose centers on dermal hydration matrices, viscosupplementation, and wound-healing scaffolds where biocompatibility and osmotic retention prove critical. Powder formulations dominate upstream margin pools due to customization flexibility for downstream pharmaceutical and cosmetic clients, while injection-grade segments command premium positioning through sterilization validation and endotoxin control protocols. Serum applications accelerate fastest among skincare brands seeking marine-origin claims to differentiate clean-beauty positioning.
EMA medical device regulations and REACH substance restrictions jointly elevate documentation burdens for marine-sourced biopolymers entering European therapeutic channels. FDA oversight of dermal filler classifications further segments market access between cosmetic and pharmaceutical pathways in the United States. China's NMPA biologics standards and SAMR cosmetic ingredient disclosure rules add parallel compliance layers for cross-border suppliers. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and cosmetic-grade approval timelines to calibrate capacity allocation and geographic prioritization.
Market Dynamics
REACH compliance is tightening raw material sourcing rules for marine-derived hyaluronan, forcing formulators to document batch-level provenance and sulfation profiles while pharmaceutical-grade specifications displace cosmetic-grade volumes in margin-weighted capacity planning.
Growth Catalysts
- MFDS biologics pathway:South Korea's streamlined approval for marine-sourced polymers accelerates dermal filler registrations, drawing cosmeceutical manufacturers to Seoul's biocluster for co-development partnerships.
- Ophthalmic viscosurgery expansion:Cataract procedure volumes in aging populations pull enzymatic-extraction grades into anterior segment surgery kits, prioritizing endotoxin control over molecular weight flexibility.
- Kelp fermentation scale-up:Macroalgal bioreactor yields from Shandong Peninsula infrastructure narrow cost gaps with terrestrial fermentation, securing domestic supply for China's NMPA-registered injectable producers.
Market Restraints
- Wild catch supply volatility:Seasonal roe harvesting from Atlantic cod and salmon fisheries constrains high-molecular-weight raw material availability, forcing processors to maintain dual-source inventories.
- EMA documentation burden:Medical device regulation substance restrictions require exhaustive traceability for marine biopolymers, extending European therapeutic channel entry timelines by 18-24 months.
- Bacterial fermentation substitution:Streptococcus zooepidemicus-derived hyaluronic acid achieves comparable viscosity at 40% lower upstream cost, pressuring marine-origin premium positioning in mass-market skincare.
Strategic Opportunities
- Wound-healing scaffold penetration:Chronic diabetic ulcer protocols in India's CDSCO-registered hospitals create demand for sulfate-modified marine grades with enhanced angiogenic signaling.
- Clean-beauty certification convergence:COSMOS and EWG Verified standards reward marine-origin claims, enabling serum brands to capture price premiums through ingredient transparency narratives.
- Direct-to-clinic distribution:Aesthetic medicine chains in Brazil bypass traditional pharmaceutical wholesalers, contracting directly with marine-grade processors for filler formulation customization.
Industry Challenges
- Sulfation analytics expertise:Precise quantification of marine-specific modifications requires mass spectrometry capabilities scarce among third-party testing laboratories, creating QC bottlenecks.
- Sterile manufacturing capex:Injection-grade validation demands isolator technology and continuous particle monitoring systems that strain mid-scale processor balance sheets.
- Cross-jurisdictional dossier divergence:FDA 510(k) substantial equivalence criteria conflict with EMA MDR technical documentation requirements, forcing parallel regulatory investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hyaluronic Acid Market |
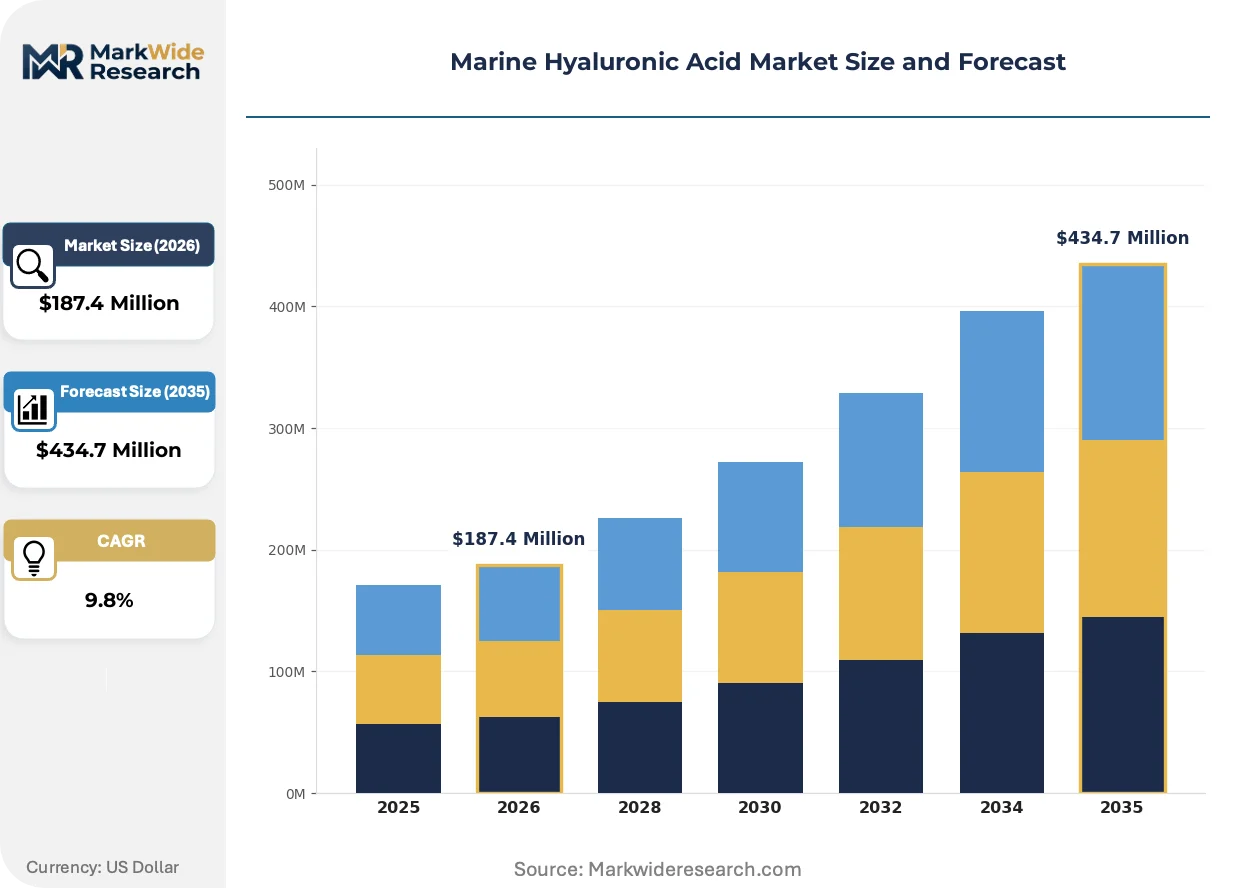
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Serum, Gel, Injection Application: Cosmetic, Pharmaceutical, Nutraceutical, Medical End User: Skincare Brands, Clinics, Hospitals, Research Institutions Distribution Channel: Online, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Allergan, Sanofi, Galderma, Ferring B.V., Anika Therapeutics, Lifecore Biomedical, Bloomage Biotechnology, Seikagaku Corporation, Kewpie Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hyaluronic Acid Market Evolving Landscape
Enzymatic extraction protocols and precision fermentation are compressing traditional supply hierarchies while regulatory documentation requirements reshape competitive moats around provenance verification capabilities.
Cell-free enzymatic synthesis from recombinant hyaluronidase reverse reactions is collapsing the yield gap between marine extraction and bacterial fermentation. Ophthalmic-grade manufacturers in Japan and South Korea are adopting these systems to achieve sub-0.05 EU/mg endotoxin specifications without roe supply dependence. The technology is collapsing batch-to-batch molecular weight variance, enabling single-specification production runs that reduce downstream formulation adjustment costs.
REACH substance restriction amendments now mandate full supply chain disclosure for marine-derived polymers entering European therapeutic channels. ECHA registration dossiers must specify catch location, processing facility, and sulfation degree by batch. Injectable-grade segments face the steepest compliance burden, with German and French formulators consolidating supplier panels to reduce audit complexity.
Certification-driven procurement is displacing price-first sourcing among premium skincare brands. COSMOS-standard manufacturers now require marine-origin documentation from kelp fermentation through finished serum, with South Korean contract manufacturers building captive algae cultivation to satisfy traceability audits. This pattern concentrates most visibly in Seoul's Gangnam district aesthetic clinics, where patient consultation protocols emphasize ingredient provenance disclosure.
Marine Hyaluronic Acid Market Segmentation
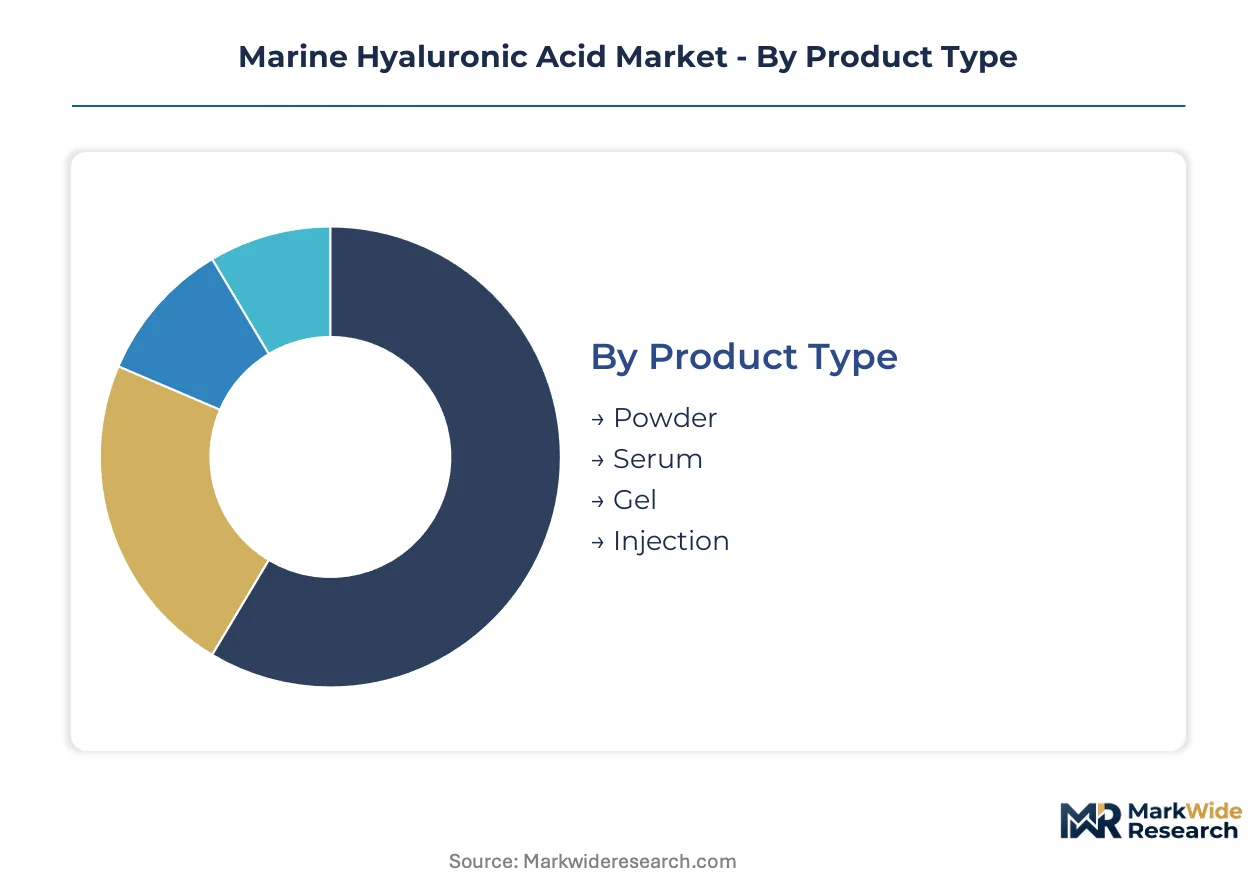
Marine hyaluronic acid supply chains fragment across molecular weight specifications, sterility grades, and provenance documentation requirements that determine channel access. Each segmentation dimension carries distinct margin structures and regulatory burdens that reshape competitive positioning.
Product Type:
Use-case spectrum spans raw material flexibility through finished sterile formulations, with powder commanding upstream customization while injection-grade absorbs validation costs.
- Powder:Unformulated glycosaminoglycan with molecular weights spanning 50 kDa to 3,000 kDa enables downstream pharmaceutical and cosmetic clients to calibrate viscosity and sulfation profiles for specific applications. Demand concentrates among South Korean contract manufacturers seeking kelp-fermentation feedstock for serum formulation, driven by COSMOS certification requirements for marine-origin traceability.
- Injection:Sterile-grade material validated to sub-0.05 EU/mg endotoxin specifications for dermal filler and viscosurgery applications absorbs the steepest compliance costs including isolator technology and continuous particle monitoring. European aesthetic medicine chains prioritize this grade for EMA MDR-registered therapeutic channels, where batch-level provenance documentation is mandatory.
- Serum:Ready-to-apply formulations targeting clean-beauty positioning with marine-origin claims for hydration matrices.
- Gel:Intermediate viscosity products for wound-healing scaffolds and topical medical applications.
The dominant share belongs to Powder, while Injection is closing the gap fastest.
Application:
Regulatory pathway divergence splits the market between cosmetic disclosure rules and pharmaceutical-grade validation protocols.
- Cosmetic:Skincare formulations leverage marine-origin claims for clean-beauty differentiation without therapeutic efficacy requirements, prioritizing ingredient transparency narratives over sterility validation. China's SAMR cosmetic ingredient disclosure rules and South Korea's MFDS streamlined biologics pathway respectively constrain and enable market access for this segment.
- Pharmaceutical:Dermal filler and viscosupplication applications demand endotoxin control, sulfation analytics, and REACH-compliant supply chain documentation that extend European entry timelines. Ophthalmic-grade specifications in Japan and South Korea absorb enzymatic extraction premiums to achieve batch-to-batch molecular weight consistency for anterior segment surgery kits.
- Medical:Wound-healing scaffolds and chronic ulcer protocols, particularly in India's CDSCO-registered hospitals, exploit sulfate-modified marine grades for enhanced angiogenic signaling.
- Nutraceutical:Oral supplementation formats with lower purity thresholds and reduced documentation burdens.
Pharmaceutical applications absorb the highest compliance investment, while Medical is expanding most quickly through chronic wound protocols.
End User:
Customer type determines procurement scale, formulation customization requirements, and regulatory sophistication.
- Skincare Brands:COSMOS and EWG Verified certification seekers driving marine-origin documentation from kelp fermentation through finished serum.
- Clinics:Brazilian aesthetic medicine chains bypassing traditional pharmaceutical wholesalers for direct filler formulation customization.
- Hospitals:India's CDSCO-registered facilities adopting sulfate-modified grades for diabetic ulcer treatment protocols.
- Research Institutions:Early-stage scaffold development and enzymatic extraction protocol validation.
Skincare Brands command volume leadership, while Clinics are gaining share fastest through direct-to-provider distribution restructuring.
Distribution Channel:
Channel selection reflects product sterility grade, customer technical sophistication, and geographic regulatory environment.
- Pharmacies:Primary channel for injection-grade products requiring cold chain integrity and pharmacist consultation in regulated markets.
- Online:Serum and cosmetic-grade powder sales to formulation laboratories and clean-beauty brands prioritizing ingredient provenance disclosure.
- Specialty Stores:Premium skincare retail in Seoul's Gangnam district aesthetic clusters where patient consultation protocols emphasize marine-origin transparency.
- Supermarkets:Mass-market nutraceutical and basic cosmetic applications with minimal technical differentiation.
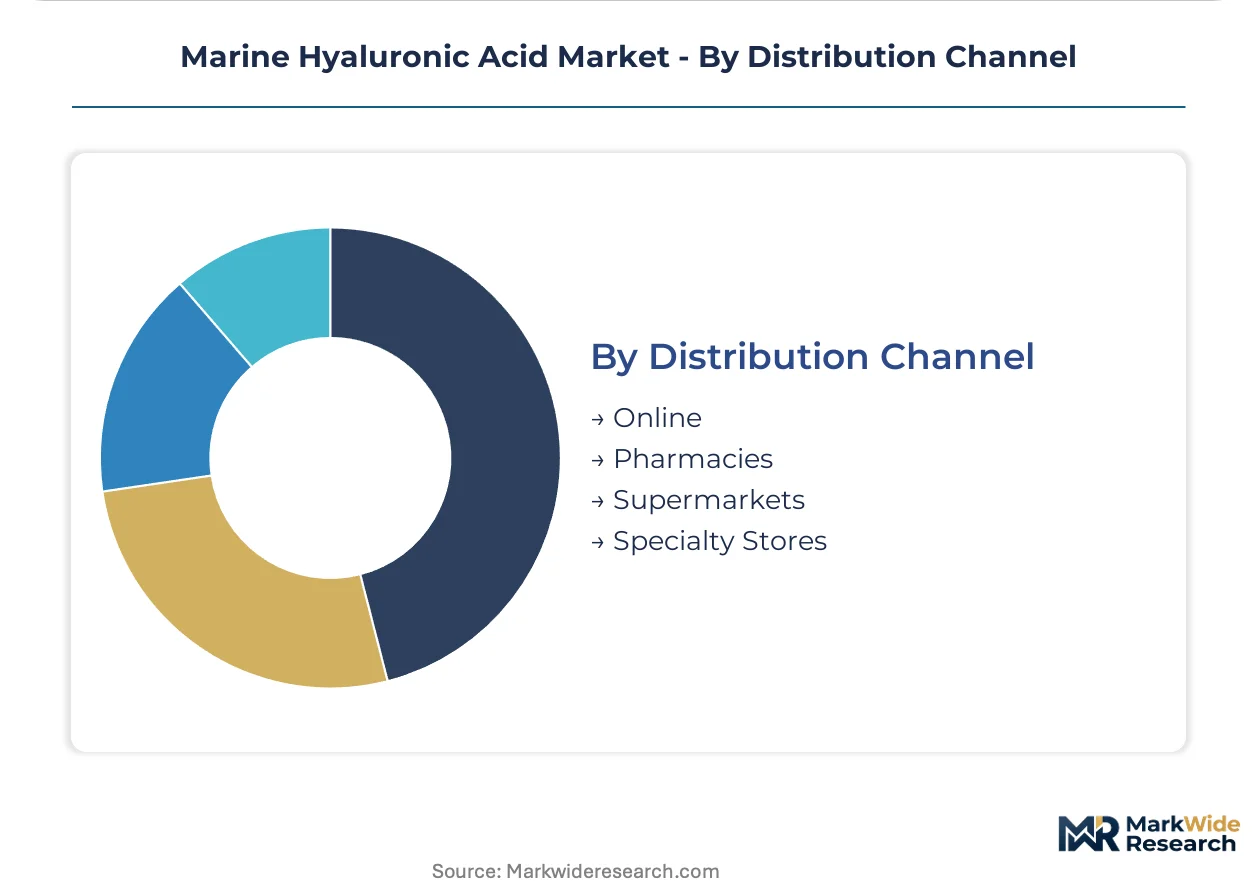
Pharmacies retain the dominant position for therapeutic grades, while Online is climbing the fastest for cosmetic raw material procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port cold-chain terminal underwrites Shandong Peninsula's role as the primary marine biopolymer gateway, connecting kelp fermentation facilities to NMPA-registered injectable producers across China's eastern seaboard.
China
NMPA biologics standards and SAMR cosmetic disclosure rules drive dual compliance layers for cross-border suppliers. Shandong Peninsula infrastructure anchors domestic raw material security through captive kelp-processing capacity. Bloomage Biotechnology consolidates supply chain control via backward integration into macroalgal cultivation.
South Korea
MFDS streamlined biologics pathway accelerates dermal filler registrations for marine-sourced polymers. Seoul's Gangnam district aesthetic clinics emphasize ingredient provenance disclosure in patient consultation protocols. Contract manufacturers scale marine biopolymer integration through co-development partnerships in the capital region biocluster.
Japan
PMDA ophthalmic-grade specifications absorb enzymatic extraction premiums for anterior segment surgery kits. Seikagaku Corporation competes on extraction precision for sub-0.05 EU/mg endotoxin targets. Tokyo-Osaka pharmaceutical corridors prioritize batch-to-batch molecular weight consistency for viscosurgery applications.
United States
FDA 510(k) substantial equivalence criteria segment market access between cosmetic and pharmaceutical pathways. Cataract procedure volumes in aging populations pull marine-derived grades into viscosupplementation kits. Boston and San Francisco biotech clusters drive wound-healing scaffold adoption for chronic diabetic ulcer protocols.
Germany
EMA MDR technical documentation requirements extend European therapeutic channel entry timelines by 18-24 months. REACH substance restriction amendments mandate full supply chain disclosure for marine-derived polymers entering injectable-grade segments. Frankfurt and Munich formulators consolidate supplier panels to reduce audit complexity under ECHA registration protocols.
Marine Hyaluronic Acid Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and fermentation technology. The vendor base separates into three strata: multinational pharmaceutical conglomerates with sterile formulation infrastructure, mid-scale biopolymer processors with kelp cultivation assets, and precision enzymatic extraction specialists serving ophthalmic-grade specifications. Competitive moves concentrate on backward integration into macroalgal supply and geographic expansion through direct-to-clinic distribution restructuring.
Within the extraction-technology tier, Seikagaku Corporation and Kewpie Corporation occupy positions defined by enzymatic precision and fermentation scale respectively. Bloomage Biotechnology anchors the Asia-Pacific supply security vector through Shandong Peninsula infrastructure. Galderma exemplifies the European formulation leadership archetype, integrating marine-derived grades into injectable portfolios under EMA compliance frameworks.
| Leading Market Players |
|---|
| Allergan |
| Sanofi |
| Galderma |
| Ferring B.V. |
| Anika Therapeutics |
| Lifecore Biomedical |
| Bloomage Biotechnology |
| Seikagaku Corporation |
| Kewpie Corporation |
| Others |
Value Network & Pricing Analysis
Shandong Peninsula kelp fermentation infrastructure anchors upstream capacity for China's NMPA-registered injectable producers, concentrating margin capture among processors with captive macroalgal supply and forcing downstream formulators into long-term offtake commitments to secure pharmaceutical-grade volumes.
Pricing Analysis
REACH substance restriction amendments dictate the pricing tier structure across European therapeutic channels, separating injection-grade segments validated to EMA MDR standards from cosmetic-grade powder sold under disclosure-light SAMR rules. Three-tier pricing structure across premium, standard, and economy levels reflects endotoxin specification, sulfation analytics documentation, and batch-level provenance verification. Cost compression in standard-grade serum formulations is intensifying because bacterial fermentation substitutes achieve comparable viscosity at lower upstream cost. Mass-market skincare brands exhibit highest price sensitivity, while ophthalmic-grade manufacturers in Japan absorb enzymatic extraction premiums without volume elasticity.
Supply Chain Analysis
Extended payment terms from South Korean contract manufacturers to Shandong Peninsula kelp processors are stabilizing working capital across the marine biopolymer corridor. Supply concentrates in China, South Korea, and Japan, with raw material dependencies spanning Atlantic cod roe, Pacific kelp biomass, and recombinant hyaluronidase enzymes. Single-source vulnerability from seasonal wild-catch volatility in North Atlantic fisheries forces dual-source inventory strategies. Distribution runs through direct-to-clinic channels in Brazil and pharmaceutical wholesalers in European aesthetic medicine chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine hyaluronic acid sits in early-cycle expansion as clean-beauty certification convergence accelerates ingredient provenance disclosure requirements across premium skincare procurement protocols.
For Market Incumbents: Pre-empt bacterial fermentation substitution by backward integration into kelp cultivation assets in Shandong Peninsula and Gangnam district bioclusters. Anchor formulation leadership through EMA MDR-registered sterile infrastructure that mid-scale processors cannot replicate. Defend margin position by consolidating supplier panels to reduce REACH audit complexity for European therapeutic channel customers. For New Entrants and Emerging Players: Pursue white-space opportunities in India's CDSCO-registered hospital networks for sulfate-modified wound-healing scaffolds and Brazil's direct-to-clinic aesthetic medicine chains. Chronic diabetic ulcer protocols represent the most penetrable medical application. Establish go-to-market presence through kelp fermentation partnerships with South Korean contract manufacturers seeking COSMOS certification feedstock. For Investors and Strategic Acquirers: Long-term, this sits as a supply-security play because pharmaceutical-grade marine hyaluronan faces structural raw material constraints from wild-catch fisheries that precision fermentation has not fully displaced. Target acquisition archetypes include mid-scale processors with Shandong Peninsula infrastructure and enzymatic extraction specialists serving ophthalmic-grade specifications. Watch for inflection in MFDS dermal filler registration volumes as signal of Seoul biocluster maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kelp Cultivation | Bloomage Biotechnology's Shandong infrastructure secures domestic raw material security under NMPA biologics standards. |
| EMA MDR Registration Pathway | Galderma's European formulation leadership depends on batch-level provenance documentation for injectable portfolios. |
| Enzymatic Extraction Scale-Up | Seikagaku Corporation competes on sub-0.05 EU/mg endotoxin precision for Japan's PMDA ophthalmic-grade specifications. |
| Direct-to-Clinic Distribution | Brazilian aesthetic medicine chains bypass traditional pharmaceutical wholesalers for filler formulation customization. |
| COSMOS Certification Convergence | Seoul's Gangnam district clinics emphasize ingredient transparency narratives in patient consultation protocols. |
Research Methodology
Desk research of regulatory filings from EMA, FDA, NMPA and MFDS preceded structured interviews with marine biopolymer processors, cosmeceutical formulation executives, ophthalmic-grade manufacturers, and hospital procurement managers across China, South Korea, and Japan. Secondary validation drew from REACH substance restriction amendments, ECHA registration dossiers, customs trade data, and SEC 10-K disclosures from listed biopolymer processors. Bottom-up volume modeling triangulated against top-down market sizing across molecular weight and sterility grade segments.
Assumptions held regulatory divergence between pharmaceutical-grade and cosmetic-grade approval timelines within observed patterns, while enzymatic extraction yield improvements and kelp fermentation scale-up were varied across sensitivity scenarios. The forecast framework segmented by product type, application, and end user, with CAGRs derived from penetration rate analysis in dermal filler and viscosurgery channels. Industry-specific inputs included cataract procedure volumes, diabetic ulcer protocol adoption, and clean-beauty certification procurement thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by bacterial fermentation specialists or sudden REACH amendment stringency would shift outcomes. Macroeconomic contraction in aesthetic medicine spending, regulatory restriction on marine-sourced biopolymers, or breakthrough cell-free synthesis commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Global Optical Brighteners Market